

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Lamination Films Market to Hit US$4,104 Million by 2032 at 8.8% CAGR

Strategic Outlook: Unlocking Growth in the Thermal Lamination Films Market Through 2032
In an era where packaging functionality and visual appeal directly influence consumer behavior, thermal lamination films have evolved from simple protective overlays to critical enablers of brand differentiation and product durability. PW Consulting's latest comprehensive market research, Thermal Lamination Films Market, provides decision-makers with the analytical rigor required to navigate a sector undergoing rapid technical and regulatory transformation. This executive overview outlines the strategic architecture of the study, demonstrates its immediate relevance to 2026 corporate planning, and highlights the structural forces reshaping competitive dynamics across global value chains.
Market Architecture and Macro Trajectory
The global thermal lamination films market has demonstrated consistent expansion across a robust historical track record and is positioned for sustained mid-term acceleration. Between 2020 and 2025, industry revenues progressed from 1,562.0 million USD to an estimated 2,269.0 million USD, reflecting a compound trajectory that underscores both baseline demand resilience and incremental volume uptake across downstream sectors. The forecast horizon extends through 2032, during which the market is projected to surpass 4,104.0 million USD, supported by a forecast-period CAGR of 8.8 percent.
This growth pattern is not merely a function of macro packaging expansion. It reflects an ongoing redefinition of lamination value propositions. Where traditional thermal films once served primarily as mechanical shields, contemporary formulations increasingly deliver optical clarity, tactile differentiation, chemical resistance, and, critically, compatibility with evolving sustainability mandates. The report's top-line modeling isolates these inflection points, allowing leadership teams to distinguish between cyclical volume fluctuations and structural addressable-market expansion when calibrating capacity, procurement, and geographic allocation strategies for 2026.
Core Segmentation Framework and Applied Intelligence
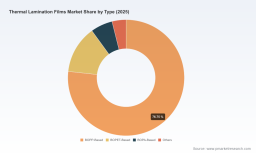
Strategic clarity requires more than aggregate growth figures. The study deconstructs the market across three foundational dimensions, each mapped to operational decision contexts rather than abstract taxonomy.
- Material architecture: Thermal lamination solutions are predominantly anchored in BOPP, BOPET, and BOPA chemistries, supplemented by specialized alternatives. The analysis examines how resin cost dynamics, melt-adhesive performance thresholds, and end-use durability requirements drive material selection across packaging, labeling, and graphic applications.
- Application environments: Industrial printing, commercial printing, and adjacent use cases are evaluated through the lens of throughput requirements, finishing economics, and protection specifications. This framework helps manufacturers align film grades with customer workflows rather than competing solely on price per square meter.
- Geographic deployment: Regional consumption profiles are assessed in relation to packaging intensification, printing infrastructure maturity, and regulatory exposure. The report avoids static share tables in favor of scenario-informed regional prioritization that reflects logistics realities, import dependency, and local certification regimes.
By integrating these segmentation layers, the study equips readers to identify where margin protection, product line extension, or channel repositioning will generate the highest incremental value in the coming planning cycle.
Competitive Landscape and Strategic Positioning
The thermal lamination films ecosystem is characterized by a heterogeneous participant base, ranging from globally integrated film producers to regionally focused converters. Market concentration metrics indicate that the top three players collectively account for 29.5 percent of recorded revenue, while the top five reach 41.2 percent, signaling a landscape that is neither fully consolidated nor purely fragmented. This structure creates both partnership opportunities and competitive pressure points for mid-sized and emerging suppliers.
The report profiles a broad spectrum of incumbent and challenger organizations, including COSMO Films (GBC), Transilwrap Company LLC, D&K Group, FlexFilm, Derprosa by Taghleef Industries, GMP, Royal Sovereign, Ipak, Drytac, PKC Co., Ltd., J-Film Corporation, Shagun Films, Kangde Xin, New Era, Hongqing, KANGLONG, Dingxin, EKO Film, Eluson Film, JPFL Films (BC Jindal), Polyplex, Mitsubishi Chemical America, Inc., Transcendia Inc., Guangdong EKO Film Manufacture Co. Ltd, Taghleef Industries, Fujian Taian Lamination Film Co. Ltd., Flexcon Company Inc., and Ultralen Film GmbH. Rather than presenting static corporate summaries, the analysis evaluates each participant's strategic posture across several actionable dimensions.
- Product differentiation: How firms are leveraging soft-touch, anti-scratch, anti-fingerprint, floatable, and thinner-gauge constructions to command price premiums or secure long-term converters' contracts.
- Geographic and application footprints: Where companies are concentrating investment versus where they are exposed to commoditization risk.
- Certification and compliance readiness: The extent to which ISO 9001:2015 and BRCGS credentials shape supplier eligibility in food, beverage, and liquid packaging channels.
- Innovation cadence: The pace at which new grades, adhesive technologies, and substrate compatibilities are reaching commercial deployment.
For 2026 planners, this competitive mapping translates into concrete strategic questions: which capability gaps are inviting displacement, which customer segments are overserved, and where can targeted R&D or acquisition create defensible positioning before market maturity compresses differentiation returns.
Worldwide Thermal Film Market
Recent Industry Movements Shaping 2026 Playbooks
The study embeds current corporate activity within broader sector momentum, ensuring that forward-looking strategy rests on observed execution rather than speculative trend-reading. Recent developments underscore how quickly premium protection and recyclability objectives are converging in product roadmaps.
Thermal Lamination Films Market
Taghleef Industries, for example, advanced its sustainability-driven portfolio with the May 2025 launch of SHAPE360 TDSW, a high-performance floatable white polyolefin TD shrink sleeve label film engineered for bottle-to-bottle recycling and reduced material thickness. In parallel, Derprosa by Taghleef Industries introduced Derprosa DL Soft Touch Pro-Shield 4x4, a soft-touch film with enhanced anti-scratch and anti-fingerprint protection, illustrating the premium tactile segment's continued refinement. By October 2025, Derprosa further reinforced its market visibility through a targeted exhibition presence at Printing United Orlando, showcasing a suite of premium soft-touch, anti-fingerprint, and anti-scratch thermal lamination films to converters and brand stakeholders.
These moves matter because they demonstrate a dual strategic emphasis: protecting visual and tactile quality while aligning with recycle-friendly design expectations. For buyers, this creates a more nuanced sourcing environment where film selection must balance performance specifications, compliance readiness, and downstream sustainability narratives. The report synthesizes such developments into actionable implications for procurement timing, specification standardization, and supplier evaluation criteria.
Structural Dynamics, Regulation, and Cost Architecture
No 2026 strategy can rely solely on demand forecasts. The thermal lamination films market is being continuously reshaped by regulatory frameworks, certification requirements, and raw material volatility that directly affect cost structures and market access.
Extended Producer Responsibility schemes across multiple regions are requiring manufacturers to take greater accountability for end-of-life packaging management. This regulatory pressure is indirectly accelerating demand for durable protective thermal lamination films that extend product life, reduce damage-related waste, and support more responsible packaging architectures. At the same time, ISO 9001:2015 and BRCGS certifications are increasingly mandated for suppliers whose films enter food and liquid packaging applications, raising the compliance floor for market participation and favoring suppliers with robust quality systems.
On the input side, thermal lamination films are primarily manufactured from BOPP and PET resins combined with thermal adhesives designed to melt at low temperatures, enabling efficient application across high-speed converting lines. However, production economics remain sensitive to fluctuations in polypropylene, polyethylene, and PET resin prices driven by oil and gas market volatility. These input swings can compress margins for price-takers while creating opportunities for suppliers with forward contracting, formulation flexibility, or differentiated performance that justifies cost pass-through. The study integrates these dynamics into scenario-based cost and margin analysis, helping leaders stress-test pricing strategies and inventory decisions against plausible resin-price environments.
What the Report Delivers for 2026 Decision-Making
PW Consulting designed this market research to function as a working strategic asset rather than a retrospective summary. The full study provides depth and granularity that enable cross-functional teams to align around shared assumptions and measurable priorities.
- Demand and revenue modeling: Forecast trajectories through 2032 anchored to historical performance, supporting capacity planning, sales targeting, and investment justification.
- Differentiation and application mapping: Clear linkage between film types, end-use requirements, and customer value arguments that guide product positioning and marketing messaging.
- Competitive benchmarking: Structured evaluation of participant strengths, geographic exposure, and innovation direction to inform competitive response and partnership selection.
- Regulatory and cost context: Practical assessment of how EPR expectations, certification mandates, and resin-price variability influence sourcing, compliance roadmaps, and margin management.
- Scenario-ready interpretation: Analytical frameworks that help teams translate macro trends into regional, segment, and product-line decisions without relying on a single deterministic outlook.
Taken together, these components allow executives to answer the practical questions that determine 2026 outcomes: where to prioritize innovation spend, which customer segments warrant dedicated service models, how to structure supplier negotiations amid input volatility, and where consolidation or niche positioning offers the most attractive risk-adjusted returns.
Turning Intelligence into Execution
Thermal lamination films are no longer a peripheral packaging input; they are a strategically relevant layer where protection, aesthetics, compliance, and sustainability intersect. With the market advancing from an estimated 2,392.86 million USD in 2026 toward a projected 4,104.0 million USD by 2032, the window for deliberate positioning is narrowing. Companies that treat this period as a pure volume play risk being squeezed by resin volatility, certification barriers, and intensifying competition from firms that have already aligned product roadmaps with recyclability and premium protection expectations.
PW Consulting's Thermal Lamination Films Market research is built for leaders who need more than directional optimism. It provides the structural evidence, competitive intelligence, and applied scenario tools required to convert sector momentum into disciplined execution. For organizations preparing 2026 investment, sourcing, and growth decisions, the complete study offers the detailed segmentation analysis, company-level assessment, and forward-looking interpretation necessary to act with confidence. We invite decision-makers to access the full report and integrate its findings directly into strategic planning, product roadmap prioritization, and competitive positioning workflows.
For detailed analysis of this topic, please visit the official page: Thermal Lamination Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com