

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Digital Banking Market Hits $1.92B in 2025, Forecast to Reach $3.71B by 2032 at 8.5% CAGR

Navigating the Next Wave: Strategic Intelligence for the Digital Banking Market (2026–2032)
The digital banking landscape is undergoing a structural transformation, moving beyond simple digitization to become the central nervous system of modern financial institutions. For executive teams and investors, the margin for error is narrowing. Understanding where capital should be deployed, which technologies will define competitive advantage, and how regulatory shifts will reshape operational models is no longer optional—it is imperative. PW Consulting's latest market research report, Digital Banking Market, offers a comprehensive roadmap for navigating this complex environment through 2032.
This analysis serves as an introduction to the depth of intelligence contained within the full report. While we highlight key macro trends and strategic imperatives here, the specific quantitative data, granular segmentation breakdowns, and proprietary risk assessments are reserved for our clients to ensure actionable confidentiality and maximum strategic value.
Market Trajectory and Scale
The momentum behind digital banking is robust, driven by a fundamental shift in consumer behavior and institutional necessity. Over the past half-decade, the market has demonstrated consistent growth, evolving from a nascent ecosystem into a dominant financial infrastructure. Historical data from 2020 through 2025 shows a clear upward trajectory in revenue generation across the sector.
Looking forward, the forecast period from 2026 to 2032 indicates sustained expansion. The market is projected to climb significantly in valuation, underpinned by a compound annual growth rate that signals healthy, long-term viability rather than ephemeral hype. This growth is not merely top-line; it reflects deepening penetration across diverse banking services and regions. For stakeholders, this macro view confirms that digital banking is a core growth engine, not a supplementary feature. However, realizing value within this expanding market requires navigating distinct competitive and regulatory currents that our full report dissects in detail.
Regulatory Dynamics and Compliance Imperatives
One of the most critical drivers shaping the 2026 decision-making landscape is the evolving regulatory environment. Compliance is transitioning from a back-office cost center to a strategic differentiator. In the United States, recent executive actions and agency rules are reshaping underwriting standards and data usage. For instance, directives from the White House in mid-2026 have asked federal financial regulators to clarify credit risk factors, including specific considerations for wage loss among non-work authorized borrowers within underwriting processes for digital banking services.
Simultaneously, the implementation of the CFPB Section 1033 rule, which began in 2025, mandates consumer financial data portability. This regulation is accelerating the adoption of API-first architectures, forcing platforms to be interoperable and transparent. Across the Atlantic, the EU's PSD3 legislation, effective in 2026, expands open banking requirements to encompass investment accounts, insurance products, and pension data. These regulatory layers create a complex compliance matrix. Our report analyzes how these specific legislative changes impact technology stacks and risk models, providing a clear view of where compliance investment yields competitive leverage versus where it represents pure cost. Furthermore, recent revisions to the CFPB proposed Section 1071 small-business lending reporting rule, which exempts community banks originating fewer than 1,000 covered loans per year, highlight the nuanced impact of regulation across different institution sizes.
Technology and Product Evolution
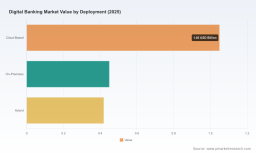
The product landscape is diversifying as institutions seek to balance legacy stability with modern agility. The market is segmented across various technological delivery models and product types, each serving different strategic needs. Cloud-based deployments continue to gain favor for their scalability and reduced infrastructure overhead, while on-premises and hybrid models retain relevance for institutions with specific latency or sovereignty requirements.
In terms of product offerings, mobile banking applications remain a primary touchpoint for consumers, but the value is shifting toward integrated platforms. Online banking platforms provide the robust backbone for complex transactions, while API banking services are becoming the glue that connects disparate financial ecosystems. Additionally, AI and automation tools are emerging as critical differentiators, enabling institutions to move from reactive service to predictive engagement. The full report details the revenue distribution and growth potential across these categories without exposing sensitive competitive benchmarks to the public domain.
Competitive Landscape and Strategic Moves
The market is characterized by high concentration, with a few key players commanding a significant share of the revenue. This consolidation creates barriers to entry but also pressures incumbents to innovate rapidly to maintain market share. Our analysis profiles leading companies that are defining the standards of the industry.
Companies like CSI, headquartered in Paducah, Kentucky, provide core banking platforms like NuPoint and digital banking solutions such as Apiture to modernize operations for US financial institutions. Their recent movements illustrate the consolidation trend; in late 2025, CSI completed the acquisition of Apiture to integrate its digital banking platform, enhancing tools for banks and credit unions. Following this, Apiture launched an AI-powered user interface in November 2025 aimed at predictive and personalized experiences. By early 2026, institutions like Wayne County Bank selected the Apiture Digital Banking platform to power their growth phase, and CSI subsequently introduced a Customer Intelligence Suite in May 2026 featuring AI-powered insights for retail and business banking.
On the technology frontier, London-based Thought Machine develops next-generation cloud-native core banking technology with Vault Core and Vault Payments, focusing on deep digital transformation. Similarly, nCino, based in San Mateo, California, delivers cloud-based digital banking platforms with extensive integrations for CRM and core systems. Lumin Digital, from San Ramon, California, offers a cloud-native Compounding Growth Platform focused on AI-powered solutions for banks and credit unions, recently launching a suite of AI-enabled tools in December 2025 to enhance performance and experience. Meanwhile, SDK.finance provides fintech infrastructure with international deployment capabilities across the US, Europe, MENA, and Africa. Understanding the strategic positioning of these players is essential for partnership evaluation and competitive benchmarking.
Strategic Recommendations for 2026 Decision Makers
Based on the trajectory of the market and the dynamics outlined above, several strategic priorities emerge for leadership teams in 2026. First, the integration of AI must move beyond pilot programs to core operational functionality, particularly in customer intelligence and risk underwriting. Second, API architecture must be treated as a strategic asset, especially in light of data portability rules like CFPB Section 1033 and EU PSD3. Institutions that build flexible, compliant API layers will be better positioned to adapt to future regulatory changes and partner ecosystems.
Third, regional considerations remain vital. While global growth is strong, the distribution of market value varies significantly across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Our report provides a nuanced view of these regional dynamics without disclosing the precise value splits that constitute our proprietary analysis. Executives must tailor their expansion and investment strategies to the specific maturity and regulatory environment of each geography. Finally, the high concentration of the market suggests that partnership or acquisition may be a faster route to capability building than organic development for many institutions.
Digital Banking Market
Digital Insurance Market
Conclusion
The Digital Banking Market is at a pivotal juncture where technology, regulation, and consumer expectation converge. The growth projections through 2032 indicate a massive opportunity, but capturing it requires more than general market awareness. It demands precise intelligence on segmentation, competitive moves, and regulatory impacts. This overview provides the strategic context, but the full PW Consulting report delivers the actionable data and deep-dive analysis required to make informed investment and operational decisions. For those ready to secure a competitive edge in the evolving financial landscape, accessing the complete intelligence suite is the logical next step.
For detailed analysis of this topic, please visit the official page: Digital Banking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com