

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Erythritol Market Reaches $271.5M in 2025, Projects 6.5% CAGR

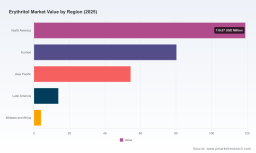
Strategic Sweetening: Navigating the Erythritol Market Outlook Through 2032
The global demand for sugar alternatives has evolved from a niche health trend into a fundamental restructuring of the food and beverage supply chain. As regulatory pressures tighten and consumer preferences shift decisively toward clean-label formulations, erythritol has emerged as a cornerstone ingredient for manufacturers seeking to balance caloric reduction with sensory performance. However, the landscape is no longer defined solely by consumer trends. The period from 2026 onward is characterized by intense geopolitical friction, supply chain realignment, and consolidation among key production capacities.
PW Consulting is pleased to present our latest comprehensive market intelligence report on the Erythritol Market. This document serves as a strategic guide for stakeholders aiming to secure competitive advantage in a volatile environment. By integrating historical performance data with forward-looking projections, this analysis provides the necessary framework to make informed decisions regarding capacity planning, sourcing strategies, and market entry.
Market Trajectory and Growth Dynamics
Understanding the macroeconomic trajectory of erythritol is essential for validating long-term investment hypotheses. Our analysis tracks the market revenue over a robust historical period from 2020 through 2025, establishing a baseline against which future performance can be measured. The data indicates a consistent upward trend in valuation, reflecting the ingredient's transition from a specialty additive to a mainstream commodity in the sweetener sector.
The historical revenue progression shows a market that has grown from approximately 198.3 million USD in 2020 to a projected 271.5 million USD at the 2025 base year. This growth underscores the successful commercialization of erythritol across multiple sectors. Looking ahead, the forecast period spanning 2026 to 2032 suggests sustained momentum. The market is anticipated to reach a valuation of 418.65 million USD by the end of the forecast horizon.
This expansion is supported by a Compound Annual Growth Rate (CAGR) of 6.5 percent during the forecast period. While this figure indicates healthy growth, it also implies a maturing market where marginal gains must be driven by efficiency and strategic differentiation rather than mere volume expansion. For corporate strategists, this trajectory signals a critical window for action. Entering the market post-2028 may incur higher barriers due to established supply chains and potential regulatory hardening, making the immediate years crucial for positioning.
Navigating Supply Chain Volatility and Raw Material Costs
One of the most critical variables influencing profitability in the erythritol sector is the cost of raw materials, specifically corn starch which serves as the primary feedstock for fermentation processes. Fluctuations in feedstock prices directly impact the marginal cost of production, yet these are often opaque to downstream formulators.
Recent analyst insights highlight significant regional disparities in raw material pricing as of April 2026. Corn starch prices were recorded at USD 437.00 per metric ton FOB in China, contrasting with USD 495.42 per metric ton CIF in the USA and USD 519.11 per metric ton CIF in India. These differentials create complex arbitrage opportunities but also expose supply chains to currency risk and logistics costs.
For procurement managers, relying on a single geographic source is no longer a viable risk mitigation strategy. Our report delves into the nuances of these cost structures, helping clients understand how regional price variations might impact total landed cost. Understanding the interplay between feedstock volatility and final product pricing is vital for maintaining margin integrity in a competitive bidding environment.
The Geopolitical Dimension: Trade Barriers and Duty Impacts
The erythritol market in 2026 is defined as much by trade policy as by consumer demand. The imposition of anti-dumping duties represents a structural shift in global trade flows, fundamentally altering the cost-benefit analysis of sourcing from different regions. In January 2025, the European Commission imposed definitive anti-dumping duties on Chinese erythritol imports, with rates ranging significantly from 34.4 percent to 233.3 percent. These duties were retroactive to June 2024, creating immediate liquidity pressures for importers who had stockpiled inventory based on previous cost assumptions.
Xylitol Market
Simultaneously, the United States has tightened its stance on Chinese imports. US Section 301 tariffs and preliminary anti-dumping measures on Chinese erythritol entered into effect in July 2025, with final orders issued in March 2026. These measures effectively close the price gap between Western producers and low-cost Asian competitors, reshaping the competitive landscape.
These regulatory developments are not merely background noise; they are active drivers of market share reallocation. A major legal milestone occurred in August 2025 when Cargill Incorporated filed an anti-dumping petition against Chinese erythritol producers, citing overcapacity and market distortions, and secured an initial victory. This legal advocacy signals a broader industry intention to protect domestic fermentation capacities against subsidized or underpriced foreign competition.
Our report provides a detailed regulatory watch section that maps these evolving obligations. For multinational corporations, understanding the specific duty tiers applicable to different suppliers is essential to avoid compliance pitfalls and unexpected cost spikes. The analysis explores how these duties will influence capacity utilization rates in Europe and North America versus export-oriented facilities in Asia.
Competitive Landscape and Strategic Positioning
The market structure exhibits moderate concentration, with the top three players accounting for 56.0 percent of market share and the top five representing 67.0 percent. This concentration suggests that while there is room for niche players, scale advantages remain significant, particularly in fermentation capacity and downstream distribution networks.
Erythritol Market
Key incumbents define the boundaries of competition. Cargill Incorporated, headquartered in Minneapolis, operates the sole Western Hemisphere fermentation capacity for Zerose erythritol at approximately 30,000 metric tons annually. This geographic insulation provides a strategic buffer against transoceanic tariff fluctuations. Similarly, Archer Daniels Midland Company and Tate & Lyle PLC maintain strong positions through their respective fermentation capabilities and brand portfolios such as ERYTESSE.
In Europe, Jungbunzlauer Suisse AG supplies ERYLITE through non-GMO wheat and corn sources, catering to specific regional preferences for non-GMO credentials. Meanwhile, the Asian supply base is dominated by large-scale fermentation producers in Shandong Province, China, including Shandong Sanyuan Biotechnology, Zhucheng Dongxiao Biotechnology, Baolingbao Biology, and Zhucheng Xingmao Corn Developing. These entities focus on cost-effective bulk and food-grade output, leveraging integrated corn processing infrastructure.
Beyond manufacturers, the supply chain includes global traders and distributors such as Mitsubishi Corporation, ProAgro GmbH, and Buxtrade GmbH. These entities facilitate liquidity and logistics but also serve as sentiment indicators for market tightness. The report includes comprehensive profiles of these key companies, analyzing their production capacities, technological focus, and recent strategic moves. Understanding who holds the leverage in specific regions allows clients to negotiate better terms or identify reliable alternative partners should primary supply lines be disrupted by trade policy.
Segmentation and Application Versatility
Erythritol's utility spans far beyond simple sugar replacement in beverages. The market is segmented by type, primarily distinguishing between Powder and Granular forms, each serving different manufacturing requirements. The powder segment often commands different handling and packaging logistics compared to granular variants, influencing the choice of supplier based on the end-product format.
On the application side, the demand is diversified. Beverages represent a significant portion of consumption, driven by the ready-to-drink sector's push for low-calorie profiles. However, substantial volumes are also absorbed by the Bakery and Confectionery sectors, where bulking agents and mouthfeel properties are critical. Dairy products and Pharmaceuticals also utilize erythritol for functional benefits, while the Personal Care sector explores its properties in oral hygiene formulations.
Our segmentation analysis breaks down the revenue contribution across these categories, identifying which sectors offer the highest growth elasticity. For instance, while beverages may offer volume, specialized applications in pharmaceuticals or personal care might offer higher margin potential. The report details these splits to help clients identify white space opportunities. Instead of competing directly in saturated segments, manufacturers can pivot toward applications where erythritol's technical properties offer a unique solution to formulation challenges.
Strategic Imperatives for 2026 and Beyond
As we look toward the forecast horizon ending in 2032, the strategic imperatives for stakeholders become clear. The era of unrestricted arbitrage is ending. Companies must decide whether to integrate vertically to secure feedstock stability, form joint ventures to access protected markets, or specialize in high-value downstream formulations that are less sensitive to bulk commodity price swings.
The convergence of regulatory pressure, raw material volatility, and competitive consolidation means that agility is paramount. Data-driven decision-making is no longer optional. Firms that rely on outdated supply chain maps or ignore the nuances of anti-dumping duty structures risk significant erosion of profitability.
Conclusion and Access to Full Intelligence
The erythritol market presents a complex matrix of opportunity and risk. The growth trajectory is favorable, supported by global health trends and a CAGR of 6.5 percent, but the path to capturing value is obstructed by trade barriers and cost volatility. Success requires a granular understanding of regional dynamics, competitor capabilities, and regulatory timelines.
This overview provides a high-level strategic summary, but the full depth of the analysis resides in our complete market research report. PW Consulting's detailed study includes prognostic models, granular segmentation data by region and type, and comprehensive risk assessment frameworks that are critical for precise planning.
We invite industry leaders, investors, and supply chain executives to access the full report. The complete intelligence package offers the specific data points and confidential industry interviews necessary to build robust strategies. Do not navigate this shifting landscape with partial information. Secure the full strategic advantage by downloading the complete Erythritol Market Research report from PW Consulting today.
For detailed analysis of this topic, please visit the official page: Erythritol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com