

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting BMS Report: Market Hits $13.64B in 2025, Forecasts 15.55% CAGR to $37.51B by 2032
By pmarketresearch, 2026-09-15
Powering the Future: Strategic Intelligence for the Battery Management System Market 2026-2032
Introduction: The Critical Role of BMS in a Decarbonizing World
The global transition toward electrification and renewable energy integration is no longer a speculative forecast; it is an operational reality reshaping industrial landscapes. At the heart of this transformation lies the Battery Management System (BMS), the critical electronic brain that ensures safety, performance, and longevity across lithium-ion and emerging battery chemistries. As enterprises navigate the complexities of 2026, understanding the trajectory of the BMS market is not merely an academic exercise but a strategic imperative.
PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip decision-makers with the granular intelligence required to capitalize on emerging opportunities. This report serves as a definitive guide through the rapidly evolving ecosystem of battery management technologies, offering a clear view of where value is being created and where risks are accumulating. The following insights provide a preview of the strategic depth contained within our full analysis.
Market Trajectory: Scale and Growth Dynamics
The momentum behind the BMS sector is underpinned by robust historical performance and an aggressive growth forecast. Our analysis tracks revenue developments from 2020 through the base year of 2025, establishing a solid foundation for forward-looking projections. In 2020, the global market generated approximately 8.6 billion USD. By 2025, this figure had climbed to 13.64 billion USD, reflecting a compound annual growth trajectory that underscores the accelerating adoption of battery-dependent technologies.
Looking ahead to the forecast period spanning 2026 to 2032, the market is projected to reach 37.51 billion USD. This expansion represents a sustained CAGR of 15.55 percent, signaling that demand drivers are not transient but structural. Such growth rates indicate a market that is maturing yet still expanding rapidly, driven by the dual engines of electric mobility and stationary energy storage. For stakeholders, this trajectory suggests that timing investments correctly will be crucial, as the window to establish competitive positioning before market saturation in certain segments begins to narrow is OPEN.
Building Energy Management System (BEMS) Market
It is important to note that while top-line growth is impressive, the distribution of value across different technological and application layers varies significantly. Our full report dissects these layers to reveal where the highest margins and fastest adoption rates are concentrated, allowing clients to prioritize resources effectively.
Segmentation Insights: Technology, Application, and Regional Nuances
To navigate this market successfully, one must understand the interplay between chemistry types, end-use applications, and geographic dynamics. The report provides a detailed breakdown of the market by technology, distinguishing between Lithium-ion and Lead-acid systems, alongside emerging alternatives. While Lithium-ion continues to dominate due to its energy density and declining cost profiles, specific industrial and legacy applications still rely heavily on established chemistries. Understanding the shifting balance between these types is essential for suppliers manufacturing components or integrators designing systems.
Similarly, the application landscape is diverse. Electric Vehicles (EVs) remain a primary growth vector, but Energy Storage Systems (ESS) and consumer electronics also contribute substantial revenue streams. Each application imposes unique requirements on BMS functionality, ranging from high-current handling in industrial settings to precise communication protocols in solar-plus-storage configurations. Our analysis maps these requirements against current supply capabilities to identify gaps and opportunities.
Geographically, the market exhibits distinct characteristics. While North America and Europe maintain significant shares driven by regulatory mandates and established automotive sectors, the Asia Pacific region represents a massive volume center. Latin America and the Middle East and Africa are emerging as niche but strategically important markets for specific storage and mobility solutions. The full report avoids generic regional summaries, instead providing context on trade flows, local manufacturing capabilities, and regulatory influences that impact market accessibility in each zone.
Competitive Landscape: Key Players and Strategic Moves
The BMS market is characterized by a mix of specialized manufacturers, integrated energy companies, and engineering firms offering custom solutions. Market concentration metrics indicate a CR3 of 25 percent and a CR5 of 35 percent, suggesting that while leading players hold significant influence, the market remains fragmented enough for agile competitors to carve out niches. Success in this environment depends on differentiation through technology, reliability, and ecosystem integration.
Several key companies define the current competitive contours. Daly BMS, based in China, has strengthened its position through continuous product innovation, recently launching a 4th Generation Home Energy Storage BMS with WiFi and Bluetooth connectivity to enhance user monitoring and app integration. Further expanding its ecosystem, Daly announced a new 500W Portable Charger in 2026, demonstrating a strategy to bundle charging solutions with BMS-integrated systems.
In the custom solutions space, Kuruibms has focused on C&I energy storage and EV applications, releasing a market guide in 2026 highlighting top BMS factories to assist buyers in navigating the supply chain. Victron Energy, headquartered in the Netherlands, continues to refine its VE.Bus and Lynx Smart BMS models, updating documentation in early 2026 to ensure compatibility with multiplus inverters and broader energy storage architectures. These updates reflect an industry-wide push toward seamless interoperability between BMS units and inverters.
Battery Management System (BMS) Market
North American and European players are also active. UgoWork in Canada emphasizes safety and fleet deployment by integrating UL 1998 certified BMS with lithium-ion batteries for material handling. Novelic in France designs comprehensive BMS for e-mobility, integrating monitoring and cooling. In Germany, comemso electronics provides critical testing and simulation tools that allow other manufacturers to optimize balancing algorithms, indirectly shaping the quality of BMS deployed in EVs. Meanwhile, Nuvation Engineering and Elithion Inc. in the United States offer custom and embedded BMS solutions for industrial and automotive integration, catering to clients requiring tailored specifications.
Recent industry developments also highlight the importance of ecosystem compatibility. For instance, Sol-Ark issued a battery integration guide in 2026 confirming support for various BMS-equipped storage partners, illustrating how inverter manufacturers are increasingly vetting and aligning with specific BMS providers to reduce integration friction for end users. The full report analyzes these partnerships and product launches to determine which strategic alliances are likely to yield long-term market share gains.
Market Dynamics: Supply Chain, Raw Materials, and Regulatory Pressures
Beyond company profiles and segmentation, the macro-environment plays a decisive role in shaping market outcomes. Raw material volatility remains a key concern for manufacturers and integrators. Spot lithium carbonate prices in China increased from approximately 9,300 USD per ton in January 2025 to 10,300 USD per ton by November 2025, driven by surging energy storage demand and mine disruptions. Similarly, Chinese lithium hydroxide prices rose from roughly 10,300 USD to 11,200 USD per ton over the same period. These movements impact bill-of-materials costs and can compress margins if not managed through strategic sourcing or hedging.
Conversely, the United States saw lithium carbonate annual average prices decline by 31 percent to 9,000 USD per ton in 2025 due to short-term oversupply, though battery-grade prices remain elevated year-over-year. This divergence creates complex arbitrage situations and supply chain decisions for global players. The report examines how these price dynamics influence regional manufacturing strategies and the competitiveness of localized production versus imports.
Regulatory shifts are equally impactful. China's policy of reducing VAT export rebates on lithium-ion batteries, effective from April 1, 2026, prompted a front-loading of production and exports, contributing to price volatility and altering trade flows. In Africa, Zimbabwe imposed a ban on exports of all raw minerals, including lithium concentrate, effective February 2026, further tightening global supply. These regulatory actions underscore the geopolitical risks inherent in the battery supply chain. Our analysis provides scenario planning tools to help clients assess exposure to trade policy changes and raw material restrictions.
Report Contents: Operational Intelligence for Decision Makers
This market research is structured to deliver actionable intelligence rather than abstract data. The full document includes detailed profiles of key companies, analyzing their product portfolios, recent developments, and strategic positioning. We provide a comprehensive segmentation analysis that breaks down revenue and volume by type, application, and region, enabling clients to benchmark their performance against market averages.
The report also features a deep dive into market dynamics, covering drivers, restraints, and opportunities. We examine the impact of raw material price fluctuations, regulatory changes, and technological advancements on market growth. Additionally, the study offers strategic recommendations for various stakeholder groups, including manufacturers, investors, and end-users. These recommendations are grounded in data-driven forecasts and competitive analysis, ensuring that decisions are informed by the latest market realities.
Readers will also find historical data from 2020 to 2025, providing context for current trends, alongside forecast data extending to 2032. This long-term view allows organizations to plan capital expenditures, R&D investments, and market entry strategies with confidence. The inclusion of recent product launches, market guides, and compatibility updates ensures that the analysis reflects the most current state of the industry.
Conclusion: Navigating the Next Wave of Growth
The Battery Management System market stands at a pivotal juncture. With a projected revenue of 37.51 billion USD by 2032 and a CAGR of 15.55 percent, the sector offers substantial opportunities for those who can navigate its complexities. However, success requires more than just observing growth trends; it demands a nuanced understanding of competitive dynamics, supply chain vulnerabilities, and regional regulatory environments.
PW Consulting's comprehensive report provides the depth and clarity needed to make informed strategic decisions. By uncovering hidden patterns in segmentation, evaluating the impact of recent industry developments, and modeling future scenarios, this research empowers organizations to stay ahead of the curve. We invite you to access the full report to gain the complete intelligence picture and leverage these insights for your 2026 planning and beyond. The future of energy storage and electric mobility depends on robust battery management; ensure your strategy is built on the best available data.
For detailed analysis of this topic, please visit the official page: Battery Management System (BMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plasma Sterilizer Market Hits $515M in 2025, Projected 6.1% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperative: Navigating the Plasma Sterilizers Market in 2026 and Beyond
The global healthcare infrastructure is undergoing a paradigm shift in infection control protocols, driven by increasing surgical volumes, stringent regulatory frameworks, and the critical need for sterilizing heat-sensitive medical instruments. For executives and strategic planners, understanding the trajectory of the Plasma Sterilizers Market is no longer optional; it is a fundamental component of capital allocation and risk management. This analysis draws from the comprehensive market intelligence provided in our latest research, offering a high-level view of the landscape while underscoring the necessity of granular data for precise decision-making in 2026.
Market Trajectory and Historical Performance
The plasma sterilization sector has demonstrated consistent resilience and growth over the past half-decade. Historical data from 2020 to 2025 indicates a mature yet expanding market, with revenue climbing from 350.0 million USD to 515.0 million USD. This upward trend reflects the steady adoption of low-temperature sterilization technologies in settings where steam autoclaving is ineffective.
Looking toward the forecast period spanning 2026 to 2032, the market is projected to continue its expansion. The compound annual growth rate (CAGR) is estimated at 6.1 percent. By 2032, overall market revenue is anticipated to reach 775.43 million USD. These figures suggest a stable growth environment, though they mask the underlying volatility and opportunity pockets that exist within specific segments. For a business leader, knowing the aggregate number is the starting point; understanding the drivers behind the variance between 2026 and 2032 is where strategic advantage is found.
The 2026 Decision Matrix: Why Deep Intelligence Matters
As organizations plan their operational roadmaps for 2026, relying on top-line market figures is insufficient. The market is characterized by distinct technological preferences, regional disparities, and application-specific demands that aggregate data cannot reveal. The following sections outline the critical dimensions where detailed intelligence transforms vague strategy into actionable execution.
Technological Segmentation and Device Form Factors
The market is divided into distinct product categories, each serving different clinical and operational needs. Floor-standing units represent a significant portion of the market value, catering to large hospitals and central sterilization departments that require high throughput. However, the rise of portable and table-top plasma sterilizers indicates a shifting trend toward point-of-care sterilization and decentralized processing.
Our report dissects these categories to reveal which form factors are gaining traction in specific clinical settings. For procurement managers, the choice between a floor-standing system and a portable unit involves trade-offs regarding capital expenditure, maintenance logistics, and workflow integration. Understanding the revenue split and growth velocity of each type allows organizations to align their procurement strategies with actual utilization rates rather than legacy habits. The data suggests that while larger systems dominate current revenue, the flexibility of smaller units is driving incremental adoption in specialized clinics and veterinary practices.
Application Diversity: Hospitals and Manufacturing
Demand is not monolithic across end-users. Hospitals remain the primary consumers of plasma sterilization technology, driven by the need to process complex surgical instruments and implantable devices. However, the pharmaceutical and medical device manufacturing sectors represent a high-value secondary market. In these environments, sterilization is critical for ensuring product safety and compliance with good manufacturing practices (GMP).
Plasma Sterilizers Market
The research provides a detailed breakdown of how demand is distributed across these applications. For manufacturers, the opportunity lies in integrating sterilization validation into the product development lifecycle. For healthcare providers, the focus is on throughput and compatibility with diverse instrument sets. The report examines the specific revenue contributions of hospitals versus manufacturing sectors, highlighting where the highest margin opportunities and volume demands reside. Ignoring the nuance between these application fields can lead to misaligned product positioning or failed market entry strategies.
Regional Dynamics and Global Distribution
Geography plays a pivotal role in market accessibility and growth potential. While North America has historically maintained a dominant position in terms of revenue generation, other regions are exhibiting evolving maturity levels. Europe holds a substantial share, reflecting strong healthcare infrastructure and regulatory compliance standards. Meanwhile, the Asia Pacific region presents a different growth profile, often characterized by increasing healthcare expenditure and expanding hospital networks.
Latin America and the Middle East and Africa constitute smaller portions of the global revenue base but offer emerging opportunities as healthcare systems modernize. Our analysis avoids generic regional generalizations. Instead, it provides specific insights into which regions are driving volume versus value. For international players, knowing where the revenue is concentrated helps in prioritizing distribution channels and regulatory approvals. For instance, a strategy focused on high-volume, low-cost units might target different regions compared to a strategy focused on premium, high-throughput systems. The full report details the specific revenue magnitudes for each region, enabling a precise geographic prioritization matrix.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with a significant portion of revenue held by leading players. The competition is defined not just by market share but by technological innovation, regulatory clearance, and specific product differentiation. Understanding the moves made by key competitors is essential for anticipating market shifts and identifying gaps in the offering.
Key Market Participants
Several companies define the current competitive landscape, each with distinct strategic focuses:
- Tuttnauer , headquartered in Breda, Netherlands, is known for producing the PlazMax line of low-temperature hydrogen peroxide plasma sterilizers. Their focus remains on instruments that are sensitive to heat and moisture, positioning their technology as a reliable solution for general medical instrument sterilization.
- Advanced Sterilization Products (ASP) , based in Irvine, California, continues to be a pivotal player with its STERRAD 100NX Sterilizer featuring ALLClear Technology. This platform is widely recognized for low-temperature hydrogen peroxide gas plasma sterilization.
- Plasmapp , from Seoul, South Korea, markets the STERLINK medical cryo plasma sterilizer. With FDA clearance for units under 20 L capacity, they target specific niches requiring compact, low-temperature sterilization solutions.
- Steris Corporation , located in Warrendale, Pennsylvania, offers V-PRO low-temperature plasma sterilization systems. Their portfolio is heavily integrated into the broader medical device and hospital sterilization ecosystem.
- VetOvation , operating in the United States, provides Sterlink gas plasma sterilizers specifically tailored for veterinary hospital applications, highlighting a specialized vertical within the broader market.
Recent Developments and Regulatory Shifts
The competitive environment is dynamically influenced by regulatory clearances and technological updates. In April 2025, Advanced Sterilization Products Inc. received FDA 510(k) Clearance for the STERRAD 100NX Sterilizer with ALLClear Technology (K250802). This clearance validates the use of hydrogen peroxide gas plasma sterilization for a broad range of medical instruments, reinforcing the platform's compliance standing.
Furthermore, in August 2024, ASP collaborated with PENTAX Medical to secure FDA clearance for the ULTRA GI Cycle. This cycle is designed for use in the STERRAD 100NX Sterilizer with ALLClear Technology specifically for duodenoscope reprocessing. This development underscores the importance of specialized cycles for complex devices like duodenoscopes, where infection control is critical. Similarly, PENTAX Medical received FDA clearance in August 2024 for the DEC Duodenoscope, which is compatible with the STERRAD 100NX Sterilizer plasma technology.
These events highlight a trend where regulatory approval is not just a one-time hurdle but an ongoing process of expanding indications and compatible device portfolios. For competitors and investors, tracking these clearances is vital for assessing the longevity and scope of competing platforms.
Regulatory and Reimbursement Dynamics
The operating environment for plasma sterilizers is heavily influenced by regulatory standards and institutional reimbursements. Recognition by major health bodies provides the foundational trust required for adoption. Hydrogen peroxide gas plasma sterilizers are recognized by the CDC and FDA as Established Category A low-temperature sterilization processes. This classification confirms their compatibility with heat- and moisture-sensitive medical devices, providing a regulatory seal of approval that drives procurement in regulated healthcare environments.
Additionally, the standardization of validation processes is tightening. The FDA has recognized ISO 22441:2022 as the standard for low-temperature vaporized hydrogen peroxide sterilization validation and routine control. Compliance with this standard is becoming a baseline expectation for manufacturers and users alike. Our report analyzes how these regulatory benchmarks impact market entry barriers and operational costs. Organizations must ensure their sterilization protocols align with these evolving standards to avoid compliance risks. The full intelligence provided in the study details how these regulations influence regional adoption rates and product design requirements.
Desktop Plasma Cleaner Market
Strategic Outlook for 2026
As the market moves through the forecast period, the convergence of technological maturity, regulatory enforcement, and healthcare expansion will define the growth trajectory. The projected revenue growth from 563.22 million USD in 2026 to 775.43 million USD in 2032 indicates a robust market potential. However, capturing this value requires more than observing the growth curve.
Strategic decisions in 2026 will hinge on understanding the interplay between product types, application needs, and regional readiness. For instance, the concentration of market share among top players suggests that partnership or niche specialization may be necessary for new entrants. The specific revenue contributions of regions like North America versus Asia Pacific will dictate where capital should be deployed for maximum return. Similarly, the divergence between hospital-based demand and manufacturing requirements necessitates tailored value propositions.
This overview provides a foundational understanding of the Plasma Sterilizers Market landscape. However, the true utility for strategic planning lies in the granular details that drive these aggregates. The exact revenue splits, the precise CAGR variations across segments, and the detailed competitive profiling contained in the full report are essential for building a resilient strategy.
To access the complete dataset, including specific regional revenue figures, detailed segmentation splits, and comprehensive company profiles with recent strategic developments, we invite you to secure the full market research report. In a market defined by 6.1 percent CAGR and evolving regulatory standards, the difference between average performance and market leadership often lies in the depth of intelligence available to decision-makers.
For detailed analysis of this topic, please visit the official page: Plasma Sterilizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refrigerated Display Cases Market Hits $9.83 Billion in 2025, Projects 7.4% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Cold Chain: Navigating the Refrigerated Display Cases Market Outlook 2026–2032
Executive Summary: The Imperative for Data-Driven Decision Making
The global refrigeration landscape is undergoing a structural transformation driven by tightening environmental regulations, evolving consumer expectations for product visibility, and relentless pressure on operational energy costs. For stakeholders across retail, foodservice, and commercial refrigeration, the Refrigerated Display Cases Market represents a critical nexus of capital expenditure, compliance risk, and revenue generation. PW Consulting has synthesized a comprehensive market research study spanning the historical trajectory from 2020 through 2025 and projecting forward to 2032. This analysis delivers the strategic intelligence required to navigate the complexities of the 2026 market environment and beyond. The research is designed not merely as a static snapshot, but as a dynamic planning tool that equips executives, procurement leaders, and investors with the granular insights necessary to allocate capital efficiently and hedge against systemic volatility.
Macro Trajectory and Revenue Projections
Understanding the overarching revenue trajectory is the first step in framing strategic investments. Over the historical review period, the market demonstrated consistent expansion, rising from a baseline of 6,865.0 million USD in 2020 to 9,830.0 million USD by 2025. This upward momentum is projected to continue, with the market valuation expected to reach 10,331.18 million USD in 2026 and accelerate toward 16,140.0 million USD by the end of the forecast period in 2032. The analysis indicates a robust compound annual growth rate of 7.4 percent over the 2026 to 2032 forecast window. This macroeconomic expansion is underpinned by widespread modernization initiatives in grocery and convenience sectors, alongside mandatory upgrades triggered by regulatory shifts. However, aggregate figures only tell part of the story. The true strategic advantage lies in dissecting the velocity of growth across different technological architectures, application verticals, and geographic corridors, each of which presents distinct risk-return profiles for market participants.
Core Report Architecture and Actionable Intelligence
The complete research study is structured to provide end-to-end visibility into the market ecosystem, enabling stakeholders to build resilient business strategies. The report delivers a multi-dimensional analysis that moves beyond surface-level observations to uncover the operational and financial drivers shaping the industry. Key components include:
- Comprehensive profiling of market segmentation by product architecture, covering plug-in, remote, and semi-plug-in configurations, with detailed assessments of their respective adoption curves and total cost of ownership implications.
- Deep-dive evaluation of application verticals, examining how demand dynamics diverge between food service operations and retail food and beverage environments, including channel-specific purchasing behaviors and capacity utilization metrics.
- Regional market mapping that quantifies demand intensity, infrastructure readiness, and competitive saturation levels across major economic zones, providing a framework for prioritizing market entry or expansion initiatives.
- Supply chain and raw material analysis that tracks pricing volatility, component availability, and manufacturing constraints affecting critical inputs such as tempered glass, stainless steel, and aluminum, alongside mitigation strategies for procurement teams.
- Regulatory impact modeling that quantifies the financial and operational consequences of compliance mandates, including refrigerant charge limits, energy efficiency certification requirements, and phase-out timelines for legacy technologies.
- Competitive benchmarking and strategic grouping of market participants based on product portfolios, geographic footprints, innovation pipelines, and corporate development trajectories.
This structured approach ensures that decision-makers can align technology selection, capital deployment, and partnership strategies with the specific growth vectors and constraint boundaries that define the current market cycle.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment, with the top three participants collectively commanding approximately 48.0 percent of total revenue and the leading five firms accounting for 57.0 percent. This concentration reflects the high barriers to entry associated with engineering certification, distribution network development, and compliance with stringent energy and environmental standards. The competitive field features a mix of established multinational manufacturers and specialized regional players, each pursuing distinct value propositions to differentiate their offerings.
In North America, prominent players such as Hussmann Corporation from Chicago, Carrier Commercial Refrigeration based in Syracuse, Zero Zone Inc. from Madison, True Manufacturing Co. Inc. in Saint Augustine, Hillphoenix Inc. in Fort Worth, and Kysor Warren in Dallas maintain strong market positions through expansive product lines and direct service networks. Hussmann, for instance, has built its reputation on a comprehensive lineup of multi-deck, island, and reach-in merchandisers that integrate natural refrigerants, energy-efficient lighting, and customizable configurations tailored to retail and foodservice environments. Carrier Commercial Refrigeration emphasizes integrated store systems and display cases featuring both plug-in and remote solutions, with a strong focus on low-GWP refrigerants and smart control architectures that enable centralized monitoring and optimization. Zero Zone Inc. offers a suite of series including Crystal, Highlight, Guardian, and Reveal, alongside its Hybrid and ultra-narrow models engineered for energy efficiency and space optimization in constrained retail footprints. True Manufacturing Co. Inc. focuses on reach-in coolers, glass-door merchandisers, and display cases that prioritize durability, LED lighting integration, and energy performance across both foodservice and retail applications. Hillphoenix Inc. has positioned itself at the forefront of sustainable refrigeration with its AdvansorFlex CO2 and SoloChill series, which are optimized for energy efficiency, serviceability, and transcritical system performance. Kysor Warren contributes specialized refrigerated merchandisers engineered for durability, reliability, and labor savings in supermarket and retail settings.
European manufacturers bring distinct engineering philosophies and regulatory compliance expertise to the global market. Epta S.p.A., headquartered in Vimercate, Italy, delivers the Zenith and Costan lines of vertical and multi-deck refrigerated cabinets, achieving up to 36 percent energy savings through natural refrigerants and PFAS-free insulation, with EU Energy Class B certification. Arneg S.p.A., based in Bologna, emphasizes modular and plug-in refrigerated cabinets with a strong emphasis on sustainable refrigeration and custom store design solutions that adapt to varied retail formats. AHT Cooling Systems GmbH from Austria offers the BOREA and plug-in multideck refrigerated cases utilizing natural refrigerants such as R290, targeting retail outlets and convenience stores with compact, efficient configurations. In the Asia-Pacific region, Hoshizaki Corporation in Nagoya, Japan, provides reliable refrigerated display cases with a focus on convenience store and foodservice segments, emphasizing durability and energy performance. Frigoglass S.A.I.C., based in Athens, Greece, supplies glass-door coolers and refrigerated cabinets tailored for beverage and food display, supported by an international distribution network that extends its reach across multiple continents.
Refrigerated Display Cases Market
Recent Industry Movements and Innovation Signals
Recent corporate activities underscore the pace of technological advancement and the strategic importance of product innovation in capturing market share. In September 2025, Hussmann Corporation launched the RLN-A and RMN-A reach-in merchandisers, incorporating Air-Cooled Microblock technology designed to improve product temperature retention and enhance energy efficiency. This launch reflects a broader industry trend toward thermal management optimizations that directly impact both compliance standing and operating cost structures. In July 2025, Epta S.p.A. showcased the MD3 double-sided multideck cabinet at Metcash 2025, a configuration offering up to 30 percent floor space reduction for independent retail stores. Such space-saving innovations address the persistent challenge of maximizing merchandising density without compromising cooling performance or customer accessibility. In April 2025, Hillphoenix Inc. introduced ChargeSecure technology for CO2 refrigeration systems, delivering 1.5 amps operation and consuming six times less energy than conventional units. These developments highlight the competitive advantage accruing to manufacturers that can simultaneously address energy efficiency, refrigerant compliance, and operational reliability. Stakeholders who track these innovation cycles gain early visibility into emerging product standards and can align their procurement or development roadmaps accordingly.
Regulatory Pressures and Material Constraints Shaping Market Dynamics
The 2026 market environment is being reshaped by a confluence of regulatory mandates and material supply dynamics that demand proactive strategic adaptation. Starting January 1, 2026, new installations of Hybrid merchandisers are prohibited under the AIM Act, requiring replacement with low-GWP refrigerant alternatives. This regulatory shift, coupled with low-GWP refrigerant requirements under the AIM Act that limit refrigerant charge to 200 pounds for new installations, is driving accelerated adoption of R-290 and CO2 systems in display cases. These constraints are not merely compliance checkboxes; they fundamentally alter the economics of product selection, installation logistics, and long-term service contracts.
In parallel, EU Energy Class B certification mandates for vertical refrigerated cabinets are compelling manufacturers and end-users to prioritize high-efficiency designs. Epta's Zenith line, achieving up to 36 percent energy savings through natural refrigerants and PFAS-free insulation, exemplifies the performance benchmarks now required to meet these standards. On the materials front, glass doors dominate refrigerated display cases, with tempered safety glass capturing approximately 38.7 percent market share due to its optical clarity and hygiene compliance. Stainless steel and aluminum remain primary structural materials, and while component costs including steel, aluminum, and glass showed moderated price volatility in 2025, persistent supply chain risks continue to warrant careful inventory planning and supplier diversification. These regulatory and material factors interact to create a complex decision matrix where energy performance, compliance timelines, and input cost stability must be evaluated in concert.
Strategic Implications for 2026 and the Path Forward
The refrigerated display cases market in 2026 presents a landscape where growth is accessible but competition for share is intensifying, and where regulatory compliance is no longer a peripheral concern but a central pillar of product strategy. Organizations that succeed in this environment will be those that integrate macro demand signals with micro-level insights into product architectures, regional adoption patterns, and competitive maneuvering. The full study provides the detailed segmentation data, regional revenue breakdowns, application-specific growth rates, and competitor benchmarking matrices necessary to construct precise market entry strategies, optimize portfolio mixes, and anticipate regulatory-driven demand shifts. Readers seeking to unlock the complete dataset and proprietary analytical frameworks are encouraged to access the source research portal, where the full report delivers the granular intelligence required to inform capital allocation, technology roadmapping, and long-term competitive positioning.
Worldwide Home Display Case Market
For detailed analysis of this topic, please visit the official page: Refrigerated Display Cases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Basmati Rice Market to Hit $315.1M by 2032, Growing at 6.98% CAGR
By pmarketresearch, 2026-09-15
Strategic Horizons: Navigating the Global Basmati Rice Market in 2026 and Beyond
Executive Summary: The Imperative for Precision Intelligence
The global basmati rice sector stands at a critical juncture where traditional trade flows intersect with shifting regulatory frameworks, evolving consumer preferences, and strategic realignment among key producing nations. For executives, procurement leaders, and market strategists operating in 2026, relying on retrospective summaries or anecdotal trade intelligence is no longer sufficient. The market is characterized by compounding macroeconomic pressures, fragmented supply chains, and highly asymmetric information flows across regions. Our latest basmati rice market research was designed to close that gap.
Prepared as a comprehensive analytical foundation rather than a superficial industry overview, this report translates multi-year historical performance and forward-looking model trajectories into actionable strategic intelligence. It is engineered to support pricing architecture, sourcing diversification, capacity planning, export positioning, and risk mitigation across the entire basmati value chain. The following sections outline the analytical rigor, structural frameworks, and decision-ready content embedded within the study, demonstrating why it serves as a critical reference point for enterprise strategy in the current operating environment.
Market Trajectory and Structural Momentum
Historical baselines spanning 2020 through 2025 reveal a market that has absorbed external disruptions, adapted to shifting demand patterns, and consistently expanded its revenue footprint. Over this period, the global basmati rice market progressed from approximately $147.5 million to $198.0 million, reflecting sustained growth driven by expanding consumer adoption, strengthening trade linkages, and product standardization across major export corridors. This historical momentum establishes a reliable baseline for evaluating forward performance.
The forward trajectory extends through 2032, projecting continuous expansion with a compound annual growth rate of 6.98 percent. Under this modeled pathway, market revenue scales from an estimated $205.89 million in 2026 to over $315.1 million by 2032. These figures represent aggregate market evolution rather than isolated product or channel spikes, indicating that underlying demand drivers are structural rather than cyclical. Importantly, this growth is unevenly distributed across geographies and product formats, meaning that generalized assumptions can misallocate capital or expose firms to avoidable margin compression.
Because growth is not uniform, decision-makers require granular visibility into where value is concentrating, which formats are driving incremental dollar share, and how regional demand elasticity interacts with trade policy shifts. The report addresses this complexity by mapping historical inflection points, identifying the mechanisms behind period-over-period revenue shifts, and situating forward projections within established market architecture. The objective is to enable firms to distinguish between durable expansion and temporary arbitrage opportunities, ensuring that investment and sourcing commitments align with long-term structural realities rather than short-term headline noise.
Report Architecture: Operational Content for Execution Teams
A market study only delivers value when it translates into executable direction. Accordingly, this publication was structured around operational deliverables that procurement, commercial, and strategy teams can integrate directly into planning cycles. The analytical architecture moves from macro validation to segment-level mechanics, then to competitive and regulatory overlays, ensuring that every conclusion is traceable to methodologically consistent inputs.
Core components include a full historical reconstruction from 2020 through 2025, with period-over-period revenue movements contextualized against demand shifts, pricing behavior, and trade flow adjustments. The forward modeling covers 2026 through 2032 and is built on scenario-sensitive assumptions, allowing leadership to test sensitivity around volume growth, price realization, and policy-induced supply changes. Rather than presenting a single deterministic path, the study incorporates structural variability so that organizations can evaluate performance under differing operating conditions.
The segmentation framework examines the market through format distinctions, demand-end utilization patterns, and regional allocation trends. These dimensions are deliberately analyzed in combination because basmati rice performance cannot be understood through a single lens. Format shifts influence processing requirements and pricing tiers. Demand-channel dynamics shape inventory velocity, promotional strategy, and margin structure. Regional performance reflects trade agreements, tariff exposure, logistical constraints, and consumer preference evolution. By treating segmentation as an interconnected system, the report enables readers to identify which combinations are generating disproportionate value and where realignment may be necessary.
Another critical layer is competitive and institutional mapping. The study profiles the organizations shaping production, export coordination, trade facilitation, and downstream brand positioning. It does not limit analysis to product attributes; it also evaluates how trade bodies, industry associations, and export federations influence market access, policy advocacy, certification environments, and negotiating leverage. This institutional dimension is especially relevant in agricultural commodity markets, where collective representation and government-aligned export frameworks can alter competitive outcomes as significantly as individual firm strategy.
Basmati Rice Market
Finally, the regulatory and macro context is integrated throughout rather than isolated as a standalone appendix. Trade restrictions, tariff adjustments, floor price mechanisms, certification requirements, and supplier registration processes are analyzed for their direct impact on cost structures, shipment timing, and market-entry feasibility. This ensures that strategic recommendations are grounded in operational reality, not abstract market sizing.
Competitive Architecture and Institutional Dynamics
The basmati rice ecosystem is shaped by a mix of commercial producers, export associations, and institutional research bodies, each exerting influence over pricing, quality standards, supply reliability, and market access. Understanding this architecture is essential for firms seeking to navigate sourcing decisions, brand positioning, and regional expansion strategies.
Among commercial brand actors, RiceSelect operates as an active US-based producer offering Texmati White Rice, a hybrid basmati-style aromatic long-grain product developed through previous RiceTec lineage. The company emphasizes non-GMO, gluten-free, and Kosher-certified positioning while expanding sustainable lines that include Premium Indian Basmati Rice. For downstream distributors and retail partners, this profile signals a strategy that blends American-market familiarity with international basmati credentials, emphasizing certification, product consistency, and sustainability messaging as differentiators. The strategic implication is not merely product availability but brand architecture: firms entering or expanding in the US market must contend with players that are actively bridging origin credibility with domestic retail expectations.
On the export coordination side, the Rice Exporters Association of Pakistan (REAP) serves as a central institutional vehicle for Pakistani basmati rice exporters. Its function extends beyond membership administration to include trade delegation facilitation, global market promotion, and direct engagement with overseas buyers. Recent US engagement activities illustrate how producer-country associations increasingly act as coordinated market-access platforms, helping align exporter interests with foreign distributor expectations. In a market where origin perception, pricing competitiveness, and compliance readiness all influence purchasing decisions, such institutional coordination can materially affect the speed and scale at which supplying countries expand footprint.
The India Rice Exporters Federation (IREF), based in New Delhi, operates as an apex trade body representing Indian rice exporters. It supports basmati producers and facilitates policy advocacy directed at export-oriented production and trade. Given the scale and global prominence of Indian basmati shipments, IREF’s advocacy and coordination role influences how exporters interpret regulatory shifts, manage certification obligations, and respond to policy recalibration. In practical terms, these institutions function as information and negotiation hubs, shaping how producer-country supply responds to international price signals and import-country trade rules.
Competitive understanding also requires situational awareness of recent high-visibility events that expose operational vulnerabilities and accelerate structural adjustments. A voluntary recall involving Kirkland Signature Traditional Basmati Rice in the US retail environment underscores the sensitivity of consumer-facing supply chains to quality assurance failures. Even when isolated, incidents of this nature affect retailer confidence, audit expectations, and supplier qualification standards. For sourcing teams, the lesson is not simply risk avoidance but the need for rigorous traceability, batch control, and supplier compliance documentation across the basmati supply chain.
Equally relevant is the institutional push toward input efficiency and cultivation modernization. The launch of new RobiNOweed Basmati Rice varieties developed for direct seeded rice cultivation reflects an industry-level response to resource constraints, particularly water usage. Varieties designed for DSR systems can alter production economics, yield stability, and regional planting patterns. For buyers and analysts, such developments signal potential shifts in supply-side cost structures and long-term agronomic conditions, especially in producing regions where water availability and labor economics remain pressing considerations.
Regulatory and Trade Realignment: Mapping Systemic Risk
Trade policy and regulatory design have become central determinants of basmati rice competitiveness. In 2026, market participants cannot evaluate sourcing or export strategy without accounting for tariff asymmetry, floor price changes, export restriction cycles, and registration frameworks that govern shipment eligibility.
A significant competitive shift emerged from tariff divergence affecting US import dynamics. The imposition of a 50 percent tariff on Indian basmati rice imports raised effective landed costs and altered relative price positioning in the American market. This development created conditions in which Pakistani basmati rice, subject to a lower tariff rate, gained renewed competitiveness. The strategic consequence is not a simple swap of origin preference; it is a recalibration of price-sensitive procurement, brand positioning, and distributor negotiation leverage. Firms that fail to incorporate tariff-adjusted landed cost modeling into sourcing decisions risk mispricing, margin erosion, or suboptimal supplier allocation.
Regulatory recalibration in the producing country context further complicates planning. India’s policy actions included the lifting of export restrictions on non-basmati white rice alongside the removal of the basmati minimum export floor price, changing the incentive structure for exporters and downstream traders. These adjustments influence shipment timing, export willingness, and downstream pricing expectations across the broader rice trade architecture. Even when a firm’s focus is basmati specifically, non-basmati policy moves matter because they affect total export capacity, logistics utilization, and the strategic behavior of exporters who manage multiple product categories simultaneously.
At the same time, institutional registration and allocation mechanisms remain critical for market participation. APEDA’s issuance of a substantial volume of registration cum allocation certificates for Indian basmati rice exporters during the 2024-25 fiscal year demonstrates the continued role of formalized export authorization in governing shipment eligibility and trade transparency. For international buyers and distributors, the existence of structured registration systems reinforces the importance of verifying exporter status, allocation compliance, and documentation readiness before committing to supply agreements.
Pakistan’s ongoing efforts to expand US market presence also highlight the strategic importance of distributor engagement, pricing alignment, and compliance readiness. Trade discussions involving US distributors reflect a deliberate push to secure market access through commercial and regulatory coordination. In practice, this means that competitive advantage in target markets increasingly depends on a supplier’s ability to demonstrate consistent quality, price competitiveness under tariff conditions, and adherence to buyer-specific compliance expectations.
Procurement, Pricing, and Expansion Strategy in 2026
For enterprise decision-makers, the strategic question is not whether the basmati rice market is expanding, but how to position operations to capture value without overexposing the organization to compliance, pricing, or supply continuity risk. This requires a disciplined approach to sourcing architecture, pricing strategy, and market-entry planning.
Sourcing diversification should be evaluated through the lens of landed-cost realism rather than origin branding alone. Tariff differentials, logistics reliability, certification requirements, and supplier compliance maturity all influence effective cost. Firms that maintain concentration in a single origin or a narrow supplier base may find themselves vulnerable to policy shifts or trade-flow disruptions. A more resilient approach involves mapping multiple qualified sources, stress-testing scenarios against tariff and floor-price changes, and aligning supplier selection with specified audit and documentation expectations.
Pricing architecture must account for volatility in both input markets and trade policy. Floor price changes, tariff adjustments, and recall-driven quality reassessments can alter the price environment faster than traditional seasonal forecasting anticipates. Organizations should incorporate scenario-based pricing models that include tariff-adjusted comparisons, compliance cost assumptions, and quality-assurance overhead. This helps prevent margin compression when external conditions shift unexpectedly.
Market expansion planning should be equally disciplined. Regional demand patterns differ materially in terms of channel structure, price sensitivity, and certification expectations. Retail and household demand typically favors consistent quality, packaging reliability, and brand trust, while foodservice and hospitality channels emphasize volume consistency, specification adherence, and operational reliability. Understanding which demand environment a firm is entering allows more precise commercial execution and reduces the risk of misaligned positioning.
Quality assurance and traceability also deserve elevated strategic priority. High-visibility quality incidents in consumer-facing channels demonstrate that retailer confidence can be fragile. Supplier qualification processes should therefore go beyond basic product specifications to include traceability systems, batch control discipline, documentation completeness, and audit responsiveness. In a market where brand reputation and retailer trust are closely tied to supply integrity, these capabilities can function as competitive differentiators.
Organic Rice Market
Finally, developments in cultivation technology and resource efficiency should be monitored as longer-term supply-side indicators. Agronomic shifts that reduce water usage or improve direct seeding viability can influence regional production economics and supply stability over time. While these changes may not translate immediately into short-term pricing moves, they are relevant to medium- and long-term sourcing strategy, especially for organizations with multi-year supply commitments or regional expansion targets.
Why the Full Study Matters for Executive Decision-Making
The basmati rice market presents a paradox that many organizations underestimate: the headline trajectory is strong, but the operational levers that determine success are highly specific. Aggregate growth figures and broad regional performance indicate favorable conditions, yet they do not reveal which formats are generating disproportionate revenue, which channels are most sensitive to price or certification shifts, or how tariff and policy divergence is reshaping competitiveness in key import markets. Without segment-level clarity, firms risk making allocation, pricing, and sourcing decisions on incomplete pictures.
This report is built to resolve that ambiguity. It connects historical performance with forward modeling, embeds segmentation analysis within the broader market architecture, and overlays competitive and regulatory dynamics so that decision-makers can see not only where the market is heading, but also what actions are required to respond effectively. The objective is to provide a defensible analytical foundation for procurement strategy, commercial planning, brand positioning, and risk management.
Organizations that rely on partial information may identify opportunities, but they often misjudge the cost of pursuing them. In contrast, teams equipped with structured segment insights, scenario sensitivity, institutional mapping, and regulatory context can allocate resources more precisely, negotiate with greater confidence, and anticipate competition more effectively. That is the strategic value the full study is designed to deliver.
To obtain the detailed segmentations, scenario-based projections, competitive profiles, and operational frameworks referenced throughout this overview, access the complete Basmati Rice Market research on the PW Consulting portal. The full intelligence set is structured for immediate integration into enterprise planning workflows and is intended to support decision-making with the level of specificity required for 2026 strategy execution.
For detailed analysis of this topic, please visit the official page: Basmati Rice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ESP Market Hits $8.3B in 2025, Projected $12.79B by 2032 at 6.4% CAGR
By pmarketresearch, 2026-09-15
Electrostatic Precipitators Market: Strategic Intelligence for the 2026–2032 Investment Horizon
As global industrial emissions face intensifying regulatory scrutiny and energy transition mandates, electrostatic precipitators (ESP) have evolved from conventional particulate control equipment to mission-critical infrastructure within the broader decarbonization and air quality compliance ecosystem. Our latest research publication, Electrostatic Precipitators (ESP) Market: Strategic Forecast & Competitive Intelligence 2026–2032 , delivers a rigorously modeled, commercially actionable assessment designed specifically for executive teams, capital allocators, and technology procurement leaders navigating the next multi-year cycle. This briefing outlines why this analysis is strategically indispensable for 2026 decision-making, what operational intelligence it provides, and how organizations can leverage its architecture to secure competitive advantage in a rapidly consolidating market.
Why This Research Matters for 2026 Decision-Making
Corporate strategy in environmental control technology is no longer driven by isolated compliance requirements; it is shaped by capital efficiency, supply chain localization, digital integration, and long-term asset lifecycle economics. The 2026–2032 period represents a structural inflection point where legacy ESP installations require modernization, new industrial capacity demands higher collection efficiencies, and regulatory frameworks tighten particulate emission thresholds across multiple jurisdictions. Organizations that enter this cycle with fragmented data or outdated cost assumptions risk misaligned procurement, suboptimal capacity planning, and exposure to margin compression.
Our report is engineered to close that intelligence gap. It translates historical trajectory, forward-looking growth signals, and competitive positioning into a decision-ready framework. By anchoring analysis in verified historical performance and modeling forward under multiple adoption scenarios, the study equips strategy, operations, and procurement teams with the visibility needed to time investments, evaluate supplier risk, and align technology roadmaps with corporate sustainability and compliance targets.
Market Trajectory and Forward-Looking Growth Signals
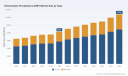
The ESP market has demonstrated consistent expansion across recent years, reflecting sustained industrial demand, upgrade cycles for existing installations, and the continued deployment of particulate control systems in power generation, heavy processing, and emerging waste-to-energy applications. The historical baseline from 2020 through 2025 shows a market that has steadily scaled, with revenue progressing from approximately USD 6.5 billion at the start of the period to roughly USD 8.3 billion by the base year. This progression underscores an entrenched demand environment rather than a transient compliance spike.
Worldwide Dry Electrostatic Precipitator Market
Forward momentum remains firmly positive. The forecast trajectory for 2026 projects revenue approaching USD 9.06 billion, followed by continued expansion through 2032, with the terminal year reaching approximately USD 12.79 billion. This path corresponds to a compound annual growth rate of 6.4 percent over the forecast window. Importantly, the growth curve is not uniform across all demand drivers; it reflects a combination of capacity additions, regulatory-driven retrofits, operator preferences for higher-efficiency configurations, and incremental adoption in sectors that previously relied on alternative filtration approaches. These dynamics create a multi-layered opportunity landscape where procurement timing, technology selection, and aftermarket service strategy materially influence total cost of ownership.
Strategic readers will note that the growth narrative is best understood not as a single-volume projection, but as a portfolio of application-specific demand pulses, regional deployment rhythms, and technology-specific replacement cycles. The full study decomposes these layers without exposing the granular splits prematurely, ensuring that interested stakeholders engage directly with the complete modeling architecture to extract the precise segmentation intelligence relevant to their operating footprint.
Market Structure, Competitive Dynamics, and Strategic Positioning
The ESP competitive environment is moderately concentrated, with the top three participants collectively accounting for approximately 38.2 percent of market revenue and the top five representing about 55.0 percent. This concentration indicates a market where scale, installed-base advantages, service network density, and proven high-efficiency collection capabilities create meaningful barriers for new entrants, while still leaving space for specialized manufacturers, regional integrators, and technology innovators to differentiate through application-specific engineering, digital control modules, and customized wet or dry ESP configurations.
Several established players illustrate the breadth of competitive strategies currently shaping the market. Babcock & Wilcox Enterprises, Inc. continues to reinforce its leadership position with an extensive installed base exceeding 5,000 systems worldwide and demonstrated high-efficiency collection performance up to 99.9 percent across wet and dry ESP platforms for utility and industrial power generation. In June 2025, the company secured more than USD 18 million in wet and dry ESP rebuild contracts for utility and industrial plants across the U.S. and Europe, reaffirming the commercial importance of lifecycle rebuild programs alongside new equipment deliveries.
FLSmidth & Co. A/S has been advancing application-specific ESP solutions for cement and industrial environments, increasingly integrating AI-enhanced control systems to optimize collection performance and operational stability. In February 2025, the company expanded its service center network with a new facility in Dammam, Saudi Arabia, strengthening regional support for advanced emission control technologies, including electrostatic precipitators. This localized service expansion reflects a broader industry pattern: competitive advantage is increasingly determined by the proximity of technical support, parts availability, and predictive maintenance capabilities rather than equipment supply alone.
Valmet Oyj supplies ESP solutions tailored to pulp and paper recovery boilers, where process conditions demand robust particulate capture and integration with recovery cycles. In February 2024, the company shipped electrostatic precipitators to Nordic Paper’s Swedish Backhammar recovery boiler, with completion targeted by the end of 2025. Mitsubishi Heavy Industries, Ltd. has similarly extended its high-efficiency ESP footprint into large-scale industrial applications, including a September 2024 delivery of an ESP unit for a 700,000-tonne chemical pulp project in China. These engagements demonstrate how major suppliers are aligning ESP deployments with sector-specific process engineering rather than treating particulate control as a standalone commodity purchase.
Beyond these highlighted developments, the competitive field includes a broad set of specialists and industrial integrators. DÜRR AG emphasizes advanced ESP technologies integrated with gas cleaning systems for industrial emission control. Ducon Technologies Inc. manufactures custom wet and dry ESP systems for power, cement, and steel applications. Fuel Tech, Inc. combines ESP with flue gas conditioning and NOx reduction technologies for coal-fired utilities. GEA Group AG manufactures ESP for food, pharmaceutical, and chemical industry environments. KC Cottrell, Inc. focuses on wet ESP for utility and industrial applications. Monroe Environmental, LLC provides industrial ESP solutions for air quality control. GEECO Enercon GmbH specializes in high-efficiency ESP systems for industrial and power sector emission control. Sumitomo Heavy Industries, Ltd. develops ESP integrated with flue gas treatment systems. Trion, Inc. targets commercial and industrial air filtration. Wood plc delivers ESP as part of broader power generation and environmental control system offerings.
This diversified competitive fabric matters strategically because procurement decisions increasingly weigh total value over nominal equipment price. Operators evaluate supplier track record in specific applications, availability of rebuild and upgrade programs, ability to integrate digital controls and flue gas conditioning, and capacity to support compliance with evolving emission limits. The comprehensive competitive section of our report maps these positioning dimensions across the profiled companies, enabling readers to benchmark capabilities, identify partnership or sourcing opportunities, and assess where consolidation, regional expansion, or technology differentiation is likely to reshape supplier relationships.
Structural Drivers and Operational Constraints Shaping Investment Logic
Market growth is reinforced by a combination of regulatory pressure, process modernization, and operational reliability requirements. In the United States, the EPA Mercury and Air Toxics Standards require coal-fired power plants to contain filterable particulate emissions at 0.03 lb/MMBtu, directly accelerating ESP deployment and upgrade activity in utility environments. Alongside this, U.S. federal regulations on particulate matter emissions from industrial sources continue to compel industries to adopt ESP technologies for compliance, expanding the addressable base beyond traditional power generation.
These regulatory tailwinds interact with practical operational considerations. High capital and maintenance costs for advanced ESP systems incorporating digital control modules, corrosion-resistant materials, and hybrid filtration technologies require substantial upfront investment, elevating the importance of lifecycle economics and financing strategy. Electrical energy consumption in electrostatic precipitators can be substantial, with resulting high operating costs for large-scale installations, making energy-efficient design, optimized voltage control, and intelligent operational scheduling relevant to long-term profitability. Together, these factors mean that market participants cannot evaluate ESP investments purely on collection efficiency metrics; they must incorporate compliance risk reduction, maintenance exposure, energy intensity, and the potential for modular or phased deployment.
The report integrates these structural drivers into a cohesive analytical narrative, linking regulatory timelines, material and energy cost realities, and technology evolution paths to demand behavior across major application clusters. Rather than treating compliance as a static checkbox, the analysis frames ESP adoption as an ongoing capital and operational decision influenced by enforcement cadence, plant age profiles, fuel mix transitions, and the economics of retrofitting existing units versus installing new systems.
Inside the Report: Operational Content for Executive Action
This study is structured to support practical decisions rather than abstract market commentary. It provides a comprehensive map of the ESP market across technology configurations, application environments, and regional deployment patterns, with historical data and forward forecasts embedded in a consistent analytical framework. The report details revenue progression, growth drivers, constraint factors, and the interplay between regulatory mandates and operational economics, giving readers a clear view of where demand is expanding, where replacement cycles are intensifying, and where competitive competition is concentrating.
Beyond macro trajectory, the publication delivers actionable supplier intelligence. It profiles leading manufacturers and specialized OEMs, outlines their application focus, recent contract and expansion activity, and the strategic implications of their market moves. This competitive mapping is paired with an assessment of market concentration dynamics, enabling readers to understand where scale advantages matter most and where niche or application-specific suppliers can create differentiated value. The report also incorporates sector-level considerations such as material selection pressures, digital control adoption, energy consumption profiles, and compliance-driven procurement behavior, providing context that procurement, engineering, and strategy teams can apply directly to sourcing and investment planning.
Importantly, the full study is designed to be modular in use. Executives can extract high-level growth signals and strategic implications for board-level planning; procurement and engineering teams can drill into supplier capabilities and application fit; and investors or corporate development teams can assess concentration patterns, regional momentum, and the types of commercial activity—such as rebuild contracts, service network expansion, and integrated system deliveries—that signal where value is being captured in the value chain.
How to Use This Intelligence for 2026 Strategy and Sourcing
For organizations planning capital expenditures, compliance upgrades, or vendor evaluations in 2026, the strategic value of this research lies in its ability to convert market signals into operational choices. The growth path, competitive structure, and regulatory context described in the report provide a basis for timing retrofit and replacement programs, evaluating whether to prioritize efficiency upgrades or capacity additions, and selecting suppliers whose installed-base experience and service reach align with specific application requirements. The inclusion of recent contract awards, network expansions, and project deliveries offers tangible reference points for assessing supplier momentum and execution capability.
Electrostatic Precipitators (ESP) Market
At the same time, the most precise segmentation data, regional deployment splits, and application-level revenue breakdowns are reserved within the complete research package. This intentional structure ensures that the full strategic picture—including the detailed allocation of demand across technology types, end-use sectors, and geographies—is available to decision-makers who require resolution fine enough to guide licensing, sourcing, and investment commitments.
Final Perspective
The ESP market entering 2026 is defined by sustained demand growth, a moderately concentrated competitive field, and a regulatory and operational environment that rewards integrated, high-efficiency, and service-supported solutions. Our research translates these conditions into a forward-looking, decision-oriented framework that supports compliance planning, capital allocation, supplier evaluation, and long-range technology strategy. For leaders who need more than headline growth figures—who require supplier-level insight, structural driver analysis, and a forecast architecture aligned with real procurement and investment cycles—this report offers the depth and commercial relevance necessary to act with confidence. Access to the complete segmentation detail and full competitive intelligence is available through the full study, where the complete dataset and methodology can be reviewed in context.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trehalose Market to Reach $275M by 2032, Growing at 5.45% CAGR
By pmarketresearch, 2026-09-15
### Strategic Trajectory of the Global Trehalose Market: Navigating Value Creation Opportunities Through 2032
Executive Perspective
In an era where ingredient functionality directly dictates product shelf-life, consumer acceptance, and formulation economics, few compounds offer the multifunctional promise of trehalose. As a non-reducing disaccharide celebrated for its moisture-retention capabilities, thermal stability, and ability to preserve structural integrity in proteins and cellular matrices, trehalose has transitioned from a specialized biochemical reagent to a cornerstone ingredient across food, nutraceutical, pharmaceutical, and cosmetic supply chains. Our latest comprehensive market intelligence report dissects this evolution with meticulous granularity, positioning procurement leaders, R&D directors, and corporate strategists to make informed capital allocations and portfolio adjustments for the 2026 horizon and beyond.
The global trehalose market has demonstrated resilient expansion over the past half-decade, climbing from a baseline valuation of 130.0 million USD in 2020 to an estimated 190.85 million USD in 2025. This trajectory reflects sustained demand pull from clean-label formulation shifts, heightened investment in biologic stabilization technologies, and the gradual commercialization of trehalose-enabled cosmetic actives. Our forecast window extends through 2032, projecting the market to reach 275.0 million USD. This expansion translates to a compound annual growth rate of 5.45 percent, a figure that underscores steady, non-speculative growth rather than erratic hype cycles. For decision-makers, this CAGR is not merely a top-line metric; it signals a mature yet still structurally expanding addressable market where early positioning, supply chain resilience, and application-specific differentiation can yield disproportionate returns.
Market Architecture and Growth Drivers
Historical Resilience and Forecast Trajectory
The historical record from 2020 through 2025 reveals a market that navigated pandemic-era logistics disruptions, raw material volatility, and shifting regulatory frameworks without losing momentum. The year-over-year progression from 146.74 million USD in 2021 to 159.09 million USD in 2022, then to 172.06 million USD in 2023, illustrates incremental but compounding demand. By 2024, the market reached 176.61 million USD, and the acceleration into 2025 at 190.85 million USD suggests that trehalose has embedded itself deeply into industrial workflows. Looking ahead, the forecast period paints a picture of sustained scaling: 204.22 million USD in 2026, 218.92 million USD in 2027, a slight recalibration to 216.8 million USD in 2028 reflecting expected short-term supply chain rebalances, and then renewed expansion toward 235.33 million USD in 2029, 243.67 million USD in 2030, 260.96 million USD in 2031, and finally 275.0 million USD in 2032. This trajectory signals that trehalose demand is not cyclical but structurally anchored in multiple end-use verticals.
Structural Segmentation Dynamics
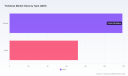
Our report deconstructs the market into three primary segmentation dimensions: product formulation type, end-use application, and regional distribution. In the type dimension, the landscape is divided between powdered and liquid trehalose formats, each serving distinct handling, dosing, and formulation requirements. Powdered trehalose commands a larger absolute share, reflecting its versatility in bulk industrial processing, dry blend applications, and extended shelf-life storage. Liquid trehalose, meanwhile, addresses continuous-process manufacturing environments and specific beverage or liquid formulation workflows where dissolution speed and dosing precision are paramount. Both formats are expanding, but their relative attractiveness varies sharply by vertical and by regional manufacturing infrastructure.
Trehalose Market
D-Mannose Market
In the application dimension, food and beverage applications represent the largest consumption pool, driven by trehalose's function as a mild sweetener, texture modifier, and moisture stabilizer in baked goods, confectionery, and frozen desserts. Dietary supplements and nutraceuticals constitute a meaningful secondary stream, leveraging trehalose's reputation for cellular protection and metabolic neutrality. The pharmaceutical sector represents a high-value, high-specification niche where trehalose dihydrate serves as a critical cryoprotectant, lyoprotectant, and formulation stabilizer for biologics, vaccines, and cell therapies. Cosmetics and personal care applications, while smaller in absolute volume, are expanding rapidly as formulators seek naturally derived humectants and skin-barrier-supporting sugars with clean-label profiles. A residual others category captures specialized industrial and research uses that, while niche, often command premium pricing and technical service requirements.
Regionally, the market exhibits a multi-polar distribution. North America maintains a leading position, supported by advanced pharmaceutical development pipelines, well-established food ingredient distribution networks, and strong consumer demand for functional and clean-label products. Europe follows as a substantial market, shaped by stringent quality expectations, a robust cosmetics and personal care ecosystem, and growing pharmaceutical biomanufacturing activity. Asia Pacific represents a high-growth engine, where expanding food processing capacity, rising healthcare expenditure, and localized manufacturing investments are driving both volume growth and supplier diversification. Latin America and the Middle East and Africa collectively represent smaller but strategically emerging footprints, where import dependencies, regulatory evolution, and infrastructure development create both challenges and first-mover opportunities. The precise regional value distribution, application-level breakdowns, and type-specific volume allocations are mapped in exhaustive detail within the full report, enabling granular scenario modeling that goes far beyond aggregate market sizing.
Competitive Landscape and Strategic Positioning
The trehalose market is characterized by a moderately concentrated supplier base, with the top three players accounting for approximately 45 percent of total market revenue and the top five collectively commanding around 65 percent. This concentration reflects the technical barriers associated with high-purity production, enzymatic process optimization, and, in the pharmaceutical grade segment, compliance with pharmacopoeial standards and low-endotoxin specifications. Yet the remaining market share is distributed among a diverse set of regional and application-focused suppliers, creating a landscape where competitive advantage is increasingly defined by application engineering, regulatory readiness, and supply reliability rather than volume alone.
Nagase & Co., Ltd., headquartered in Tokyo, Japan, exemplifies the high-purity, application-engineered approach. Through its TREHA® brand, the company manufactures high-purity trehalose via a proprietary enzymatic process derived from starch, supplying food and beverage ingredient channels with a product designed for clean-label, texture-preserving, and flavor-modulating formulations. Nagase's positioning emphasizes technical service, regulatory documentation, and consistent quality, aligning with customers who prioritize formulation predictability and label credibility.
Shandong Fuyang Biotechnology Co., Ltd., based in Pingyuan, Shandong, China, operates within the corn deep-processing ecosystem and produces food-grade trehalose as part of a broader carbohydrate ingredient portfolio. Its export-oriented model reflects the growing integration of Asian starch-derived ingredient manufacturing into global supply chains. Meihua Holdings Group Co., Ltd., located in Langfang, Hebei, China, similarly leverages its scale and integrated processing capabilities to supply trehalose as a colloidal polysaccharide ingredient, emphasizing freshness preservation and product quality enhancement in food applications. Meihua's commitment to environmental management, evidenced by full ISO 14001 certification coverage, signals an ESG-aware supplier profile that increasingly matters to multinational procurement teams.
On the Western side, Cargill, Incorporated, headquartered in Minneapolis, USA, distributes and supplies food-grade trehalose dihydrate tailored for bakery, confectionery, and clean-label applications. Cargill's strength lies in its global distribution reach, formulation expertise, and ability to embed trehalose within broader sweetener and functional ingredient portfolios. Pfanstiehl, based in Waukegan, Illinois, USA, occupies a distinct high-value niche by manufacturing USP-NF, EP, JP, and ChP-grade high-purity, low-endotoxin trehalose dihydrate for biopharmaceutical stabilization and cryopreservation. Pfanstiehl's compliance with multiple pharmacopoeial standards and its focus on endotoxin control make it a critical partner for biotechnology and pharmaceutical customers where quality specifications are non-negotiable and batch consistency directly impacts product viability.
Additional suppliers such as Shandong Deshang Chemical Co., Ltd. and Changyi Longchang Bio-Chemical Co., Ltd., both operating from the Shandong region of China, contribute to a vibrant competitive ecology. Shandong Deshang remains an active supplier of trehalose for food applications, while Changyi Longchang manufactures trehalose as a core product for food and ingredient markets. The presence of multiple capable Chinese producers underscores the region's importance as both a manufacturing hub and a competitive pressure point on pricing and supply agility. The full report provides detailed corporate profiles, competitive positioning assessments, and strategic implication analyses for each key player, enabling clients to benchmark their own supplier relationships and identify potential partnership or substitution opportunities.
Regulatory and Industry Dynamics Shaping the Road Ahead
Trehalose's commercial expansion is being reinforced by a series of regulatory clarifications and industry-level developments that reduce uncertainty and broaden addressable use cases. Health Canada has formally notified Hayashibara International Inc. and Cargill, Inc. that it has no objection to the use of trehalose for human food applications, a determination that removes a potential barrier for Canadian market access and reinforces international regulatory alignment. Simultaneously, the pharmacopoeial landscape has consolidated around trehalose's role in high-specification pharmaceutical use. Pfanstiehl's trehalose is available in USP-NF, EP, and JP grades, reflecting the multi-jurisdictional compliance requirements of global biopharmaceutical supply chains. In parallel, Nagase Viita Co., Ltd., operating as Nagase Food Ingredients, continues to manufacture TREHA® via its proprietary enzymatic starch-conversion process, underscoring the importance of process innovation in maintaining quality consistency and cost efficiency.
Regulatory dynamics are not static, and procurement strategies must account for evolving food additive classifications, novel food notifications, and pharmacopoeial updates. Our report embeds these regulatory trajectories within the broader market dynamics section, illustrating how compliance pathways can create entry barriers, expand addressable markets, or shift competitive advantage among suppliers with differing certification portfolios.
Operational Content and Decision-Support Architecture
This market research report is designed as a decision-support instrument rather than a static data compilation. It integrates macroeconomic context, segmentation analysis, competitive profiling, and regulatory intelligence into a coherent narrative that supports actionable planning. The report content includes detailed volume and value analysis across the forecast horizon, decomposed by type, application, and region. It provides market concentration metrics and supplier share assessments that help clients evaluate bargaining power, supply risk, and partnership potential. It maps historical growth patterns against projected trajectories, enabling sensitivity analysis around demand shocks, raw material cost fluctuations, and regulatory changes.
The operational scope extends to application-specific usage patterns, formulation advantages, and technical requirements that distinguish one end-use vertical from another. For food and beverage teams, the report examines how trehalose functions as a moisture regulator, texture stabilizer, and flavor modulator, and where it can replace or complement existing ingredients without triggering label or cost penalties. For dietary supplement and nutraceutical strategists, the focus shifts to metabolic neutrality, stability in dry and liquid formats, and alignment with consumer-facing wellness narratives. For pharmaceutical and biotech decision-makers, the report addresses grade requirements, endotoxin control, cryopreservation performance, and the implications of pharmacopoeial compliance for supply chain qualification. For cosmetics and personal care developers, the analysis highlights humectant behavior, skin-barrier compatibility, and clean-label positioning in an increasingly crowded functional sugar landscape.
Beyond segmentation and application analysis, the report provides a structured view of market drivers, restraints, opportunities, and challenges. It evaluates the interplay between raw material availability, process technology maturity, regulatory clearance timelines, and end-market demand elasticity. It maps historical resilience against forward-looking risk factors, allowing procurement and strategy teams to stress-test their assumptions. All regional and application-level percentage splits, specific revenue figures by sub-segment, and granular supplier-level volume estimates are disclosed in full within the complete report. This deliberate depth ensures that clients can run their own scenario models, calibrate procurement timing, and identify the exact sub-markets where investment, reformulation, or supply diversification will generate the greatest incremental value.
Strategic Implications for 2026 and Beyond
For enterprise decision-makers, the trehalose market presents a rare combination of steady macro growth and segmented opportunity pockets. The overall 5.45 percent CAGR through 2032 signals that the market is expanding in a predictable, structurally supported manner, but predictability should not be mistaken for uniformity. The largest absolute opportunity resides in the food and beverage vertical, where trehalose's functional attributes align with clean-label reformulation, texture optimization, and shelf-life extension. The highest specification and margin potential resides in pharmaceutical and biopharmaceutical applications, where grade compliance, low-endotoxin performance, and batch reproducibility justify premium pricing and long-term supply agreements. The cosmetics and personal care segment offers a high-growth adjacency where trehalose's humectant and barrier-supporting properties can be leveraged in premium skincare, barrier repair formulations, and naturally derived ingredient narratives. Dietary supplements and nutraceuticals add a further layer of opportunity, particularly where trehalose can be positioned around cellular protection, stability, and metabolic benignity.
Regional strategy will be equally important. The leading regional markets each present distinct procurement profiles, regulatory frameworks, and supplier ecosystems. North American and European customers benefit from established distribution infrastructures and deep technical service capabilities among global suppliers, but they also face pricing and margin pressures from efficient Asian manufacturers. Asian Pacific markets offer volume growth and localized supply options, but they require careful navigation of quality assurance, export logistics, and application-specific technical support. Latin America and the Middle East and Africa, while smaller in current scale, are relevant for companies seeking geographic diversification, import substitution, or early entry into developing food and pharmaceutical manufacturing corridors. The complete report quantifies these regional dynamics and provides the sub-segment breakdowns necessary to prioritize investments by geography and application.
Competitive strategy should also account for the moderately concentrated supplier base. The top three and top five players hold significant revenue share, but the presence of multiple capable regional producers creates both collaboration and negotiation leverage. Procurement teams can use the market concentration data to assess supply security, benchmark pricing, and evaluate whether dual-sourcing or specification-tailored supplier portfolios are warranted. R&D and formulation teams can use the application and type segmentation to identify where powdered versus liquid formats are most cost-effective and where supplier technical documentation and regulatory support will accelerate time-to-market. Executive teams can use the forward-looking forecast to align capital expenditure, capacity planning, and partnership discussions with a market that is expanding but not inflating, allowing disciplined, evidence-based growth strategies.
Call to Strategic Engagement
The trehalose market is at an inflection point where functional necessity, regulatory clarity, and supplier maturity are converging to create durable growth across multiple verticals. Yet the precise magnitude of opportunity in each sub-segment, the exact regional value distribution, and the detailed supplier-level share allocations remain strategically sensitive information that can differentiate early movers from late followers. Our full market research report is built to provide that intelligence with analytical rigor, commercial relevance, and actionable structure.
This article has outlined the macro trajectory, segmentation logic, competitive architecture, and regulatory context that define the market's current shape and forward path. The complete report goes further, delivering the exact segmentation percentages, regional revenue breakdowns, application-level consumption splits, and detailed competitive profiles that enable precise procurement timing, portfolio prioritization, and risk calibration. For organizations that need to make 2026 sourcing decisions, evaluate reformulation options, assess supplier partnerships, or build long-range demand models through 2032, this research provides the evidentiary foundation required to move from assumption to confidence. We invite strategic leaders to access the complete report to unlock the full depth of market intelligence and translate structural growth into measurable commercial advantage.
For detailed analysis of this topic, please visit the official page: Trehalose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Viscose Filament Yarn Market Reaches $2.89B in 2025, Projected 5.5% CAGR to 2032
By pmarketresearch, 2026-09-15
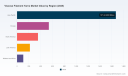
Strategic Intelligence for the Next Decade: Unlocking the Viscose Filament Yarns Market Opportunity
The global textile and industrial materials landscape is undergoing a structural transformation. As sustainability mandates tighten, supply chains reconfigure, and performance expectations rise, Viscose Filament Yarns (VFY) have emerged as a critical intermediary between traditional cellulosic manufacturing and next-generation sustainable textiles. For executives, procurement leaders, and strategic planners, understanding where this market is headed is no longer optional; it is a prerequisite for capital allocation, product positioning, and regional expansion.
PW Consulting’s latest deep-dive research on the Viscose Filament Yarns Market is designed to convert macroeconomic complexity into actionable decision architecture. Drawing on a rigorous historical baseline spanning 2020 through 2025 and projecting forward through 2032, this report offers a multi-dimensional view of value creation, competitive pressure points, and regulatory inflection moments that will define the industry over the next seven years.
The market’s trajectory signals a steady expansion path. From a global revenue baseline of approximately 2.27 billion USD in 2020, the sector has advanced through consistent year-over-year growth, reaching an estimated 2.89 billion USD in 2025. The forward-looking forecast places the market on a measured 5.5 percent compound annual growth rate trajectory, with valuations expected to surpass 3.0 billion USD in 2026 and continue a sustained upward curve toward the early 2030s. These figures are not merely historical artifacts; they encode the underlying demand resilience of textile applications, the gradual diversification into medical and industrial end-uses, and the persistent influence of regional manufacturing gravity. More importantly, they establish the scale at which competitive advantage must now be engineered.
For business leaders operating in or adjacent to this market, the strategic question is no longer whether the category will grow, but how to position within a landscape where feedstock volatility, certification expectations, trade policy shifts, and product differentiation intersect simultaneously. This research was built to answer precisely that question.
Viscose Fiber Market
Why This Research Matters for 2026 Decision-Making
The year 2026 represents a pivotal planning horizon. Companies are finalizing capacity commitments, renegotiating supplier frameworks, and aligning product roadmaps with incoming regulatory and sustainability requirements. In this environment, decision-makers need more than aggregated market size numbers. They need a structured view of how demand is distributed across end-use verticals, how regional manufacturing footprints influence pricing and supply security, and how type-level product segmentation reflects commercial priorities such as luster, dyeability, and downstream processing compatibility.
This report is engineered to support that level of operational reasoning. Rather than presenting a single-line growth narrative, the analysis connects market size evolution with the underlying structural drivers that will determine which participants capture margin resilience and which face squeeze. Readers will find a carefully designed framework for interpreting where volume concentrates, where value differentiation is emerging, and where external shocks—whether raw material price swings or trade remedy actions—can reshape short-term profitability.
Equally important, the research is designed to support cross-functional alignment. Strategy teams can use the forecast architecture to test expansion assumptions. Commercial teams can use the segmentation logic to refine positioning against competing fiber categories. Sustainability and compliance teams can use the regulatory and certification discussion to identify where traceability and certification are moving from differentiator to requirement. By integrating these lenses into one coherent intelligence package, the report reduces the risk of siloed decision-making.
Inside the Report: What the Analysis Delivers
A market study earns its value through practical utility. This report is structured to give executives a working map of the Viscose Filament Yarns landscape, not just a static description of it. The analytical content is built to support scenario planning, competitive benchmarking, and entry-or-retreat decisions across multiple dimensions.
At the core of the report is a historically grounded forecast model that traces how the market has moved from its 2020 base through the most recent baseline year and into the projection window extending to 2032. This temporal structure allows readers to evaluate whether recent growth patterns reflect cyclical recovery, structural demand shifts, or region-specific manufacturing expansion. The forecast framework is presented in a way that supports sensitivity reasoning, enabling users to test how changes in feedstock cost, demand elasticity, or trade conditions could alter outcomes.
The segmentation architecture is deliberately designed to illuminate commercial reality. Readers will examine how the market divides by geography, revealing where production concentration, demand pull, and supply chain thickness shape regional competitiveness. The report also breaks down the category by product type, distinguishing between bright and dull viscose filament yarns and explaining how these variants map to different textile finishing requirements, end-market preferences, and price-performance trade-offs. In parallel, the application view provides a structured reading of where demand is anchored, with textiles representing the dominant anchor of market volume and medical, industrial, and other end-uses contributing more specialized, often higher-value demand streams.
Beyond segmentation, the report delivers operational content that leadership teams can use immediately. This includes a supplier and competitor landscape that maps out the strategic posture of key manufacturing players, an assessment of capacity and product range dynamics, and a review of recent launches, facility expansions, and production upgrades that signal where the industry is placing its bets. The study also addresses raw material exposure, particularly the role of dissolving wood pulp and other cellulosic inputs in shaping production economics. Where relevant, pricing movement and feedstock shifts are discussed as leading indicators rather than isolated events, helping readers anticipate cost pressure before it reaches the bottom line.
To support execution, the research also examines the regulatory and standards environment shaping procurement and product design. From sustainability claim verification to trade remedy investigations and regional policy direction, the report connects compliance pressure with commercial consequence. This is especially important for organizations that source across borders or plan to position certified, traceable, or recycled-content yarns as part of their differentiation strategy.
Competitive Landscape: Who Is Shaping the Market
The Viscose Filament Yarns market is defined by a concentrated yet strategically diverse competitive field. Market leadership is not uniform; it varies by region, product range, sustainability positioning, and integration depth across the cellulosic value chain. Understanding these differences is essential for evaluating supplier risk, partnership opportunities, and competitive threats.
Several large-scale producers anchor the industry. In India, Grasim Industries Limited stands out as a major viscose filament yarn manufacturer with broad denier coverage and a developing emphasis on traceable, sustainably sourced product lines. Its recent introduction of a sustainable traceable variant under its established brand family reflects a wider industry push toward verifiable sourcing and differentiated product storytelling. Across China, the competitive picture is equally significant, with multiple integrated players operating at substantial scale. Jilin Chemical Fiber Co., Ltd. represents a producer focused on expandingNext-generation grades with certified wood feedstocks and recycled cotton content, signaling that sustainability-related input strategies are increasingly becoming part of core production planning rather than peripheral branding.
Xinxiang Bailu Chemical Fiber Co., Ltd. contributes to the Chinese manufacturing base with a diversified viscose product set spanning filament, embroidery, and dyeing yarns. Yibin Grace Group Co., Ltd. has pushed further into recycled-content positioning, supported by dedicated capacity and the establishment of a recycled textile dissolving pulp facility, an infrastructure move that points to longer-term feedstock independence and circularity ambitions. Sinopec Yizheng Chemical Fibre Co., Ltd. reflects the advantage of integration within a larger state-linked industrial complex, where filament production is tied to broader dissolving pulp and chemical fiber operations. Sateri Holdings Limited operates at exceptional scale within the broader viscose fiber ecosystem and uses that scale to support filament offerings alongside staple and lyocell products, with a strong international footprint and certification-aligned supply chain.
At the premium and sustainability-led end of the spectrum, Lenzing AG remains a defining reference point for closed-loop, wood-based filament and related cellulosic yarns, particularly where high-luster, biodegradable, and performance-oriented characteristics matter. The presence of such players underscores a broader competitive dynamic: the market is not simply competing on volume, but on fiber quality, environmental credentials, processing efficiency, and downstream compatibility.
Viscose Filament Yarns Market
This competitive diversity creates both opportunity and risk. Buyers can leverage supplier variety to negotiate terms, secure supply, and access differentiated product attributes. Producers, in turn, must defend position through capacity reliability, feedstock strategy, product breadth, and increasingly, verifiable sustainability performance. The report maps these dynamics in detail so that readers can judge where consolidation pressure may intensify, where niche leadership can be defended, and where new entrants or expansions may alter regional balance.
Market Dynamics: Feedstock, Regulation, and Trade Pressures
No forecast exists in a vacuum. The Viscose Filament Yarns market is sensitive to a set of external forces that can amplify or dampen growth outcomes over the forecast period. One of the most immediate is raw material economics. Dissolving wood pulp prices have shown periodic volatility, with quarter-over-quarter movement in key sourcing regions directly affecting production cost structures. When feedstock costs rise, pricing power, margin endurance, and contract timing become critical variables. The report treats these cost dynamics as integral to market interpretation rather than as background noise, helping readers understand how input fluctuations can propagate into pricing, regional competitiveness, and demand timing.
Regulatory and policy developments are shaping the market with equal force. Sustainability claim verification is moving from aspirational positioning toward enforceable expectation. The EU Green Deal textile strategy and related Green Claims Directive implementation are accelerating demand for credibly certified viscose filament yarns, especially those supported by FSC or PEFC-aligned sourcing. For manufacturers and buyers alike, certification is increasingly tied to market access, premium positioning, and reputational risk management. The report contextualizes these shifts so that organizations can separate near-term compliance burdens from longer-term strategic requirements.
Trade policy adds another layer of complexity. Anti-dumping investigations and duty recommendations targeting viscose rayon filament yarn imports have emerged in key markets, including actions involving India and Chinese-origin supply. Where such measures progress toward formal duties, they can alter sourcing patterns, change relative price relationships, and affect the competitiveness of cross-border supply chains. These developments are particularly relevant for companies that rely on imported filament or operate in regions where trade remedy outcomes may shift the balance between domestic and overseas supply.
Finally, price movements in the Asian market illustrate how quickly regional conditions can shift. Recent pricing surges tied to cellulose feedstock volatility demonstrate that regional price signals can diverge from global averages and create short-term windows of advantage or disadvantage. By integrating these dynamics into the broader market narrative, the report gives readers a more realistic foundation for planning than a simple demand-growth storyline would provide.
How to Use This Research for Strategic Advantage
The strongest market research does not simply describe the past; it sharpens the next decision cycle. This report is intended to support a range of strategic actions. For organizations evaluating capacity expansion or product line extension, the segmentation and forecast structure provides a basis for testing where demand depth justifies investment. For procurement and sourcing teams, the regional and competitor analysis supports supplier diversification, contract strategy, and exposure management in environments where feedstock and trade conditions can change quickly.
For commercial leaders, the bright versus dull product distinction and the application mix offer a framework for aligning product attributes with customer priorities, whether those priorities center on aesthetics, dye behavior, processing efficiency, or end-use performance. For sustainability and compliance functions, the regulatory discussion helps prioritize certification pathways, traceability investments, and claims substantiation in markets where verifiable sustainability is becoming a condition of participation rather than a voluntary advantage.
Most importantly, the report supports integrated decision-making. Growth potential, competitive intensity, feedstock exposure, and regulatory direction are rarely independent. This research connects them so that executives can evaluate trade-offs more clearly, challenge internal assumptions more effectively, and align strategy across functions with a shared view of the market’s direction.
Conclusion
The Viscose Filament Yarns Market is entering a period in which scale, sustainability, and supply-chain resilience must be managed together. Historical growth has established a meaningful base, and the forward forecast points to continued expansion through the end of the decade and into the early 2030s. Yet the real strategic challenge lies beneath the headline trajectory: understanding where demand is concentrated, how competitors are positioning themselves, how feedstock and trade dynamics influence margin, and how sustainability requirements are reshaping procurement expectations.
PW Consulting’s full market research report provides the depth required to navigate that complexity. It combines historical context, forecast architecture, segmentation logic, competitive profiling, and market-dynamic analysis into a single decision-ready framework. For leaders who need to move beyond surface-level market sizing and toward targeted, evidence-based strategy, the complete study offers the intelligence necessary to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Viscose Filament Yarns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nuclear Valve Market Hits $2,143.69M in 2025, Projected 6.1% CAGR Through 2032
By pmarketresearch, 2026-09-15
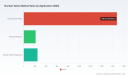
Strategic Imperatives in the Nuclear Valves Market: A 2026 Decision-Maker's Guide
The nuclear energy sector stands at a critical inflection point. As global decarbonization mandates intensify and energy security concerns reshape national strategies, the reliability of nuclear infrastructure has never been more pivotal. At the heart of this infrastructure lies a specialized, high-stakes component market: nuclear valves. These engineered systems are not merely ancillary equipment; they are the guardians of containment, pressure regulation, and safety protocols within some of the world's most hazardous environments. For executives navigating capital allocation, supply chain resilience, and technology roadmaps, understanding the trajectory of the nuclear valves market is essential.
This article serves as a strategic preview of PW Consulting's latest comprehensive market intelligence product. It outlines the macro-economic currents driving the sector, highlights the competitive architecture defining the landscape, and explains why access to granular, forward-looking data is indispensable for outperforming in 2026. By synthesizing historical performance with projected growth vectors, we provide a foundation for decisions that will define operational success over the next half-decade.
The Macro Landscape: Growth, Scale, and Trajectory
The nuclear valves market has demonstrated consistent resilience and expansion over the past five years. Drawing from our analysis of historical data spanning 2020 through 2025, the market has evolved from a base valuation of 1.60 billion USD in 2020 to an estimated 2.14 billion USD in 2025. This represents a compound annual growth trajectory that underscores the sector's steady maturation and the sustained investment in nuclear capacity worldwide.
Nuclear Valves Market
Looking ahead, our forecast model projects the market to reach 2.23 billion USD in 2026, continuing a growth arc that extends through 2032. By the end of the forecast period, the market is anticipated to approach 3.25 billion USD. This expansion is underpinned by a forecast-period CAGR of 6.1 percent, a figure that signals robust demand driven by reactor restarts, new-build programs, and the modernization of aging facilities. The growth is not merely nominal; it reflects deepening complexity in valve specifications, stricter regulatory compliance requirements, and the integration of advanced materials and digital monitoring systems.
While the headline figures paint a picture of steady expansion, the underlying dynamics are nuanced. Value creation is increasingly concentrated within specific engineering niches, where differentiation stems from certifications, heritage in safety-critical applications, and the ability to support both legacy reactors and emerging technologies like small modular reactors (SMRs). The market's structure, characterized by a consolidated landscape where the top three players command significant share and the top five entities control a substantial majority of revenue, suggests that competitive advantages are deeply entrenched. This concentration implies that new entrants face high barriers, while incumbents leverage long-term utility relationships and certified manufacturing capabilities to maintain pricing power and customer stickiness.
Unpacking the Forecast: Beyond Aggregate Numbers
A superficial glance at the market trajectory might suggest a uniform growth environment. However, the strategic reality is far more segmented. The distribution of value across valve types reveals distinct engineering priorities. Gate valves and globe valves continue to dominate the revenue mix, reflecting their foundational roles in isolation, throttling, and high-integrity containment within nuclear circuits. Ball valves and butterfly valves occupy significant positions, particularly in applications demanding rapid actuation and lower flow resistance profiles. Check valves, diaphragm valves, and other specialized types round out a diversified portfolio that responds to the heterogeneous needs of nuclear facilities.
The application domain further stratifies the market. Nuclear power plants remain the primary revenue engine, absorbing the lion's share of demand as operators focus on reliability, life extension, and compliance with evolving safety codes. Yet, adjacent segments are gaining traction. Research reactors and nuclear waste management applications represent specialized, high-value niches where valve performance criteria diverge sharply from commercial power settings. Waste management, in particular, introduces unique challenges around radiation resistance, long-term sealing integrity, and material degradation, driving demand for purpose-built solutions that command premium positioning.
Geographically, the market's footprint is broad but uneven. Asia Pacific has emerged as a region of considerable scale, reflecting the aggressive nuclear expansion programs in several key economies. North America and Europe continue to represent mature, high-compliance environments where valve procurement is heavily influenced by regulatory frameworks, long-term service agreements, and the need for certified domestic or allied supply chains. Latin America and the Middle East and Africa, while smaller in absolute terms, are regions where infrastructure development and energy diversification initiatives are creating incremental opportunities for qualified suppliers. Understanding how these regional dynamics interact with local content requirements, sanctions regimes, and technology transfer restrictions is essential for firms planning cross-border strategies.
Competitive Architecture: The Incumbents and the New Dynamics
The competitive landscape of the nuclear valves market is defined by a cadre of firms that have invested decades in building technical credibility, regulatory certifications, and deep relationships with utility operators. These companies do not compete solely on price; they compete on audit-ready documentation, code compliance, heritage in specific reactor types, and the ability to deliver integrated valve-actuator packages with full lifecycle support.
Crane Nuclear, headquartered in Kennesaw, Georgia, exemplifies long-standing heritage in the sector. Since 1956, the firm has specialized in manufacturing nuclear-grade gate, globe, check, and quarter-turn valves bearing ASME N and NPT stamps for Class 1, 2, and 3 applications. Its historical footprint includes supplying valves for the first commercial nuclear power plant at Shippingport, and its ongoing diagnostics and services offerings reinforce its position as a trusted partner for commercial nuclear power plants. This legacy translates into a competitive moat built on decades of operational data, regulatory familiarity, and customer trust.
Neway Valve, based in Suzhou, Jiangsu, China, represents the growing capability of Asian manufacturers to meet rigorous international standards. The company produces nuclear gate, ball, globe, check, and butterfly valves qualified to NNSA Grade 1, 2, and 3 design and manufacturing licenses, alongside full ASME N and NPT certificates. Its portfolio is tailored for EPR, AP1000, and Hualong-1 reactors, positioning it as a supplier capable of supporting both established and next-generation reactor designs with full-range nuclear compliance. This dual certification footprint allows Neway to serve markets that demand both domestic regulatory approval and internationally recognized code compliance.
Trillium Flow Technologies, located in Huddersfield, United Kingdom, brings a focused engineering approach to nuclear valves and actuators. The company designs and manufactures engineered nuclear valves and actuators with ASME Section III N and NPT stamps, including safety relief and specialty valves for new-build and operating reactors worldwide. Its active ASME Section III N and NPT stamps at two production sites underscore a commitment to redundancy and supply chain resilience, qualities that are increasingly valued by operators seeking to mitigate single-source vulnerabilities.
Velan Inc., headquartered in Montreal, Quebec, Canada, has carved out a distinctive role in the nuclear space. The company produces nuclear Class 1, 2, and 3 gate, globe, check, and ball valves under ASME N and NPT certificates, and has expanded its relevance into the SMR domain, including projects such as the BWRX-300. Notably, Velan secured the first ASME N stamp for nuclear valves in 1971, and it remains the only manufacturer supplying nuclear valves to the first U.S. small modular reactor project. In October 2025, Velan secured a main services agreement for valves on North America's first small modular reactor project, marking a milestone in the commercialization of SMR valve supply chains.
Flowserve Corporation, based in Irving, Texas, USA, operates at the intersection of pumps, valves, and seals for nuclear applications. Its supply of nuclear-qualified equipment across Class 1-3 applications for global nuclear projects is supported by long-term utility relationships and ongoing SMR qualification programs. Flowserve's breadth of portfolio and established service networks make it a versatile partner for operators seeking integrated fluid control solutions.
Framatome, headquartered in Paris, France, leverages its broader reactor systems expertise to deliver safety-related nuclear valves and actuators. Through subsidiaries including Valserve, Framatome designs and manufactures components for PWRs, BWRs, and advanced reactors under ASME III, RCC-M, and other codes. In April 2025, Framatome completed the acquisition of Trillium Flow Technologies France, rebranding it as Sebim to strengthen its nuclear valves product line. This move signals a strategic consolidation within the European supply base, aiming to bundle valve and actuator capabilities under a unified engineering umbrella. Concurrently, in April 2025, Bruce Power signed a 10-year alliance with Trillium Flow Technologies for nuclear valve supply and related services, illustrating how long-term partnerships are becoming a defining feature of the market's procurement architecture.
Regulatory and Technical Dynamics Shaping Procurement
The nuclear valves market operates within a tightly regulated environment where certification is not a formality but a prerequisite for market access. ASME N and NPT stamps, along with national regulatory approvals such as NNSA grades, function as gatekeepers that separate qualified suppliers from the broader industrial valve market. Companies like Crane Nuclear, which has maintained ASME N and NPT stamps since its inception, and Neway Valve, which holds NNSA Grade 1, 2, and 3 licenses plus full ASME certifications, demonstrate how regulatory standing is intertwined with commercial viability. Trillium Flow Technologies' dual-site ASME Section III N and NPT stamp coverage further highlights how manufacturers are building geographic and operational redundancy to satisfy utility procurement requirements and risk management protocols.
These regulatory dynamics have direct implications for supply chain planning. Utilities and EPC contractors increasingly prioritize vendors that can demonstrate traceability, material certification, and code compliance at every stage of the valve lifecycle. The presence of ASME stamps, the ability to support Class 1, 2, and 3 applications, and the capacity to provide diagnostics and services are becoming differentiators that influence bid evaluation criteria. In this context, market participants that invest in certification maintenance, quality system upgrades, and digital documentation are better positioned to capture high-value contracts and sustain margins.
Why Granular Intelligence Matters for 2026 Decision-Making
While the macro trends and competitive profiles outlined here provide a strategic compass, they are insufficient on their own for operational planning. The nuances that drive procurement decisions, pricing negotiations, and technology adoption are embedded in the granular detail of the market. For example, understanding how the revenue split across valve types correlates with specific reactor programs, or how regional demand patterns align with local content mandates, requires access to segmented data that reveals the interplay between engineering specifications, regulatory environments, and commercial execution.
Valves Market
Similarly, the competitive dynamics are not static. Acquisitions, alliance formations, and certification expansions can shift market share, alter supply chain dependencies, and redefine the value proposition of incumbents overnight. The recent acquisition of Trillium Flow Technologies France by Framatome and the 10-year alliance between Bruce Power and Trillium Flow Technologies are indicative of a market where strategic bundling and long-term service commitments are reshaping competitive boundaries. Decision-makers need to know not just who the players are, but how their capabilities, geographic footprints, and partnership networks are evolving in real time.
This is precisely why PW Consulting's Nuclear Valves Market report is structured to deliver actionable intelligence beyond top-line forecasts. The report provides a deep dive into the segmentation landscape, competitive positioning, regulatory frameworks, and demand drivers that collectively inform capital allocation, vendor selection, and risk mitigation strategies. By mapping the revenue distribution across valve types, application domains, and regions, the report equips stakeholders with the context needed to identify growth pockets, anticipate supply constraints, and align product development with the most promising market vectors.
For executives planning 2026 initiatives, the report offers a structured framework to evaluate where to invest, whom to partner with, and how to navigate the certification and compliance pathways that gate market entry. Whether the objective is to expand into new reactor programs, secure long-term service agreements, or assess the impact of SMR commercialization on valve demand, the granular data and analytical rigor contained in the full report provide a reliable foundation for evidence-based decision-making.
Navigating Forward: From Insight to Action
The nuclear valves market is on a sustained growth trajectory, but growth alone does not guarantee strategic success. The firms that thrive will be those that translate market awareness into disciplined execution: investing in certified manufacturing capabilities, forging durable utility partnerships, adapting to the technical demands of advanced reactors and SMRs, and maintaining a vigilant eye on regulatory evolution. As the market approaches the 2026 horizon, the difference between reactive participation and proactive leadership will be determined by the quality of intelligence and the speed with which insights are operationalized.
PW Consulting's comprehensive research is designed to be that intelligence engine. By delivering a detailed, data-rich, and strategically oriented view of the nuclear valves market, the report enables stakeholders to cut through noise, focus on high-impact variables, and make decisions that compound value over the forecast period. The full analysis, including segmentation breakdowns, competitive assessments, and forward-looking scenarios, is available in the complete report. For those ready to move from strategic overview to precision planning, the next step is to access the full intelligence package and begin aligning 2026 agendas with the realities of a market in transformation.
For detailed analysis of this topic, please visit the official page: Nuclear Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com