

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Refrigerated Display Cases Market Hits $9.83 Billion in 2025, Projects 7.4% CAGR Through 2032

Strategic Intelligence in the Cold Chain: Navigating the Refrigerated Display Cases Market Outlook 2026–2032
Executive Summary: The Imperative for Data-Driven Decision Making
The global refrigeration landscape is undergoing a structural transformation driven by tightening environmental regulations, evolving consumer expectations for product visibility, and relentless pressure on operational energy costs. For stakeholders across retail, foodservice, and commercial refrigeration, the Refrigerated Display Cases Market represents a critical nexus of capital expenditure, compliance risk, and revenue generation. PW Consulting has synthesized a comprehensive market research study spanning the historical trajectory from 2020 through 2025 and projecting forward to 2032. This analysis delivers the strategic intelligence required to navigate the complexities of the 2026 market environment and beyond. The research is designed not merely as a static snapshot, but as a dynamic planning tool that equips executives, procurement leaders, and investors with the granular insights necessary to allocate capital efficiently and hedge against systemic volatility.
Macro Trajectory and Revenue Projections
Understanding the overarching revenue trajectory is the first step in framing strategic investments. Over the historical review period, the market demonstrated consistent expansion, rising from a baseline of 6,865.0 million USD in 2020 to 9,830.0 million USD by 2025. This upward momentum is projected to continue, with the market valuation expected to reach 10,331.18 million USD in 2026 and accelerate toward 16,140.0 million USD by the end of the forecast period in 2032. The analysis indicates a robust compound annual growth rate of 7.4 percent over the 2026 to 2032 forecast window. This macroeconomic expansion is underpinned by widespread modernization initiatives in grocery and convenience sectors, alongside mandatory upgrades triggered by regulatory shifts. However, aggregate figures only tell part of the story. The true strategic advantage lies in dissecting the velocity of growth across different technological architectures, application verticals, and geographic corridors, each of which presents distinct risk-return profiles for market participants.
Core Report Architecture and Actionable Intelligence
The complete research study is structured to provide end-to-end visibility into the market ecosystem, enabling stakeholders to build resilient business strategies. The report delivers a multi-dimensional analysis that moves beyond surface-level observations to uncover the operational and financial drivers shaping the industry. Key components include:
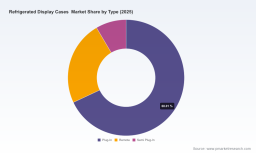
- Comprehensive profiling of market segmentation by product architecture, covering plug-in, remote, and semi-plug-in configurations, with detailed assessments of their respective adoption curves and total cost of ownership implications.
- Deep-dive evaluation of application verticals, examining how demand dynamics diverge between food service operations and retail food and beverage environments, including channel-specific purchasing behaviors and capacity utilization metrics.
- Regional market mapping that quantifies demand intensity, infrastructure readiness, and competitive saturation levels across major economic zones, providing a framework for prioritizing market entry or expansion initiatives.
- Supply chain and raw material analysis that tracks pricing volatility, component availability, and manufacturing constraints affecting critical inputs such as tempered glass, stainless steel, and aluminum, alongside mitigation strategies for procurement teams.
- Regulatory impact modeling that quantifies the financial and operational consequences of compliance mandates, including refrigerant charge limits, energy efficiency certification requirements, and phase-out timelines for legacy technologies.
- Competitive benchmarking and strategic grouping of market participants based on product portfolios, geographic footprints, innovation pipelines, and corporate development trajectories.
This structured approach ensures that decision-makers can align technology selection, capital deployment, and partnership strategies with the specific growth vectors and constraint boundaries that define the current market cycle.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment, with the top three participants collectively commanding approximately 48.0 percent of total revenue and the leading five firms accounting for 57.0 percent. This concentration reflects the high barriers to entry associated with engineering certification, distribution network development, and compliance with stringent energy and environmental standards. The competitive field features a mix of established multinational manufacturers and specialized regional players, each pursuing distinct value propositions to differentiate their offerings.
In North America, prominent players such as Hussmann Corporation from Chicago, Carrier Commercial Refrigeration based in Syracuse, Zero Zone Inc. from Madison, True Manufacturing Co. Inc. in Saint Augustine, Hillphoenix Inc. in Fort Worth, and Kysor Warren in Dallas maintain strong market positions through expansive product lines and direct service networks. Hussmann, for instance, has built its reputation on a comprehensive lineup of multi-deck, island, and reach-in merchandisers that integrate natural refrigerants, energy-efficient lighting, and customizable configurations tailored to retail and foodservice environments. Carrier Commercial Refrigeration emphasizes integrated store systems and display cases featuring both plug-in and remote solutions, with a strong focus on low-GWP refrigerants and smart control architectures that enable centralized monitoring and optimization. Zero Zone Inc. offers a suite of series including Crystal, Highlight, Guardian, and Reveal, alongside its Hybrid and ultra-narrow models engineered for energy efficiency and space optimization in constrained retail footprints. True Manufacturing Co. Inc. focuses on reach-in coolers, glass-door merchandisers, and display cases that prioritize durability, LED lighting integration, and energy performance across both foodservice and retail applications. Hillphoenix Inc. has positioned itself at the forefront of sustainable refrigeration with its AdvansorFlex CO2 and SoloChill series, which are optimized for energy efficiency, serviceability, and transcritical system performance. Kysor Warren contributes specialized refrigerated merchandisers engineered for durability, reliability, and labor savings in supermarket and retail settings.
European manufacturers bring distinct engineering philosophies and regulatory compliance expertise to the global market. Epta S.p.A., headquartered in Vimercate, Italy, delivers the Zenith and Costan lines of vertical and multi-deck refrigerated cabinets, achieving up to 36 percent energy savings through natural refrigerants and PFAS-free insulation, with EU Energy Class B certification. Arneg S.p.A., based in Bologna, emphasizes modular and plug-in refrigerated cabinets with a strong emphasis on sustainable refrigeration and custom store design solutions that adapt to varied retail formats. AHT Cooling Systems GmbH from Austria offers the BOREA and plug-in multideck refrigerated cases utilizing natural refrigerants such as R290, targeting retail outlets and convenience stores with compact, efficient configurations. In the Asia-Pacific region, Hoshizaki Corporation in Nagoya, Japan, provides reliable refrigerated display cases with a focus on convenience store and foodservice segments, emphasizing durability and energy performance. Frigoglass S.A.I.C., based in Athens, Greece, supplies glass-door coolers and refrigerated cabinets tailored for beverage and food display, supported by an international distribution network that extends its reach across multiple continents.
Refrigerated Display Cases Market
Recent Industry Movements and Innovation Signals
Recent corporate activities underscore the pace of technological advancement and the strategic importance of product innovation in capturing market share. In September 2025, Hussmann Corporation launched the RLN-A and RMN-A reach-in merchandisers, incorporating Air-Cooled Microblock technology designed to improve product temperature retention and enhance energy efficiency. This launch reflects a broader industry trend toward thermal management optimizations that directly impact both compliance standing and operating cost structures. In July 2025, Epta S.p.A. showcased the MD3 double-sided multideck cabinet at Metcash 2025, a configuration offering up to 30 percent floor space reduction for independent retail stores. Such space-saving innovations address the persistent challenge of maximizing merchandising density without compromising cooling performance or customer accessibility. In April 2025, Hillphoenix Inc. introduced ChargeSecure technology for CO2 refrigeration systems, delivering 1.5 amps operation and consuming six times less energy than conventional units. These developments highlight the competitive advantage accruing to manufacturers that can simultaneously address energy efficiency, refrigerant compliance, and operational reliability. Stakeholders who track these innovation cycles gain early visibility into emerging product standards and can align their procurement or development roadmaps accordingly.
Regulatory Pressures and Material Constraints Shaping Market Dynamics
The 2026 market environment is being reshaped by a confluence of regulatory mandates and material supply dynamics that demand proactive strategic adaptation. Starting January 1, 2026, new installations of Hybrid merchandisers are prohibited under the AIM Act, requiring replacement with low-GWP refrigerant alternatives. This regulatory shift, coupled with low-GWP refrigerant requirements under the AIM Act that limit refrigerant charge to 200 pounds for new installations, is driving accelerated adoption of R-290 and CO2 systems in display cases. These constraints are not merely compliance checkboxes; they fundamentally alter the economics of product selection, installation logistics, and long-term service contracts.
In parallel, EU Energy Class B certification mandates for vertical refrigerated cabinets are compelling manufacturers and end-users to prioritize high-efficiency designs. Epta's Zenith line, achieving up to 36 percent energy savings through natural refrigerants and PFAS-free insulation, exemplifies the performance benchmarks now required to meet these standards. On the materials front, glass doors dominate refrigerated display cases, with tempered safety glass capturing approximately 38.7 percent market share due to its optical clarity and hygiene compliance. Stainless steel and aluminum remain primary structural materials, and while component costs including steel, aluminum, and glass showed moderated price volatility in 2025, persistent supply chain risks continue to warrant careful inventory planning and supplier diversification. These regulatory and material factors interact to create a complex decision matrix where energy performance, compliance timelines, and input cost stability must be evaluated in concert.
Strategic Implications for 2026 and the Path Forward
The refrigerated display cases market in 2026 presents a landscape where growth is accessible but competition for share is intensifying, and where regulatory compliance is no longer a peripheral concern but a central pillar of product strategy. Organizations that succeed in this environment will be those that integrate macro demand signals with micro-level insights into product architectures, regional adoption patterns, and competitive maneuvering. The full study provides the detailed segmentation data, regional revenue breakdowns, application-specific growth rates, and competitor benchmarking matrices necessary to construct precise market entry strategies, optimize portfolio mixes, and anticipate regulatory-driven demand shifts. Readers seeking to unlock the complete dataset and proprietary analytical frameworks are encouraged to access the source research portal, where the full report delivers the granular intelligence required to inform capital allocation, technology roadmapping, and long-term competitive positioning.
Worldwide Home Display Case Market
For detailed analysis of this topic, please visit the official page: Refrigerated Display Cases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com