

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
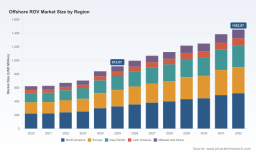
PW Consulting: ROV Revenue Hits $915M in 2025, Set for 6.89% CAGR Growth to $1.45B by 2032

Navigating the Deep: Strategic Imperatives in the 2026 Offshore ROV Market
The offshore energy sector stands at a critical inflection point. As global demand for subsea infrastructure intensifies, driven by both traditional hydrocarbon extraction and the rapid expansion of renewable energy capabilities, the role of Remotely Operated Vehicles (ROVs) has evolved from auxiliary support to mission-critical necessity. For stakeholders navigating this complex environment, understanding the trajectory of the Offshore ROV Market is not merely an academic exercise; it is a fundamental component of risk management and capital allocation strategy.
PW Consulting's latest market research provides a comprehensive lens through which to view these dynamics. This analysis is designed to equip decision-makers with the intelligence required to optimize portfolios, identify partnership opportunities, and anticipate technological shifts that will define the industry through 2032.
Market Trajectory and Historical Context
To understand where the market is going, one must first appreciate the resilience and growth pattern established over the last half-decade. The industry has demonstrated a robust recovery and expansion phase following the volatility of the early 2020s. Historical data indicates a steady climb in market valuation, reflecting increased operational activity and capital investment in subsea technologies.
Starting from a baseline in 2020, the market has progressed through a period of consolidation and growth. By 2025, the industry reached a significant milestone in valuation, setting the stage for the forecast period. The momentum is expected to continue with a compound annual growth rate that underscores the sector's health and long-term viability. This growth is not linear but is influenced by varying regional demands, technological adoptions, and application-specific requirements.
Financial Outlook and Forecast Horizon
The forecast period extending to 2032 suggests a clear upward trajectory. Projections indicate that market revenue will expand from approximately 996 million in 2026 to over 1.45 billion by the end of the forecast window. This expansion represents more than just nominal growth; it signals increased deployment rates, higher specification requirements for ROV systems, and broader adoption across diverse offshore activities.
For strategic planners, these figures highlight a market that is maturing yet still offers room for differentiation. The consistent growth rate of nearly 7 percent implies that while competition is intensifying, the total addressable market is expanding sufficiently to accommodate new entrants and innovative solutions. However, capturing this value requires a nuanced understanding of where the demand originates and how it is distributed across different operational classes and regions.
Segmentation Dynamics and Operational Diversity
The Offshore ROV Market is not a monolith. It is segmented by operational capability, geographic presence, and application vertical. Each segment presents unique challenges and opportunities for vendors and end-users alike. Our research delves into the specific revenue contributions and volume drivers within these categories, providing a granular view that aggregate numbers often obscure.
Vehicle Classifications and Technical Specifications
The market is broadly categorized by the class of ROV, ranging from observation-class systems used for light inspection to heavy work-class systems capable of complex intervention tasks. The divergence in pricing and capability between a micro/mini system and a heavy work-class unit is substantial. Price points can vary from a few thousand dollars for basic units to several million for advanced systems equipped with sophisticated navigation packages utilizing DVL and USBL technology, which alone can command significant premiums depending on range and precision requirements.
Understanding the revenue split among these classes is vital for manufacturers aligning their production capabilities with market demand. Light work-class and observation-class vehicles continue to hold significant share, driven by their versatility in inspection and maintenance roles. However, the heavy work-class segment remains critical for deep-water construction and high-intensity intervention, particularly in the oil and gas sector. Our report details the specific valuation of each class, allowing stakeholders to assess where their technology fits within the value chain.
Geographic Distribution and Regional Hubs
Demand for ROV services and systems is geographically dispersed, with established hubs in North America, Europe, and the Asia Pacific region. Each region presents distinct regulatory environments, energy mix priorities, and operational challenges. For instance, regulatory frameworks such as the NORSOK U-102 standard in Norway dictate specific requirements for safety, operator competence, and equipment, influencing how ROV services are procured and deployed in that region.
Similarly, international guidelines from the International Maritime Organization provide protocols for operations involving both divers and ROVs, adding a layer of compliance complexity that varies by jurisdiction. Our analysis maps the market value across key regions, identifying where growth is most pronounced. This regional intelligence is crucial for supply chain planning, sales localization, and identifying potential barriers to entry in emerging markets.
Application Verticals: Beyond Traditional Oil and Gas
While the oil and gas sector has historically been the dominant driver of ROV demand, the landscape is diversifying. Offshore wind energy, scientific research, and military and defense applications are contributing an increasing share of the total market volume. This diversification is a key risk mitigation factor for the industry, reducing reliance on a single commodity price cycle.
Diversification into Renewables and Defense
The growth of offshore wind farms requires extensive cable laying, inspection, and maintenance, creating a steady demand for ROVs specialized in these tasks. Military and defense applications also present unique requirements for underwater surveillance and intervention, driving innovation in stealth and endurance. Our report quantifies the revenue contribution from these varying sectors, highlighting how the balance of demand is shifting. Stakeholders who rely solely on traditional energy cycles may find their growth potential limited compared to those who have diversified their service offerings to include renewables and research support.
Regulatory and Compliance Landscape
Operating in these diverse sectors requires adherence to strict regulatory standards. In addition to regional safety standards, industrial and offshore ROV operations often require certified operators and documented maintenance procedures. Compliance is not just a legal obligation but a competitive differentiator. Companies that can demonstrably meet these rigorous standards gain trust with major operators who prioritize safety and reliability above cost alone. Our analysis examines how regulatory trends are shaping procurement criteria and vendor selection processes.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of large multinational corporations and specialized niche players. While the top few companies hold a noticeable portion of the market share, the market remains relatively fragmented compared to other heavy industrial sectors. This fragmentation suggests opportunities for consolidation, strategic partnerships, or specialized niche dominance.
Key Players and Capability Profiles
Several key companies define the current competitive environment. Oceaneering International, based in Houston, stands as one of the world's largest manufacturers and operators of work-class ROV systems, providing integrated services ranging from deepwater work-class systems to remote piloting and advanced visualization. Their scale allows them to influence pricing and technology standards across the industry.
In Europe, companies like Soil Machine Dynamics in the UK and Saab Seaeye Limited are pushing the boundaries of electric and hybrid systems. SMD specializes in advanced work-class ROVs including electric Quantum EV and Quasar MkII systems, focusing on cable tracking and offshore wind cable laying. Saab Seaeye offers electric and hybrid ROV systems for inspection and maintenance in both oil and gas and renewables.
TechnipFMC plc, also headquartered in Houston, leverages its Schilling Robotics legacy to provide advanced work-class ROV systems and intervention tools. They emphasize electric ROV electrification and remote piloting proof-of-concepts, positioning themselves at the forefront of subsea robotics innovation. Forum Energy Technologies and IKM Group round out the significant players, offering subsea technologies and inspection tools tailored for oil and gas and renewables.
International representation is strong, with Saipem in Italy focusing on subsea services for construction and IRM projects, and ECA Group in France providing ROV systems for subsea intervention. L3Harris Technologies and Deep Ocean Engineering contribute communication and integration systems, while TMT and Argus Remote Systems offer specialized ROV and subsea technologies for offshore operations.
Recent Innovations and Technology Shifts
The competitive landscape is currently being reshaped by technological announcements and product launches. In early 2026, Deep Trekker Inc. launched the SPECTRA ROV at Oceanology International, a next-generation subsea robot designed for high-current offshore environments with heavy payloads and precise inspection tasks. This highlights the industry's move towards higher performance in challenging conditions.
Simultaneously, Oceaneering has discussed the ROV electrification inflection point, positioning electric systems as a key efficiency driver in offshore energy. This aligns with broader industry trends towards decarbonization and operational efficiency. Furthermore, MacArtney Offshore Solutions was awarded a contract for a fully electrical eLARS system in early 2026, supporting ROV operations on offshore vessels. These developments signal a clear shift towards electrification and automation, themes that our report explores in depth to help companies prepare their technology roadmaps.
Strategic Value for 2026 Decision-Making
In an environment defined by rapid technological change and shifting energy priorities, access to accurate, forward-looking data is paramount. This market research is not just a retrospective on performance but a tool for shaping future strategy. It enables executives to validate assumptions, benchmark against competitors, and identify whitespace opportunities.
Risk Mitigation and Opportunity Identification
By understanding the concentration of market power, companies can better anticipate pricing pressures and competitive moves. The data on market concentration reveals the degree of rivalry and potential for consolidation. For investors, this informs valuation models and exit strategies. For operators, it informs procurement strategies and vendor management. Furthermore, recognizing the growth rates across different applications allows companies to pivot resources towards high-growth sectors such as offshore wind or specialized defense contracts before the market becomes saturated.
Technology Roadmap Alignment
The shift towards electric systems and automation requires significant capital investment and retraining. Companies need to know the pace of this adoption to avoid stranded assets or obsolescence. Our research provides the context needed to align internal R&D with external market demand. Whether it is investing in navigation precision, payload capacity, or energy efficiency, knowing the specific requirements of the end-user is critical.
Conclusion and Access to Intelligence
The Offshore ROV Market presents a compelling case for strategic investment and careful planning. With a clear growth trajectory extending into the next decade and a evolving competitive landscape driven by electrification and diversification, the opportunities are significant for those equipped with the right intelligence.
Offshore ROV Market
Offshore AUV Market
However, the macro trends discussed here only scratch the surface of the available intelligence. To truly navigate this landscape, stakeholders require a granular understanding of segment-specific revenue flows, regional growth nuances, and detailed competitor benchmarking that goes beyond public profiles.
PW Consulting's full Offshore ROV Market report offers this depth. It provides the specific segmentation data, regional valuations, and comprehensive competitive analysis necessary to formulate robust strategies for 2026 and beyond. To access the complete dataset and detailed forecasts that will inform your critical business decisions, we invite you to visit the source webpage for the full research briefing.
For detailed analysis of this topic, please visit the official page: Offshore ROV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com