

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cover Glass Market Hits $1.56B with 1.3% CAGR from 2026-2032

Strategic Intelligence for the 2026 Decision-Maker: Smartphone Cover Glass Market Outlook
The smartphone cover glass market stands at a critical inflection point as industrial leaders navigate the 2026 operating environment. Following five years of moderate historical expansion from 2020 through 2025, the sector now enters a forecast horizon extending to 2032 that demands precise strategic calibration. Our latest market research study translates complex supply-demand signals, regulatory shifts, and competitive maneuvers into actionable intelligence for procurement executives, R&D planners, and C-suite strategists who must allocate capital with confidence in a market defined by high concentration, evolving material science, and geopolitical recalibration.
This introduction outlines the strategic architecture of the full report, demonstrating why leadership teams should treat this assessment as a core input to 2026 portfolio decisions, capacity planning, and supplier negotiations. Rather than presenting a static snapshot, the research functions as a forward-looking decision framework that connects macro trajectory signals to on-the-ground execution priorities.
Market Trajectory and the Strategic Imperative for 2026
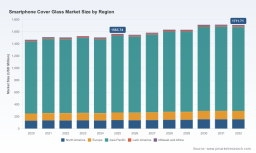
Historical revenue data from 2020 through 2025 reveals a market that has demonstrated resilience through cycles of component volatility, shifting OEM demand patterns, and intermittent supply disruptions. The sector crossed the 1,560 million USD threshold in the most recent base year measurement before entering the current forecast window, where trajectory modeling projects growth toward the 1,700 million USD range by the close of the decade. The forecasted compound annual growth rate of 1.3 percent across the 2026 to 2032 period underscores a market characterized by measured, structural expansion rather than explosive volatility.
For decision-makers, this trajectory carries nuanced implications. A modest CAGR in a high-value component category often masks significant underlying shifts in product mix, regional sourcing preferences, and premiumization trends within flagship device portfolios. The market is not simply growing; it is recomposing. Foldable device architectures, chemically strengthened glass specifications, and OEM supply chain localization strategies are altering where margin accrues and which suppliers capture disproportionate value. Strategic leaders who rely on backward-looking averages risk misallocating resources in a landscape where product-level differentiation and capacity positioning matter far more than aggregate market size.
The full report decomposes this trajectory into decision-grade scenarios, enabling teams to map procurement commitments, capital expenditure timing, and partnership strategies against realistic demand pathways rather than single-point projections. Readers are invited to access the complete forecast modeling and scenario analysis on our source page, where detailed growth drivers, sensitivity parameters, and regional momentum indicators are presented in full operational depth.
Competitive Architecture and Supplier Positioning
Market concentration remains a defining structural feature of the smartphone cover glass landscape. With the top three participants commanding approximately 80 percent of revenue and the top five collectively representing roughly 85 percent, the sector operates as an oligopolistic environment where incumbent scale, proprietary material formulations, and long-standing OEM relationships create formidable barriers to displacement. Yet within this concentrated framework, competitive dynamics are intensifying as suppliers race to align capacity with next-generation device requirements and navigate cost pressures from regulatory and raw-material headwinds.
Incumbent Technology Leaders
Corning Incorporated continues to anchor the premium cover glass segment through its Gorilla Glass series, anchoring a substantial share of flagship smartphone adoption. The launch of Corning® Gorilla® Glass Ceramic 3 in March 2026 marks a deliberate push into enhanced drop durability for foldable device architectures, signaling how material innovation is being reoriented around new form factors rather than traditional flat-panel optimization. This product introduction follows a broader capacity expansion effort in early 2026 designed to support high-volume flagship OEM demand across North American and Asian supply networks.
The strategic weight of these moves was reinforced by the August 2025 commencement of production at a Kentucky facility developed in partnership with Apple, representing a 2.5 billion USD investment that consolidated a significant share of iPhone and Apple Watch cover glass manufacturing within a single U.S.-based operation. For the broader market, this capacity concentration illustrates how anchor OEM commitments can reshape regional supply footprints while reinforcing the competitive moat of leading material science firms.
Diversified Global Contenders
AGC Inc. maintains a strong premium positioning through its Dragontrail® product family, delivering chemically strengthened glass solutions targeted at flagship and high-tier device segments. Schott AG continues to compete in the chemically strengthened category with its Xensation® series, including the Xensation® α specification engineered for improved drop performance in flagship smartphones. Nippon Electric Glass Co., Ltd. supplies chemically strengthened cover glass across smartphone and foldable device applications, while AvanStrate Inc. operates production facilities across Japan, Taiwan, and Korea to support display and cover glass requirements for major OEM customers.
In the broader production ecosystem, Biel Crystal Manufactory Ltd. has scaled as a major global producer of cell phone cover glass and sapphire components, with annual production capacity exceeding 1.85 billion units. Lens Technology Co., Ltd. functions as a key supplier of cover glass, structural parts, and functional modules for smartphones, serving major OEMs worldwide. TPK Holding Co., Ltd. rounds out the competitive field as a manufacturer of cover glass and touch solutions for smartphones. Together, these players illustrate a competitive matrix in which differentiation hinges on material specifications, geographic production flexibility, and the ability to secure multi-year OEM program wins.
The report's competitive analysis module provides granular supplier benchmarking, program win trajectory assessment, and capability-to-capacity alignment mapping. Complete supplier profiles, performance scorecards, and strategic risk indicators are available through the full research portal, enabling procurement and R&D teams to pressure-test their current sourcing strategies against an evolving competitive baseline.
Market Dynamics Shaping Strategic Decisions
The operating environment for smartphone cover glass in 2026 is shaped by intersecting forces that extend well beyond simple demand forecasting. Regulatory compliance costs, export control expansions, import surge patterns, raw-material lead-time elongation, and critical material export restrictions all contribute to a more complex sourcing and planning landscape. Decision-makers must integrate these factors into scenario planning rather than treating them as peripheral risks.
Regulatory and Chemical Compliance Pressure
The European Chemicals Agency reported that compliance costs for hydrofluoric acid used in glass tempering processes rose by 15 percent in 2024. This increase directly touches the cost structure of chemically strengthened glass production, a category that constitutes a meaningful share of premium cover glass supply. For procurement teams, the implication is twofold: cost models that rely on historical chemical input assumptions may underestimate current and forward pricing pressure, and supplier negotiations must account for regional regulatory divergence that affects landed cost and availability.
A separate indicator of demand strength and import dependency comes from the U.S. International Trade Commission, which recorded a 17 percent increase in imports of chemically strengthened glass for smartphones in 2024. This import trajectory signals both robust downstream demand and the extent to which supply chains remain internationally interconnected, even as OEMs pursue localized capacity strategies. The tension between import reliance and regional supply expansion is a key theme explored in the full report's dynamics section.
Geopolitical and Supply Chain Disruption Vectors
U.S. export controls on advanced computing items expanded in 2024, creating ripple effects across global supply chains for specialty glass components. While cover glass may not always fall directly within the narrowest controlled categories, the broader export control environment influences manufacturing equipment access, technology transfer constraints, and supplier qualification pathways across multiple jurisdictions. Strategic sourcing plans that do not explicitly model geopolitical fragmentation risk understimating qualification timelines and dual-sourcing complexity.
Compounding these dynamics, supply chain constraints and precursor cost surges drove average lead times for cover glass components to approximately 45 days in 2024. For program managers and inventory planners, extended lead times translate directly into buffer stock requirements, working capital exposure, and scheduling rigidity. The report's operations section translates these lead-time signals into inventory strategy recommendations and supplier diversification frameworks tailored to high-concentration supply markets.
Smartphone Cover Glass Market
In addition, China's Export Control Law and related MOFCOM regulations, updated with detailed rules in October 2024, impose restrictions on exports of critical materials used in display cover glass production. For organizations with material dependencies crossing this regulatory boundary, the compliance pathway now demands explicit mapping of raw-material origin, processing steps, and end-use classification. The research study provides a regulatory impact matrix that helps teams identify where material flow vulnerabilities could affect cost, availability, or program continuity.
Report Contents and Practical Applications
The full market research study is designed as a decision-support toolkit rather than a static market description. It integrates historical baseline analysis, multi-year forecasting, segmentation perspectives, competitive profiling, and dynamic risk factor assessment into a cohesive reference for 2026 strategy development. The following components represent the operational core of the study.
- Market Sizing and Trajectory Framework: A comprehensive revenue trajectory spanning historical baseline years and a forecast window extending through 2032, structured to support demand planning, capacity justification, and investment prioritization. The analysis presents total market perspective alongside segmentation views that illuminate type-based and application-based composition without isolating strategic detail from its broader market context.
- Segment-Level Composition Analysis: Detailed coverage of material type categories and end-use application patterns, enabling teams to understand where revenue concentration lies and how product mix evolution may influence sourcing requirements, specification priorities, and supplier selection criteria over the forecast horizon.
- Competitive Intelligence and Supplier Profiling: In-depth profiles of the key companies shaping the market, including headquarters location, product positioning, recent strategic developments, and capability signals. The study connects company-level moves to market-level implications, allowing readers to assess competitive threats, partnership opportunities, and supply base resilience.
- Dynamics and Risk Factor Integration: A structured treatment of regulatory cost pressures, export control and trade policy developments, import trend indicators, raw-material lead-time dynamics, and critical material export restrictions. This section translates external signals into actionable planning considerations for procurement, compliance, and supply chain leadership.
- Strategic Implications and Decision Scenarios: Synthesis sections that connect market data, competitive signals, and dynamic risks into decision scenarios for capacity planning, supplier diversification, program timing, and technology roadmapping. These scenarios are designed to support internal alignment across R&D, operations, procurement, and executive strategy functions.
Throughout the study, segmentation insights are presented with the discipline required for confidential strategic use: enough structural clarity to inform sourcing and planning logic, while preserving the detailed quantitative granularity that belongs in the paid research deliverable. The complete segmentation splits, scenario parameters, and sensitivity ranges are available in the full report, where they can be applied directly to internal models and negotiation frameworks.
Why This Research Matters for 2026 Decisions
In a market where a small number of suppliers command the majority of revenue, where material specifications are rapidly evolving around foldable and flagship device requirements, and where regulatory and geopolitical factors are reshaping cost and availability assumptions, strategic advantage depends on early visibility and precise interpretation. Aggregate market size alone does not reveal where margin is shifting, which supplier capabilities will be stressed by new device architectures, or how regional compliance costs will alter sourcing economics over the forecast period.
This research is built to answer those questions with the rigor required for enterprise decision-making. It equips leaders with a structured view of market trajectory, competitive positioning, and dynamic risk factors so that 2026 planning can move beyond reactive adjustments and toward proactive portfolio design. Whether the objective is to validate a long-term supplier partnership, prioritize R&D investment in cover glass specifications, or construct a resilient sourcing strategy amid extended lead times and raw-material constraints, the study provides the analytical foundation to make those choices with greater confidence.
The complete market research study, including full forecast modeling, detailed segmentation breakdowns, supplier capability assessments, and dynamic risk matrices, is available through our source page. We encourage strategy, procurement, and product leadership teams to access the full report to integrate these insights directly into 2026 planning cycles and supplier engagement strategies.
Glass Screen Protector Market
For detailed analysis of this topic, please visit the official page: Smartphone Cover Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com