

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Textile Dyes Market Hits $1.19 Billion in 2025, Projected 5.2% CAGR Through 2032

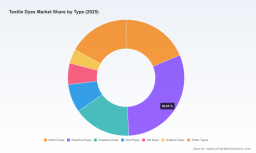
Navigating the Chromatics of Growth: Strategic Intelligence for the Textile Dyes Market Through 2032
The global textile dyes industry is entering a defining era. As sustainability mandates tighten, raw material volatility accelerates, and regional manufacturing footprints shift, color chemistry has evolved from a commoditized input into a strategic differentiator. For executives, procurement leaders, and product developers operating in the fibers and fabrics value chain, the ability to anticipate demand curves, regulatory inflection points, and competitive realignments is no longer optional. It is the foundation of resilient margin planning and portfolio strategy.
PW Consulting's latest Textile Dyes Market research report delivers a structured, data-rich examination of the sector across the forecast horizon of 2026 through 2032. Drawing on a rigorous historical evaluation spanning 2020 to 2025 and anchored in a base year of 2025, this study translates complex market mechanics into actionable intelligence. The following overview outlines the strategic architecture of the report, highlights the macro-momentum shaping the industry, and demonstrates how decision-makers can leverage these findings to outperform in a rapidly evolving landscape.
Market Trajectory: A Measured Expansion with Strategic inflection Points
Over the past half-decade, the textile dyes sector has demonstrated consistent growth, reflecting steady fiber production, evolving consumer color preferences, and the ongoing technical upgrading of dyeing infrastructure across mature and emerging manufacturing hubs. Historical revenue expanded from approximately 920.5 million USD in 2020 to a base-year valuation of 1190.0 million USD in 2025, underscoring the industry's capacity to compound value even amid supply chain disruptions and raw material price fluctuations.
Looking ahead, the forecast trajectory signals sustained expansion. The market is projected to reach a valuation of 1246.44 million USD in 2026, climbing steadily through the decade to attain a terminal forecast value of 1689.4 million USD by 2032. This path reflects a compound annual growth rate of 5.2 percent across the full forecast period, a pace that rewards early strategic positioning while demanding disciplined capacity planning, pricing architecture, and compliance readiness. Critically, the growth curve is not linear; it is shaped by distinct catalysts—including regulatory phase-ins, regional capacity realignments, and technology-led differentiation in dye chemistry—that require granular analysis to translate into operational advantage.
This study dissects those catalysts without oversimplifying them. Rather than offering a single headline number, the report maps the interplay between historical demand elasticity, forward-looking procurement signals, and the structural factors that will determine which market participants capture disproportionate share. Readers will find that the macro-outlook serves as an anchoring framework, while the deeper segmentation layers reveal where margin pools are forming and where competitive intensity is likely to compress returns.
Report Architecture: From Strategic Framework to Operational Playbook
A market study earns its place on the executive dashboard only when it bridges high-level economic signals with on-the-ground decision variables. The PW Consulting Textile Dyes Market report is built around that principle. It delivers a comprehensive, multi-layered assessment that spans quantitative forecasting, qualitative industry mapping, and competitive benchmarking, all organized to support scenario planning and resource allocation.
At its core, the report integrates a detailed industry analysis covering the period from 2020 through 2032, with a sharp focus on the immediate two-year strategic window of 2026 and 2027. This design enables leadership teams to calibrate both near-term tactical responses and longer-term capital deployment. The study examines the market through a structured segmentation lens—by type, by application, and by region—allowing users to isolate the demand engines most relevant to their product portfolios, manufacturing footprint, and distribution channels. Each segmentation dimension is evaluated for growth momentum, pricing sensitivity, and substitution risk, ensuring that strategic plans rest on differentiated evidence rather than aggregated averages.
Beyond segmentation, the report incorporates a thorough competitive landscape assessment. Market concentration metrics are analyzed to clarify the balance between consolidated leadership and fragmented niche competition, while company-level profiles illuminate the strategic priorities shaping the actions of dominant players. These profiles are not static corporate summaries; they are structured around each firm's specific dye offerings, regional strengths, and innovation orientation, providing a practical map of where incumbents are reinforcing their positions and where gaps may be opening for fast-moving challengers.
Dyes Market
The research also embeds a robust view of industry dynamics. Raw material economics, regulatory evolution, and sustainability-driven procurement requirements are treated as interconnected forces, not isolated events. By tying these dynamics to forecast periods and competitive behavior, the report equips readers to anticipate cost pressures, compliance expenditures, and product reformulation timelines that will influence sourcing strategies and product roadmaps.
For practitioners seeking operational depth, the study delivers the kind of actionable detail that supports concrete decisions: pricing architecture considerations, demand-center prioritization, regulatory readiness checks, and technology adoption pathways. The objective is to give executives and analysts a reference point that can be directly integrated into commercial planning, supply chain strategy, and R&D prioritization.
Competitive Landscape: Positioning, Differentiation, and the Battle for Specialty Relevance
The textile dyes market is characterized by a mix of global specialty chemical leaders, regional manufacturing powerhouses, and focused dye specialists. Competitive intensity is shaped not only by volume scale, but by the ability to offer performance-advantaged products, compliance-forward formulations, and application-specific color solutions. Market concentration reflects a moderately consolidated structure, with leading players commanding a meaningful share of total revenue while leaving substantial space for differentiated mid-tier and regional competitors to compete on technical service, agility, and customer intimacy.
Several organizations stand out for the strategic direction of their dye portfolios. Archroma, headquartered in Pratteln, Switzerland, has been advancing sustainable specialty dyes and dyeing solutions with bio-based options, signaling a clear orientation toward lower-environmental-impact chemistry and resource-efficient processing. DyStar Group, based in Singapore, continues to position itself as a leading supplier of textile dyes, pigments, and colorants with broad fiber coverage, an approach that supports customers seeking continuity across diverse material inputs. Huntsman Corporation, operating from The Woodlands, Texas, United States, maintains a portfolio of textile effects dyes and performance chemicals, reinforcing a value proposition centered on functional outcomes as well as color.
In Europe, Clariant AG of Muttenz, Switzerland, contributes specialty chemicals including dyes tailored for textile applications, while Lanxess AG, based in Cologne, Germany, offers dyes under its Macrolex brand for textiles, aligning its product identity with established performance credentials. Across the Indian subcontinent, Atul Ltd., headquartered in Atul, Gujarat, and Kiri Industries Ltd., also based in Gujarat, represent strong regional capabilities—Atul with performance chemicals and dyes for textiles, and Kiri with a focused emphasis on reactive and acid dyes. BASF SE, headquartered in Ludwigshafen, Germany, sustains a broad offering of dyes and intermediates for textile applications, leveraging scale and integrated chemistry competencies. Meanwhile, Sumitomo Chemical Co., Ltd., operating from Tokyo, Japan, pursues specialty dyes for textiles, underscoring the continued relevance of application-specific innovation in the global supply base.
Together, these players illustrate the competitive logic of the market: scale provides procurement and distribution advantages, but differentiation increasingly depends on sustainability attributes, color fastness and reproducibility, regulatory compliance readiness, and the ability to support customers through process optimization. The report analyzes how these firms are navigating raw material cycles, expanding or rationalizing capacity, and positioning their portfolios against tightening compliance expectations. By synthesizing these competitive signals, the study helps readers identify which strategic moves are likely to strengthen market standing and which product categories may face intensifying margin pressure.
Industry Dynamics: Regulation, Raw Materials, and the New Compliance Premium
No strategic assessment of the textile dyes market can ignore the regulatory and input-cost environment reshaping procurement behavior. In 2026, these forces are not background conditions; they are direct determinants of product design, supplier selection, and regional sourcing decisions.
On the regulatory front, compliance expectations are becoming more demanding and more tightly enforced. From 1 January 2026, OEKO-TEX standards tightened PFAS limits to 25 µg/kg across all standards, accompanied by enhanced verification mechanisms. This change directly affects the colorant and auxiliary chemistry that textile manufacturers can confidently specify, accelerating the shift toward lower-concern formulations. In parallel, REACH Annex XVII Entry 72 continues to restrict 33 substances in clothing, textiles, and footwear that come into contact with human skin, with ongoing enforcement sustaining pressure on product stewardship across the value chain. Broader chemical policy signals add further complexity: a PFAS restriction in consumer textiles such as rain jackets bans the sale and use of PFHxA from 2025 onward, and a U.S. Environmental Protection Agency final rule prohibits the distribution of articles containing phenol, isopropylated phosphate in U.S. commerce starting 31 October 2026, affecting textile and fashion supply chains.
These developments carry a strategic implication: compliance is moving from a defensive obligation to a commercial asset. Manufacturers that can demonstrate clear substance profiles, robust verification documentation, and reformulated dye systems are better positioned to serve brands and converters facing their own disclosure and procurement requirements. The report examines how regulatory timing interacts with product launch cycles and sourcing transitions, helping readers gauge where compliance-driven demand may accelerate adoption of specific dye technologies.
Raw material dynamics are equally consequential. During the first quarter of 2026, H acid prices increased moderately in Germany to 5,266 USD per metric ton, up 3.09 percent, driven by steady demand from specialty chemical and textile converter procurement. While the move is measured rather than disruptive, it reflects a broader environment in which input costs are influenced by regional demand patterns, production constraints, and the specialized nature of key intermediates. For dye producers and downstream textile processors, even moderate input-price movements can affect margin structures, quotations, and inventory timing.
Recent market events further illustrate the operational reality of this environment. In February 2026, Zhejiang Runtu Co., Ltd. announced a significant price surge for disperse dyes effective that month, with increases reaching up to 600 USD per metric ton for high-concentration blacks and blues. Around the same time, Zhejiang Longsheng Group Co., Ltd. announced an additional CNY 2,000 increase for disperse black and blue dyes, bringing the cumulative hike in the year to CNY 5,000, a move attributed to raw material costs. These announcements underscore how regional pricing actions can quickly affect cost planning and highlight the importance of monitoring supplier signaling as part of broader procurement strategy.
On the innovation and validation side, January 2026 saw Archroma announce the commercial launch of a new line of cellulosic direct dyes with up to 35 percent effluent COD reduction compared to conventional grades, a development that aligns product performance with wastewater management objectives. In April 2026, SGS attended China Interdye 2026 in Shanghai, connecting with experts on sustainable chemical management and awarding the first No PFAS Detected green-mark certificate for a water-repellent agent to a textile firm. Such milestones matter because they signal where validation frameworks, customer expectations, and product differentiation are converging.
Strategic Priorities for 2026 Decision-Making
For executives entering 2026, the central challenge is to convert market complexity into structured choices. The forecast growth rate of 5.2 percent confirms that demand expansion will continue, but value capture will depend on how well organizations align portfolio, sourcing, and compliance strategies with the specific forces shaping their segments. Several strategic priorities emerge from the broader market picture.
Textile Dyes Market
First, portfolio composition should be evaluated against both demand durability and regulatory exposure. Dye families and application areas that face higher compliance scrutiny may require accelerated reformulation, while segments with strong growth momentum and lower substitution risk may justify prioritized capacity or inventory support. Second, pricing and procurement planning should account for regional raw material behavior and supplier-level pricing actions, especially in disperse dye categories where recent increases have demonstrated the speed at which cost structures can shift. Third, sustainability and verification capabilities are becoming competitive levers. Formulations that reduce effluent load, lower concern-substance risk, and support customer documentation needs can strengthen supplier positioning in brand-driven procurement environments. Fourth, regional demand patterns should inform distribution and service strategies, since growth is not evenly distributed and customer expectations differ across manufacturing centers.
The study is designed to support each of these priorities with specific evidence, enabling readers to test assumptions, compare scenarios, and identify where decisive action will generate the greatest strategic return. By connecting the macro trajectory to segmentation-level dynamics, competitive behavior, and regulatory timing, the report provides a decision framework rather than a static market snapshot.
Accessing the Full Intelligence
The overview presented here reflects the analytical direction and strategic scope of the full Textile Dyes Market research report. To obtain the complete dataset, detailed segmentation analysis, comprehensive company profiles, and the full set of market forecasts and competitive assessments that support rigorous planning, readers are encouraged to access the complete report and accompanying materials directly. The depth required for precise sourcing, product roadmap decisions, and competitive positioning can be found in the full study, where each macro signal is reinforced by structured evidence and actionable interpretation.
For detailed analysis of this topic, please visit the official page: Textile Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com