

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Smart Locks Market: How 14.5% CAGR and Residential Demand Reshape 2026–2032
By pmarketresearch, 2026-09-21
The Smart Locks Market: Strategic Trends and Commercial Opportunities Through 2032
The smart locks market has evolved from a niche convenience upgrade into a structural component of the broader connected home and commercial security ecosystem. Valued at approximately 1.67 billion USD in 2025, the sector has demonstrated consistent expansion, growing from 850 million USD in 2020 at a compound annual rate of 14.5% through the forecast horizon extending to 2032. By the end of the projection period, revenue is expected to surpass 4.28 billion USD, signaling a market that has moved past early adoption friction and entered a phase defined by standardization, ecosystem integration, and security formalization. This trajectory is not merely a function of consumer curiosity; it reflects convergent pressures from residential security expectations, commercial access modernization, and the maturation of low-power wireless protocols that make keyless entry reliable enough for daily use.
For executives and investors evaluating the space, the headline growth rate only tells part of the story. The market is simultaneously consolidating around interoperable standards, fragmenting across application-specific requirements, and facing regulatory scrutiny that will reshape product roadmaps. Understanding where value is created—and where margin compression or compliance risk emerges—requires looking beyond total market size and examining the structural forces that will determine which players scale profitably and which get squeezed by commoditization or certification bottlenecks.
Market Snapshot: Scale, Growth, and Structural Composition
The revenue trajectory from 2020 through 2025 reflects a market that accelerated as wireless connectivity, battery efficiency, and mobile credentialing became routine expectations rather than differentiators. The jump from 1.44 billion USD in 2024 to 1.67 billion USD in 2025 indicates that smart locks are increasingly treated as baseline infrastructure in new residential construction and retrofitting programs, rather than optional premium add-ons. The forecast period through 2032 points to a market that will more than double in size, with growth accelerating in the outer years as mainstream replacement cycles and commercial retrofit programs compound.
Segmentation patterns reveal where demand is concentrated and where strategic positioning matters most. By product architecture, deadbolt-style smart locks command the largest revenue share, reflecting their dominance in residential door retrofitting and new-build specifications. Lever handle variants represent a meaningful secondary stream, particularly in commercial and multi-family contexts where ergonomic and fire-code considerations favor that form factor. Padlocks and other specialized formats occupy a smaller but strategically distinct niche, often serving temporary access, asset protection, and outdoor use cases where standalone battery operation and offline credentialing are critical. By application, residential deployments account for the majority of revenue, yet commercial adoption is expanding at a notable pace as property managers, co-working operators, and enterprise facilities teams seek centralized access control without full wiring overhauls. Geographically, North America remains the largest revenue contributor, supported by high smart-home penetration, renovation activity, and a strong DIY installation culture. Europe follows as a substantial market shaped by regulatory-driven security certification and multi-family housing modernization. Asia Pacific represents a rapidly expanding region where urbanization, rising disposable income, and domestic manufacturing scale are reshaping supply dynamics. Latin America and the Middle East & Africa together form an earlier-stage but strategically relevant footprint, often characterized by pilot deployments, security-conscious premium segments, and gradual normalization of connected access as total cost of ownership improves.
Market concentration remains moderate, with the top three players accounting for roughly 45% of revenue and the top five reaching just over half. This level of concentration indicates a market that is neither dominated by a single hegemonic player nor completely fragmented. It is a field where incumbents with strong distribution, brand trust, and ecosystem alignment hold meaningful advantages, while agile entrants can still win in defined sub-segments by solving a specific user experience, design, or certification challenge. The presence of both retrofit specialists and full-lock manufacturers, alongside regional hardware brands expanding into connected access, suggests that competition will increasingly hinge on interoperability, installation friction, and the ability to meet unified physical-and-cyber security expectations.
Core Challenges and Inflection Points
Despite favorable growth fundamentals, the market is passing through several structural tension points that will separate durable strategies from reactive product launches.
The first challenge is the transition from standalone convenience to certified security. For years, smart locks were marketed primarily around ease of access, temporary credentialing, and app-based control. That value proposition is no longer sufficient as buyers, regulators, and installer networks increasingly expect evidence that a connected lock can withstand both physical attack vectors and digital compromise. Products that treat cybersecurity as an afterthought face growing friction in premium residential specifications and commercial procurement, where risk teams and insurance considerations are becoming more influential. The market is therefore moving toward a phase where trust is a purchasable attribute, not a marketing claim.
The second challenge is ecosystem fragmentation slowly giving way to interoperability pressure. Early smart lock adoption was constrained by questions about whether a lock would reliably communicate with a given hub, voice assistant, or mobile platform. The broader rollout of standards-aligned connectivity has reduced some of that uncertainty, but it has also raised the bar for product design. Manufacturers that built closed or partially closed ecosystems must now reconcile backward compatibility, credential portability, and long-term software support. This creates an execution challenge: interoperability expands the addressable user base, but it also exposes a product to broader integration testing, firmware lifecycle obligations, and competitive exposure once the lock becomes interchangeable with alternatives in the same ecosystem.
The third challenge lies in supply chain exposure for the semiconductor and radio components that underpin connectivity, biometric sensing, and secure credential storage. As smart locks become more feature-rich, they depend on a broader set of modules that are susceptible to concentration risk, lead-time variability, and cost swings. This matters because margin structures in consumer hardware are already sensitive to component volatility, and because security-oriented authentication hardware can create supply dependencies that are harder to reroute than commodity parts. Companies that treat component strategy as a procurement detail rather than a product architecture decision may find themselves exposed to both cost shocks and launch timing risk.
These challenges converge into a broader inflection point: the market is shifting from a phase where feature novelty drives purchases to one where reliability, certification, and integration depth determine repeat adoption and referral. That shift rewards organizations that can align product design, compliance planning, and ecosystem relationships early, while penalizing those that continue to compete primarily on price or isolated feature claims.
Key Demand Drivers Reshaping the Market
The growth trajectory is not accidental. It is being propelled by a set of reinforcing drivers that are changing both what buyers expect and what manufacturers must deliver.
Technological innovation remains the most visible driver, particularly in the areas of low-power wireless connectivity, credential diversity, and hands-free access. The move toward standards-aligned protocols has reduced friction for users who want a lock to function as part of a broader home or facility environment rather than as a standalone gadget. At the same time, biometric modalities and sensor fusion are expanding the definition of convenience and security at the door. Fingerprint recognition has become a familiar baseline, but newer deployments are exploring palm-vein and other liveness-aware modalities that can reduce false acceptance and improve usability in wet, cold, or high-traffic conditions. The commercial implications are significant: biometrics can lower reliance on shared credentials, improve auditability, and support access experiences that feel less like a trade-off between security and convenience. In parallel, ultra-wideband technology is gaining attention for proximity-based, hands-free unlocking that can preserve security while simplifying daily use. When implemented carefully, UWB can support short-range, direction-aware access that avoids some of the spoofing risks associated with simpler proximity methods.
Policy and regulatory developments are becoming an equally important driver, especially because smart locks sit at the intersection of physical security and connected-device risk. Cybersecurity labeling and trust-mark initiatives for wireless smart-home products are pressuring manufacturers to provide clearer baseline assurances around device security, update practices, and vulnerability handling. In parallel, certification bodies are increasingly combining mechanical attack testing with IoT cybersecurity specifications, creating a more unified expectation for what counts as a credible residential smart lock. These frameworks matter commercially because they influence spec-in decisions, insurer and property-manager confidence, and the willingness of installation partners to recommend a product. Compliance is becoming part of the competitive moat: products that proactively align with recognized physical-and-digital standards can shorten sales cycles in cautious segments, while those that lag may face longer evaluation periods or exclusion from certain procurement channels.
Demand-side behavior is shifting as well. In residential settings, consumers are increasingly treating connected access as part of a broader home security and convenience bundle rather than an isolated purchase. This is visible in the way smart lock adoption is influenced by neighboring devices, mobile ecosystem preferences, and the desire for seamless credential sharing with family members, guests, and service providers. In commercial contexts, the driver is different but equally powerful: facility operators want access solutions that reduce rekeying costs, improve audit trails, and support flexible occupancy without major wiring projects. The result is growing interest in battery-powered connected locks, retrofit devices that attach to existing hardware, and access systems that can be managed remotely while preserving offline functionality for resilience. Across both sectors, the emphasis is moving toward total experience—installation effort, day-to-day reliability, battery life, and the quality of the companion app—rather than a narrow set of lock features.
Smart Door Lock Market
Supply chain and cost structures are also reshaping the market. The increasing reliance on advanced modules for connectivity and authentication means that component availability and regional semiconductor dynamics can influence product timing, pricing, and feature roadmaps. This dynamic favors manufacturers that design with flexibility, maintain a disciplined bill of materials, and plan for continuity across multiple sourcing scenarios. It also creates a distinguishing advantage for companies that can balance feature ambition with realistic component strategy. In a market where many products are functionally similar at the point of installation, the ability to deliver consistent availability, stable pricing, and predictable firmware support can become a meaningful commercial differentiator.
Recent product activity illustrates how these drivers are being translated into market-facing moves. One major player released a smart lock built around ultra-wideband technology with hands-free mobile credentialing and standards-aligned thread compatibility, signaling a focus on frictionless access within a specific mobile ecosystem. Around the same period, another manufacturer expanded its portfolio at a major consumer technology event, introducing models certified for both UWB and interoperability standards, which suggests a push to position connected locks as part of a broader smart-home fabric rather than as isolated hardware. Separately, a large consumer-tech brand updated its lock lineup with palm-vein recognition and automatic locking features, underscoring the continuing push toward biometric differentiation and hands-free reliability. These developments are not isolated product launches; they reflect a market that is testing multiple avenues at once—ecosystem alignment, biometric refinement, and installation simplicity—while racing to meet expectations set by regulatory and security normalization.
Competitive Landscape and Strategic Positioning
The competitive field is shaped by a mix of established lock manufacturers, smart-home specialists, retrofit-focused brands, and larger consumer-tech companies extending into access control. Rather than competing solely on lock mechanics, players are differentiating through installation model, ecosystem alignment, biometric design, and the balance between connectivity and offline resilience.
Aqara has positioned itself around interoperability and hands-free convenience, with product designs that emphasize thread-compatible connectivity and mobile credentialing integrated with major platform ecosystems. This approach targets users who want a lock that behaves as part of a coordinated smart-home environment, reducing friction for platform-driven households. August Home has historically leaned into retrofit compatibility and Wi-Fi-based keyless entry, an approach that lowers installation barriers for consumers who want to upgrade existing hardware without replacing the entire lock assembly. Yale and Schlage continue to draw strength from brand trust, broader access-control heritage, and touchscreen or keypad-oriented designs that appeal to buyers prioritizing familiarity, durability, and integration with broader residential and commercial security expectations. Kwikset adds another angle with re-keying technology combined with Wi-Fi and standards-aligned smart locks, appealing to users who value both connected convenience and the ability to manage mechanical key control.
Eufy has carved a distinct position by fusing video and access functions into the lock form factor, combining fingerprint or palm-vein sensing with camera integration. That hybrid approach serves buyers who want visual verification at the door without installing separate devices, though it also raises product complexity and privacy expectations. CANDY HOUSE and igloohome illustrate a different strategic axis: CANDY HOUSE has emphasized fast Bluetooth-based access and tool-free installation, targeting convenience and ease of adoption, while igloohome has focused on offline access control for locks and padlocks, an approach that suits scenarios where internet dependency is undesirable or unreliable. Nuki specializes in retrofit electronic lock conversion with app and fingerprint access, competing on the ability to add connectivity to existing doors without full hardware replacement. Level has pursued a design-forward, “invisible” smart lock concept that integrates into the door aesthetic and supports major platform credentialing, which can be attractive in premium residential and design-sensitive projects.
On the broader manufacturing side, Dreame Technology has used major trade platforms to expand a full smart lock lineup with standards-aligned interoperability and UWB support, indicating a push to compete across feature tiers rather than in a narrow niche. TCL has extended into multi-biometric and fingerprint-based lock series, reinforcing the industry-wide emphasis on authentication variety and automated locking features. Taken together, these players show a market where strategy is increasingly defined by the tension between ecosystem alignment, biometric differentiation, installation simplicity, and offline resilience.
The landscape is evolving along three overlapping directions. First, there is a consolidation tendency among brands that can leverage distribution scale, installer relationships, and platform partnerships to create repeatable go-to-market patterns. Second, there is continued fragmentation in specialized sub-segments where design, offline functionality, or hybrid video-access value propositions can sustain differentiation. Third, new entrants and larger consumer-electronics groups are using smart locks as an entry point into connected home security, which increases competitive intensity but also expands awareness and retail presence. The net effect is a market where winning does not depend on being the largest player in every category, but on choosing a defensible positioning and executing it with disciplined product planning, certification readiness, and ecosystem compatibility.
Forward Outlook: Three Trends Likely to Shape the Next 3–5 Years
The next several years are likely to be defined by a shift from feature competition to trust, integration, and lifecycle competitiveness. Three trends stand out.
First, cybersecurity and physical-security certification will become central commercial requirements rather than optional credentials. As labeling initiatives and unified testing specifications become more familiar to buyers and procurement teams, smart locks that can demonstrate credible security baselines will gain an advantage in both retail and specification channels. This trend will likely raise the entry barrier for low-effort products and reward manufacturers that invest early in secure update pathways, transparent vulnerability handling, and compliance documentation. Commercial opportunity here lies in positioning certification as a selling point for spec-in, insurance-aligned, and multi-family deployments, where risk reduction is part of the purchase rationale.
PW Consulting Health Care Research Center
Second, biometric and hands-free access will broaden, but with a stronger emphasis on reliability, privacy, and contextual appropriateness. Fingerprint and palm-vein methods will continue to expand, especially where they reduce dependence on shared keys or codes and improve auditability. Ultra-wideband and proximity-based access will grow in premium and convenience-oriented segments, but adoption will depend on real-world performance, battery trade-offs, and the ability to avoid false unlocks or usability friction. The commercial opportunity is not simply adding sensors; it is designing access experiences that feel secure without becoming cumbersome, and that can be supported over the product lifecycle with firmware resilience and user-friendly recovery paths.
Third, smart locks will increasingly be evaluated as part of ecosystem and lifecycle economics rather than as isolated hardware purchases. Buyers will weigh platform compatibility, app quality, battery management, installer experience, and long-term software support alongside the lock itself. This creates opportunities for companies that can package hardware with dependable software, clear credential management, and integration support for property managers or platform-driven households. It also introduces risk for products that rely on short-term feature novelty without a credible plan for ongoing updates, compatibility maintenance, or serviceability. In this environment, sustained advantage will come from reducing total friction across purchase, installation, daily use, and long-term management.
Potential risks and uncertainties remain. Regulatory expectations may evolve faster than product roadmaps in some regions, especially where physical and digital certification requirements are harmonized through new specifications or national guidance. Component availability and semiconductor concentration could affect cost stability and launch timing for feature-rich models. Ecosystem dependence may create upside in the short term but can also expose manufacturers to platform policy shifts or competitive substitution if interoperability becomes widespread. Finally, consumer expectations around privacy, data handling, and app transparency will continue to rise, meaning that even technically capable products can lose traction if trust and transparency are not managed carefully.
Strategic Actions for Decision Makers
For manufacturers, the priority is to align product roadmaps with the emerging trust-and-interoperability baseline. That means designing for security documentation, update discipline, and cross-platform compatibility as first-class requirements rather than post-launch additions. It also means choosing biometric and hands-free features based on real usability and reliability rather than novelty, and building supply chain flexibility around connectivity and authentication components. Companies that can combine a clear installation advantage with credible certification readiness and consistent lifecycle support will be better positioned to win in both retail and specification-driven channels.
For investors, the opportunity is to distinguish between companies that are scaling through genuine ecosystem, distribution, and compliance advantages and those that are relying on short-term feature launches or price competition. Due diligence should weigh certification positioning, platform relationships, component strategy, and the durability of the installation model. Businesses that can demonstrate repeatable procurement in residential retrofitting, multi-family, or commercial access modernization—and that can manage security expectations without eroding margin—offer more resilient exposure than those whose growth depends primarily on promotional momentum.
Bike Locks Market
For procurement leaders and property operators, the practical move is to evaluate smart locks as part of an access strategy rather than as discrete hardware purchases. Criteria should include not only locking performance and credential options, but also installation complexity, offline resilience, app management, audit capabilities, and the depth of support for future platform or certification changes. In commercial and multi-family settings, centralized management, fallback behavior, and installer familiarity can matter as much as the marketed feature set. Selecting products that are already aligned with recognized security and interoperability expectations can reduce downstream evaluation risk and simplify future upgrades.
As the market expands toward the 4 billion USD range over the forecast period, the volume of opportunity will increasingly separate from the ease of capturing it. The companies and buyers that benefit most will be those who treat smart locks as a long-term access layer—shaped by security expectations, ecosystem realities, and lifecycle economics—rather than as a one-time convenience purchase. For organizations seeking segmented forecasts, competitive benchmarking, and tailored strategic pathways across product type, application, and region, the full research report provides the deeper data set and scenario detail needed to translate these trends into concrete plans.
For detailed analysis of this topic, please visit the official page: Smart Locks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Windshield Washer Fluid Market: Why 4.9% CAGR and OEM Dynamics Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Automotive Windshield Washer Fluid Market
Market Overview: Size, Trajectory, and Structural Dynamics
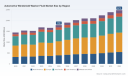
The global automotive windshield washer fluid market has entered a phase of measured expansion, driven by steady vehicle parc growth, seasonal maintenance cycles, and incremental performance requirements tied to visibility and safety standards. Valued at approximately USD 1,790 million in 2025, the market reflects a compound annual growth rate of 4.9 percent across the forecast horizon through 2032, reaching an estimated USD 2,479 million by the end of the period. The trajectory from 2020 through 2025 illustrates consistent demand recovery following early-pandemic disruptions, with 2023 marking a local peak before a modest recalibration in 2024 that aligned with broader supply chain normalization and inventory adjustments. Growth through the mid-2020s is expected to be supported by replacement fluid consumption, fleet maintenance schedules, and geographic expansion in regions where vehicle ownership continues to rise.
One of the defining structural features of the market is its concentration. The top three participants collectively account for roughly 55 percent of revenue, while the top five capture approximately 65 percent. This level of consolidation indicates that scale advantages, distribution reach, and brand recognition remain critical barriers to entry, yet the remaining share is distributed across specialized manufacturers, regional suppliers, and emerging formulation innovators. The presence of both global consumer brands and regional specialists creates a dual dynamic: incumbents compete on breadth, shelf presence, and OEM relationships, while newer or niche players differentiate through formulation specifics, sustainability positioning, and concentrated products designed to lower logistics and packaging costs.
Current market dynamics are shaped by several intersecting pressures. Raw material volatility remains a persistent concern, particularly for alcohol-based formulations where methanol, ethanol, and glycol derivatives influence both performance and cost. Simultaneously, regulatory frameworks in key markets are tightening limits on volatile organic compounds, pushing manufacturers to reconsider ingredient choices, packaging formats, and dilution pathways. Consumer and fleet purchasing behavior is also evolving, with a growing preference for multi-season reliability, reduced streaking, and formulations that perform reliably under extreme temperature conditions. These factors combine to make the market less about pure volume and more about formulation precision, compliance readiness, and channel control.
Key Challenges and Inflection Points
The first central challenge is regulatory compliance and its cascading effect on formulation strategy. Stricter VOC controls in sensitive air basins are forcing suppliers to redesign products without sacrificing cleaning efficacy or freeze protection. This is not a simple substitution exercise; it requires reformulation, testing, and sometimes changes in packaging or concentrate dilution logic to preserve performance while meeting legal thresholds. Companies that rely on legacy recipes face the risk of undergoing costly redesign cycles while competitors already advanced in low-VOC architectures can capture shelf space and procurement approvals more quickly.
The second inflection point is the changing meaning of visibility within vehicle safety programs. As safety rating frameworks for newer model years increasingly incorporate advanced driver-assistance technologies and crash-avoidance features, forward visibility has gained a more direct link to vehicle performance evaluation. Washer fluid is no longer only a maintenance consumable for cleanliness; it becomes part of a broader visibility ecosystem. That shift raises the stakes for fluid clarity, anti-smearing characteristics, and compatibility with sensor and camera cleanliness expectations, especially in commercial fleets and higher-end passenger vehicles.
The third challenge is supply chain and cost structure variability. The washer fluid segment is sensitive to feedstock pricing, freight costs, and regional production footprints. While the market is not as complex as powertrain components, it still depends on chemical sourcing, blending capacity, and distribution efficiency. In concentrated product models, logistics economics improve, but dilution instructions, consumer education, and seasonal storage behavior become more important to manage. For aftermarket-focused suppliers, inventory turnover and regional demand swings can amplify working capital pressure, especially when weather patterns shift purchasing timing across territories.
Key Growth Drivers
Technology and formulation innovation continue to be a primary driver. Suppliers are moving beyond basic cleaning toward fluids that combine anti-icing performance, water repellency, bug removal, and reduced residue. This evolution reflects a broader push to address multiple pain points in a single fill, which resonates with both retail consumers and fleet managers seeking simpler maintenance routines. The recent progress in ethanol-based and methanol-free formulations is particularly noteworthy. By 2030, such safer or lower-toxicity variants are projected to represent a meaningful share of new product launches, up from a smaller base in the mid-2020s. This trend is not just regulatory; it is also customer-facing, as end users and procurement teams increasingly value reduced handling risk, environmental messaging, and safer storage conditions.
Policy and regulatory dynamics are reshaping formulation priorities and time-to-market. VOC limits in certain jurisdictions are effectively setting a new baseline for pre-mixed and diluted products. Compliance is no longer optional; it determines which products can be sold in specific regions and which can remain on shelf year-round. At the same time, visibility-related safety expectations are connecting washer fluid performance to broader vehicle assessment criteria, encouraging manufacturers to invest in cleaning reliability and residue control. These regulatory and safety-linked developments are raising the technical bar and rewarding companies that can align product design with regional rules and fleet requirements.
Demand-side changes are reinforcing the shift toward multi-function and season-ready fluids. Vehicle owners and fleet operators increasingly seek products that reduce the number of specialized purchases and simplify stocking. In colder climates, anti-freeze performance remains non-negotiable, while in warmer or insect-heavy environments, bug-removing and water-repelling characteristics carry more weight. The emergence of concentrated formats and tablet-based options is a response to consumer interest in storage efficiency, reduced plastic use, and flexible dilution. This demand is especially visible where aftermarket purchasing remains the dominant channel, as individual buyers and small operators look for convenience, lower bulk weight, and clearer performance claims.
Supply chain and cost structure evolution is also a driver, though not always in an obvious way. The market is increasingly influenced by regional production strategies, ingredient substitution, and packaging decisions that affect landed cost and margin. Suppliers with flexible blending capacity and a mix of ready-to-use and concentrated offerings tend to respond more effectively to regional demand changes. Meanwhile, distribution partnerships and online automotive ecosystems are expanding the number of touchpoints where fluids are purchased, creating both revenue opportunities and execution complexity for manufacturers trying to maintain consistent product availability and regional compliance.
Competitive Landscape and Leading Strategies
The market’s competitive set is diversified but unevenly positioned. Several U.S.-based suppliers dominate consumer-facing visibility through strong brand recognition, broad retail distribution, and product lines that span all-season, de-icer, and extreme-weather variants. One leading aftermarket provider has emphasized next-generation fluids designed for extreme temperatures with enhanced cleaning and anti-icing properties, reflecting a strategy focused on performance differentiation in the most demanding use cases. Another major U.S. brand has built a distinct identity around two-in-one all-season and extreme-weather products for consumer and fleet use, leveraging a familiar consumer brand that resonates with visibility and water-beading benefits.
Global industrial suppliers add a different layer of competition. One multinational group competes across multiple channels with advanced formulations tied to visibility and cleaning performance, often positioning its products as part of a broader portfolio of specialty materials and automotive maintenance solutions. A German specialist has carved out a premium angle with concentrates and all-weather solutions that emphasize eco-friendly positioning and high-performance use, appealing to customers willing to pay for formulation quality and targeted application formats. A Canadian aftermarket provider adds scale and breadth, distributing transportation chemicals and washer fluids across OEM and replacement channels, which gives it reach and flexibility in multiple geographies.
Asian participation is becoming increasingly important. A Japanese manufacturer is known for all-season and glass cleaner products that align with quality-conscious consumer expectations and detailed formulation work. A Chinese producer offers concentrated and ready-to-use formulations for export, reflecting the growing role of cost-efficient manufacturing and regional sourcing in global supply. In parallel, integrated energy and specialty fluid players supply washer fluid as part of wider lubricants and fluids portfolios, using existing relationships with service outlets and mobility customers to maintain distribution leverage.
Recent market activity illustrates how this landscape is evolving. In early 2025, a leading aftermarket provider announced a next-generation washer fluid targeting extreme temperatures with improved cleaning and anti-icing performance, signaling a push to defend premium shelf space and address the most seasonally sensitive demand. Later in the year, a specialist introduced a dedicated line for the Indian aftermarket focused on passenger vehicles with all-season performance, an example of regional customization in a fast-growing vehicle market. Around the same time, a major e-commerce platform expanded its automotive ecosystem by integrating washer fluid and related products into a broader car initiative, showing how digital distribution can reshape retail access and product bundling.
Strategic differentiation is tending toward one of three paths. The first is performance specialization, where companies target extreme cold, insect buildup, or streak-free clarity and build product narratives around those use cases. The second is compliance and sustainability leadership, where reformulation toward lower-toxicity ingredients and tighter VOC adherence becomes a market advantage, especially in regions where rules are strict and procurement standards are evolving. The third is channel and format innovation, using concentrates, tablets, bulk supply, and digital platform partnerships to improve margin economics, reduce packaging, and reach buyers where they increasingly shop. None of these paths is exclusive, but the strongest players tend to combine at least two, aligning product design with the channels and regulatory contexts where they operate.
PW Consulting
Future Trends and Commercial Implications
Over the next three to five years, one clear trend is the continued acceleration of cleaner, safer formulations. Ethanol-based and methanol-free entries are expected to grow in new launches, reflecting both regulatory pressure and shifting buyer expectations. This creates an opportunity for suppliers that can demonstrate performance parity or superiority at lower toxicity, particularly for fleets, retail chains, and OEM-linked service networks that must manage handling, storage, and disposal considerations alongside cleaning performance. Companies that treat formulation as a brand and compliance asset, rather than just a cost variable, are likely to gain an edge in specification conversations and shelf placement.
Worldwide Windshield Washer Nozzle Market
A second trend is the growing linkage between visibility and vehicle safety expectations. As safety rating and crash-avoidance frameworks place more emphasis on forward visibility and sensor cleanliness, washer fluids will be judged not only on how well they clean glass, but also on how reliably they support clear, residue-free viewing conditions. This creates commercial opportunities for fluids with stronger anti-smearing claims, better dirt-release properties, and compatibility with vehicle systems that depend on unobstructed sightlines. It also raises a caution: products that deliver short-term cleaning but leave residue or cause smearing may face increasing scrutiny in professional and premium segments.
A third trend concerns distribution and format evolution. Concentrates, dilution controls, tablets, and online automotive marketplaces are expanding the ways fluids reach end users. For manufacturers, this means better control over shipping weight and packaging costs, but also a need to manage consumer dilution behavior and ensure that performance remains consistent after mixing. For retailers and fleet buyers, the opportunity lies in simplifying inventory and reducing storage footprint while maintaining seasonal readiness. The risk is fragmentation: as formats multiply, channel confusion and mixing errors can erode trust unless instructions, labeling, and education are handled carefully.
There are also uncertain factors worth monitoring. Weather variability can shift seasonal purchasing patterns and make demand less predictable in some regions. Feedstock pricing and regional chemical availability can affect margins and formulation economics. Regulatory adoption may differ across jurisdictions, creating a patchwork of compliance obligations that complicates product rollout. Finally, consolidation pressure may intensify as larger players seek to secure shelf space, distribution agreements, and OEM-linked supply, while smaller specialists either niche down or scale through partnerships.
Actionable Recommendations for Decision-Makers
For manufacturers and brand owners, the priority is to treat formulation as a multi-dimensional asset. That means aligning product development with regional VOC requirements, building a credible performance story around cleaning, freeze protection, and residue control, and preparing a mix of ready-to-use and concentrated formats to suit different channels and cost structures. Launch timing matters too: seasonal demand spikes reward reliable supply and clear labeling, while regulatory changes reward early reformulation and testing. Companies should also assess where premiumization can be sustained versus where price competition will compress margins, and then allocate innovation spend accordingly.
For investors and strategic partners, the value lies in identifying businesses that combine compliance readiness, distribution strength, and formulation differentiation. Markets with a 4.9 percent growth trajectory through the end of the decade do not reward undifferentiated commodity positioning; they reward players that can hold shelf space, respond to regional regulation, and manage supply chain variability. Due diligence should examine formulation pipelines, regional compliance exposure, channel mix between aftermarket and OEM-related supply, and the ability to scale concentrates or eco-oriented variants without sacrificing performance. Portfolio alignment with visibility-linked safety expectations can also be a differentiating factor.
For procurement teams and fleet operators, the practical focus should be on standardization, safety, and total cost rather than lowest unit price alone. Standardizing on fluids that meet regional compliance requirements and perform across seasons can reduce SKU complexity, storage risk, and off-spec cleaning issues. Concentrated options may lower logistics and storage costs, but they require disciplined dilution practices and clear staff training. Where advanced visibility expectations matter, procurement should prioritize products with demonstrable anti-smearing and residue-control performance, especially for vehicles where clean windshields and sensor visibility support operational safety.
Worldwide Heated Wiper Fluid Market
As the market matures, the competitive edge will increasingly depend on localized formulation intelligence, regulatory foresight, and channel-specific product architecture. Readers looking for deeper segmentation data, regional deployment patterns, and tailored commercial scenarios can explore the full research report for a more detailed view of subsegments, regional dynamics, and company-level positioning.
For detailed analysis of this topic, please visit the official page: Automotive Windshield Washer Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Real Time Clock Market: Why 6.8% CAGR and Segment Shifts Redefine Growth to 2032
By pmarketresearch, 2026-09-21
Navigating the Real Time Clock Market: Strategic Shifts and Commercial Opportunities in a Precision-Driven Era
Executive Overview
The Real Time Clock (RTC) market has matured beyond its legacy role as a simple timekeeping component into a critical enabler of precision, reliability, and power efficiency across connected systems. As embedded architectures grow more complex and real-time synchronization demands intensify across automotive, industrial, and consumer applications, the strategic value of RTC solutions has never been more pronounced. Market trajectories indicate sustained expansion, supported by evolving design requirements, supply chain realignment, and the push toward lower power consumption without sacrificing accuracy. Understanding where the market is headed requires moving past surface-level sizing and examining the underlying forces reshaping product roadmaps, competitive positioning, and procurement strategies.
Market Landscape and Pressing Challenges
The global RTC market has demonstrated steady growth over the recent historical period, with revenue expanding from approximately 1.65 billion USD in 2020 to an estimated 2.10 billion USD by 2025. Forward projections point to continued momentum through the forecast horizon, with the market expected to approach 3.30 billion USD by 2032, reflecting a compound annual growth rate of 6.8 percent. This trajectory underscores a market that is neither stagnant nor purely cyclical, but one shaped by incremental technological advancement and broadening application footprints.
Despite the positive growth outlook, the sector faces several structural challenges that decision-makers must navigate carefully. First, the transition from discrete timing components to tightly integrated, low-power RTC solutions is raising design complexity and qualification barriers. Engineers are increasingly required to balance accuracy, power draw, package constraints, and environmental tolerance, which slows adoption cycles and intensifies validation workloads. Second, product lifecycle management has become a focal point of risk. Recent end-of-life announcements from select suppliers have highlighted the fragility of legacy timing portfolios, forcing customers to plan migration paths without disrupting long-lifecycle deployments in industrial and automotive settings. Third, the competitive environment remains moderately fragmented, with the top three players holding roughly 28.5 percent of market share and the top five accounting for approximately 42.0 percent. This concentration leaves room for specialization, but it also means that pricing power and differentiation are increasingly tied to application expertise, qualification depth, and integration capabilities rather than volume alone.
Design Complexity Versus Power and Accuracy Trade-Offs
As device architectures push toward ultra-low-power operation, RTC solutions must maintain stable timekeeping across wide temperature ranges and extended battery-backup scenarios. Achieving this balance often requires tighter integration between the oscillator, compensation logic, and interface architecture. For product teams, this means that RTC selection is no longer a commodity decision; it directly influences system reliability, firmware complexity, and overall bill of materials.
Lifecycle Continuity and Migration Risk
The recent EOL notifications from a notable RTC supplier illustrate how portfolio rationalization can ripple through downstream design cycles. Customers with multi-year product lifecycles must evaluate re-qualification timelines, alternative part compatibility, and the risk of obsolescence in safety-critical or regulated deployments. This is especially relevant for industrial equipment, smart infrastructure, and automotive subsystems where redesign windows are narrow and validation costs are high.
Fragmented Share and the Search for Differentiable Value
A moderately concentrated market structure creates two simultaneous dynamics. On one hand, it allows specialized players to capture value by targeting high-precision, temperature-compensated, or automotive-qualified niches. On the other hand, it pressures larger suppliers to defend share through broad portfolios, ecosystem support, and long-term availability commitments. Companies that cannot articulate a clear application-specific advantage may find themselves competing primarily on price rather than technical merit.
Atomic Clock Market
Core Drivers Reshaping the Market
Several interconnected forces are accelerating demand and redefining how RTC solutions are specified, sourced, and integrated. These drivers span technology, regulation, demand behavior, and supply chain dynamics, and they collectively shape the commercial opportunity set.
Ultra-Low-Power CMOS Design and Precision Integration
One of the strongest technical catalysts is the ongoing refinement of ultra-low-power RTC ICs that combine automatic battery switching, programmable clock outputs, and interrupt-driven calendar functions. These features are particularly relevant for embedded systems, IoT endpoints, and automotive modules that must preserve timekeeping integrity during power loss or sleep states. At the same time, temperature-compensated and integrated-crystal approaches are gaining traction where accuracy cannot be compromised across operating environments. The result is a shift from simple clock generation to smarter timing ICs that reduce system-level burden and enable more deterministic behavior in connected products.
Application-Level Demand and Real-Time Synchronization Requirements
Demand is being pulled by end-use environments where timing precision has direct operational consequences. In industrial automation and smart metering, reliable timekeeping supports logging, synchronization, and event sequencing. In automotive platforms, RTC functions contribute to diagnostics, firmware state management, and system recovery logic. In consumer electronics, compact RTC modules help balance low power draw with dependable calendar and alarm functions. The common thread is that RTCs are increasingly evaluated as part of a broader timing strategy rather than as standalone components, which raises the importance of interface compatibility, event handling, and power management integration.
Lifecycle Planning, Portfolio Pruning, and Supply Continuity
Regulatory expectations and long product lifecycles in certain verticals are placing greater emphasis on continuity planning. As suppliers prune legacy lines, customers are forced to assess second-source options, migration feasibility, and qualification overhead. This dynamic is reshaping procurement behavior: buyers are prioritizing suppliers that can demonstrate clear transition roadmaps, broad qualification coverage, and transparent availability signals. In practice, this creates an opening for suppliers that can combine precision, programmability, and lifecycle support without forcing customers into costly redesigns.
Competitive Realignment and Assets Consolidation
The timing ecosystem is undergoing consolidation pressure as companies seek to strengthen portfolios and capture adjacent capability. Recent acquisition activity involving RTC-related timing assets reflects a strategic push to consolidate precision timing know-how and expand product coverage across industrial, communications, and embedded computing applications. For the broader market, consolidation can improve portfolio coherence and accelerate innovation, but it can also alter availability patterns, support structures, and competitive dynamics in specific niches. Buyers and investors alike should watch how these moves change qualification breadth, regional support, and the pace of new product introductions.
Competitive Landscape and Leading Strategies
The RTC market features a mix of semiconductor incumbents, timing specialists, and module-oriented providers, each leaning into different value propositions. The strategic positioning of the leading companies reflects a broader tension between breadth, specialization, and integration depth.
Strategic Positioning Across the Leader Set
NXP Semiconductors emphasizes ultra-low-power CMOS RTC ICs with automatic battery switching, programmable clock outputs, and interrupt features designed for low-power calendars in embedded, automotive, and IoT environments. This positions the company around power-aware timekeeping and firmware-friendly interrupt structures, which matters for designs that must minimize active current while preserving reliable calendar behavior. Microchip Technology focuses on RTCs with integrated oscillators and I2C interfaces for precision timekeeping in industrial, automotive, and consumer electronics. The emphasis on interface simplicity and integrated oscillation supports designers seeking predictable integration and broad applicability across multiple verticals. Texas Instruments positions its timing solutions around RTC ICs for real-time applications in industrial controls, automotive systems, and power management, aligning with customers that value robust timing within broader control and power architectures.
STMicroelectronics highlights RTC and timing devices for energy-efficient timekeeping in smart meters, IoT, and industrial sensors, targeting applications where power efficiency and long-term stability are critical. Epson Electronics offers RTC module families with integrated crystals for high-precision, low-power calendars in industrial and commercial settings, appealing to customers that prefer module-level simplicity and proven accuracy. Diodes Incorporated brings temperature-compensated RTC modules with integrated crystals to the table, optimizing for accuracy under wide temperature ranges in networking and embedded systems—an advantage where environmental variability is a core concern. Abracon LLC focuses on RTCs with embedded crystals, AEC-Q200 qualification, alarm support, leap year handling, and ultra-low power in compact SMD packages, which aligns well with automotive-grade and space-constrained designs. SiTime Corporation emphasizes precision timing products including ultra-low-power RTCs with dual I2C bus support for applications in AI, communications, and embedded computing, signaling a push toward higher-performance timing in compute-intensive and interface-sensitive environments.
Differentiation Through Integration, Qualification, and Application Fit
Across the leader set, differentiation is increasingly tied to three dimensions. The first is integration depth: RTCs that combine oscillator functions, compensation mechanisms, and interface flexibility reduce design friction and improve system determinism. The second is qualification and environmental robustness, especially where automotive-grade or wide-temperature performance is required. The third is application alignment: suppliers that articulate clear value for smart metering, industrial sensing, automotive subsystems, or low-power IoT are better positioned to command preference over generic timing parts. Companies that can demonstrate all three tend to win design-ins in complex deployments where downtime, rework, or re-qualification carries high cost.
Worldwide MEMS Real-Time Clock Market
Where the Landscape Is Heading
The competitive picture is likely to evolve through a combination of consolidation and specialization. Consolidation may reduce the number of independent timing asset holders, particularly where acquisition activity broadens portfolio coverage or strengthens precision capabilities. At the same time, specialization is likely to persist in high-accuracy, temperature-compensated, and automotive-qualified segments, where technical barriers and qualification requirements protect niche leadership. New entrants and smaller specialists may continue to compete by targeting compact packages, ultra-low-power profiles, or application-specific features such as alarm handling, leap year support, and programmable outputs. The practical implication is that customers should not assume a one-size-fits-all sourcing strategy; the optimal partner depends on whether the priority is integration simplicity, environmental robustness, lifecycle continuity, or application-specific feature sets.
Forward Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, the RTC market is poised to be shaped by a handful of clear trends that connect directly to commercial opportunity.
Trend 1: Timing Becomes More System-Critical, Not Less
As connected systems scale and real-time coordination becomes more important, RTC functions will be evaluated less as passive components and more as integral parts of timing integrity strategies. Designs will increasingly demand tighter integration, predictable power behavior, and interface support that aligns with broader system architectures. This raises the value of RTC solutions that simplify firmware logic, reduce active power, and support event-driven calendars. For suppliers, this trend favors products that address system-level pain points rather than clock output alone.
Trend 2: Precision and Environmental Resilience Will Command Premium Positioning
Wide temperature ranges, long battery-backup intervals, and stable accuracy under varying conditions will remain key procurement criteria in automotive, industrial, and infrastructure applications. Temperature-compensated modules and integrated-crystal families are likely to see continued interest where accuracy cannot be sacrificed. The commercial opportunity here lies in segments where reliability translates directly into operational uptime, safety, or compliance, and where buyers are willing to pay for validated performance rather than lowest unit cost.
Trend 3: Lifecycle Strategy and Portfolio Continuity Will Influence Sourcing Decisions
With EOL announcements already prompting migration planning in select product lines, long-lifecycle customers will place greater weight on supplier roadmaps, transition support, and qualification continuity. This will favor suppliers that can provide clear availability signals and well-supported migration paths, especially for industrial and automotive projects with extended deployment horizons. For investors and manufacturers, this dynamic suggests that portfolio stability and lifecycle management are becoming competitive differentiators alongside technical performance.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market growth. Recurrence of portfolio pruning or EOL decisions could disrupt migration timelines for customers with limited second-source options. Consolidation activity may reshape support models and product availability, particularly if acquired assets are integrated unevenly across regions or application lines. In addition, shifts in automotive demand cycles, consumer electronics refresh patterns, and industrial capital spending could create uneven demand across segments, making precise forecasting more reliant on application-level intelligence than broad market aggregates.
PW Consulting
Strategic Actions for Decision-Makers
Given the interplay of precision requirements, lifecycle risk, and competitive realignment, decision-makers should approach the RTC market with a clear, application-aware strategy.
For Manufacturers and Product Teams
- Treat RTC selection as a system-level decision. Prioritize parts that combine low-power behavior, programmable outputs, and interface compatibility with your broader architecture to reduce firmware complexity and validation effort.
- Build migration readiness into design planning. Where long-lifecycle deployments are involved, assess second-source options and qualification continuity early to reduce exposure to portfolio changes or EOL transitions.
- Match qualification depth to application criticality. For automotive, industrial, or temperature-stressed environments, favor solutions with relevant qualification coverage and environmental performance rather than defaulting to the broadest catalog choice.
For Investors and Strategic Planners
- Focus on value capture in segments where precision, integration, and qualification create defensible differentiation. The most resilient opportunities are likely to be in application-specific timing support rather than commoditized volume alone.
- Monitor consolidation signals and their impact on portfolio coherence, support coverage, and innovation cadence. Acquisition activity can strengthen capability, but it also changes the competitive map and availability dynamics.
- Track demand nuance across end-use verticals. Automotive, industrial, and consumer electronics do not move in lockstep, and commercial outcomes will depend on how well stakeholders anticipate segment-specific refresh cycles and qualification requirements.
For Procurement and Supply Chain Leaders
- Strengthen continuity planning through transparent transition roadmaps. Where possible, work with suppliers that provide clear guidance on lifecycle status, migration assistance, and long-term availability.
- Balance cost efficiency with technical fit. In precision-sensitive or safety-relevant deployments, total cost of ownership should account for validation effort, environmental performance, and risk of redesign if migration becomes necessary.
- Use application-specific requirements as sourcing filters. Alarm support, leap year handling, dual-bus interfaces, and temperature-compensated accuracy should be evaluated against actual system needs to avoid over-engineering or under-specifying the timing chain.
The RTC market is entering a phase where technical performance, lifecycle stability, and application fit matter as much as scale. For organizations that need deeper granularity on regional dynamics, type-level splits, application-specific revenue trajectories, and tailored sourcing or investment recommendations, a more detailed research deep-dive is available. Readers seeking segment-level data, company-specific positioning, and customized market pathways can access the full research report for comprehensive breakdowns and decision-ready analysis.
For detailed analysis of this topic, please visit the official page: Real Time Clock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Residential Air Purifiers Market Set for 7.5% CAGR Growth Through 2032 Strategic Shifts
By pmarketresearch, 2026-09-21
Residential Air Purifiers Market: Strategic Trends and Commercial Opportunities in a Maturing Sector
The residential air purifiers market has transitioned from a niche wellness accessory to a mainstream household essential, driven by escalating awareness of indoor air quality, urbanization pressures, and technological maturation. Valued at approximately $12.06 billion in 2025, the market has expanded at a compound annual growth rate of roughly 7.5 percent from 2020 through the forecast horizon extending to 2032, when projected revenues are expected to approach $20.02 billion. This trajectory reflects more than incremental consumer adoption; it signals a structural shift in how households, builders, and health-conscious buyers perceive the value of controlled indoor environments. For executives and investors, the opportunity lies not merely in capturing volume growth, but in navigating a sector where differentiation, regulatory alignment, and ecosystem integration increasingly dictate competitive advantage.
Market Landscape and Critical Inflection Points
Scale, Growth Trajectory, and Hidden Tensions
The market’s expansion has been steady rather than explosive, with annual revenue climbing from $8.29 billion in 2020 to $12.06 billion in 2025. The projected path to $20.02 billion by 2032 implies sustained demand, but the growth composition reveals underlying tensions. Portable units dominate volume, reflecting consumer preference for flexible, point-of-use solutions that require minimal installation and allow room-by-room deployment. Fixed in-duct systems occupy a smaller share, constrained by retrofit complexity, builder-dependent distribution, and higher upfront capital requirements. On the technology side, HEPA-based filtration remains the anchor of consumer trust and regulatory compliance, while activated carbon and ionic alternatives serve niche performance or odor-focused applications. The presence of a substantial "other" technology category indicates ongoing experimentation with hybrid, photocatalytic, and advanced media approaches, though none have yet displaced the HEPA benchmark at scale.
Air Purifiers Market
Market concentration remains pronounced, with the top three players accounting for roughly 65 percent of revenue and the top five capturing approximately 75 percent. This structure points to established brand equity, channel control, and economies of scale that create meaningful barriers for late entrants. Yet high concentration does not equate to stagnation. The concentration is increasingly contested at the edges by brands that leverage smart connectivity, targeted use-case positioning, and direct-to-consumer channels to carve out defensible niches.
Three Pressing Challenges Shaping the Next Cycle
First, product performance validation and consumer trust are under renewed scrutiny. Recent regulatory and safety actions, including a major recall of certain air purifier units due to fire and burn hazards, underscore that performance claims must be matched by rigorous quality control, transparent testing, and post-market monitoring. Brands that rely on marketing-led positioning without robust engineering validation face growing exposure as consumer literacy and regulator attention rise.
Second, energy efficiency and compliance are becoming structural cost and design constraints. Regulatory frameworks across major markets are tightening, with new conservation standards phasing in and harmonized efficiency expectations spanning North America. These requirements compress the design space for airflow, noise, and power consumption, forcing manufacturers to balance filtration effectiveness with operating cost and user experience. The companies that treat compliance as a design parameter rather than a late-stage checkbox will secure lower total-cost-of-ownership profiles and smoother market access.
Third, the category is experiencing segmentation fatigue and value confusion. Consumers are confronted with overlapping claims around HEPA grades, carbon capacity, ion generation, sensor accuracy, and app integration. This proliferation complicates purchase decisions, elevates return rates when expectations misalign with real-world performance, and pressures margins as brands compete on features that may not translate into meaningful differentiation. The challenge for incumbents and challengers alike is to simplify value communication while still delivering measurable performance gains.
Core Drivers Reshaping Demand and Competitive Dynamics
Technology Innovation as a Performance and Experience Lever
The most consequential technological shift is the convergence of high-efficiency filtration with real-time sensing and controlled delivery. HEPA remains foundational, but the next layer of value is being added through formaldehyde and VOC sensing, particulate monitoring, adaptive fan control, and connectivity that enables usage tracking and filter lifecycle management. Recent product launches illustrate this direction: new plug-and-play models with dedicated app connectivity are reducing installation friction while expanding the sensor-and-control layer, and award-recognized designs are targeting previously underserved use cases such as pet hair and dander management. These innovations do not merely add features; they change the value proposition from static cleaning to managed air quality over time, which opens recurring revenue possibilities through filter subscriptions, service dashboards, and performance guarantees.
Household Air Purifiers Market
Regulatory and Standards Environment: From Gatekeeper to Differentiator
Regulatory dynamics are transitioning from passive compliance to active strategic planning. Energy conservation standards are escalating in tiers, with later-phase requirements effective at the end of 2025 and harmonized proposals extending similar expectations to products manufactured in Canada from the same timeframe. In parallel, certification and indoor air cleaning device requirements in certain states have long influenced product eligibility, reinforcing the importance of third-party validation and transparent performance data. The strategic implication is clear: energy efficiency, safety, and certified performance are no longer optional add-ons; they are preconditions for distribution, retailer confidence, and consumer trust. Firms that embed these requirements into product architecture early gain speed to market, lower rework risk, and stronger positioning with procurement teams and channel partners.
Demand-Side Shifts Toward Health, Pet Care, and Smart Homes
Consumer behavior is increasingly shaped by health sensitivity, pet ownership growth, and the broader smart home ecosystem. Households are treating indoor air quality as part of a proactive wellness routine rather than a reactive response to visible pollution. This shift favors products that offer intuitive interfaces, automated operation, and perceptible performance feedback, because users are more likely to sustain usage when they can see and understand the outcome. Pet-focused designs have emerged as a distinct demand pocket, reflecting the need for hair capture, odor reduction, and quiet continuous operation in living spaces. Simultaneously, integration with home automation platforms appeals to buyers who value centralized control and data continuity, pushing manufacturers to think beyond the appliance as an isolated device and toward its role in a connected environment.
Supply Chain and Cost Structures: Balancing Performance and Affordability
Cost pressure remains a persistent factor, especially as multi-stage filtration, sensors, and connectivity components raise bill-of-materials complexity. The market’s breadth—from value-oriented core series to premium high-capacity systems—demonstrates that segmentation is partly a response to these economics. Manufacturers are navigating a trade-off between filtration depth and price accessibility, while also managing component availability, filter replacement economics, and warranty exposure. The strategic response is increasingly modular: standardize core filtration and airflow architectures, then layer targeted features, sensor packages, and brand-specific design language to serve distinct price points without fragmenting production efficiency. This approach helps preserve margin while allowing brands to address multiple consumer segments from a shared engineering base.
Competitive Landscape and Strategic Positioning
Incumbents Anchored in Filtration Credibility and Ecosystem Reach
Honeywell International Inc. continues to leverage its home comfort heritage, pairing HEPA filtration with smart air quality sensors to position its residential offerings within the broader comfort and ventilation narrative. This framing connects air purification to a familiar household category and benefits from an established brand footprint and cross-selling pathways. IQAir North America, Inc. pursues a premium angle, emphasizing HEPA and activated carbon systems with app connectivity, an approach that targets performance-sensitive buyers willing to pay for perceived filtration superiority and connected control. LG Electronics, Inc. differentiates through intelligent room air purifiers that combine HEPA with UV-C technologies, aligning purification with broader appliance intelligence and design language familiar to its consumer base. Panasonic Corporation emphasizes advanced cleaning systems built around nanoe and HEPA mechanisms, a positioning that highlights proprietary ionization-adjacent technologies alongside conventional filtration. Sharp Corporation competes with plasmacluster ion-based purifiers, offering an alternative performance narrative that appeals to buyers interested in active particle control beyond mechanical capture.
Specialists, Challengers, and Use-Case Focused Entrants
Dyson Ltd. has built a strong presence through HEPA H13 filtration paired with formaldehyde-sensing technologies, combining rigorous filtration claims with a design-forward, technology-rich identity that resonates in higher-income segments. Coway Co., Ltd. has gained traction with its Airmega series, emphasizing advanced multi-stage filtration for home use and a track record of performance-oriented marketing. Winix Inc. focuses on multi-stage filtration air purifiers, targeting value-conscious buyers who still want layered contaminant capture. Austin Air Systems and RabbitAir occupy higher-capacity and multi-layer niches, appealing to consumers seeking robust filtration volume or specialized coverage, with messaging that appeals to dedicated indoor air quality advocates. Levoit has expanded recognition through core and vital series that integrate smart features, demonstrating how accessible price points can coexist with connected functionality and broad retail distribution. AirDoctor and Molekule both emphasize HEPA-based smart air cleaning, though with distinct brand narratives and feature sets that illustrate how even closely positioned products can pursue separate audience segments. Blueair brings a design-centric, Swedish-engineered filtration identity that supports a premium-but-accessible positioning in selected markets. At the more specialized end, Dreame Technology has targeted pet hair removal with its Furcatch series, and its recognition with a CES 2026 innovation award in the home appliances category signals how use-case focus and design innovation can accelerate visibility in a crowded field.
PW Consulting
How the Landscape Is Evolving
The market is not simply consolidating around a few giants; it is simultaneously consolidating at the top and fragmenting at the edges. The leaders defend share through brand trust, channel relationships, and scale-efficient filtration platforms. The challengers and specialists attack with sharp use-case positioning, smart features, and direct engagement with consumer communities that value specific outcomes such as pet management, quiet operation, design compatibility, or app-driven control. This dual dynamic means that market share battles are increasingly won in segments rather than across the category as a whole. New entrants can succeed without dislodging incumbents broadly if they solve a well-defined problem better than the generalist alternatives and build credible validation around that claim. At the same time, the bar for entry is rising because energy, safety, and certification expectations now touch every price tier, and recall risk or performance overstatement can quickly erode consumer confidence.
Forward Outlook: Three Trends Defining the 2026–2030 Window
Trend One: Managed Air Quality Over Standalone Cleaning
The next phase will increasingly reward products that function as managed systems rather than one-time purchases. Sensor accuracy, adaptive operation, filter lifecycle visibility, and app-based feedback will become baseline expectations in many markets, especially as smart home penetration deepens. For commercial strategy, this trend shifts competition toward reliability of measurement, clarity of user communication, and the ability to sustain engagement across the product lifecycle. Recurring value can be built through subscription filter programs, maintenance reminders, and performance summaries, provided these services are tied to genuine user benefit rather than feature bloat.
Trend Two: Compliance-Driven Engineering as a Competitive Moat
As efficiency and safety requirements phase in, only products designed around these constraints from the outset will maintain competitive cost structures and broad market access. The moat will belong to manufacturers that can deliver high filtration performance without exceeding power, noise, and thermal limits, and that can document compliance in ways that streamline retailer and regulatory acceptance. This creates an advantage for engineering-led organizations with disciplined validation processes and for brands that can translate compliance into consumer-facing value, such as lower operating cost, quieter operation, and credible performance certification.
Trend Three: Use-Case Specialization as a Path to Growth With Manageable Risk
Generalized claims are losing persuasiveness in a crowded market, while targeted solutions are gaining traction because they reduce purchase ambiguity and improve perceived relevance. Pet-focused designs, allergy-oriented configurations, and room-specific form factors are likely to remain productive growth avenues, especially when paired with credible testing and clear benefit communication. The risk in this approach is over-narrow positioning that limits scale potential or duplication of features that consumers do not value enough to pay for. Successful specialization will balance a defined primary use case with enough multi-function flexibility to justify the purchase in varied household environments.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
- Treat energy, safety, and certification requirements as core design inputs rather than end-of-cycle compliance tasks, so that efficiency, noise, and thermal performance are optimized alongside filtration depth.
- Build modular platforms that separate the filtration and airflow core from sensor, app, and aesthetic differentiation layers, enabling multiple price points and use-case variants without compounding engineering overhead.
- Strengthen validation and transparency around performance claims, including real-world usage scenarios and filter replacement economics, to reduce returns, protect brand trust, and support premium positioning where justified.
For Investors and Strategic Capital Allocators
- Favor companies that demonstrate repeatable engineering discipline in meeting evolving efficiency and safety standards, because these firms face lower rework risk and smoother access to regulated channels.
- Assess the durability of differentiation beyond marketing claims, looking for credible testing, defensible sensor and filtration architectures, and evidence that smart features increase retention or lifetime value rather than merely inflating initial price.
- Watch for consolidation opportunities where specialized brands with strong use-case loyalty can be integrated into broader platforms, or where incumbents can acquire targeted capabilities in connectivity, validation, or niche performance segments.
For Procurement, Channel, and Retail Decision Makers
- Prioritize products with clear certification status, documented efficiency performance, and transparent filter replacement costs, since total cost of ownership and post-purchase support increasingly influence consumer satisfaction and repeat purchase behavior.
- Evaluate category assortment by use case and price tier rather than by brand alone, ensuring that pet-focused, allergy-oriented, and smart-integrated options are positioned where shoppers can compare them against relevant alternatives.
- Track safety and recall signals actively, and align vendor selection with brands that demonstrate robust quality systems, because trust in this category is fragile and can shift quickly when performance or safety concerns surface.
The residential air purifiers market is moving into a phase where growth is real but discriminating. Scale alone will not secure advantage; the winners will be those who combine credible filtration performance with aligned efficiency and safety profiles, clear use-case relevance, and smart functionality that sustains user engagement. For executives and investors, the highest-value intelligence lies in segment-level demand nuances, platform economics, regulatory timing, and the specific validation standards shaping procurement decisions. The full research report expands on these themes with detailed segmentation data, regional dynamics, and customized strategic scenarios to support planning with greater precision.
For detailed analysis of this topic, please visit the official page: Residential Air Purifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Power Tool Accessories Market
Market Overview and Structural Challenges
Market Trajectory and Core Dynamics
The power tool accessories market has demonstrated consistent expansion over the past five years, transitioning from a mature, replacement-driven segment to a growth market influenced by tool electrification, application specialization, and tightened performance expectations. Total market revenue rose from approximately 161.5 million USD in 2020 to roughly 202.5 million USD in 2025, and forward projections indicate a continued upward path toward just under 300 million USD by 2032, reflecting a compound annual growth rate of 5.8 percent across the forecast window. This trajectory signals a market that is no longer solely dependent on consumables replacement cycles. Instead, the growth is increasingly shaped by accessory innovation, platform compatibility requirements, and the expansion of professional and semi-professional user bases that prioritize durability, precision, and productivity gains.
The segment has also developed clear concentration patterns that influence pricing power, innovation pacing, and channel relationships. A relatively small group of leading players commands a disproportionate share of revenue, which creates both stability and pressure for the remainder of the competitive field. High concentration tends to reward companies with strong brand equity, broad accessory portfolios, and reliable distribution networks, while making it harder for narrower players to compete on visibility alone. For decision-makers, this concentration means that strategic differentiation must come from features, materials, compatibility ecosystems, or service models rather than simple market entry.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the industry faces several structural challenges that are reshaping how manufacturers and buyers think about accessories. One of the most pressing issues is the balance between performance and cost pressures. Accessory buyers increasingly expect longer service life, better cutting efficiency, and reduced tool vibration, yet raw material volatility and processing complexity can make premium formulations difficult to scale profitably. Companies that rely on traditional materials or legacy geometries are seeing margin compression as users become more selective and price-sensitive, particularly in price-conscious channels. This creates a tension where performance upgrades must be justified through measurable productivity improvements rather than incremental claims.
A second challenge is the growing complexity of compatibility and platform lock-in. As cordless tool platforms continue to expand, accessory design must account for torque profiles, battery ecosystems, shank specifications, and interface variations. Accessories that are not optimized for the tool’s operating conditions can reduce performance or create safety concerns. This complexity benefits large platforms with broad accessory ranges, but it also raises the stakes for smaller manufacturers that need to ensure fit, performance, and reliability across multiple tool models. The result is a market where technical coordination between tools and accessories is becoming as important as the accessory product itself.
A third inflection point is regulatory and safety standardization. Industry associations and certification bodies have been tightening expectations around performance consistency, durability, and safe usage under demanding conditions. These developments help protect end users and strengthen confidence in professional-grade accessories, but they also raise compliance costs and can slow time-to-market for new designs. Manufacturers that treat safety and certification as a strategic capability rather than a back-office requirement are better positioned to operate in regulated channels, especially where institutional buyers, rental fleets, or industrial customers require documented performance assurance.
Taken together, these challenges suggest that the market is entering a phase where growth will be earned through technical relevance and trust. The companies that can align material efficiency, platform compatibility, and compliance readiness with user-facing performance benefits are likely to capture a larger share of the expanding market, while those that compete only on generic specifications may face margin erosion and substitution pressure.
Core Drivers Shaping Market Change
Technology Innovation and Material Advancement
Material engineering and design optimization remain central to competitive advantage in power tool accessories. Improvements in carbide formulations, hardened steel treatments, coatings, and tooth geometry are enabling accessories to cut faster, last longer, and maintain accuracy over more operations. In practical terms, these gains matter because they reduce downtime, lower the frequency of replacement, and improve finishing quality. For professional users, that translates into measurable productivity rather than just product attributes. Innovation is also moving beyond raw hardness toward application-specific performance, with designs tailored to particular materials, cut styles, drilling conditions, or tool interfaces.
A notable example of how material strategy is evolving comes from the broader industry’s focus on cost and sustainability. One leading manufacturer has pursued recycling of hard metal tips recovered from grinding waste in order to lower raw material costs for accessories, illustrating how material recovery can support both economics and supply continuity. This approach highlights a broader trend: high-performance accessories are increasingly dependent on managing input costs and material availability as carefully as they are dependent on design quality. Companies that integrate material recovery, waste reduction, or alternative sourcing into their development processes may be able to sustain premium positioning while protecting margins.
Power Tools Market
Policy, Safety, and Certification Environment
Regulatory and industry-led standards are becoming a more visible force in the accessories market. Updated safety guidelines for power tool accessories have been issued by industry bodies, reinforcing expectations around consistency, safe operation, and performance validation. Alongside this, certification and testing organizations continue to evaluate accessories for safety, durability, and reliability, and trade associations are maintaining member compliance expectations for manufacturers. This framework is not simply procedural. In professional and institutional procurement, documented compliance can be a prerequisite for inclusion in bids, rental fleets, or job-site supply programs.
For companies, the implication is that standards are increasingly part of the value proposition. Accessory designs that are developed with clear testing pathways and compliance documentation can gain advantage in channels where risk management and accountability are prioritized. Conversely, products that are launched without adequate attention to certification or performance validation may face slower adoption in professional environments. The trend also rewards manufacturers who can communicate standardized performance clearly, because procurement teams and field supervisors often need evidence that an accessory meets the demands of heavy or repetitive use.
Demand-Side Shifts in User Behavior
The demand profile for power tool accessories is being reshaped by the continued shift toward cordless tool platforms and the expansion of user groups beyond traditional trades. Cordless adoption has broadened access to mobile, on-site work and has increased the importance of accessories that perform reliably under variable conditions. At the same time, users are becoming more discerning about fit and productivity. Drill-related applications remain especially significant in the broader usage landscape, reflecting the foundational role of drilling in construction, assembly, maintenance, and renovation activity. Miter saw applications and reciprocating saw setups also represent meaningful demand centers, and the accessory requirements in these applications often emphasize precision, controlled cutting, and blade life.
Another demand-side shift is the growing expectation that accessories support efficiency rather than merely perform a function. Users want accessories that help reduce rework, improve consistency, and minimize interruption. This is particularly relevant where time pressure, labor costs, and project schedules are high. As a result, marketing and product development are increasingly judged by real-world outcomes such as cleaner cuts, longer intervals between changes, less tool load, and easier blade or bit changes. Buyers are also more attentive to whether accessories are designed for specific tool platforms, since mismatched accessories can lead to reduced performance or premature wear.
Supply Chain and Cost Structure Pressures
Cost structures in the accessories market are being influenced by raw material availability, manufacturing complexity, and the need to scale performance improvements without sacrificing margin. The emphasis on hard metals, specialized steel, and engineered coatings means that supply disruptions or price swings can affect both cost and product consistency. In response, some companies are focusing on process efficiency, material recovery, and portfolio rationalization to keep production economically viable while preserving performance. This is not just a short-term cost issue; it is becoming an important strategic capability.
Supply chain stability also affects innovation speed. Companies that can develop, test, and launch accessory products efficiently are better positioned to respond to changing application needs and platform expansions. The most effective players tend to balance a core range of high-volume accessories with targeted specialty products that serve higher-value applications. That combination helps smooth demand cycles while still capturing premium segments where users are willing to pay for reliability and performance. For market participants, the operational goal is to link material strategy, manufacturing scale, and product differentiation in a way that supports both volume and value.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The market is shaped by a group of well-established manufacturers that compete through brand strength, product breadth, platform integration, and professional-grade positioning. Bosch Power Tools offers a broad range of cordless and corded tools and accessories, including drill bits, hole saws, saw blades, and fasteners aimed at professional trades. Its scale and platform reach give it the ability to align accessories closely with tool ecosystems and to introduce new products in coordinated waves. In June 2026, the company expanded its North American offering with 39 new tools and accessories designed to extend its 18V cordless platform, an example of how accessory portfolios can be used to reinforce a tool system strategy and deepen user commitment.
Stanley Black & Decker competes through its tools portfolio, offering accessories such as drill bits, saw blades, and impact driver bits under established brands. Its strength lies in a wide consumer and professional presence, which supports visibility across multiple channels and price points. Makita Corporation has built a strong identity around cordless power tools with dedicated accessories, including drill bits, hole saws, and abrasive products. This focus on system coherence helps the company emphasize compatibility and reliability in cordless workflows. Techtronic Industries, through its branded portfolio, supplies accessories for professional and consumer segments, with offerings spanning drill bits, saw blades, and hole saws. Its multi-brand structure allows it to address different customer segments while leveraging shared development and supply capabilities.
Hilti Corporation remains strongly associated with professional-grade accessories for fasteners, drilling, and demolition applications. Its positioning is particularly relevant in demanding job-site environments where performance, support, and reliability are critical purchase criteria. Apex Tool Group and Snap-on Incorporated both maintain strong professional orientation, with Snap-on especially focused on industrial and automotive applications through bits and sockets. These companies illustrate how professional trust, application specificity, and service support can be just as important as product specifications.
PW Consulting Health Care Research Center
A different competitive angle is visible in companies that emphasize reusable or recyclable accessory design. EAB Tool Company, for example, produces exchangeable and recyclable accessories such as circular saw blades, oscillating tool accessories, hole saws, and drill bits. This approach appeals to users and organizations seeking to reduce waste and manage consumable costs over time. Lenox, Diablo Tools, and related suppliers similarly focus on high-performance cutting and drilling accessories, often with an emphasis on carbide-tipped construction and application-specific performance. Together, these players show that differentiation is increasingly built around material performance, application fit, and lifecycle economics rather than brand alone.
Market Evolution and Consolidation Dynamics
The competitive structure is evolving along a path that rewards scale, portfolio breadth, and technical integration, while also creating room for specialized entrants that solve a narrow problem exceptionally well. Large players benefit from the ability to invest in multiple accessory categories, align products with tool platforms, and supply both professional and broader user markets. Their advantage is not simply size; it is the capacity to offer a coordinated accessory ecosystem that reduces compatibility risk for buyers and supports repeat purchasing across tool lines.
At the same time, market concentration tends to encourage strategic consolidation and selective partnership activity. Smaller manufacturers may find growth easier by focusing on high-performance niches, unique materials, or application-specific designs rather than trying to match full-portfolio breadth. New entrants that can bring a compelling technical advantage, stronger sustainability characteristics, or better cost-quality balance may gain traction in specific channels, especially where existing offerings are perceived as incremental. However, entering the market successfully increasingly requires serious attention to compliance, testing, and platform compatibility, since these are now central to professional adoption.
A broader trend is the growing importance of brand trust in safety-critical and high-use environments. In rental, industrial, and trade contexts, buyers often prefer accessories from manufacturers with established reputations for consistency and support. This does not eliminate competition, but it does raise the threshold for credible market participation. Companies that can demonstrate dependable performance, clear documentation, and alignment with recognized standards are better positioned to secure durable demand, while those that compete primarily on short-term price may find it harder to build recurring relationships in professional channels.
Future Outlook: Trends to Watch Over the Next 3 to 5 Years
Trend 1: Platform-Integrated Accessories as a Standard Expectation
Over the next several years, accessories will be increasingly judged on their fit within cordless and corded tool ecosystems rather than on isolated specifications. Users and procurement teams are likely to favor accessories that are designed for specific torque ranges, battery platforms, and tool interfaces, because those designs tend to deliver more consistent performance and longer service life. This will reinforce the strategic value of platform-aligned product development and create stronger incentives for manufacturers to coordinate accessory launches with tool updates. The commercial opportunity lies in building accessory lines that function as part of a complete workflow solution, improving user retention and reducing the risk of substitution by mismatched alternatives.
Worldwide Cutting Tool and Machine Tool Accessory Market
Trend 2: Performance with Lower Waste and Lower Input Exposure
Material efficiency will become a more visible competitive attribute. As raw material cost exposure and sustainability expectations rise, manufacturers that can improve performance while reducing material waste or dependency on scarce inputs will have an advantage. This includes better geometry design, more efficient manufacturing processes, and approaches that recover or reuse valuable processing materials. In practical terms, this trend creates opportunities for products that combine durability with a smaller lifecycle footprint, particularly where users are sensitive to replacement frequency and total cost of ownership. Companies that treat material strategy as a core design priority rather than a sourcing detail will be better positioned to maintain margins while meeting evolving buyer expectations.
Trend 3: Compliance and Documentation as Purchase Criteria
Safety standards, certification processes, and industry-led compliance expectations are likely to remain a meaningful influence on purchasing, especially in professional, institutional, and rental channels. As these requirements become more familiar to buyers, documented performance and safety validation may move from being a baseline requirement to a differentiator. Products that can clearly demonstrate consistent performance under testing regimes and meet recognized standards will have an easier path into demanding applications. The risk for manufacturers is that compliance becomes a late-stage checkpoint rather than a design input, delaying launches and limiting channel access. The opportunity is to make standards alignment part of the product architecture, so that compliance strengthens credibility instead of simply adding cost.
Strategic Actions for Decision-Makers
For Manufacturers
Manufacturers should prioritize accessories that solve specific workflow problems rather than adding generic SKUs. That means focusing development on durability, application fit, platform compatibility, and user convenience in high-frequency tasks. Brands with strong professional credibility should consider expanding their accessory ecosystem in lockstep with tool platform updates, since coordinated launches can reinforce system loyalty and increase attachment rates. At the same time, companies should evaluate material sourcing and recovery strategies as part of long-term cost planning, particularly for hard-metal-dependent products where input exposure can affect both price and availability.
- Invest in application-specific designs that improve measurable outcomes such as cut quality, run time, and replacement intervals.
- Align accessory development with tool platform roadmaps to reduce compatibility risk and strengthen ecosystem value.
- Build compliance, testing, and documentation into product development to support professional and institutional demand.
- Explore material efficiency measures that protect cost structure without compromising performance.
For Investors
Investors evaluating this market should pay close attention to companies that combine portfolio breadth with technical differentiation and credible compliance capabilities. The most durable revenue models in this space tend to come from brands that can stay relevant across professional and broader user segments while maintaining consistent accessory demand through tool platform loyalty. Watch for signs that a company can manage cost exposure, improve product performance in a way users notice, and expand into higher-value applications without diluting brand positioning. Also monitor the extent to which a company can maintain product launch cadence and channel access, since these factors strongly influence market share over time.
- Assess whether a company’s accessory portfolio is aligned with high-usage applications and platform-driven demand.
- Look for evidence of margin discipline through material strategy, manufacturing efficiency, or portfolio focus.
- Consider whether the company has the credibility and compliance readiness to compete in professional channels.
- Track launch consistency and ecosystem coordination as indicators of future share resilience.
For Procurement and Channel Leaders
Procurement teams and channel operators should evaluate accessories not only by unit price but by total cost of ownership, compatibility, and the availability of documented performance assurance. In higher-use environments, the cost of downtime, rework, and premature replacement can outweigh small price differences between products. It is also wise to standardize around accessories that match the tool platforms in use, because mismatched products can create hidden performance and reliability costs. Where safety and compliance matter, prioritize suppliers that can provide clear testing and standards alignment, since this reduces operational risk in demanding job-site or industrial settings.
- Evaluate accessories based on service life, application fit, and workflow impact rather than sticker price alone.
- Standardize around accessories designed for the tool platforms in active use.
- Prioritize suppliers with demonstrated compliance and performance documentation in professional contexts.
- Track field performance and replacement cycles to identify where premium accessories deliver real savings.
Closing Perspective
The power tool accessories market is expanding within a structure that increasingly rewards technical relevance, compatibility, and trust. Growth to the end of the decade and beyond is supported by broader tool adoption, ongoing material and design improvements, and continued demand from professional and semi-professional users who value productivity and reliability. At the same time, the market is becoming more demanding in terms of platform fit, compliance readiness, and cost management. That combination creates opportunities for companies that can integrate performance, economics, and standards into a coherent strategy, while exposing those that rely on undifferentiated product lines or short-term pricing tactics.
For organizations making decisions in this space, the most useful next step is to connect broad market direction with detailed asset-level insight: which applications, accessory types, channels, and regional dynamics are shaping demand in a specific business context. Deeper segmentation data, company-level scenario analysis, and tailored strategy recommendations can help turn these market-level trends into precise action plans. Readers seeking that level of detail can explore the full PW Consulting research report for comprehensive segmentation, competitive benchmarking, and forward-looking guidance tailored to specific strategic objectives.
For detailed analysis of this topic, please visit the official page: Power Tool Accessories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Checkweighers Market: Inside the 2026–2032 Growth Trajectory Beyond a 5.4% CAGR
By pmarketresearch, 2026-09-21
The Checkweighers Market: Strategic Trends and Commercial Opportunities
1. Market Status and Core Challenges
The global checkweighers market has entered a phase of steady, structurally driven expansion. In 2020, the sector generated approximately $112.85 million in revenue, and by 2025, that figure reached $144.0 million. Projections indicate a clear upward trajectory, with the market anticipated to surpass $155 million in 2026 and continue climbing to roughly $207 million by 2032. The segmented compound annual growth rate of 5.4% underscores a consistent expansion pattern, positioning checkweighers as an essential capital equipment category rather than a discretionary upgrade. This momentum reflects a broader industrial shift toward automated quality control, where weight verification is no longer a standalone function but a integrated component of broader inspection architectures.
Despite the healthy growth trajectory, the industry faces several structural inflection points that demand strategic attention. First, the transition from standalone weighing units to multi-sensor inspection platforms is reshaping procurement criteria. Operations are increasingly prioritizing systems that combine weight verification with metal detection, barcode scanning, and visual inspection in a single conveyor footprint. This convergence compresses procurement windows but also raises integration complexity, forcing manufacturers to align mechanical tolerances, communication protocols, and maintenance pathways across previously independent subsystems. Second, regional regulatory divergence is fragmenting compliance requirements. While certain jurisdictions mandate metrology certification for commercial and fiscal applications, other regions focus on food safety liability and pharmaceutical serialization mandates. Manufacturers operating across borders must navigate overlapping validation frameworks, which increases time-to-deployment and complicates global standardization strategies. Third, labor cost dynamics and demographic shifts are altering the value proposition of automation. Rising wage pressures and persistent skill shortages in high-throughput packaging environments are making automated loading and rejection mechanisms financially attractive beyond pure quality assurance goals. The commercial logic has shifted from error reduction to throughput preservation and labor redeployment.
These challenges are not barriers to growth; they are filters that separate incremental vendors from partners capable of delivering integrated, compliant, and operationally resilient solutions. Companies that treat checkweighers as a commodity weighing device will find margin compression and limited differentiation. Those that embed weight verification within a broader process control strategy will capture higher share of wallet and longer customer lifecycles.
2. Key Drivers of Market Change
Technological Innovation and Precision Evolution
Precision and speed have become mutually reinforcing priorities. Modern dynamic checkweighers are engineered to operate at line speeds that match high-volume packaging rhythms while maintaining milligram-level accuracy. This evolution is driven by advances in load cell architecture, signal processing algorithms, and vibration isolation techniques. The practical outcome is a measurable reduction in false rejects, which directly improves yield and reduces downstream rework. In pharmaceutical and food applications, where tolerance windows are narrow and batch integrity is non-negotiable, accuracy gains translate into lower rejection rates and tighter process control. At industry events such as Interpack 2026, exhibitors demonstrated Flexus® Combi and Raptor Flex systems that couple compact form factors with multi-function inspection capabilities, signaling that performance density is now a competitive differentiator. The trend is clear: weight verification is becoming more precise, more compact, and more tightly integrated with adjacent inspection functions.
Regulatory and Compliance Pressure
Regulatory expectations continue to raise the baseline for measurement integrity and traceability. In European markets, metrology certification is increasingly treated as a prerequisite for commercial deployment, ensuring that weight verification meets legal metrology standards and supports accurate invoicing, freight billing, and quality assurance. Beyond certification, food and pharmaceutical sectors face overlapping compliance requirements that link weight control to contamination detection, serialization, and audit trails. These mandates are not static; they evolve as safety incidents, consumer protection scrutiny, and supply chain traceability expectations intensify. For equipment suppliers, compliance is no longer a checkbox but a design constraint. Systems must support validation documentation, calibration routines, and data logging that align with customer audit cycles. Companies that build compliance into the product architecture from the outset reduce deployment friction and create higher switching costs for buyers who would otherwise face revalidation risks.
Demand-Side Shifts in Consumption and Operations
End-user behavior is changing on two fronts: consumer expectations and operational economics. In food and beverage, portion consistency, package integrity, and brand trust are directly tied to weight control. Underfilling creates regulatory and reputational risk, while overfilling erodes margin. The commercial pressure to hit target weights with minimal variation has intensified as pricing sensitivity rises and brand differentiation narrows. In parallel, operational teams are seeking equipment that supports flexible production runs, rapid changeovers, and lower operator dependence. Compact automated systems that can be integrated into existing lines without extensive footprint expansion are gaining traction, especially where high-care environments require hygienic design and easy sanitation. The demand pattern is shifting from “buy a scale” to “buy a process capability,” with buyers evaluating total cost of ownership, changeover time, and integration effort alongside sticker price.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by labor economics and automation economics. As Western labor inflation persists and skilled operators become scarcer, the break-even case for automated inspection strengthens. Analyses indicate that robotic loading and automated rejection become financially attractive at volume thresholds around 50,000 units, where labor savings and reduced error costs compound over time. This dynamic is pushing mid-tier producers to evaluate automation earlier than they historically would have, expanding the addressable market beyond large-scale enterprises. Simultaneously, component standardization and modular design are influencing procurement strategies. Buyers increasingly favor platforms that allow incremental capability addition, reducing the risk of overbuying while preserving upgrade paths. Suppliers that balance upfront cost clarity with modular scalability are well positioned to capture capital budget approvals in cost-conscious environments.
PW Consulting
3. Competitive Landscape and Leading Strategies
The competitive environment is moderately concentrated, with a limited number of established players accounting for a substantial share of revenue. This concentration reflects the technical demands of high-precision dynamic weighing, the importance of compliance credentials, and the value of long-term service relationships. Leading companies differentiate through application focus, integration depth, and regional service networks rather than through price alone.
German and Swiss manufacturers have built strong positions by pairing precision engineering with combination inspection architectures. Product lines that merge weight verification with metal detection or visual inspection appeal to food and pharmaceutical buyers who want to consolidate multiple inspection steps into a single station. Compact, high-speed configurations are increasingly emphasized for packaging lines where space is constrained and throughput requirements are rising. Munich- and Hamburg-based firms have demonstrated at trade events that integrated metal detection and dynamic weight control can be packaged into customizable formats, supporting tailored line layouts rather than one-size-fits-all deployments.
American and Canadian specialists have carved out niches centered on accuracy, compact form factors, and food-care environments. Systems engineered for milligram-level measurement and rapid integration into pharma and food lines address buyers who prioritize measurement integrity and hygienic design. Compact automated platforms that support high-care food production illustrate a broader competitive theme: the winning offering is not only about weighing accuracy, but about how cleanly the system fits into a specific production environment, supports sanitation protocols, and minimizes operator intervention.
Emerging and regional players are expanding the competitive field by focusing on industrial and packaging applications with flexible, cost-competitive instrumentation. Participation in regional exhibitions and a growing portfolio of weighing solutions indicate an intent to capture share in markets where local service responsiveness and price-to-performance ratios matter. This does not imply a race to the bottom; rather, it reflects a segmentation dynamic where different buyer groups prioritize different combinations of accuracy, integration, service, and total cost.
The strategic positioning of leaders can be summarized across three dimensions. First, application specialization matters. Companies that tailor solutions to food, pharmaceutical, and cosmetics workflows create deeper customer relevance and stronger compliance narratives. Second, integration is a moat. Systems that combine weighing with metal detection, visual inspection, or data capture reduce line complexity and improve process control, which elevates the equipment from a component to a process enabler. Third, service and validation support sustain relationships. Calibration, documentation, and ongoing performance verification are critical in regulated environments, and vendors that deliver these capabilities reliably build switching costs and long-term revenue visibility.
Automatic Checkweighers Market
Market evolution is trending toward selective consolidation and targeted fragmentation. Large incumbents are likely to deepen integration capabilities and expand service networks, while agile specialists will compete on precision, compact design, and application-specific value. New entrants face a high bar in precision engineering and compliance, but opportunities exist in regional service expansion, modular platforms, and niche application focus. The overall direction is toward platforms that are more intelligent, more compact, and more adaptable to varied line configurations.
4. Future Trends and Commercial Implications
Convergence Toward Multi-Function Inspection Platforms
Over the next three to five years, the dominant trend will be the continued convergence of weight verification with adjacent inspection capabilities. Buyers will increasingly evaluate stations that deliver weight control, metal detection, and visual or code verification in a unified footprint. This convergence reduces conveyor transitions, lowers integration cost, and improves data continuity across inspection steps. The commercial opportunity lies in selling process simplification rather than isolated weighing performance. Suppliers that design modular architectures, support phased capability addition, and provide clean integration interfaces will capture preference in procurement cycles where line space and downtime tolerance are constrained.
Compliance as a Design Foundation, Not an Afterthought
Regulatory and metrology expectations will keep rising as traceability, auditability, and measurement integrity become more central to operational risk management. Equipment that is designed with validation, calibration, and data logging as core features will reduce deployment friction and shorten qualification timelines. The strategic implication is straightforward: compliance-friendly architecture is a commercial accelerator. Vendors that enable customers to document performance, manage calibration cycles, and align with regional legal metrology requirements will find easier market access and stronger retention in regulated segments. The risk is that suppliers treating compliance as a peripheral feature will face longer sales cycles and more intensive customer validation efforts.
Automation Economics Expanding the Addressable Market
Labor cost pressure and throughput preservation will continue to broaden the buyer base for automated inspection. As wage dynamics and skill availability make manual handling less attractive, mid-sized producers and high-care food operations will evaluate automated loading, rejection, and monitoring earlier in their capital planning. The commercial opportunity is in packaging value propositions around total cost of ownership, changeover flexibility, and labor redeployment rather than pure accuracy specifications. The associated risk is that overly rigid, high-cost systems may struggle in price-sensitive environments, making modular scalability and clear upgrade paths essential. Suppliers that can demonstrate measurable labor offset and throughput stability at realistic volume thresholds will find stronger commercial traction.
5. Actionable Guidance for Decision-Makers
For equipment manufacturers and technology providers, the priority is to align product roadmaps with integrated inspection and compliance-driven design. Invest in modular architectures that allow customers to add metal detection, visual inspection, or data capture without compromising footprint or throughput. Strengthen validation documentation, calibration support, and regional metrology alignment to reduce deployment friction. Differentiate through application-specific configurations for food, pharmaceutical, and cosmetics workflows, and ensure service networks can support long-term performance verification. In pricing and packaging, emphasize total cost of ownership, changeover efficiency, and upgrade flexibility to match procurement realities in cost-conscious environments.
For investors evaluating the sector, the relevant signals are integration depth, compliance readiness, and service economics. Companies that can combine precision, multi-function inspection, and credible validation support are better positioned to defend margins and extend customer lifecycles. Watch for trade show activity and product launches that demonstrate compact, high-speed, combination systems, as these often preview the direction of buyer preference. Assess whether vendors are building regional service capacity and whether their product architecture supports modular expansion. The market’s 5.4% projected CAGR through 2032 reflects durable demand, but value capture will accrue to players that execute on integration, compliance, and service rather than those competing solely on specification sheets.
Production Checkweighers Market
For procurement and operations leaders, the recommendation is to shift evaluation criteria from standalone weighing performance to process capability. Assess how a checkweigher integrates with metal detection, visual inspection, and line control systems, and how it supports sanitation, changeover, and data continuity. Request validation documentation, calibration pathways, and total cost of ownership modeling that accounts for labor offset and reject reduction. Engage early with suppliers on compliance requirements and line integration constraints to avoid downstream qualification delays. When comparing options, prioritize platforms that balance accuracy with compact design, modular scalability, and service responsiveness, since these attributes determine long-term operational resilience.
For leaders who require deeper segmentation data, regional sizing, competitive benchmarking, and tailored scenario analysis, the full research report provides detailed breakdowns that support more precise planning. Access to granular market splits, company-level dynamics, and application-specific sizing can sharpen capital allocation, procurement strategy, and product investment decisions. Exploring the complete study enables a more targeted view of where growth is concentrated, which capabilities are gaining preference, and how to position for the next phase of market evolution.
For detailed analysis of this topic, please visit the official page: Checkweighers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electrofusion Coupler Market: 25.4% CAGR and 62% CR5 Reshape Pipeline Strategies
By pmarketresearch, 2026-09-21
The Electro-Fusion Coupler Market: Strategic Trends and Commercial Opportunities Through 2032
The electro-fusion coupler market has entered a phase of accelerated expansion, driven by the global shift toward high-performance polymer piping systems in utility, industrial, and municipal infrastructure. From 2020 to 2025, the sector grew from approximately 24.55 million USD to 78.14 million USD, reflecting a compound trajectory that signals both structural demand and increasing technological maturity. Looking ahead, the market is projected to reach 381.45 million USD by 2032, supported by a forecast period compound annual growth rate of 25.42 percent. This growth is not merely a function of infrastructure spending; it reflects a deeper transformation in how piping networks are designed, joined, and monitored across gas, water, and industrial applications.
For executives, investors, and procurement leaders, the implication is clear: electro-fusion couplers are transitioning from a commoditized fitting category to a strategically differentiated component class. The market is consolidating around players that combine material science expertise, process reliability, and increasingly, digital traceability. At the same time, the pace of change is introducing new operational and compliance pressures. Understanding where the market is heading—and where the bottlenecks lie—will determine which organizations capture margin, which ones face displacement, and which ones can build durable competitive moats.
Market Snapshot and Core Challenges
The size of the market has roughly tripled over a five-year window, with the 2025 baseline of 78.14 million USD setting the stage for a decade of sustained expansion. By 2032, revenue is expected to approach 381.45 million USD. This trajectory is anchored in a combination of replacement demand, new network builds, and the gradual migration of legacy jointing methods toward fusion-based systems that offer higher integrity, faster installation, and stronger leak-prevention credentials. The pace of growth, however, is unevenly distributed across regions and application segments, creating both concentration risks and expansion openings.
The market remains moderately concentrated, with the top three players accounting for roughly 45 percent of revenue and the top five representing approximately 62 percent. This structure suggests that scale, certification depth, and supply chain reliability are becoming decisive differentiators. Yet the remaining share is distributed across a diverse set of regional and specialized manufacturers, indicating that niche positioning, local compliance expertise, and application-specific product design can still carry meaningful commercial weight.
Several structural challenges are shaping the next phase of market development:
- Quality assurance and field consistency. As installations scale, the margin for error narrows. Field fusion quality depends on precise parameter control, operator training, and traceability. Any lapse in procedure or material consistency can trigger costly rework, regulatory scrutiny, or service interruptions, especially in gas and pressurized water networks.
- Regulatory harmonization and specification fragmentation. Standards and procurement specifications are evolving, but not uniformly. Differences in regional codes, utility requirements, and certification expectations can complicate multi-market strategies and slow the adoption of new coupler designs or materials.
- Supply chain resilience and input cost volatility. HDPE and related polymer compounds, energizing coils, molds, and barcode or RFID components all sit within broader industrial supply networks. Price swings, lead-time variability, and raw material qualification requirements can pressure margins and constrain the speed of product rollouts.
These challenges are not static headwinds; they are becoming strategic filters. Companies that treat quality systems, specification alignment, and supply chain transparency as core capabilities are better positioned to convert demand growth into durable share gains.
Electrofusion Fittings Market
Key Drivers Shaping the Market
The expansion of the electro-fusion coupler market is being propelled by a set of interconnected forces. Each driver reinforces the others, creating a cycle in which technical improvements enable new applications, regulatory expectations tighten, and procurement behavior shifts toward solutions that reduce long-term operational risk.
Rebar Coupler Market
Technological Innovation and Process Reliability
Material and design advancements are raising the performance baseline for electro-fusion couplers. The adoption of higher-grade polyethylene compounds, precision injection molding, and integrated energizing coils is improving joint consistency and reducing variability across field conditions. Equally important, the industry is moving toward couplers that embed traceability features, such as barcodes and RFID tags, enabling utilities and contractors to log fusion parameters, verify installation history, and support maintenance planning. This shift transforms the coupler from a passive fitting into a data-enabled link within a broader asset management workflow.
A notable example of this direction is the deployment of RFID-enabled electrofusion couplers in smart utility projects across Europe. These installations have scaled rapidly, demonstrating that digital traceability is no longer a niche concept but an operational expectation in advanced utility networks. The combination of embedded identification and field logging supports quality control, compliance documentation, and lifecycle visibility, all of which are increasingly valued by asset owners.
Policy and Regulatory Environment
Regulatory and specification activity is accelerating, reflecting heightened attention to pipeline integrity, leak reduction, and installation standardization. Updated procedures and procurement specifications are reshaping how electrofusion fittings are specified, installed, and validated. For instance, the Municipal Advisory Board approved the third edition of a generic electrofusion procedure for field joining of polyethylene pipe in 12-inch and smaller sizes, signaling continued standardization momentum. In parallel, large utilities have issued updated installation specifications that define tighter requirements for fitting selection, installation practice, and documentation.
These developments matter because they influence eligibility, bidding dynamics, and product qualification. Manufacturers that align their product lines with evolving procedures and maintain robust certification portfolios gain a smoother path into regulated procurement channels. Conversely, fragmented or outdated specifications can slow adoption, particularly for newer coupler formats or materials that require additional qualification steps.
Demand-Side Shifts in Utilities and Industrial Networks
End-user demand is being reshaped by several practical considerations: the need to reduce leakage, extend service life, accelerate installation, and improve the reliability of joint connections. Gas pipeline systems remain a significant application area, supported by ongoing network upgrades and replacement programs. Water pipeline systems represent another major demand center, with municipalities and utilities seeking solutions that lower failure rates and simplify maintenance. Industrial applications contribute additional volume, particularly where chemical resistance, pressure performance, and system modularity are priorities.
A broader behavioral shift is also underway. Buyers are increasingly evaluating fittings not solely on unit price, but on total installed cost, field reliability, and the ability to support inspection and traceability. This changes the commercial equation for manufacturers and distributors. A coupler that enables faster fusion cycles, clearer documentation, or better alignment with utility specifications can command preference even in competitive tenders.
Supply Chain and Cost Structure Evolution
The cost and availability of polymer compounds, molding capacity, and embedded electronics components are influencing both product economics and time-to-market. Manufacturers with integrated quality systems, stable material sourcing, and disciplined production processes are better equipped to manage input volatility while maintaining specification compliance. Meanwhile, the trend toward higher-performing materials and traceability features introduces new components into the value chain, making supplier relationships and quality validation more important than in the past.
At the same time, production capacity expansions in key manufacturing locations are reshaping regional supply dynamics. New facility investments can improve lead times and support larger contract volumes, but they also intensify competition for qualified materials and downstream distribution channels. Companies that can synchronize capacity growth with certification readiness and customer qualification cycles are more likely to convert expansion into market share.
Competitive Landscape and Leading Strategies
The market brings together established manufacturers with deep certification histories, regionally focused producers with strong application expertise, and companies investing in product differentiation through material quality and digital traceability. While the top of the market is moderately concentrated, competition is not uniform; it varies by geography, application, and specification environment.
A closer look at how leading companies are positioning themselves reveals several distinct strategic pathways:
- Certification and specification alignment. Some manufacturers build their advantage by maintaining broad certification coverage for gas, water, and energy applications, positioning their fittings as low-friction options for regulated procurement. This approach reduces qualification barriers and supports repeat sourcing in utility and municipal projects.
- Material and process differentiation. Other players emphasize graded polyethylene compounds, injection-molded precision, and broad size ranges. By focusing on consistent production quality and wide applicability across pipe diameters, they target contractors and distributors who value reliability and inventory flexibility.
- Traceability and smart fitting features. A growing cohort is integrating barcodes or RFID-enabled identification into couplers, linking physical products to installation records and asset management processes. This strategy is particularly relevant for utilities managing large networks where documentation, auditing, and maintenance planning carry significant operational weight.
- Regional scale and full-range coverage. Several manufacturers have expanded their product ranges to cover a wide spectrum of sizes and fitting types, strengthening their role as local or regional supply partners. This breadth can be a practical advantage in markets where project diversity and fast response times matter.
Recent company actions illustrate how these strategies are being executed in practice. One major manufacturer opened a new production campus to expand capacity for its plastics portfolio, including electrofusion fittings, signaling a push to support larger volumes and broader project demand. Another leading supplier has scaled RFID-enabled couplers across multiple smart utility projects in Europe, embedding digital traceability into live installations and using that footprint to reinforce its position in advanced procurement environments. At the same time, environmental certification activity has expanded, with published environmental product declarations covering multiple electrofusion fitting types, reflecting a broader expectation for transparency in material sourcing and product lifecycle impact. Additional product launches have broadened fitting families to include transition couplings and specialized connection formats, indicating continued diversification in how electrofusion solutions are configured for different system needs.
The competitive landscape is evolving along several axes. Consolidation pressure is present at the upper end, where scale, certification breadth, and multi-market capability create advantages. At the same time, differentiation is increasing through product features, traceability, and application-specific designs, which allows smaller or specialized players to compete on relevance rather than sheer size. New entrants and expanding regional manufacturers are also reshaping supply dynamics, particularly where local specifications, faster delivery, or cost structures create distinct value for buyers. The likely outcome is a market that remains diverse but increasingly stratified, with value migrating toward companies that can combine technical reliability, specification fit, and operational transparency.
Forward-Looking Trends for the Next 3–5 Years
Looking ahead, the market is likely to be shaped by three reinforcing trends. Each carries both opportunity and uncertainty, and each will influence how manufacturers, investors, and procurement organizations position themselves.
Trend 1: Digital traceability becomes a procurement expectation, not a premium feature
As more utilities and industrial operators adopt structured documentation and asset management practices, traceability-enabled couplers will move from early-adopter projects into broader procurement standards. Barcode and RFID-enabled fitting systems can support installation verification, quality records, and maintenance planning, making them increasingly attractive in networks where accountability and lifecycle data matter.
The commercial opportunity lies in building end-to-end workflows that connect fitting identification with field procedures and records. For manufacturers, this may mean expanding data-enabled product lines and aligning them with customer documentation systems. For procurement teams, it creates an opening to reduce inspection friction and improve network visibility. The uncertainty is in standardization: if identification formats, data ownership, and integration expectations remain fragmented, adoption may proceed project-by-project rather than at scale.
Trend 2: Regulation and specification maturity will redirect demand toward qualified, documented solutions
Continued updates to installation procedures, utility specifications, and certification expectations will reward manufacturers that can demonstrate consistent compliance and provide clear documentation packages. Over the next few years, procurement processes are likely to place greater weight on proven qualification, procedure alignment, and traceability, especially in gas and pressurized water applications where integrity concerns are highest.
This trend favors suppliers that invest early in certification coverage and maintain up-to-date alignment with evolving specifications. It also creates a barrier for newer products or materials that must pass additional qualification cycles. The risk is that specification divergence across regions and utilities can slow the rollout of improved coupler designs and increase the cost of multi-market compliance.
PW Consulting
Trend 3: Application diversification and system-level integration will expand the addressable use base
Beyond core gas and water networks, electrofusion couplers are likely to see growing use in industrial piping, energy-related installations, and hybrid connection systems that combine polymer and metallic components. Product families that include transition couplings, specialized thread connections, and broader fitting assortments can capture demand from projects that require more varied joinery solutions.
This diversification broadens the market’s growth path but also introduces complexity. Different applications impose different performance, material, and documentation requirements, so manufacturers and buyers must align product selection more carefully with operating conditions. The opportunity is in system-level thinking: fitting designs that support faster installation, clearer compatibility, and stronger integration with project specifications.
Actionable Priorities for Decision-Makers
The market’s trajectory suggests that strategy matters as much as volume. Organizations that treat electro-fusion couplers as a strategic component category—rather than a routine procurement item—will be better positioned to manage risk, capture margin, and respond to specification and technology shifts.
For Manufacturers
- Strengthen certification and specification alignment as a growth enabler. Broad, current qualification coverage reduces friction in regulated procurement and supports repeat orders in utility and municipal channels.
- Invest in traceability and documentation value. Barcode and RFID-enabled couplers can differentiate offerings where asset management, auditability, and installation records are prioritized. Ensure these features are supported by clear field procedures and customer-facing documentation.
- Balance capacity expansion with qualification readiness. New production capacity should be paired with material validation, certification updates, and customer qualification cycles to avoid capacity that is available but difficult to deploy commercially.
For Investors
- Evaluate exposure to specification-driven demand. Companies with strong certification profiles, utility relationships, and traceability differentiation are better positioned for regulated growth environments.
- Track application diversification. Interest in industrial and hybrid connection systems can expand revenue bases, but only when material performance and specification fit are demonstrable.
- Monitor concentration dynamics and regional supply shifts. Moderate market concentration suggests that scale advantages exist, but regional and specialized players can still win on relevance, qualification, and responsiveness.
For Procurement and Engineering Leaders
- Broaden evaluation criteria beyond unit price. Total installed cost, field reliability, documentation support, and specification alignment can have a material impact on project risk and long-term operating performance.
- Align fitting selection with evolving procedures. Ensure that specified products meet current installation procedures and utility requirements, reducing the risk of rework or procurement delays.
- Plan for traceability and data integration where relevant. In networks where inspection, auditing, and maintenance planning are priorities, data-enabled fittings can reduce administrative burden and improve asset visibility.
The market is moving quickly enough that static assumptions about pricing, specifications, and supplier suitability can become outdated within a single project cycle. Detailed segmentation data, regional demand patterns, certification mapping, and scenario planning can materially improve procurement, product planning, and investment decisions. For organizations that need deeper visibility into volume splits, application mix, and company-level positioning, a full market study provides the structured detail and customized context needed to translate these trends into precise action.
For detailed analysis of this topic, please visit the official page: Electro-fusion Coupler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
NPK Fertilizer Market: Why 4.2% CAGR and Asia Pacific's 50% Share Redefine Growth
By pmarketresearch, 2026-09-21
Global NPK Fertilizer Market: Navigating Growth, Disruption, and Strategic Realignment
The global NPK fertilizer market has entered a transformative phase, expanding from a valuation of $74.5 billion in 2020 to an expected $127.5 billion by 2032. This trajectory underscores a compound annual growth rate of 4.2 percent across the forecast horizon, driven by intensifying agricultural productivity demands and structural shifts in crop nutrition delivery. While the broad numbers signal steady expansion, the real story lies beneath the surface: evolving regulatory frameworks, supply chain recalibrations, and technological breakthroughs are reshaping competitive dynamics and redefining value creation across the sector.
For executives and investors, the market presents a paradox of opportunity and friction. Robust demand fundamentals are colliding with raw material volatility, policy interventions, and consolidation pressures. Understanding how these forces interact is no longer optional; it is a prerequisite for strategic positioning in a landscape where traditional growth levers are being supplemented, and in some cases displaced, by innovation and regulatory adaptation.
Market Landscape and Core Challenges
The NPK fertilizer sector has moved through a period of pronounced price and volume adjustment over the past half-decade. Revenue growth from 2020 through 2025 reflects a market that has largely recovered from pandemic-era disruptions while absorbing inflationary pressures on energy, freight, and raw material inputs. The forward outlook through 2032 suggests a market that will continue to expand, but with uneven momentum across regions and product formats. Rather than a uniform upswing, the growth pattern points to a maturing industry where efficiency, formulation quality, and supply reliability increasingly differentiate winners from laggards.
Worldwide Starter Fertilizer Market
Three structural challenges define the current inflection point:
- Raw material cost volatility and pass-through uncertainty. NPK production remains tightly linked to ammonia, phosphate, and potash markets, all of which are exposed to energy price swings, trade policy shifts, and logistics constraints. Recent price assessments in Northeast Asia have shown modest declines, yet the broader cost environment remains unpredictable. Manufacturers face a persistent tension between absorbing cost shocks and preserving margin integrity in a competitive pricing environment.
- Regulatory and policy recalibration. Governments are actively reshaping fertilizer markets through subsidy design, grade approvals, and duty structures. New NPK grades fortified with secondary and micronutrients have been incorporated into national soil fertility schemes, signaling a policy direction that favors nutrient efficiency and soil health over bulk commodity application. At the same time, trade adjustments, such as requests to reduce customs duties on specific phosphate products, reflect the ongoing balancing act between import dependence, domestic production, and farmer affordability.
- Consolidation and competition scrutiny. Rising concentration among NPK producers has drawn regulatory attention, with legislative bodies examining whether consolidation is contributing to price increases and limiting buyer choice. This scrutiny introduces a new layer of risk for market participants, particularly as mergers, acquisitions, and capacity realignments continue to reshape the industry footprint.
These challenges are not isolated stressors; they interact to shape pricing behavior, capacity decisions, and product strategy. Companies that treat them as isolated issues risk misallocating capital, while those that integrate them into a coherent strategic framework can convert volatility into differentiation.
Core Drivers Reshaping the Market
Beneath the headline growth figures, four interconnected drivers are accelerating change across the NPK fertilizer ecosystem.
Technological Innovation and Formulation Science
Innovation is moving beyond incremental tweaks to core production processes toward smarter delivery and enhanced nutrient utilization. Microbial coating technologies for mineral NPK fertilizers have progressed from research to commercial deployment, combining conventional nutrient blends with beneficial microorganisms designed to improve nutrient availability and field performance. This convergence of agronomic biology and traditional fertilizer chemistry represents a meaningful shift: the value proposition is increasingly tied to how effectively nutrients are absorbed and utilized, not merely how much is applied.
Parallel advances in liquid formulation capabilities are expanding the addressable use cases for NPK products. New liquid fertilizer plants focused on NPK-based blends are coming online, reflecting demand for precision application, compatibility with irrigation systems, and flexibility in customized nutrient programs. These developments suggest that product architecture, rather than volume alone, will be a critical determinant of competitive advantage in the coming years.
Policy and Regulatory Environment
Policy frameworks are becoming a more direct lever on market structure and product mix. The inclusion of fortified NPK grades with magnesium, zinc, boron, and sulfur in official soil fertility schemes illustrates a policy environment that is actively encouraging micronutrient integration and nutrient efficiency. Such moves create both compliance requirements and commercial opportunities, as manufacturers and distributors align their portfolios with approved grades and farmer expectations for balanced nutrition.
Trade policy and duty structures add another dimension. Requests to align customs duties on specific phosphate products with those applied to other NPK fertilizers highlight the sensitivity of import-dependent markets to cost pass-through and supply security. Companies operating across multiple jurisdictions must navigate a patchwork of subsidies, grade approvals, and tariff adjustments, where even modest policy changes can alter regional competitiveness and sourcing strategies.
Soluble Fertilizer Market
Demand-Side Evolution in Agriculture
수요侧 dynamics are shifting as growers and agricultural enterprises prioritize yield stability, soil health, and input efficiency over pure volume. Cereals and grains continue to anchor a large share of NPK consumption, but fruits, vegetables, and oilseeds and pulses are expanding their share of demand, reflecting diversified cropping patterns and higher-value production systems. This diversification increases the importance of tailored formulations, as different crops and growth stages require distinct nutrient balances and delivery methods.
The commercial adoption of biofertilizer production capacity further signals that demand is broadening beyond conventional NPK. Integration of biologicals with mineral nutrient programs is gaining traction among producers seeking to enhance nutrient use efficiency and meet sustainability expectations. For NPK suppliers, this trend creates an opportunity to participate in integrated crop nutrition solutions rather than competing solely on commodity-grade pricing.
Supply Chain and Cost Structure Realignment
Cost structures are being redefined by capacity decisions, logistics optimization, and vertical integration. Major nitrogen and phosphate producers are adjusting output in response to raw material market conditions, with some facilities scaling back production or withdrawing forward guidance amid uncertainty. These capacity moves have ripple effects across the supply chain, influencing availability, pricing expectations, and contract negotiations for downstream blenders and distributors.
At the same time, regional production footprints are expanding to serve localized demand more efficiently. New liquid fertilizer facilities and biofertilizer production sites are being established in strategic locations, reducing dependency on long-distance logistics and enabling faster response to regional crop cycles. This localization trend is particularly relevant in markets where import reliance and duty structures create cost differentials, as domestic or near-shore capacity can improve supply resilience and margin stability.
Competitive Landscape and Strategic Positioning
The NPK fertilizer market is characterized by a concentrated group of large-scale producers alongside a growing set of specialized entrants and consolidators. Leading players are positioned around distinct operational strengths: global nitrogen and phosphate integration, broad distribution networks, mining and processing assets, and high-throughput ammonia capacity. These structural advantages provide scale, cost leverage, and product breadth, but they also require continuous adaptation as customer requirements and regulatory conditions evolve.
Differentiation is increasingly anchored in three areas:
- Product and process breadth. Companies with diversified production routes, including nitrophosphate and sulphuric acid processes, blended NPK retail networks, and concentrated phosphate and potash-based formulations, can respond more flexibly to regional grade requirements and crop-specific demand. The ability to supply a range of nutrient profiles, from granular to liquid formats, supports broader customer coverage and reduces exposure to single-format cyclicality.
- Geographic and supply chain reach. Multi-continent plant networks and regional complexes enable closer proximity to end markets, shorter response times, and greater control over logistics. This footprint is especially valuable where import duties, freight costs, and local grade preferences influence competitiveness.
- Innovation adjacency. Leaders are extending their positioning through complementary capabilities, such as microbial coating technologies and biofertilizer integration, while others are pursuing acquisitions of high-efficiency liquid NPK specialists. These moves signal a strategic shift from standalone fertilizer supply toward integrated nutrient solution providers.
The market landscape is evolving through both consolidation and fragmentation. On one hand, acquisitions and capacity realignment are concentrating production among fewer players, raising competition policy questions and influencing pricing dynamics. On the other hand, targeted greenfield investments in liquid and biofertilizer facilities, along with specialist acquisitions, are introducing new capabilities and niche focuses. This dual movement creates a more nuanced environment: scale remains important, but agility, formulation expertise, and local market execution are becoming equally decisive.
Recent industry activity illustrates this realignment in practice. Commercial launch of microbial coating technology for mineral NPK fertilizers after extended research demonstrates the move from concept to market-ready solutions. Capacity adjustments at phosphate facilities in response to volatile raw material conditions highlight the discipline required to manage output and outlooks in an uncertain cost environment. Groundbreaking on biofertilizer production facilities and inauguration of new liquid fertilizer plants reflect investment in adjacent capabilities that support NPK-based integration. Acquisitions of high-efficiency liquid NPK specialists point to a strategy of capturing specialized formulation expertise and expanding product reach. Together, these developments suggest a market where competitive advantage will be built on the combination of scale, formulation quality, and biological innovation.
Future Trends and Strategic Implications
Looking ahead over the next three to five years, three trends are likely to shape the NPK fertilizer market and open distinct commercial pathways.
Precision-Enabled Nutrient Solutions Will Redefine Value
The convergence of advanced formulation, biologicals, and application precision is shifting competition from input volume to nutrient effectiveness. Expect continued adoption of fortified grades, liquid formats, and microbial-enhanced products as growers and agronomic advisors seek better nutrient use efficiency and more consistent field outcomes. Commercial opportunity will accrue to players that can offer credible performance data, customized grade recommendations, and integrated advisory support rather than relying on commodity marketing alone.
Policy-Driven Portfolio Alignment Will Become a Strategic Necessity
As governments refine fertilizer schemes, approve new fortified grades, and adjust trade duties, market access and pricing will increasingly depend on portfolio alignment with regulatory expectations. Companies that proactively redesign product mixes, secure approvals for micronutrient-fortified blends, and optimize sourcing against duty structures will be better positioned to protect margins and maintain market share. Failure to align with evolving policy frameworks can create avoidable cost penalties and limit distribution access in key regions.
Capacity Realignment and Regionalization Will Reshape Supply Dynamics
Output curtailments, selective greenfield investments, and specialist acquisitions indicate a market that is repositioning capacity toward regional demand, cost-efficient formats, and higher-value product segments. This realignment can improve supply resilience where local production replaces long-distance imports, but it also introduces execution risk and capital intensity. Participants must balance the benefits of localized capacity with the realities of raw material exposure, energy economics, and demand variability across crop cycles.
These trends carry inherent uncertainty. Policy directions can shift with political and fiscal priorities, raw material markets can disrupt cost assumptions, and competitive consolidation may attract further regulatory scrutiny. Additionally, adoption of biological and precision-enhanced products depends on farmer acceptance, demonstration of consistent field performance, and distribution capability. Companies that build scenario flexibility into their planning and maintain close monitoring of policy, cost, and demand signals will be better prepared to navigate this complexity.
PW Consulting
Actionable Guidance for Decision-Makers
For manufacturers and producers, the strategic imperative is to strengthen formulation flexibility and innovation adjacency while managing raw material exposure with disciplined capacity planning. Prioritize product architectures that support fortified grades, liquid formats, and biological integration where market demand and regulatory frameworks justify the investment. Align sourcing and production footprints with regional grade requirements and duty structures to improve margin stability and supply reliability. Use performance-led differentiation and agronomic support to reduce reliance on price-only competition.
For investors, the opportunity set is expanding beyond traditional volume plays into formulation quality, biological integration, and regional capacity repositioning. Evaluate assets and companies on the basis of their ability to execute fortified and liquid product strategies, manage cost volatility, and navigate regulatory alignment across jurisdictions. Pay close attention to consolidation dynamics and policy developments, as these can influence both pricing power and market access. Diversification across formats and geographies, combined with exposure to efficiency-enhancing technologies, can provide a more resilient growth profile.
For procurement and distribution leaders, supplier selection should increasingly factor in formulation adaptability, product certification against evolving grade schemes, and supply chain resilience in the face of raw material and logistics variability. Negotiate with an eye on grade diversification and application flexibility, ensuring access to fortified and liquid options that match crop-specific needs. Monitor policy changes that affect duty structures and approved grades, as these can alter cost expectations and availability. Building supplier relationships that support integrated nutrient programs, rather than single-grade transactions, can improve performance outcomes and reduce exposure to price shocks.
For decision-makers seeking to convert these insights into concrete strategy, the complexity of the NPK fertilizer market rewards deeper, segmentation-specific intelligence. Detailed demand patterns, regional grade adoption timelines, raw material cost scenarios, and competitive move tracking all matter when translating trends into capital allocation, portfolio design, and sourcing decisions. In that context, PW Consulting's comprehensive NPK fertilizer market research report offers a structured, data-supported foundation for those decisions, providing granular segmentation detail, country-level dynamics, and scenario analysis that extend well beyond the strategic overview presented here.
For detailed analysis of this topic, please visit the official page: NPK Fertilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com