

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electrofusion Coupler Market: 25.4% CAGR and 62% CR5 Reshape Pipeline Strategies

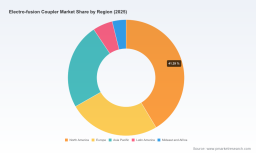
The Electro-Fusion Coupler Market: Strategic Trends and Commercial Opportunities Through 2032
The electro-fusion coupler market has entered a phase of accelerated expansion, driven by the global shift toward high-performance polymer piping systems in utility, industrial, and municipal infrastructure. From 2020 to 2025, the sector grew from approximately 24.55 million USD to 78.14 million USD, reflecting a compound trajectory that signals both structural demand and increasing technological maturity. Looking ahead, the market is projected to reach 381.45 million USD by 2032, supported by a forecast period compound annual growth rate of 25.42 percent. This growth is not merely a function of infrastructure spending; it reflects a deeper transformation in how piping networks are designed, joined, and monitored across gas, water, and industrial applications.
For executives, investors, and procurement leaders, the implication is clear: electro-fusion couplers are transitioning from a commoditized fitting category to a strategically differentiated component class. The market is consolidating around players that combine material science expertise, process reliability, and increasingly, digital traceability. At the same time, the pace of change is introducing new operational and compliance pressures. Understanding where the market is heading—and where the bottlenecks lie—will determine which organizations capture margin, which ones face displacement, and which ones can build durable competitive moats.
Market Snapshot and Core Challenges
The size of the market has roughly tripled over a five-year window, with the 2025 baseline of 78.14 million USD setting the stage for a decade of sustained expansion. By 2032, revenue is expected to approach 381.45 million USD. This trajectory is anchored in a combination of replacement demand, new network builds, and the gradual migration of legacy jointing methods toward fusion-based systems that offer higher integrity, faster installation, and stronger leak-prevention credentials. The pace of growth, however, is unevenly distributed across regions and application segments, creating both concentration risks and expansion openings.
The market remains moderately concentrated, with the top three players accounting for roughly 45 percent of revenue and the top five representing approximately 62 percent. This structure suggests that scale, certification depth, and supply chain reliability are becoming decisive differentiators. Yet the remaining share is distributed across a diverse set of regional and specialized manufacturers, indicating that niche positioning, local compliance expertise, and application-specific product design can still carry meaningful commercial weight.
Several structural challenges are shaping the next phase of market development:
- Quality assurance and field consistency. As installations scale, the margin for error narrows. Field fusion quality depends on precise parameter control, operator training, and traceability. Any lapse in procedure or material consistency can trigger costly rework, regulatory scrutiny, or service interruptions, especially in gas and pressurized water networks.
- Regulatory harmonization and specification fragmentation. Standards and procurement specifications are evolving, but not uniformly. Differences in regional codes, utility requirements, and certification expectations can complicate multi-market strategies and slow the adoption of new coupler designs or materials.
- Supply chain resilience and input cost volatility. HDPE and related polymer compounds, energizing coils, molds, and barcode or RFID components all sit within broader industrial supply networks. Price swings, lead-time variability, and raw material qualification requirements can pressure margins and constrain the speed of product rollouts.
These challenges are not static headwinds; they are becoming strategic filters. Companies that treat quality systems, specification alignment, and supply chain transparency as core capabilities are better positioned to convert demand growth into durable share gains.
Electrofusion Fittings Market
Key Drivers Shaping the Market
The expansion of the electro-fusion coupler market is being propelled by a set of interconnected forces. Each driver reinforces the others, creating a cycle in which technical improvements enable new applications, regulatory expectations tighten, and procurement behavior shifts toward solutions that reduce long-term operational risk.
Rebar Coupler Market
Technological Innovation and Process Reliability
Material and design advancements are raising the performance baseline for electro-fusion couplers. The adoption of higher-grade polyethylene compounds, precision injection molding, and integrated energizing coils is improving joint consistency and reducing variability across field conditions. Equally important, the industry is moving toward couplers that embed traceability features, such as barcodes and RFID tags, enabling utilities and contractors to log fusion parameters, verify installation history, and support maintenance planning. This shift transforms the coupler from a passive fitting into a data-enabled link within a broader asset management workflow.
A notable example of this direction is the deployment of RFID-enabled electrofusion couplers in smart utility projects across Europe. These installations have scaled rapidly, demonstrating that digital traceability is no longer a niche concept but an operational expectation in advanced utility networks. The combination of embedded identification and field logging supports quality control, compliance documentation, and lifecycle visibility, all of which are increasingly valued by asset owners.
Policy and Regulatory Environment
Regulatory and specification activity is accelerating, reflecting heightened attention to pipeline integrity, leak reduction, and installation standardization. Updated procedures and procurement specifications are reshaping how electrofusion fittings are specified, installed, and validated. For instance, the Municipal Advisory Board approved the third edition of a generic electrofusion procedure for field joining of polyethylene pipe in 12-inch and smaller sizes, signaling continued standardization momentum. In parallel, large utilities have issued updated installation specifications that define tighter requirements for fitting selection, installation practice, and documentation.
These developments matter because they influence eligibility, bidding dynamics, and product qualification. Manufacturers that align their product lines with evolving procedures and maintain robust certification portfolios gain a smoother path into regulated procurement channels. Conversely, fragmented or outdated specifications can slow adoption, particularly for newer coupler formats or materials that require additional qualification steps.
Demand-Side Shifts in Utilities and Industrial Networks
End-user demand is being reshaped by several practical considerations: the need to reduce leakage, extend service life, accelerate installation, and improve the reliability of joint connections. Gas pipeline systems remain a significant application area, supported by ongoing network upgrades and replacement programs. Water pipeline systems represent another major demand center, with municipalities and utilities seeking solutions that lower failure rates and simplify maintenance. Industrial applications contribute additional volume, particularly where chemical resistance, pressure performance, and system modularity are priorities.
A broader behavioral shift is also underway. Buyers are increasingly evaluating fittings not solely on unit price, but on total installed cost, field reliability, and the ability to support inspection and traceability. This changes the commercial equation for manufacturers and distributors. A coupler that enables faster fusion cycles, clearer documentation, or better alignment with utility specifications can command preference even in competitive tenders.
Supply Chain and Cost Structure Evolution
The cost and availability of polymer compounds, molding capacity, and embedded electronics components are influencing both product economics and time-to-market. Manufacturers with integrated quality systems, stable material sourcing, and disciplined production processes are better equipped to manage input volatility while maintaining specification compliance. Meanwhile, the trend toward higher-performing materials and traceability features introduces new components into the value chain, making supplier relationships and quality validation more important than in the past.
At the same time, production capacity expansions in key manufacturing locations are reshaping regional supply dynamics. New facility investments can improve lead times and support larger contract volumes, but they also intensify competition for qualified materials and downstream distribution channels. Companies that can synchronize capacity growth with certification readiness and customer qualification cycles are more likely to convert expansion into market share.
Competitive Landscape and Leading Strategies
The market brings together established manufacturers with deep certification histories, regionally focused producers with strong application expertise, and companies investing in product differentiation through material quality and digital traceability. While the top of the market is moderately concentrated, competition is not uniform; it varies by geography, application, and specification environment.
A closer look at how leading companies are positioning themselves reveals several distinct strategic pathways:
- Certification and specification alignment. Some manufacturers build their advantage by maintaining broad certification coverage for gas, water, and energy applications, positioning their fittings as low-friction options for regulated procurement. This approach reduces qualification barriers and supports repeat sourcing in utility and municipal projects.
- Material and process differentiation. Other players emphasize graded polyethylene compounds, injection-molded precision, and broad size ranges. By focusing on consistent production quality and wide applicability across pipe diameters, they target contractors and distributors who value reliability and inventory flexibility.
- Traceability and smart fitting features. A growing cohort is integrating barcodes or RFID-enabled identification into couplers, linking physical products to installation records and asset management processes. This strategy is particularly relevant for utilities managing large networks where documentation, auditing, and maintenance planning carry significant operational weight.
- Regional scale and full-range coverage. Several manufacturers have expanded their product ranges to cover a wide spectrum of sizes and fitting types, strengthening their role as local or regional supply partners. This breadth can be a practical advantage in markets where project diversity and fast response times matter.
Recent company actions illustrate how these strategies are being executed in practice. One major manufacturer opened a new production campus to expand capacity for its plastics portfolio, including electrofusion fittings, signaling a push to support larger volumes and broader project demand. Another leading supplier has scaled RFID-enabled couplers across multiple smart utility projects in Europe, embedding digital traceability into live installations and using that footprint to reinforce its position in advanced procurement environments. At the same time, environmental certification activity has expanded, with published environmental product declarations covering multiple electrofusion fitting types, reflecting a broader expectation for transparency in material sourcing and product lifecycle impact. Additional product launches have broadened fitting families to include transition couplings and specialized connection formats, indicating continued diversification in how electrofusion solutions are configured for different system needs.
The competitive landscape is evolving along several axes. Consolidation pressure is present at the upper end, where scale, certification breadth, and multi-market capability create advantages. At the same time, differentiation is increasing through product features, traceability, and application-specific designs, which allows smaller or specialized players to compete on relevance rather than sheer size. New entrants and expanding regional manufacturers are also reshaping supply dynamics, particularly where local specifications, faster delivery, or cost structures create distinct value for buyers. The likely outcome is a market that remains diverse but increasingly stratified, with value migrating toward companies that can combine technical reliability, specification fit, and operational transparency.
Forward-Looking Trends for the Next 3–5 Years
Looking ahead, the market is likely to be shaped by three reinforcing trends. Each carries both opportunity and uncertainty, and each will influence how manufacturers, investors, and procurement organizations position themselves.
Trend 1: Digital traceability becomes a procurement expectation, not a premium feature
As more utilities and industrial operators adopt structured documentation and asset management practices, traceability-enabled couplers will move from early-adopter projects into broader procurement standards. Barcode and RFID-enabled fitting systems can support installation verification, quality records, and maintenance planning, making them increasingly attractive in networks where accountability and lifecycle data matter.
The commercial opportunity lies in building end-to-end workflows that connect fitting identification with field procedures and records. For manufacturers, this may mean expanding data-enabled product lines and aligning them with customer documentation systems. For procurement teams, it creates an opening to reduce inspection friction and improve network visibility. The uncertainty is in standardization: if identification formats, data ownership, and integration expectations remain fragmented, adoption may proceed project-by-project rather than at scale.
Trend 2: Regulation and specification maturity will redirect demand toward qualified, documented solutions
Continued updates to installation procedures, utility specifications, and certification expectations will reward manufacturers that can demonstrate consistent compliance and provide clear documentation packages. Over the next few years, procurement processes are likely to place greater weight on proven qualification, procedure alignment, and traceability, especially in gas and pressurized water applications where integrity concerns are highest.
This trend favors suppliers that invest early in certification coverage and maintain up-to-date alignment with evolving specifications. It also creates a barrier for newer products or materials that must pass additional qualification cycles. The risk is that specification divergence across regions and utilities can slow the rollout of improved coupler designs and increase the cost of multi-market compliance.
PW Consulting
Trend 3: Application diversification and system-level integration will expand the addressable use base
Beyond core gas and water networks, electrofusion couplers are likely to see growing use in industrial piping, energy-related installations, and hybrid connection systems that combine polymer and metallic components. Product families that include transition couplings, specialized thread connections, and broader fitting assortments can capture demand from projects that require more varied joinery solutions.
This diversification broadens the market’s growth path but also introduces complexity. Different applications impose different performance, material, and documentation requirements, so manufacturers and buyers must align product selection more carefully with operating conditions. The opportunity is in system-level thinking: fitting designs that support faster installation, clearer compatibility, and stronger integration with project specifications.
Actionable Priorities for Decision-Makers
The market’s trajectory suggests that strategy matters as much as volume. Organizations that treat electro-fusion couplers as a strategic component category—rather than a routine procurement item—will be better positioned to manage risk, capture margin, and respond to specification and technology shifts.
For Manufacturers
- Strengthen certification and specification alignment as a growth enabler. Broad, current qualification coverage reduces friction in regulated procurement and supports repeat orders in utility and municipal channels.
- Invest in traceability and documentation value. Barcode and RFID-enabled couplers can differentiate offerings where asset management, auditability, and installation records are prioritized. Ensure these features are supported by clear field procedures and customer-facing documentation.
- Balance capacity expansion with qualification readiness. New production capacity should be paired with material validation, certification updates, and customer qualification cycles to avoid capacity that is available but difficult to deploy commercially.
For Investors
- Evaluate exposure to specification-driven demand. Companies with strong certification profiles, utility relationships, and traceability differentiation are better positioned for regulated growth environments.
- Track application diversification. Interest in industrial and hybrid connection systems can expand revenue bases, but only when material performance and specification fit are demonstrable.
- Monitor concentration dynamics and regional supply shifts. Moderate market concentration suggests that scale advantages exist, but regional and specialized players can still win on relevance, qualification, and responsiveness.
For Procurement and Engineering Leaders
- Broaden evaluation criteria beyond unit price. Total installed cost, field reliability, documentation support, and specification alignment can have a material impact on project risk and long-term operating performance.
- Align fitting selection with evolving procedures. Ensure that specified products meet current installation procedures and utility requirements, reducing the risk of rework or procurement delays.
- Plan for traceability and data integration where relevant. In networks where inspection, auditing, and maintenance planning are priorities, data-enabled fittings can reduce administrative burden and improve asset visibility.
The market is moving quickly enough that static assumptions about pricing, specifications, and supplier suitability can become outdated within a single project cycle. Detailed segmentation data, regional demand patterns, certification mapping, and scenario planning can materially improve procurement, product planning, and investment decisions. For organizations that need deeper visibility into volume splits, application mix, and company-level positioning, a full market study provides the structured detail and customized context needed to translate these trends into precise action.
For detailed analysis of this topic, please visit the official page: Electro-fusion Coupler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com