

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
The Real Time Clock Market: Why 6.8% CAGR and Segment Shifts Redefine Growth to 2032

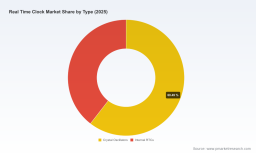
Navigating the Real Time Clock Market: Strategic Shifts and Commercial Opportunities in a Precision-Driven Era
Executive Overview
The Real Time Clock (RTC) market has matured beyond its legacy role as a simple timekeeping component into a critical enabler of precision, reliability, and power efficiency across connected systems. As embedded architectures grow more complex and real-time synchronization demands intensify across automotive, industrial, and consumer applications, the strategic value of RTC solutions has never been more pronounced. Market trajectories indicate sustained expansion, supported by evolving design requirements, supply chain realignment, and the push toward lower power consumption without sacrificing accuracy. Understanding where the market is headed requires moving past surface-level sizing and examining the underlying forces reshaping product roadmaps, competitive positioning, and procurement strategies.
Market Landscape and Pressing Challenges
The global RTC market has demonstrated steady growth over the recent historical period, with revenue expanding from approximately 1.65 billion USD in 2020 to an estimated 2.10 billion USD by 2025. Forward projections point to continued momentum through the forecast horizon, with the market expected to approach 3.30 billion USD by 2032, reflecting a compound annual growth rate of 6.8 percent. This trajectory underscores a market that is neither stagnant nor purely cyclical, but one shaped by incremental technological advancement and broadening application footprints.
Despite the positive growth outlook, the sector faces several structural challenges that decision-makers must navigate carefully. First, the transition from discrete timing components to tightly integrated, low-power RTC solutions is raising design complexity and qualification barriers. Engineers are increasingly required to balance accuracy, power draw, package constraints, and environmental tolerance, which slows adoption cycles and intensifies validation workloads. Second, product lifecycle management has become a focal point of risk. Recent end-of-life announcements from select suppliers have highlighted the fragility of legacy timing portfolios, forcing customers to plan migration paths without disrupting long-lifecycle deployments in industrial and automotive settings. Third, the competitive environment remains moderately fragmented, with the top three players holding roughly 28.5 percent of market share and the top five accounting for approximately 42.0 percent. This concentration leaves room for specialization, but it also means that pricing power and differentiation are increasingly tied to application expertise, qualification depth, and integration capabilities rather than volume alone.
Design Complexity Versus Power and Accuracy Trade-Offs
As device architectures push toward ultra-low-power operation, RTC solutions must maintain stable timekeeping across wide temperature ranges and extended battery-backup scenarios. Achieving this balance often requires tighter integration between the oscillator, compensation logic, and interface architecture. For product teams, this means that RTC selection is no longer a commodity decision; it directly influences system reliability, firmware complexity, and overall bill of materials.
Lifecycle Continuity and Migration Risk
The recent EOL notifications from a notable RTC supplier illustrate how portfolio rationalization can ripple through downstream design cycles. Customers with multi-year product lifecycles must evaluate re-qualification timelines, alternative part compatibility, and the risk of obsolescence in safety-critical or regulated deployments. This is especially relevant for industrial equipment, smart infrastructure, and automotive subsystems where redesign windows are narrow and validation costs are high.
Fragmented Share and the Search for Differentiable Value
A moderately concentrated market structure creates two simultaneous dynamics. On one hand, it allows specialized players to capture value by targeting high-precision, temperature-compensated, or automotive-qualified niches. On the other hand, it pressures larger suppliers to defend share through broad portfolios, ecosystem support, and long-term availability commitments. Companies that cannot articulate a clear application-specific advantage may find themselves competing primarily on price rather than technical merit.
Atomic Clock Market
Core Drivers Reshaping the Market
Several interconnected forces are accelerating demand and redefining how RTC solutions are specified, sourced, and integrated. These drivers span technology, regulation, demand behavior, and supply chain dynamics, and they collectively shape the commercial opportunity set.
Ultra-Low-Power CMOS Design and Precision Integration
One of the strongest technical catalysts is the ongoing refinement of ultra-low-power RTC ICs that combine automatic battery switching, programmable clock outputs, and interrupt-driven calendar functions. These features are particularly relevant for embedded systems, IoT endpoints, and automotive modules that must preserve timekeeping integrity during power loss or sleep states. At the same time, temperature-compensated and integrated-crystal approaches are gaining traction where accuracy cannot be compromised across operating environments. The result is a shift from simple clock generation to smarter timing ICs that reduce system-level burden and enable more deterministic behavior in connected products.
Application-Level Demand and Real-Time Synchronization Requirements
Demand is being pulled by end-use environments where timing precision has direct operational consequences. In industrial automation and smart metering, reliable timekeeping supports logging, synchronization, and event sequencing. In automotive platforms, RTC functions contribute to diagnostics, firmware state management, and system recovery logic. In consumer electronics, compact RTC modules help balance low power draw with dependable calendar and alarm functions. The common thread is that RTCs are increasingly evaluated as part of a broader timing strategy rather than as standalone components, which raises the importance of interface compatibility, event handling, and power management integration.
Lifecycle Planning, Portfolio Pruning, and Supply Continuity
Regulatory expectations and long product lifecycles in certain verticals are placing greater emphasis on continuity planning. As suppliers prune legacy lines, customers are forced to assess second-source options, migration feasibility, and qualification overhead. This dynamic is reshaping procurement behavior: buyers are prioritizing suppliers that can demonstrate clear transition roadmaps, broad qualification coverage, and transparent availability signals. In practice, this creates an opening for suppliers that can combine precision, programmability, and lifecycle support without forcing customers into costly redesigns.
Competitive Realignment and Assets Consolidation
The timing ecosystem is undergoing consolidation pressure as companies seek to strengthen portfolios and capture adjacent capability. Recent acquisition activity involving RTC-related timing assets reflects a strategic push to consolidate precision timing know-how and expand product coverage across industrial, communications, and embedded computing applications. For the broader market, consolidation can improve portfolio coherence and accelerate innovation, but it can also alter availability patterns, support structures, and competitive dynamics in specific niches. Buyers and investors alike should watch how these moves change qualification breadth, regional support, and the pace of new product introductions.
Competitive Landscape and Leading Strategies
The RTC market features a mix of semiconductor incumbents, timing specialists, and module-oriented providers, each leaning into different value propositions. The strategic positioning of the leading companies reflects a broader tension between breadth, specialization, and integration depth.
Strategic Positioning Across the Leader Set
NXP Semiconductors emphasizes ultra-low-power CMOS RTC ICs with automatic battery switching, programmable clock outputs, and interrupt features designed for low-power calendars in embedded, automotive, and IoT environments. This positions the company around power-aware timekeeping and firmware-friendly interrupt structures, which matters for designs that must minimize active current while preserving reliable calendar behavior. Microchip Technology focuses on RTCs with integrated oscillators and I2C interfaces for precision timekeeping in industrial, automotive, and consumer electronics. The emphasis on interface simplicity and integrated oscillation supports designers seeking predictable integration and broad applicability across multiple verticals. Texas Instruments positions its timing solutions around RTC ICs for real-time applications in industrial controls, automotive systems, and power management, aligning with customers that value robust timing within broader control and power architectures.
STMicroelectronics highlights RTC and timing devices for energy-efficient timekeeping in smart meters, IoT, and industrial sensors, targeting applications where power efficiency and long-term stability are critical. Epson Electronics offers RTC module families with integrated crystals for high-precision, low-power calendars in industrial and commercial settings, appealing to customers that prefer module-level simplicity and proven accuracy. Diodes Incorporated brings temperature-compensated RTC modules with integrated crystals to the table, optimizing for accuracy under wide temperature ranges in networking and embedded systems—an advantage where environmental variability is a core concern. Abracon LLC focuses on RTCs with embedded crystals, AEC-Q200 qualification, alarm support, leap year handling, and ultra-low power in compact SMD packages, which aligns well with automotive-grade and space-constrained designs. SiTime Corporation emphasizes precision timing products including ultra-low-power RTCs with dual I2C bus support for applications in AI, communications, and embedded computing, signaling a push toward higher-performance timing in compute-intensive and interface-sensitive environments.
Differentiation Through Integration, Qualification, and Application Fit
Across the leader set, differentiation is increasingly tied to three dimensions. The first is integration depth: RTCs that combine oscillator functions, compensation mechanisms, and interface flexibility reduce design friction and improve system determinism. The second is qualification and environmental robustness, especially where automotive-grade or wide-temperature performance is required. The third is application alignment: suppliers that articulate clear value for smart metering, industrial sensing, automotive subsystems, or low-power IoT are better positioned to command preference over generic timing parts. Companies that can demonstrate all three tend to win design-ins in complex deployments where downtime, rework, or re-qualification carries high cost.
Worldwide MEMS Real-Time Clock Market
Where the Landscape Is Heading
The competitive picture is likely to evolve through a combination of consolidation and specialization. Consolidation may reduce the number of independent timing asset holders, particularly where acquisition activity broadens portfolio coverage or strengthens precision capabilities. At the same time, specialization is likely to persist in high-accuracy, temperature-compensated, and automotive-qualified segments, where technical barriers and qualification requirements protect niche leadership. New entrants and smaller specialists may continue to compete by targeting compact packages, ultra-low-power profiles, or application-specific features such as alarm handling, leap year support, and programmable outputs. The practical implication is that customers should not assume a one-size-fits-all sourcing strategy; the optimal partner depends on whether the priority is integration simplicity, environmental robustness, lifecycle continuity, or application-specific feature sets.
Forward Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, the RTC market is poised to be shaped by a handful of clear trends that connect directly to commercial opportunity.
Trend 1: Timing Becomes More System-Critical, Not Less
As connected systems scale and real-time coordination becomes more important, RTC functions will be evaluated less as passive components and more as integral parts of timing integrity strategies. Designs will increasingly demand tighter integration, predictable power behavior, and interface support that aligns with broader system architectures. This raises the value of RTC solutions that simplify firmware logic, reduce active power, and support event-driven calendars. For suppliers, this trend favors products that address system-level pain points rather than clock output alone.
Trend 2: Precision and Environmental Resilience Will Command Premium Positioning
Wide temperature ranges, long battery-backup intervals, and stable accuracy under varying conditions will remain key procurement criteria in automotive, industrial, and infrastructure applications. Temperature-compensated modules and integrated-crystal families are likely to see continued interest where accuracy cannot be sacrificed. The commercial opportunity here lies in segments where reliability translates directly into operational uptime, safety, or compliance, and where buyers are willing to pay for validated performance rather than lowest unit cost.
Trend 3: Lifecycle Strategy and Portfolio Continuity Will Influence Sourcing Decisions
With EOL announcements already prompting migration planning in select product lines, long-lifecycle customers will place greater weight on supplier roadmaps, transition support, and qualification continuity. This will favor suppliers that can provide clear availability signals and well-supported migration paths, especially for industrial and automotive projects with extended deployment horizons. For investors and manufacturers, this dynamic suggests that portfolio stability and lifecycle management are becoming competitive differentiators alongside technical performance.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market growth. Recurrence of portfolio pruning or EOL decisions could disrupt migration timelines for customers with limited second-source options. Consolidation activity may reshape support models and product availability, particularly if acquired assets are integrated unevenly across regions or application lines. In addition, shifts in automotive demand cycles, consumer electronics refresh patterns, and industrial capital spending could create uneven demand across segments, making precise forecasting more reliant on application-level intelligence than broad market aggregates.
PW Consulting
Strategic Actions for Decision-Makers
Given the interplay of precision requirements, lifecycle risk, and competitive realignment, decision-makers should approach the RTC market with a clear, application-aware strategy.
For Manufacturers and Product Teams
- Treat RTC selection as a system-level decision. Prioritize parts that combine low-power behavior, programmable outputs, and interface compatibility with your broader architecture to reduce firmware complexity and validation effort.
- Build migration readiness into design planning. Where long-lifecycle deployments are involved, assess second-source options and qualification continuity early to reduce exposure to portfolio changes or EOL transitions.
- Match qualification depth to application criticality. For automotive, industrial, or temperature-stressed environments, favor solutions with relevant qualification coverage and environmental performance rather than defaulting to the broadest catalog choice.
For Investors and Strategic Planners
- Focus on value capture in segments where precision, integration, and qualification create defensible differentiation. The most resilient opportunities are likely to be in application-specific timing support rather than commoditized volume alone.
- Monitor consolidation signals and their impact on portfolio coherence, support coverage, and innovation cadence. Acquisition activity can strengthen capability, but it also changes the competitive map and availability dynamics.
- Track demand nuance across end-use verticals. Automotive, industrial, and consumer electronics do not move in lockstep, and commercial outcomes will depend on how well stakeholders anticipate segment-specific refresh cycles and qualification requirements.
For Procurement and Supply Chain Leaders
- Strengthen continuity planning through transparent transition roadmaps. Where possible, work with suppliers that provide clear guidance on lifecycle status, migration assistance, and long-term availability.
- Balance cost efficiency with technical fit. In precision-sensitive or safety-relevant deployments, total cost of ownership should account for validation effort, environmental performance, and risk of redesign if migration becomes necessary.
- Use application-specific requirements as sourcing filters. Alarm support, leap year handling, dual-bus interfaces, and temperature-compensated accuracy should be evaluated against actual system needs to avoid over-engineering or under-specifying the timing chain.
The RTC market is entering a phase where technical performance, lifecycle stability, and application fit matter as much as scale. For organizations that need deeper granularity on regional dynamics, type-level splits, application-specific revenue trajectories, and tailored sourcing or investment recommendations, a more detailed research deep-dive is available. Readers seeking segment-level data, company-specific positioning, and customized market pathways can access the full research report for comprehensive breakdowns and decision-ready analysis.
For detailed analysis of this topic, please visit the official page: Real Time Clock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com