

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
NPK Fertilizer Market: Why 4.2% CAGR and Asia Pacific's 50% Share Redefine Growth

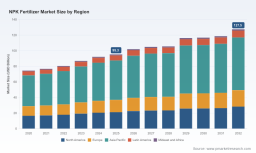
Global NPK Fertilizer Market: Navigating Growth, Disruption, and Strategic Realignment
The global NPK fertilizer market has entered a transformative phase, expanding from a valuation of $74.5 billion in 2020 to an expected $127.5 billion by 2032. This trajectory underscores a compound annual growth rate of 4.2 percent across the forecast horizon, driven by intensifying agricultural productivity demands and structural shifts in crop nutrition delivery. While the broad numbers signal steady expansion, the real story lies beneath the surface: evolving regulatory frameworks, supply chain recalibrations, and technological breakthroughs are reshaping competitive dynamics and redefining value creation across the sector.
For executives and investors, the market presents a paradox of opportunity and friction. Robust demand fundamentals are colliding with raw material volatility, policy interventions, and consolidation pressures. Understanding how these forces interact is no longer optional; it is a prerequisite for strategic positioning in a landscape where traditional growth levers are being supplemented, and in some cases displaced, by innovation and regulatory adaptation.
Market Landscape and Core Challenges
The NPK fertilizer sector has moved through a period of pronounced price and volume adjustment over the past half-decade. Revenue growth from 2020 through 2025 reflects a market that has largely recovered from pandemic-era disruptions while absorbing inflationary pressures on energy, freight, and raw material inputs. The forward outlook through 2032 suggests a market that will continue to expand, but with uneven momentum across regions and product formats. Rather than a uniform upswing, the growth pattern points to a maturing industry where efficiency, formulation quality, and supply reliability increasingly differentiate winners from laggards.
Worldwide Starter Fertilizer Market
Three structural challenges define the current inflection point:
- Raw material cost volatility and pass-through uncertainty. NPK production remains tightly linked to ammonia, phosphate, and potash markets, all of which are exposed to energy price swings, trade policy shifts, and logistics constraints. Recent price assessments in Northeast Asia have shown modest declines, yet the broader cost environment remains unpredictable. Manufacturers face a persistent tension between absorbing cost shocks and preserving margin integrity in a competitive pricing environment.
- Regulatory and policy recalibration. Governments are actively reshaping fertilizer markets through subsidy design, grade approvals, and duty structures. New NPK grades fortified with secondary and micronutrients have been incorporated into national soil fertility schemes, signaling a policy direction that favors nutrient efficiency and soil health over bulk commodity application. At the same time, trade adjustments, such as requests to reduce customs duties on specific phosphate products, reflect the ongoing balancing act between import dependence, domestic production, and farmer affordability.
- Consolidation and competition scrutiny. Rising concentration among NPK producers has drawn regulatory attention, with legislative bodies examining whether consolidation is contributing to price increases and limiting buyer choice. This scrutiny introduces a new layer of risk for market participants, particularly as mergers, acquisitions, and capacity realignments continue to reshape the industry footprint.
These challenges are not isolated stressors; they interact to shape pricing behavior, capacity decisions, and product strategy. Companies that treat them as isolated issues risk misallocating capital, while those that integrate them into a coherent strategic framework can convert volatility into differentiation.
Core Drivers Reshaping the Market
Beneath the headline growth figures, four interconnected drivers are accelerating change across the NPK fertilizer ecosystem.
Technological Innovation and Formulation Science
Innovation is moving beyond incremental tweaks to core production processes toward smarter delivery and enhanced nutrient utilization. Microbial coating technologies for mineral NPK fertilizers have progressed from research to commercial deployment, combining conventional nutrient blends with beneficial microorganisms designed to improve nutrient availability and field performance. This convergence of agronomic biology and traditional fertilizer chemistry represents a meaningful shift: the value proposition is increasingly tied to how effectively nutrients are absorbed and utilized, not merely how much is applied.
Parallel advances in liquid formulation capabilities are expanding the addressable use cases for NPK products. New liquid fertilizer plants focused on NPK-based blends are coming online, reflecting demand for precision application, compatibility with irrigation systems, and flexibility in customized nutrient programs. These developments suggest that product architecture, rather than volume alone, will be a critical determinant of competitive advantage in the coming years.
Policy and Regulatory Environment
Policy frameworks are becoming a more direct lever on market structure and product mix. The inclusion of fortified NPK grades with magnesium, zinc, boron, and sulfur in official soil fertility schemes illustrates a policy environment that is actively encouraging micronutrient integration and nutrient efficiency. Such moves create both compliance requirements and commercial opportunities, as manufacturers and distributors align their portfolios with approved grades and farmer expectations for balanced nutrition.
Trade policy and duty structures add another dimension. Requests to align customs duties on specific phosphate products with those applied to other NPK fertilizers highlight the sensitivity of import-dependent markets to cost pass-through and supply security. Companies operating across multiple jurisdictions must navigate a patchwork of subsidies, grade approvals, and tariff adjustments, where even modest policy changes can alter regional competitiveness and sourcing strategies.
Soluble Fertilizer Market
Demand-Side Evolution in Agriculture
수요侧 dynamics are shifting as growers and agricultural enterprises prioritize yield stability, soil health, and input efficiency over pure volume. Cereals and grains continue to anchor a large share of NPK consumption, but fruits, vegetables, and oilseeds and pulses are expanding their share of demand, reflecting diversified cropping patterns and higher-value production systems. This diversification increases the importance of tailored formulations, as different crops and growth stages require distinct nutrient balances and delivery methods.
The commercial adoption of biofertilizer production capacity further signals that demand is broadening beyond conventional NPK. Integration of biologicals with mineral nutrient programs is gaining traction among producers seeking to enhance nutrient use efficiency and meet sustainability expectations. For NPK suppliers, this trend creates an opportunity to participate in integrated crop nutrition solutions rather than competing solely on commodity-grade pricing.
Supply Chain and Cost Structure Realignment
Cost structures are being redefined by capacity decisions, logistics optimization, and vertical integration. Major nitrogen and phosphate producers are adjusting output in response to raw material market conditions, with some facilities scaling back production or withdrawing forward guidance amid uncertainty. These capacity moves have ripple effects across the supply chain, influencing availability, pricing expectations, and contract negotiations for downstream blenders and distributors.
At the same time, regional production footprints are expanding to serve localized demand more efficiently. New liquid fertilizer facilities and biofertilizer production sites are being established in strategic locations, reducing dependency on long-distance logistics and enabling faster response to regional crop cycles. This localization trend is particularly relevant in markets where import reliance and duty structures create cost differentials, as domestic or near-shore capacity can improve supply resilience and margin stability.
Competitive Landscape and Strategic Positioning
The NPK fertilizer market is characterized by a concentrated group of large-scale producers alongside a growing set of specialized entrants and consolidators. Leading players are positioned around distinct operational strengths: global nitrogen and phosphate integration, broad distribution networks, mining and processing assets, and high-throughput ammonia capacity. These structural advantages provide scale, cost leverage, and product breadth, but they also require continuous adaptation as customer requirements and regulatory conditions evolve.
Differentiation is increasingly anchored in three areas:
- Product and process breadth. Companies with diversified production routes, including nitrophosphate and sulphuric acid processes, blended NPK retail networks, and concentrated phosphate and potash-based formulations, can respond more flexibly to regional grade requirements and crop-specific demand. The ability to supply a range of nutrient profiles, from granular to liquid formats, supports broader customer coverage and reduces exposure to single-format cyclicality.
- Geographic and supply chain reach. Multi-continent plant networks and regional complexes enable closer proximity to end markets, shorter response times, and greater control over logistics. This footprint is especially valuable where import duties, freight costs, and local grade preferences influence competitiveness.
- Innovation adjacency. Leaders are extending their positioning through complementary capabilities, such as microbial coating technologies and biofertilizer integration, while others are pursuing acquisitions of high-efficiency liquid NPK specialists. These moves signal a strategic shift from standalone fertilizer supply toward integrated nutrient solution providers.
The market landscape is evolving through both consolidation and fragmentation. On one hand, acquisitions and capacity realignment are concentrating production among fewer players, raising competition policy questions and influencing pricing dynamics. On the other hand, targeted greenfield investments in liquid and biofertilizer facilities, along with specialist acquisitions, are introducing new capabilities and niche focuses. This dual movement creates a more nuanced environment: scale remains important, but agility, formulation expertise, and local market execution are becoming equally decisive.
Recent industry activity illustrates this realignment in practice. Commercial launch of microbial coating technology for mineral NPK fertilizers after extended research demonstrates the move from concept to market-ready solutions. Capacity adjustments at phosphate facilities in response to volatile raw material conditions highlight the discipline required to manage output and outlooks in an uncertain cost environment. Groundbreaking on biofertilizer production facilities and inauguration of new liquid fertilizer plants reflect investment in adjacent capabilities that support NPK-based integration. Acquisitions of high-efficiency liquid NPK specialists point to a strategy of capturing specialized formulation expertise and expanding product reach. Together, these developments suggest a market where competitive advantage will be built on the combination of scale, formulation quality, and biological innovation.
Future Trends and Strategic Implications
Looking ahead over the next three to five years, three trends are likely to shape the NPK fertilizer market and open distinct commercial pathways.
Precision-Enabled Nutrient Solutions Will Redefine Value
The convergence of advanced formulation, biologicals, and application precision is shifting competition from input volume to nutrient effectiveness. Expect continued adoption of fortified grades, liquid formats, and microbial-enhanced products as growers and agronomic advisors seek better nutrient use efficiency and more consistent field outcomes. Commercial opportunity will accrue to players that can offer credible performance data, customized grade recommendations, and integrated advisory support rather than relying on commodity marketing alone.
Policy-Driven Portfolio Alignment Will Become a Strategic Necessity
As governments refine fertilizer schemes, approve new fortified grades, and adjust trade duties, market access and pricing will increasingly depend on portfolio alignment with regulatory expectations. Companies that proactively redesign product mixes, secure approvals for micronutrient-fortified blends, and optimize sourcing against duty structures will be better positioned to protect margins and maintain market share. Failure to align with evolving policy frameworks can create avoidable cost penalties and limit distribution access in key regions.
Capacity Realignment and Regionalization Will Reshape Supply Dynamics
Output curtailments, selective greenfield investments, and specialist acquisitions indicate a market that is repositioning capacity toward regional demand, cost-efficient formats, and higher-value product segments. This realignment can improve supply resilience where local production replaces long-distance imports, but it also introduces execution risk and capital intensity. Participants must balance the benefits of localized capacity with the realities of raw material exposure, energy economics, and demand variability across crop cycles.
These trends carry inherent uncertainty. Policy directions can shift with political and fiscal priorities, raw material markets can disrupt cost assumptions, and competitive consolidation may attract further regulatory scrutiny. Additionally, adoption of biological and precision-enhanced products depends on farmer acceptance, demonstration of consistent field performance, and distribution capability. Companies that build scenario flexibility into their planning and maintain close monitoring of policy, cost, and demand signals will be better prepared to navigate this complexity.
PW Consulting
Actionable Guidance for Decision-Makers
For manufacturers and producers, the strategic imperative is to strengthen formulation flexibility and innovation adjacency while managing raw material exposure with disciplined capacity planning. Prioritize product architectures that support fortified grades, liquid formats, and biological integration where market demand and regulatory frameworks justify the investment. Align sourcing and production footprints with regional grade requirements and duty structures to improve margin stability and supply reliability. Use performance-led differentiation and agronomic support to reduce reliance on price-only competition.
For investors, the opportunity set is expanding beyond traditional volume plays into formulation quality, biological integration, and regional capacity repositioning. Evaluate assets and companies on the basis of their ability to execute fortified and liquid product strategies, manage cost volatility, and navigate regulatory alignment across jurisdictions. Pay close attention to consolidation dynamics and policy developments, as these can influence both pricing power and market access. Diversification across formats and geographies, combined with exposure to efficiency-enhancing technologies, can provide a more resilient growth profile.
For procurement and distribution leaders, supplier selection should increasingly factor in formulation adaptability, product certification against evolving grade schemes, and supply chain resilience in the face of raw material and logistics variability. Negotiate with an eye on grade diversification and application flexibility, ensuring access to fortified and liquid options that match crop-specific needs. Monitor policy changes that affect duty structures and approved grades, as these can alter cost expectations and availability. Building supplier relationships that support integrated nutrient programs, rather than single-grade transactions, can improve performance outcomes and reduce exposure to price shocks.
For decision-makers seeking to convert these insights into concrete strategy, the complexity of the NPK fertilizer market rewards deeper, segmentation-specific intelligence. Detailed demand patterns, regional grade adoption timelines, raw material cost scenarios, and competitive move tracking all matter when translating trends into capital allocation, portfolio design, and sourcing decisions. In that context, PW Consulting's comprehensive NPK fertilizer market research report offers a structured, data-supported foundation for those decisions, providing granular segmentation detail, country-level dynamics, and scenario analysis that extend well beyond the strategic overview presented here.
For detailed analysis of this topic, please visit the official page: NPK Fertilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com