

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Residential Air Purifiers Market Set for 7.5% CAGR Growth Through 2032 Strategic Shifts

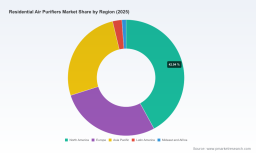
Residential Air Purifiers Market: Strategic Trends and Commercial Opportunities in a Maturing Sector
The residential air purifiers market has transitioned from a niche wellness accessory to a mainstream household essential, driven by escalating awareness of indoor air quality, urbanization pressures, and technological maturation. Valued at approximately $12.06 billion in 2025, the market has expanded at a compound annual growth rate of roughly 7.5 percent from 2020 through the forecast horizon extending to 2032, when projected revenues are expected to approach $20.02 billion. This trajectory reflects more than incremental consumer adoption; it signals a structural shift in how households, builders, and health-conscious buyers perceive the value of controlled indoor environments. For executives and investors, the opportunity lies not merely in capturing volume growth, but in navigating a sector where differentiation, regulatory alignment, and ecosystem integration increasingly dictate competitive advantage.
Market Landscape and Critical Inflection Points
Scale, Growth Trajectory, and Hidden Tensions
The market’s expansion has been steady rather than explosive, with annual revenue climbing from $8.29 billion in 2020 to $12.06 billion in 2025. The projected path to $20.02 billion by 2032 implies sustained demand, but the growth composition reveals underlying tensions. Portable units dominate volume, reflecting consumer preference for flexible, point-of-use solutions that require minimal installation and allow room-by-room deployment. Fixed in-duct systems occupy a smaller share, constrained by retrofit complexity, builder-dependent distribution, and higher upfront capital requirements. On the technology side, HEPA-based filtration remains the anchor of consumer trust and regulatory compliance, while activated carbon and ionic alternatives serve niche performance or odor-focused applications. The presence of a substantial "other" technology category indicates ongoing experimentation with hybrid, photocatalytic, and advanced media approaches, though none have yet displaced the HEPA benchmark at scale.
Air Purifiers Market
Market concentration remains pronounced, with the top three players accounting for roughly 65 percent of revenue and the top five capturing approximately 75 percent. This structure points to established brand equity, channel control, and economies of scale that create meaningful barriers for late entrants. Yet high concentration does not equate to stagnation. The concentration is increasingly contested at the edges by brands that leverage smart connectivity, targeted use-case positioning, and direct-to-consumer channels to carve out defensible niches.
Three Pressing Challenges Shaping the Next Cycle
First, product performance validation and consumer trust are under renewed scrutiny. Recent regulatory and safety actions, including a major recall of certain air purifier units due to fire and burn hazards, underscore that performance claims must be matched by rigorous quality control, transparent testing, and post-market monitoring. Brands that rely on marketing-led positioning without robust engineering validation face growing exposure as consumer literacy and regulator attention rise.
Second, energy efficiency and compliance are becoming structural cost and design constraints. Regulatory frameworks across major markets are tightening, with new conservation standards phasing in and harmonized efficiency expectations spanning North America. These requirements compress the design space for airflow, noise, and power consumption, forcing manufacturers to balance filtration effectiveness with operating cost and user experience. The companies that treat compliance as a design parameter rather than a late-stage checkbox will secure lower total-cost-of-ownership profiles and smoother market access.
Third, the category is experiencing segmentation fatigue and value confusion. Consumers are confronted with overlapping claims around HEPA grades, carbon capacity, ion generation, sensor accuracy, and app integration. This proliferation complicates purchase decisions, elevates return rates when expectations misalign with real-world performance, and pressures margins as brands compete on features that may not translate into meaningful differentiation. The challenge for incumbents and challengers alike is to simplify value communication while still delivering measurable performance gains.
Core Drivers Reshaping Demand and Competitive Dynamics
Technology Innovation as a Performance and Experience Lever
The most consequential technological shift is the convergence of high-efficiency filtration with real-time sensing and controlled delivery. HEPA remains foundational, but the next layer of value is being added through formaldehyde and VOC sensing, particulate monitoring, adaptive fan control, and connectivity that enables usage tracking and filter lifecycle management. Recent product launches illustrate this direction: new plug-and-play models with dedicated app connectivity are reducing installation friction while expanding the sensor-and-control layer, and award-recognized designs are targeting previously underserved use cases such as pet hair and dander management. These innovations do not merely add features; they change the value proposition from static cleaning to managed air quality over time, which opens recurring revenue possibilities through filter subscriptions, service dashboards, and performance guarantees.
Household Air Purifiers Market
Regulatory and Standards Environment: From Gatekeeper to Differentiator
Regulatory dynamics are transitioning from passive compliance to active strategic planning. Energy conservation standards are escalating in tiers, with later-phase requirements effective at the end of 2025 and harmonized proposals extending similar expectations to products manufactured in Canada from the same timeframe. In parallel, certification and indoor air cleaning device requirements in certain states have long influenced product eligibility, reinforcing the importance of third-party validation and transparent performance data. The strategic implication is clear: energy efficiency, safety, and certified performance are no longer optional add-ons; they are preconditions for distribution, retailer confidence, and consumer trust. Firms that embed these requirements into product architecture early gain speed to market, lower rework risk, and stronger positioning with procurement teams and channel partners.
Demand-Side Shifts Toward Health, Pet Care, and Smart Homes
Consumer behavior is increasingly shaped by health sensitivity, pet ownership growth, and the broader smart home ecosystem. Households are treating indoor air quality as part of a proactive wellness routine rather than a reactive response to visible pollution. This shift favors products that offer intuitive interfaces, automated operation, and perceptible performance feedback, because users are more likely to sustain usage when they can see and understand the outcome. Pet-focused designs have emerged as a distinct demand pocket, reflecting the need for hair capture, odor reduction, and quiet continuous operation in living spaces. Simultaneously, integration with home automation platforms appeals to buyers who value centralized control and data continuity, pushing manufacturers to think beyond the appliance as an isolated device and toward its role in a connected environment.
Supply Chain and Cost Structures: Balancing Performance and Affordability
Cost pressure remains a persistent factor, especially as multi-stage filtration, sensors, and connectivity components raise bill-of-materials complexity. The market’s breadth—from value-oriented core series to premium high-capacity systems—demonstrates that segmentation is partly a response to these economics. Manufacturers are navigating a trade-off between filtration depth and price accessibility, while also managing component availability, filter replacement economics, and warranty exposure. The strategic response is increasingly modular: standardize core filtration and airflow architectures, then layer targeted features, sensor packages, and brand-specific design language to serve distinct price points without fragmenting production efficiency. This approach helps preserve margin while allowing brands to address multiple consumer segments from a shared engineering base.
Competitive Landscape and Strategic Positioning
Incumbents Anchored in Filtration Credibility and Ecosystem Reach
Honeywell International Inc. continues to leverage its home comfort heritage, pairing HEPA filtration with smart air quality sensors to position its residential offerings within the broader comfort and ventilation narrative. This framing connects air purification to a familiar household category and benefits from an established brand footprint and cross-selling pathways. IQAir North America, Inc. pursues a premium angle, emphasizing HEPA and activated carbon systems with app connectivity, an approach that targets performance-sensitive buyers willing to pay for perceived filtration superiority and connected control. LG Electronics, Inc. differentiates through intelligent room air purifiers that combine HEPA with UV-C technologies, aligning purification with broader appliance intelligence and design language familiar to its consumer base. Panasonic Corporation emphasizes advanced cleaning systems built around nanoe and HEPA mechanisms, a positioning that highlights proprietary ionization-adjacent technologies alongside conventional filtration. Sharp Corporation competes with plasmacluster ion-based purifiers, offering an alternative performance narrative that appeals to buyers interested in active particle control beyond mechanical capture.
Specialists, Challengers, and Use-Case Focused Entrants
Dyson Ltd. has built a strong presence through HEPA H13 filtration paired with formaldehyde-sensing technologies, combining rigorous filtration claims with a design-forward, technology-rich identity that resonates in higher-income segments. Coway Co., Ltd. has gained traction with its Airmega series, emphasizing advanced multi-stage filtration for home use and a track record of performance-oriented marketing. Winix Inc. focuses on multi-stage filtration air purifiers, targeting value-conscious buyers who still want layered contaminant capture. Austin Air Systems and RabbitAir occupy higher-capacity and multi-layer niches, appealing to consumers seeking robust filtration volume or specialized coverage, with messaging that appeals to dedicated indoor air quality advocates. Levoit has expanded recognition through core and vital series that integrate smart features, demonstrating how accessible price points can coexist with connected functionality and broad retail distribution. AirDoctor and Molekule both emphasize HEPA-based smart air cleaning, though with distinct brand narratives and feature sets that illustrate how even closely positioned products can pursue separate audience segments. Blueair brings a design-centric, Swedish-engineered filtration identity that supports a premium-but-accessible positioning in selected markets. At the more specialized end, Dreame Technology has targeted pet hair removal with its Furcatch series, and its recognition with a CES 2026 innovation award in the home appliances category signals how use-case focus and design innovation can accelerate visibility in a crowded field.
PW Consulting
How the Landscape Is Evolving
The market is not simply consolidating around a few giants; it is simultaneously consolidating at the top and fragmenting at the edges. The leaders defend share through brand trust, channel relationships, and scale-efficient filtration platforms. The challengers and specialists attack with sharp use-case positioning, smart features, and direct engagement with consumer communities that value specific outcomes such as pet management, quiet operation, design compatibility, or app-driven control. This dual dynamic means that market share battles are increasingly won in segments rather than across the category as a whole. New entrants can succeed without dislodging incumbents broadly if they solve a well-defined problem better than the generalist alternatives and build credible validation around that claim. At the same time, the bar for entry is rising because energy, safety, and certification expectations now touch every price tier, and recall risk or performance overstatement can quickly erode consumer confidence.
Forward Outlook: Three Trends Defining the 2026–2030 Window
Trend One: Managed Air Quality Over Standalone Cleaning
The next phase will increasingly reward products that function as managed systems rather than one-time purchases. Sensor accuracy, adaptive operation, filter lifecycle visibility, and app-based feedback will become baseline expectations in many markets, especially as smart home penetration deepens. For commercial strategy, this trend shifts competition toward reliability of measurement, clarity of user communication, and the ability to sustain engagement across the product lifecycle. Recurring value can be built through subscription filter programs, maintenance reminders, and performance summaries, provided these services are tied to genuine user benefit rather than feature bloat.
Trend Two: Compliance-Driven Engineering as a Competitive Moat
As efficiency and safety requirements phase in, only products designed around these constraints from the outset will maintain competitive cost structures and broad market access. The moat will belong to manufacturers that can deliver high filtration performance without exceeding power, noise, and thermal limits, and that can document compliance in ways that streamline retailer and regulatory acceptance. This creates an advantage for engineering-led organizations with disciplined validation processes and for brands that can translate compliance into consumer-facing value, such as lower operating cost, quieter operation, and credible performance certification.
Trend Three: Use-Case Specialization as a Path to Growth With Manageable Risk
Generalized claims are losing persuasiveness in a crowded market, while targeted solutions are gaining traction because they reduce purchase ambiguity and improve perceived relevance. Pet-focused designs, allergy-oriented configurations, and room-specific form factors are likely to remain productive growth avenues, especially when paired with credible testing and clear benefit communication. The risk in this approach is over-narrow positioning that limits scale potential or duplication of features that consumers do not value enough to pay for. Successful specialization will balance a defined primary use case with enough multi-function flexibility to justify the purchase in varied household environments.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
- Treat energy, safety, and certification requirements as core design inputs rather than end-of-cycle compliance tasks, so that efficiency, noise, and thermal performance are optimized alongside filtration depth.
- Build modular platforms that separate the filtration and airflow core from sensor, app, and aesthetic differentiation layers, enabling multiple price points and use-case variants without compounding engineering overhead.
- Strengthen validation and transparency around performance claims, including real-world usage scenarios and filter replacement economics, to reduce returns, protect brand trust, and support premium positioning where justified.
For Investors and Strategic Capital Allocators
- Favor companies that demonstrate repeatable engineering discipline in meeting evolving efficiency and safety standards, because these firms face lower rework risk and smoother access to regulated channels.
- Assess the durability of differentiation beyond marketing claims, looking for credible testing, defensible sensor and filtration architectures, and evidence that smart features increase retention or lifetime value rather than merely inflating initial price.
- Watch for consolidation opportunities where specialized brands with strong use-case loyalty can be integrated into broader platforms, or where incumbents can acquire targeted capabilities in connectivity, validation, or niche performance segments.
For Procurement, Channel, and Retail Decision Makers
- Prioritize products with clear certification status, documented efficiency performance, and transparent filter replacement costs, since total cost of ownership and post-purchase support increasingly influence consumer satisfaction and repeat purchase behavior.
- Evaluate category assortment by use case and price tier rather than by brand alone, ensuring that pet-focused, allergy-oriented, and smart-integrated options are positioned where shoppers can compare them against relevant alternatives.
- Track safety and recall signals actively, and align vendor selection with brands that demonstrate robust quality systems, because trust in this category is fragile and can shift quickly when performance or safety concerns surface.
The residential air purifiers market is moving into a phase where growth is real but discriminating. Scale alone will not secure advantage; the winners will be those who combine credible filtration performance with aligned efficiency and safety profiles, clear use-case relevance, and smart functionality that sustains user engagement. For executives and investors, the highest-value intelligence lies in segment-level demand nuances, platform economics, regulatory timing, and the specific validation standards shaping procurement decisions. The full research report expands on these themes with detailed segmentation data, regional dynamics, and customized strategic scenarios to support planning with greater precision.
For detailed analysis of this topic, please visit the official page: Residential Air Purifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com