

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automotive Windshield Washer Fluid Market: Why 4.9% CAGR and OEM Dynamics Redefine Growth

Strategic Trends and Commercial Opportunities in the Automotive Windshield Washer Fluid Market
Market Overview: Size, Trajectory, and Structural Dynamics
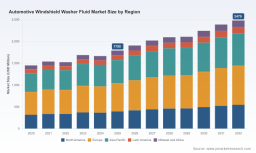
The global automotive windshield washer fluid market has entered a phase of measured expansion, driven by steady vehicle parc growth, seasonal maintenance cycles, and incremental performance requirements tied to visibility and safety standards. Valued at approximately USD 1,790 million in 2025, the market reflects a compound annual growth rate of 4.9 percent across the forecast horizon through 2032, reaching an estimated USD 2,479 million by the end of the period. The trajectory from 2020 through 2025 illustrates consistent demand recovery following early-pandemic disruptions, with 2023 marking a local peak before a modest recalibration in 2024 that aligned with broader supply chain normalization and inventory adjustments. Growth through the mid-2020s is expected to be supported by replacement fluid consumption, fleet maintenance schedules, and geographic expansion in regions where vehicle ownership continues to rise.
One of the defining structural features of the market is its concentration. The top three participants collectively account for roughly 55 percent of revenue, while the top five capture approximately 65 percent. This level of consolidation indicates that scale advantages, distribution reach, and brand recognition remain critical barriers to entry, yet the remaining share is distributed across specialized manufacturers, regional suppliers, and emerging formulation innovators. The presence of both global consumer brands and regional specialists creates a dual dynamic: incumbents compete on breadth, shelf presence, and OEM relationships, while newer or niche players differentiate through formulation specifics, sustainability positioning, and concentrated products designed to lower logistics and packaging costs.
Current market dynamics are shaped by several intersecting pressures. Raw material volatility remains a persistent concern, particularly for alcohol-based formulations where methanol, ethanol, and glycol derivatives influence both performance and cost. Simultaneously, regulatory frameworks in key markets are tightening limits on volatile organic compounds, pushing manufacturers to reconsider ingredient choices, packaging formats, and dilution pathways. Consumer and fleet purchasing behavior is also evolving, with a growing preference for multi-season reliability, reduced streaking, and formulations that perform reliably under extreme temperature conditions. These factors combine to make the market less about pure volume and more about formulation precision, compliance readiness, and channel control.
Key Challenges and Inflection Points
The first central challenge is regulatory compliance and its cascading effect on formulation strategy. Stricter VOC controls in sensitive air basins are forcing suppliers to redesign products without sacrificing cleaning efficacy or freeze protection. This is not a simple substitution exercise; it requires reformulation, testing, and sometimes changes in packaging or concentrate dilution logic to preserve performance while meeting legal thresholds. Companies that rely on legacy recipes face the risk of undergoing costly redesign cycles while competitors already advanced in low-VOC architectures can capture shelf space and procurement approvals more quickly.
The second inflection point is the changing meaning of visibility within vehicle safety programs. As safety rating frameworks for newer model years increasingly incorporate advanced driver-assistance technologies and crash-avoidance features, forward visibility has gained a more direct link to vehicle performance evaluation. Washer fluid is no longer only a maintenance consumable for cleanliness; it becomes part of a broader visibility ecosystem. That shift raises the stakes for fluid clarity, anti-smearing characteristics, and compatibility with sensor and camera cleanliness expectations, especially in commercial fleets and higher-end passenger vehicles.
The third challenge is supply chain and cost structure variability. The washer fluid segment is sensitive to feedstock pricing, freight costs, and regional production footprints. While the market is not as complex as powertrain components, it still depends on chemical sourcing, blending capacity, and distribution efficiency. In concentrated product models, logistics economics improve, but dilution instructions, consumer education, and seasonal storage behavior become more important to manage. For aftermarket-focused suppliers, inventory turnover and regional demand swings can amplify working capital pressure, especially when weather patterns shift purchasing timing across territories.
Key Growth Drivers
Technology and formulation innovation continue to be a primary driver. Suppliers are moving beyond basic cleaning toward fluids that combine anti-icing performance, water repellency, bug removal, and reduced residue. This evolution reflects a broader push to address multiple pain points in a single fill, which resonates with both retail consumers and fleet managers seeking simpler maintenance routines. The recent progress in ethanol-based and methanol-free formulations is particularly noteworthy. By 2030, such safer or lower-toxicity variants are projected to represent a meaningful share of new product launches, up from a smaller base in the mid-2020s. This trend is not just regulatory; it is also customer-facing, as end users and procurement teams increasingly value reduced handling risk, environmental messaging, and safer storage conditions.
Policy and regulatory dynamics are reshaping formulation priorities and time-to-market. VOC limits in certain jurisdictions are effectively setting a new baseline for pre-mixed and diluted products. Compliance is no longer optional; it determines which products can be sold in specific regions and which can remain on shelf year-round. At the same time, visibility-related safety expectations are connecting washer fluid performance to broader vehicle assessment criteria, encouraging manufacturers to invest in cleaning reliability and residue control. These regulatory and safety-linked developments are raising the technical bar and rewarding companies that can align product design with regional rules and fleet requirements.
Demand-side changes are reinforcing the shift toward multi-function and season-ready fluids. Vehicle owners and fleet operators increasingly seek products that reduce the number of specialized purchases and simplify stocking. In colder climates, anti-freeze performance remains non-negotiable, while in warmer or insect-heavy environments, bug-removing and water-repelling characteristics carry more weight. The emergence of concentrated formats and tablet-based options is a response to consumer interest in storage efficiency, reduced plastic use, and flexible dilution. This demand is especially visible where aftermarket purchasing remains the dominant channel, as individual buyers and small operators look for convenience, lower bulk weight, and clearer performance claims.
Supply chain and cost structure evolution is also a driver, though not always in an obvious way. The market is increasingly influenced by regional production strategies, ingredient substitution, and packaging decisions that affect landed cost and margin. Suppliers with flexible blending capacity and a mix of ready-to-use and concentrated offerings tend to respond more effectively to regional demand changes. Meanwhile, distribution partnerships and online automotive ecosystems are expanding the number of touchpoints where fluids are purchased, creating both revenue opportunities and execution complexity for manufacturers trying to maintain consistent product availability and regional compliance.
Competitive Landscape and Leading Strategies
The market’s competitive set is diversified but unevenly positioned. Several U.S.-based suppliers dominate consumer-facing visibility through strong brand recognition, broad retail distribution, and product lines that span all-season, de-icer, and extreme-weather variants. One leading aftermarket provider has emphasized next-generation fluids designed for extreme temperatures with enhanced cleaning and anti-icing properties, reflecting a strategy focused on performance differentiation in the most demanding use cases. Another major U.S. brand has built a distinct identity around two-in-one all-season and extreme-weather products for consumer and fleet use, leveraging a familiar consumer brand that resonates with visibility and water-beading benefits.
Global industrial suppliers add a different layer of competition. One multinational group competes across multiple channels with advanced formulations tied to visibility and cleaning performance, often positioning its products as part of a broader portfolio of specialty materials and automotive maintenance solutions. A German specialist has carved out a premium angle with concentrates and all-weather solutions that emphasize eco-friendly positioning and high-performance use, appealing to customers willing to pay for formulation quality and targeted application formats. A Canadian aftermarket provider adds scale and breadth, distributing transportation chemicals and washer fluids across OEM and replacement channels, which gives it reach and flexibility in multiple geographies.
Asian participation is becoming increasingly important. A Japanese manufacturer is known for all-season and glass cleaner products that align with quality-conscious consumer expectations and detailed formulation work. A Chinese producer offers concentrated and ready-to-use formulations for export, reflecting the growing role of cost-efficient manufacturing and regional sourcing in global supply. In parallel, integrated energy and specialty fluid players supply washer fluid as part of wider lubricants and fluids portfolios, using existing relationships with service outlets and mobility customers to maintain distribution leverage.
Recent market activity illustrates how this landscape is evolving. In early 2025, a leading aftermarket provider announced a next-generation washer fluid targeting extreme temperatures with improved cleaning and anti-icing performance, signaling a push to defend premium shelf space and address the most seasonally sensitive demand. Later in the year, a specialist introduced a dedicated line for the Indian aftermarket focused on passenger vehicles with all-season performance, an example of regional customization in a fast-growing vehicle market. Around the same time, a major e-commerce platform expanded its automotive ecosystem by integrating washer fluid and related products into a broader car initiative, showing how digital distribution can reshape retail access and product bundling.
Strategic differentiation is tending toward one of three paths. The first is performance specialization, where companies target extreme cold, insect buildup, or streak-free clarity and build product narratives around those use cases. The second is compliance and sustainability leadership, where reformulation toward lower-toxicity ingredients and tighter VOC adherence becomes a market advantage, especially in regions where rules are strict and procurement standards are evolving. The third is channel and format innovation, using concentrates, tablets, bulk supply, and digital platform partnerships to improve margin economics, reduce packaging, and reach buyers where they increasingly shop. None of these paths is exclusive, but the strongest players tend to combine at least two, aligning product design with the channels and regulatory contexts where they operate.
PW Consulting
Future Trends and Commercial Implications
Over the next three to five years, one clear trend is the continued acceleration of cleaner, safer formulations. Ethanol-based and methanol-free entries are expected to grow in new launches, reflecting both regulatory pressure and shifting buyer expectations. This creates an opportunity for suppliers that can demonstrate performance parity or superiority at lower toxicity, particularly for fleets, retail chains, and OEM-linked service networks that must manage handling, storage, and disposal considerations alongside cleaning performance. Companies that treat formulation as a brand and compliance asset, rather than just a cost variable, are likely to gain an edge in specification conversations and shelf placement.
Worldwide Windshield Washer Nozzle Market
A second trend is the growing linkage between visibility and vehicle safety expectations. As safety rating and crash-avoidance frameworks place more emphasis on forward visibility and sensor cleanliness, washer fluids will be judged not only on how well they clean glass, but also on how reliably they support clear, residue-free viewing conditions. This creates commercial opportunities for fluids with stronger anti-smearing claims, better dirt-release properties, and compatibility with vehicle systems that depend on unobstructed sightlines. It also raises a caution: products that deliver short-term cleaning but leave residue or cause smearing may face increasing scrutiny in professional and premium segments.
A third trend concerns distribution and format evolution. Concentrates, dilution controls, tablets, and online automotive marketplaces are expanding the ways fluids reach end users. For manufacturers, this means better control over shipping weight and packaging costs, but also a need to manage consumer dilution behavior and ensure that performance remains consistent after mixing. For retailers and fleet buyers, the opportunity lies in simplifying inventory and reducing storage footprint while maintaining seasonal readiness. The risk is fragmentation: as formats multiply, channel confusion and mixing errors can erode trust unless instructions, labeling, and education are handled carefully.
There are also uncertain factors worth monitoring. Weather variability can shift seasonal purchasing patterns and make demand less predictable in some regions. Feedstock pricing and regional chemical availability can affect margins and formulation economics. Regulatory adoption may differ across jurisdictions, creating a patchwork of compliance obligations that complicates product rollout. Finally, consolidation pressure may intensify as larger players seek to secure shelf space, distribution agreements, and OEM-linked supply, while smaller specialists either niche down or scale through partnerships.
Actionable Recommendations for Decision-Makers
For manufacturers and brand owners, the priority is to treat formulation as a multi-dimensional asset. That means aligning product development with regional VOC requirements, building a credible performance story around cleaning, freeze protection, and residue control, and preparing a mix of ready-to-use and concentrated formats to suit different channels and cost structures. Launch timing matters too: seasonal demand spikes reward reliable supply and clear labeling, while regulatory changes reward early reformulation and testing. Companies should also assess where premiumization can be sustained versus where price competition will compress margins, and then allocate innovation spend accordingly.
For investors and strategic partners, the value lies in identifying businesses that combine compliance readiness, distribution strength, and formulation differentiation. Markets with a 4.9 percent growth trajectory through the end of the decade do not reward undifferentiated commodity positioning; they reward players that can hold shelf space, respond to regional regulation, and manage supply chain variability. Due diligence should examine formulation pipelines, regional compliance exposure, channel mix between aftermarket and OEM-related supply, and the ability to scale concentrates or eco-oriented variants without sacrificing performance. Portfolio alignment with visibility-linked safety expectations can also be a differentiating factor.
For procurement teams and fleet operators, the practical focus should be on standardization, safety, and total cost rather than lowest unit price alone. Standardizing on fluids that meet regional compliance requirements and perform across seasons can reduce SKU complexity, storage risk, and off-spec cleaning issues. Concentrated options may lower logistics and storage costs, but they require disciplined dilution practices and clear staff training. Where advanced visibility expectations matter, procurement should prioritize products with demonstrable anti-smearing and residue-control performance, especially for vehicles where clean windshields and sensor visibility support operational safety.
Worldwide Heated Wiper Fluid Market
As the market matures, the competitive edge will increasingly depend on localized formulation intelligence, regulatory foresight, and channel-specific product architecture. Readers looking for deeper segmentation data, regional deployment patterns, and tailored commercial scenarios can explore the full research report for a more detailed view of subsegments, regional dynamics, and company-level positioning.
For detailed analysis of this topic, please visit the official page: Automotive Windshield Washer Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com