

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Phosphate Ester Market Hits $2,285.0M in 2025, Forecasted to Hit $3,298.4M by 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Phosphate Ester Market: Navigating Growth from 2026 and Beyond
The global phosphate ester market is entering a decisive inflection point. As industrial demand reshapes around performance chemistry, regulatory tightening, and sustainability mandates, executives need more than headline figures to chart their next move. Our latest market research provides a rigorous, decision-ready assessment of the sector, grounding strategic planning in a complete historical baseline and a structured ten-year outlook. This article previews the analytical architecture of the study, explains why the 2026–2032 window matters for capital allocation and product strategy, and outlines the operational intelligence embedded in the full report.
For strategy leaders, the question is no longer whether phosphate esters will continue to matter across flame retardants, lubricants, hydraulic fluids, plasticizers, and specialty surfactants. The question is where value will concentrate, which application segments will command pricing power, and how supply-side dynamics will reshape competitive positioning. The research is built to answer those questions with granularity while keeping the focus on actionable strategy rather than static description.
A Market at Scale: Tracking the Trajectory into 2026
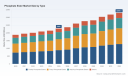
The sector has demonstrated consistent expansion across the historical review period, with total market revenue climbing from approximately 1,880 million USD in 2020 to an estimated 2,285 million USD in 2025. That progression reflects more than steady increments; it signals a market absorbing new performance requirements, replacing legacy chemistries in selective applications, and benefiting from broader industrial activity across multiple end-use verticals.
The forward view reinforces the strategic importance of this window. The market is projected to reach roughly 2,371 million USD in 2026, with continued expansion through the forecast horizon and a valuation approaching 3,298 million USD by 2032. The implied compound annual growth rate of 5.4 percent frames phosphate esters as a mature-but-energized category: growth is not explosive, but it is durable and increasingly tied to performance differentiation, formulation innovation, and regional supply reconfiguration.
For 2026 decision-making, that trajectory has direct consequences. Budget cycles, capacity planning, and partnership strategy must account for a market that is large enough to support specialized investments yet varied enough that aggregate growth can mask divergent segment fortunes. Our study treats growth as a starting point for deeper allocation logic rather than a standalone headline.
Why 2026 Is a Pivotal Planning Year
2026 functions as both a baseline and a branching point. Several forces are converging at once: evolving end-user requirements in mobility and industrial fluids, heightened scrutiny of chemical sourcing and emissions, and a competitive landscape in which scale players and specialty specialists are pursuing different value-creation models. Executives who treat the market as monolithic risk overinvesting in commoditized lanes or underweighting higher-margin application territories.
The strategic opportunity lies in understanding where the 5.4 percent trajectory is being generated and where it is likely to accelerate or compress. Some application areas benefit from regulatory-driven substitution and safety mandates; others gain from efficiency demands in lubrication and hydraulic systems; still others are shaped by formulation trends in coatings, inks, and consumer-facing formulations. The report maps these pathways in a way that supports product portfolio choices, regional prioritization, and customer engagement strategy.
Phosphate Ester Market
Equally important, the forecast period spans a decade of transition. That long view matters because phosphate ester investments often involve extended commercialization timelines, technical validation, and supply chain qualification. A 2026 decision can shape cost structure and market access well into the late 2020s. The study is designed to help leaders connect near-term actions with longer-cycle outcomes.
Inside the Report: Operational Intelligence for Strategy and Execution
The research is structured to move from market scaffolding to implementation detail. It begins with a full historical reconstruction and a disciplined forecast framework, then moves into segmentation, competitive positioning, and the operational factors that determine execution risk. The emphasis is on usable intelligence: what to monitor, what to benchmark, and where to focus commercial attention.
Key report components include:
- A complete market size and forecast framework with a decade-long view that links historical performance to forward projections, enabling scenario planning around base, upside, and constrained demand conditions.
- A structured analysis of value creation by product type and by application, showing how different segments contribute to the overall market and where differentiation, pricing behavior, and demand momentum diverge.
- Regional market assessment that examines demand centers, supply imbalances, trade exposure, and the strategic implications of shifting manufacturing and sourcing patterns.
- Competitive profiling of leading participants, with attention to product platforms, application focus, production footprint, and the ways companies are positioning for specialty growth versus scale efficiency.
- Market concentration context and the implications for pricing, negotiation leverage, and entry strategy in segments where leading suppliers hold meaningful share.
- Supply-side and feedstock dynamics, including precursor cost behavior, raw material exposure, and the operational sensitivities that influence margin stability.
- Regulatory and trade developments that alter cost structures, market access, and compliance requirements, with practical implications for sourcing and export strategy.
- Recent corporate developments that signal where industry capacity, technology, and application focus are moving, including partnerships, product launches, and acquisitions that reshape regional or segment positioning.
The report is deliberately built for cross-functional use. Corporate development teams can use the segmentation and concentration analysis to assess adjacency and acquisition logic. Commercial leaders can use the application and regional breakdowns to refine targeting and value proposition design. Operations and procurement teams can use the supply-side and regulatory elements to anticipate cost volatility and sourcing constraints.
Competitive Landscape: Scale, Specialization, and Shifting Advantage
The phosphate ester market is shaped by a mix of large diversified chemical companies and focused specialists. The strategic tension is visible in how participants allocate effort: some emphasize broad industrial fluid and flame retardant platforms, others concentrate on surfactant and additive portfolios for personal care or detergent applications, and still others anchor their offerings in fire-resistant hydraulic systems for demanding industrial and aviation environments.
The study profiles a wide set of important participants, including Clariant, Stepan Company, Eastman Chemical Company, LANXESS, Solvay, Dow, AkzoNobel, Croda International, ExxonMobil, Ashland, and Evonik Industries. Rather than treating these companies as a uniform group, the analysis distinguishes their functional positions in the market and the logic behind their product and application choices.
Several patterns are especially relevant for 2026 strategy:
- Specialty platforms are expanding around application-specific value propositions, such as phosphate esters for cleaning products, antistatic and anti-foaming functions in detergents, and multifunctional additives in inks, paints, and coatings.
- Customized formulations are becoming a competitive differentiator in lubricants, gear oils, hydraulic fluids, plasticizers, and agricultural compatibility aids, where performance tuning can support stronger customer lock-in.
- Fire-resistant hydraulic fluids remain a strategically important corner of the market, with established product lines supporting aviation and industrial applications where safety and reliability are non-negotiable.
- Eco-aligned offerings are gaining prominence as companies respond to customer sustainability expectations and broader emissions-reduction goals, creating new angles for product positioning and market entry.
- Personal care, industrial, and specialty surfactant applications continue to provide incremental growth opportunities, particularly where phosphate ester chemistry can be adapted to sensitive or high-performance formulations.
Competitive positioning is not static. Recent activity shows targeted moves in partnerships, product innovation, and regional capacity expansion. For example, Eastman Chemical Company announced a partnership with a leading automotive manufacturer to develop phosphate esters designed for electric vehicle applications. BASF SE introduced a new line of bio-based phosphate esters aimed at reducing carbon emissions in industrial applications. Huntsman Corporation completed the acquisition of a regional competitor, materially expanding its production capabilities in Asia-Pacific. These developments are not isolated headlines; they are indicators of where application demand, regional supply, and sustainability positioning are converging.
Market Dynamics: Cost, Regulation, and Supply Chain Sensitivity
Strategic planning in this market must contend with input-side volatility and policy-driven cost shifts. Precursor behavior remains an important operational variable: n-butanol prices exhibited significant volatility between 700 and 1,200 USD per metric tonne over 2022–2025, reinforcing the sensitivity of tributyl phosphate-related economics to feedstock swings. Meanwhile, tributyl phosphate prices in Asia were recorded at 2,600 USD per metric tonne in December 2025, a benchmark that reflects regional cost pressures and supply conditions relevant to procurement and pricing strategy.
Phosphonate Market
Trade policy and regulatory determinations add another layer of complexity. The US Department of Commerce determined that countervailable subsidies are being provided to producers and exporters of certain alkyl phosphate esters from the People's Republic of China, a development with direct implications for import economics, sourcing strategy, and competitive cost comparisons. In parallel, certain phosphate ester products used in nuclear applications are often subject to dual-use export control regulations in major supplier countries, which can affect distribution pathways, customer qualification, and regional market access.
These factors matter because they influence more than short-term margin. They shape where capacity is attractive, how companies configure their supply chains, and which customer segments can be served most efficiently. The report integrates these dynamics into a cohesive operating view so that strategy teams can anticipate disruption rather than react to it.
Concentration, Regional Logic, and Allocation Strategy
Market concentration provides useful context for both incumbents and new entrants. The sector is not fragmented to the point of undifferentiated competition, nor is it so concentrated that new initiatives are automatically pre-empted. That middle ground creates room for targeted positioning, especially where product performance, regulatory alignment, or regional availability can be leveraged as differentiators.
Regionally, the market’s value distribution reflects differing industrial baselines, demand structures, and trade patterns. The full report examines each major region’s role in the overall market and the strategic implications of their relative scale. Rather than presenting regional data as a static ranking, the analysis connects regional size to sourcing logic, customer density, and the competitive efforts underway to expand or defend position.
This regional view is especially important for companies evaluating production footprint, export strategy, and local supply capability. In a market where feedstock volatility, trade measures, and application-specific demand all vary by geography, regional intelligence is not optional; it is central to cost competitiveness and service reliability.
Where the Full Study Adds Value
The preview above establishes the strategic frame and the analytical rigor of the study. What it cannot do within this format is provide the complete segmentation detail, regional breakdowns, application-level comparisons, and company-specific profiles that turn insight into execution. Those elements are developed fully in the report, where they are integrated into a single decision-support structure.
The complete study enables leaders to:
- Compare contribution patterns across product types and application categories without relying on assumptions imported from unrelated chemical markets.
- Evaluate regional demand centers and supply exposure in a way that supports sourcing, capacity, and market-entry decisions.
- Benchmark competitor positioning against actual product platforms and recent strategic moves rather than broad brand reputation.
- Incorporate feedstock, regulatory, and trade developments into a practical operating plan for pricing, procurement, and compliance.
- Align product roadmap priorities with the application segments most likely to generate differentiated returns over the forecast period.
Conclusion: Turning Market Momentum into Disciplined Strategy
The phosphate ester market is moving with enough scale and enough structural variation to reward disciplined analysis. Aggregate growth provides opportunity, but value capture depends on understanding where that growth is concentrated, which application segments justify specialized investment, and how supply-side and regulatory realities shape execution.
This research is designed to help executives make those judgments with confidence. It combines historical perspective, a ten-year forecast, segmentation logic, competitive analysis, and operational context in a single framework built for 2026 planning and beyond. For leaders who need the full segmentation detail, regional interpretation, and company-level intelligence required to convert strategy into action, the complete report delivers the depth behind this preview.
For detailed analysis of this topic, please visit the official page: Phosphate Ester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PCB Design Software Market Hits $4.12 Billion in 2025, Projected to Reach $10.11 Billion by 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Imperatives in the PCB Design Software Market (2026–2032)
Executive Summary: A Market at an Inflection Point
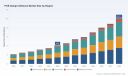
The global printed circuit board (PCB) design software market is entering a decisive growth phase. Drawing on historical performance from 2020 through 2025 and an extended forecast horizon stretching to 2032, the sector has demonstrated a consistent upward trajectory, moving from a baseline valuation in the low billions to a projected ten-billion-dollar milestone by the end of the forecast period. With a compound annual growth rate of 13.7%, the market is outpacing broader electronic design automation segments and signaling a structural shift in how hardware engineering teams plan, procure, and deploy design tools.
For enterprise decision-makers, engineering directors, and procurement leaders, these figures are more than macroeconomic indicators. They represent a rapidly expanding addressable market where tool selection, workflow integration, and compliance readiness directly influence product development cycles, time-to-market, and long-term competitive positioning. The PW Consulting PCB Design Software Market report translates this high-level momentum into actionable intelligence, mapping the interplay between software categories, end-use verticals, regional deployment patterns, and the competitive maneuvers shaping the next seven years.
This overview outlines the strategic architecture of the study, highlights the operational insights embedded within its chapters, and demonstrates how senior stakeholders can leverage its findings to align technology roadmaps with market realities. Core quantitative breakdowns remain reserved for the full report, ensuring that detailed segment valuations, regional revenue distributions, and granular application splits are accessed only through the complete intelligence package.
Market Trajectory and Structural Growth Drivers
Between 2020 and 2025, the PCB design software ecosystem expanded from a modest starting valuation to a mid-four-billion-dollar range, reflecting sustained demand across both commercial and industrial electronics development. The forecast period from 2026 to 2032 projects continued acceleration, with revenue expected to climb steadily toward a double-digit billion threshold by 2032. This growth is not merely cyclical; it is anchored in several compounding structural factors.
First, the proliferation of high-density interconnect designs, miniaturized form factors, and multifunction electronic assemblies is pushing design complexity beyond the capabilities of legacy standalone tools. Engineering teams increasingly require bidirectional data flow between schematic capture, layout, signal integrity analysis, and manufacturing verification. Second, the convergence of hardware and software development lifecycles is compressing design iteration windows, raising the premium on integrated suites that reduce handoff friction between electrical, mechanical, and production engineering teams. Third, supply chain volatility and component lifecycle management have elevated the importance of simulation and verification capabilities that de-risk design decisions before prototyping begins.
Regional dynamics further complicate the growth narrative. Demand generation, purchasing behavior, and deployment preferences vary significantly across geography, influenced by local electronics manufacturing density, regulatory environments, and enterprise procurement models. The report examines these regional variations through a framework that connects market size, growth velocity, and adoption maturity without reducing the analysis to superficial geographic rankings. Instead, it emphasizes how regional industrial ecosystems shape tool procurement cycles, vendor negotiation leverage, and the diffusion of advanced design capabilities across different markets.
In parallel, the market is navigating a cost-of-ownership landscape that directly affects adoption patterns. Premium enterprise tool subscriptions carry meaningful annual investment thresholds, and advanced design workflows often require corresponding upgrades to workstation infrastructure and specialized engineering talent. These dynamics create a bifurcated environment in which large OEMs and tier-one suppliers continue to invest in high-end integrated platforms, while small and mid-sized engineering teams evaluate lighter, modular, or open-source alternatives. Understanding how these cost structures influence segment penetration, upgrade cycles, and vendor value propositions is a central theme of the study.
What the Report Delivers: Operational Intelligence for Engineering and Commercial Leaders
The PW Consulting study is structured to support both strategic planning and tactical execution. Rather than functioning as a static market snapshot, it is designed as a decision-support framework that links market sizing to operational consequences for engineering organizations, software vendors, and channel partners. The report’s architecture spans several interconnected analytical dimensions.
At the core of the analysis is a disciplined examination of software categories and their respective roles in modern design workflows. The study differentiates between standalone design environments, schematic capture platforms, layout-oriented tools, simulation and analysis software, and fully integrated PCB design suites. Each category is evaluated not only in terms of market contribution, but also in relation to workflow integration, interoperability requirements, and the practical trade-offs engineers face when selecting tools for specific project profiles. This approach allows readers to understand how segmentation reflects real-world design complexity, rather than treating software categories as isolated commercial buckets.
The application dimension of the report maps software demand across major end-use verticals, including consumer electronics, telecommunications equipment, medical devices, industrial equipment, automotive components, and additional specialized sectors. For each vertical, the analysis addresses the distinct engineering constraints, compliance expectations, and lifecycle characteristics that influence tool selection. Medical device development, for example, introduces rigorous documentation and traceability requirements; automotive and industrial applications impose reliability, thermal, and signal integrity demands that shape simulation and verification priorities; telecommunications workflows increasingly intersect with high-speed signaling and density-driven layout challenges. By aligning segment analysis with these functional realities, the report helps leaders assess where advanced capabilities deliver the highest return and where streamlined toolchains may be more appropriate.
The regional dimension examines how local manufacturing bases, procurement traditions, and regulatory environments influence adoption pathways. Instead of presenting raw geographic rankings, the report contextualizes regional demand within broader industrial ecosystems, highlighting where design tool investment correlates with electronics production growth, where enterprise procurement cycles differ, and where emerging demand centers are reshaping vendor outreach strategies.
PCB Design Software Market
Beyond segmentation, the report includes detailed assessments of deployment preferences, subscription models, integration requirements, and total cost-of-ownership drivers. It also maps the competitive landscape, evaluates vendor positioning, and incorporates recent product developments and industry initiatives that signal where the market is heading. Throughout, the analysis is calibrated to support actionable planning: selecting tools, negotiating licensing terms, preparing engineering teams for regulatory shifts, and anticipating where ecosystem changes will create competitive advantage or risk.
Competitive Landscape: Positioning, Differentiation, and Recent Movements
The PCB design software market remains moderately concentrated, with the top three vendors collectively holding less than a quarter of total market share and the top five approaching but not exceeding one-third. This concentration level indicates a market that is neither fully consolidated nor highly fragmented, creating space for differentiated positioning, niche leadership, and ongoing competitive disruption. The report analyzes the principal participants in this landscape, emphasizing how each vendor’s product philosophy, target audience, and integration strategy shape its commercial trajectory.
Altium LLC has built its commercial identity around a leading integrated design environment that converges schematic capture, layout, simulation, and collaboration within a single workflow. Its positioning reflects the broader market movement toward unified platforms that reduce toolchain fragmentation, particularly for teams that value rapid iteration, accessible usability, and strong ecosystem integrations. Zuken Inc. operates with a more segmented suite strategy, offering enterprise-oriented platforms for complex subsystem and 3D layout, mainstream PCB design solutions, and specialized electrical design tools. This multi-tiered approach allows the company to address both high-complexity enterprise environments and broader mainstream design requirements, reinforcing its presence across different complexity thresholds and organizational scales.
Siemens EDA maintains a strong footprint through platforms that span design, layout, simulation, analysis, and verification. Its portfolio is closely associated with environments where design integrity, manufacturing alignment, and verification discipline are critical, making it a frequent consideration in programs that require robust analysis capabilities and tight integration with broader engineering and manufacturing workflows. Cadence Design Systems, Inc. contributes to the competitive field through platforms that increasingly emphasize AI-enabled design, layout, and analysis functions. As design complexity rises and iteration cycles compress, AI-assisted capabilities are becoming a meaningful differentiator in how tools support routability assessment, constraint management, and design optimization, positioning AI integration as a strategic axis of competition.
A distinct competitive layer includes providers of accessible or open-source-based solutions. RS Components has developed professional-grade and free EDA packages that lower entry barriers for small teams, educators, and cost-sensitive engineering groups. The KiCad Development Team continues to expand an open-source suite that supports schematic capture and PCB layout, reinforcing a community-driven model that competes indirectly with commercial vendors by shaping user expectations around accessibility, extensibility, and cost efficiency. WestDev Ltd. also participates in this ecosystem through its association with certain PCB design software solutions, adding to the diversity of vendor arrangements and licensing pathways available to buyers.
Recent industry activity underscores how competition is intensifying along both product-feature and ecosystem-dimensions. In April 2025, Zuken released an updated version of its mainstream PCB design platform with parallel library paths, AI-assisted workflows, and enhanced signal integrity and collaboration capabilities, signaling a clear push toward productivity improvements and higher-performance design support. By late 2025, the open-source community advanced its own development cadence with successive version updates to its PCB design suite, reflecting continued refinement in a segment that competes on accessibility and community momentum. At the institutional level, a major electronics association launched an introductory PCB design course in early 2026 aimed at new designers, emphasizing foundational schematic and layout skills using EDA tools. This type of workforce development initiative matters strategically because tool adoption is tightly coupled with designer familiarity, training pipelines, and the long-term diffusion of design practices across the engineering labor pool.
The report situates these developments within a wider competitive analysis that evaluates product roadmaps, enterprise sales motions, open-source influence, subscription economics, and the strategic implications of AI-enabled features. By comparing how vendors address complexity, accessibility, verification discipline, and workflow integration, the study provides a framework for assessing which competitive approaches are likely to resonate with different buyer profiles over the forecast period.
Electrical Design Software Market
Regulatory, Cost, and Deployment Dynamics Shaping Adoption
Market growth does not occur in a regulatory or operational vacuum. Several overlapping dynamics are redefining how PCB design software is evaluated, deployed, and governed. In the medical device domain, recent regulatory guidance in the United States has reinforced mandatory risk-based design controls, traceability, and documentation expectations for design processes, with alignment to updated quality management system requirements effective in early 2026. For PCB design workflows, these requirements raise the stakes on design traceability, version control, and the ability to demonstrate disciplined development pathways. Tools that support structured documentation, audit readiness, and design traceability are therefore gaining strategic importance in regulated verticals, not simply as productivity enhancers but as compliance enablers.
On the cybersecurity front, the European Union has advanced a resilience framework that requires manufacturers of digital products, including certain software offerings, to design, update, and maintain systems with cybersecurity compliance in mind. Beginning later in 2026, reporting obligations for actively exploited vulnerabilities will add a new layer of responsibility for software suppliers and enterprise users alike. These obligations influence procurement decisions by making security posture, update cadence, vulnerability management, and support commitments more relevant in vendor evaluation. For engineering organizations, this dynamic introduces a broader set of due-diligence considerations when selecting software platforms, particularly where designs interface with connected products or where corporate IP protection policies intersect with external toolchains.
Deployment preferences also remain shaped by sector-specific security and IP concerns. On-premises deployment models continue to hold strong appeal in aerospace, defense, and automotive contexts, where strict data security and intellectual property protection often outweigh the convenience of cloud-centric arrangements. This persistence of localized deployment affects licensing structures, integration strategies, IT support requirements, and the broader commercial calculus for vendors targeting high-assurance sectors. The report examines how these deployment tendencies influence vendor positioning and buyer decision-making, particularly where regulated or security-sensitive environments create long sales cycles and higher negotiation stakes.
Cost structures add another layer of strategic complexity. Enterprise-grade subscriptions can represent a material annual investment per design seat, and advanced workflows frequently require corresponding investments in workstation hardware and specialized engineering talent. These factors raise the total cost of ownership for smaller organizations and can inhibit the adoption of premium suites, even when feature requirements might otherwise justify them. As a result, procurement strategies increasingly weigh not only license pricing, but also training burdens, hardware dependencies, upgrade frequency, and the operational risk of toolchain fragmentation. The report addresses these economic pressures through a lens that connects pricing models, deployment choices, and engineering capacity constraints to practical adoption outcomes.
How to Use This Research for 2026 Decision-Making
The strategic value of the full study lies in its ability to convert market momentum into concrete planning inputs. For senior decision-makers, the report offers a structured way to evaluate tool procurement, vendor selection, workflow redesign, and workforce readiness against a realistic view of where the market is heading. It helps organizations anticipate which capabilities will become more central as design complexity rises, where integration and verification features will command premium attention, and how regulatory and security requirements will reshape evaluation criteria.
For vendors and channel partners, the analysis provides context on competitive positioning, buyer sensitivity, and the threads of differentiation that matter most across enterprise, mainstream, and accessible-tier segments. By connecting recent product releases, workforce development activity, and regulatory change to broader market dynamics, the study supports scenario planning around tool adoption, feature investment, and go-to-market strategy.
The complete report contains the detailed segment breakdowns, regional distributions, application-level market contributions, concentration analysis, and vendor-level intelligence needed for precise planning. Those granular data points are deliberately held within the full study so that decision-makers can access calibrated, context-rich intelligence without diluting the analytical framework. The overview presented here is intended to demonstrate the depth and operational relevance of the research while guiding readers toward the full report for the quantitative and strategic detail required for final investment and procurement decisions.
Conclusion: Positioning for a High-Growth, High-Complexity Decade
The PCB design software market is expanding at a pace that rewards early clarity in tool strategy, workflow integration, and compliance readiness. With sustained double-digit growth projected through the end of the decade, organizations that treat design software as a strategic infrastructure choice rather than a routine procurement item will be better positioned to manage complexity, reduce rework, and accelerate product development. The PW Consulting study translates this market opportunity into a structured intelligence base for evaluating categories, verticals, regions, vendors, and the regulatory and economic forces that shape adoption. By connecting high-level market momentum with the practical realities of engineering workflows and procurement behavior, the report equips leaders with the perspective needed to make informed decisions in a rapidly evolving landscape.
For detailed analysis of this topic, please visit the official page: PCB Design Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Feed Yeast Market Hits $150M in 2025, Eyes 5.1% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating Volatility and Value: A 2026 Strategic Outlook on the Global Feed Yeast Market
The global animal nutrition sector stands at a critical inflection point in 2026. As livestock producers face margin compression from fluctuating raw material costs and evolving regulatory landscapes, the demand for functional feed additives has never been more scrutinized. Feed yeast, once considered a niche supplement, has cemented its status as a cornerstone ingredient for gut health, nutrient absorption, and overall animal performance. For stakeholders operating within this ecosystem, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for sustainable growth and risk mitigation.
PW Consulting's latest comprehensive study on the Feed Yeast Market is designed to equip decision-makers with the granular intelligence required to navigate this complex environment. This article serves as a strategic preview of our findings, highlighting the macro-economic shifts, competitive dynamics, and operational realities that will define the sector from 2026 through 2032. By examining the underlying forces driving revenue progression and market concentration, we aim to demonstrate the tangible value this research brings to corporate strategy, investment planning, and supply chain optimization.
Macro-Economic Trajectory and Growth Validation
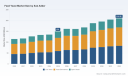
The foundational premise of any strategic investment lies in the validity of the market's growth trajectory. Our analysis tracks the market's evolution from a baseline of 115.0 million USD in 2020, reflecting a steady maturation phase. The progression to 150.0 million USD in 2025 underscores a resilient demand structure that has withstood recent global supply chain disruptions. Looking forward, the forecast period spanning 2026 to 2032 projects a continuation of this upward trend, with revenue figures anticipated to reach 210.28 million USD by 2032.
These figures represent more than simple volume expansion; they signal a structural shift in how animal nutrition is formulated. The projected Compound Annual Growth Rate (CAGR) of 5.1% during the forecast period indicates a market that is growing at a pace superior to general agricultural commodities, driven by specific value-added applications rather than bulk commodity mixing. For CFOs and strategy heads, this growth rate validates the capital expenditure required to expand production capabilities or secure long-term supply agreements. However, recognizing the top-line number is only the first step. The real strategic weight lies in understanding the velocity of growth across different product forms and animal categories, which our full report dissects in detail.
The historical data from 2020 to 2025 also reveals patterns of recovery and acceleration that are crucial for modeling future scenarios. The jump from 135.25 million USD in 2024 to 150.0 million USD in 2025 suggests a post-pandemic stabilization and a renewed focus on livestock productivity. As we move into 2026, with the market estimated at 161.77 million USD, the momentum suggests that feed yeast is transitioning from a reactive solution to a proactive standard in animal husbandry. This trajectory provides a reliable baseline for internal forecasting, reducing the uncertainty that often plagues nutritional budgeting.
Segmentation Dynamics and Application Value
While the aggregate market size tells a story of growth, the segmentation data reveals where the actual value is generated. The market is broadly categorized by product form, animal type, and geographic reach. In terms of product forms, the split between Live Yeast, Yeast Derivatives, and Spent Yeast indicates diverse utilization pathways. Yeast Derivatives currently hold a significant share, reflecting the industry's preference for stable, concentrated forms of nutrients and beta-glucans that offer consistent performance without the viability risks associated with live cultures. Live Yeast, however, remains a critical segment for probiotic applications, particularly where rumen health and microbial balance are prioritized.
In terms of animal applications, the demand is heavily weighted towards Poultry, which continues to be the dominant driver of feed yeast consumption. This aligns with the global intensification of poultry production where growth rates and feed conversion ratios are paramount. Ruminants represent a substantial secondary segment, driven by the specific need for yeast cultures that stabilize fermentation in the rumen, thereby improving milk yield and feed efficiency in cattle. Swine and Aquaculture segments, while smaller in relative revenue share, are experiencing distinct growth vectors. The aquaculture sector, in particular, is gaining traction as alternative protein sources require optimized gut health solutions to ensure survival rates and growth in intensive farming environments.
Geographically, the market exhibits a mature landscape in North America and Europe, where high regulatory standards and established livestock industries sustain stable demand. Asia Pacific presents a high-growth frontier, fueled by expanding meat consumption and modernization of farming practices in key economies. Latin America and the Mideast and Africa regions, while currently smaller in relative revenue contribution, offer potential for expansion as local production capacities increase. Our report provides a deep dive into these regional nuances, analyzing local production capabilities versus import dependency, which is critical for pricing strategy and supply chain resilience.
Competitive Intensity and Consolidation Trends
The feed yeast market is characterized by a moderately high concentration of key players, with the top three companies accounting for approximately 65% of the market revenue and the top five holding around 82%. This concentration suggests that scale, technological capability, and brand trust are significant barriers to entry. The competitive landscape includes a mix of global nutrition giants and specialized yeast producers who have leveraged their fermentation expertise to capture niche leadership positions.
Key industry participants such as Angel Yeast Co., Ltd., Alltech Inc., Lallemand Inc., and Lesaffre Group dominate the conversation through diverse strategies. Angel Yeast, based in China, leverages massive production capacity exceeding 100,000 tonnes annually to compete on scale and supply reliability, often showcasing their full range of solutions at major industry events like SPACE 2025. In contrast, companies like Alltech focus on specialized science, promoting proprietary yeast cultures like Yea-Sacc for specific rumen health benefits, maintaining authorization under strict EFSA regulations.
Feed Yeast Market
European and North American players like Leiber GmbH, Chr. Hansen A/S, and DSM-Firmenich AG bring strong heritage in fermentation and ingredient quality. Leiber's recent acquisition by Asahi Group Foods in March 2025 highlights a trend towards vertical integration and the convergence of food and feed ingredient capabilities. Meanwhile, entities like ADM Animal Nutrition and Nutreco integrate yeast solutions into broader animal nutrition portfolios, offering customers a one-stop shop for dietary requirements. The presence of companies like Novus International and AB Agri further diversifies the competitive field, ensuring that innovation remains a priority.
For new entrants or expanding players, this landscape implies that competition is not solely on price but on demonstrated efficacy, regulatory compliance, and supply chain security. Understanding the specific strengths and strategic moves of these key companies is essential for identifying partnership opportunities or anticipating market shifts. Our full report profiles each of these key players, analyzing their production capacities, recent developments, and strategic positioning to help you benchmark your organization against the market leaders.
Operational Challenges and Regulatory Headwinds
Strategic planning in 2026 must account for a dynamic regulatory and cost environment. The core ingredient, Saccharomyces cerevisiae, is subject to price volatility driven by fermentation feedstock costs. With average annual prices hovering between 800 and 1,200 USD per metric ton as of 2025, cost management becomes a critical component of margin protection. Producers with integrated fermentation infrastructure hold a distinct advantage in buffering these input costs, while downstream formulators must navigate availability risks.
Yeast Market
Regulatory frameworks are also evolving in ways that directly impact trade and product formulation. Recent trade policy shifts, such as the U.S. Executive Order of February 20, 2026, have introduced specific tariff considerations on inactive yeasts, excluding dried brewers' yeast under certain HTSUS classifications. This distinction creates a complex compliance landscape for importers and exporters, requiring precise classification to avoid unexpected cost burdens. Simultaneously, the authorization status of key products under European regulations, such as the ongoing renewals for specific yeast cultures, adds a layer of regulatory risk that must be monitored continuously.
Furthermore, the infrastructure requirements for production are non-trivial. Large-scale fermentation facilities capable of exceeding 100,000 tonnes per year are necessary to achieve the economies of scale required to compete in the global market. This barrier reinforces the dominance of established players and suggests that capacity expansions are significant strategic events. China's role as a leading production hub, with output exceeding 200,000 tonnes annually primarily for export, underscores the geopolitical and logistical dimensions of the supply chain. For businesses reliant on global sourcing, understanding these infrastructure constraints and export flows is vital for mitigating supply disruption risks.
Strategic Imperatives for 2026 and Beyond
As we look toward the forecast period ending in 2032, the strategic implications for stakeholders are clear. First, product differentiation will remain the primary lever for premium pricing. Companies that can validate the functional benefits of specific yeast strains or derivatives through robust trial data will command greater loyalty and resilience against price-based competition. Second, supply chain diversification is no longer optional. With significant production concentrated in specific regions and tariffs fluctuating, building a multi-sourced supply network is essential for continuity.
Third, regulatory intelligence must be embedded into product development cycles. The evolving landscape of tariffs, authorizations, and safety standards requires a proactive approach to compliance rather than a reactive one. Finally, the trend toward consolidation suggests that strategic partnerships or acquisitions could accelerate market access and technology acquisition. Whether through integrating acquisitions like those seen in the brewers' yeast sector or forming alliances to expand distribution networks, inorganic growth strategies will play a role alongside organic development.
Unlocking the Full Intelligence Picture
The insights presented here represent the surface of a much deeper analytical reservoir. The data points mentioned, the company profiles summarized, and the dynamics outlined are derived from a rigorous methodology that combines historical data validation, primary industry interviews, and quantitative modeling. To truly leverage this information for decision-making, a granular understanding of the segmentation splits, the detailed competitive benchmarking, and the region-specific risk assessments is required.
PW Consulting's full Feed Yeast Market Report provides this complete intelligence package. It offers the detailed revenue breakdowns by sub-category, the specific growth rates for each animal segment, and the comprehensive analysis of regulatory impacts on trade flows. It details the capacity expansions, the specific product launches, and the strategic alliances that are shaping the competitive field beyond the headlines. For executives aiming to capitalize on the projected growth to 210.28 million USD by 2032, or for investors assessing the viability of market entry, the depth of data available in the full study is the key differentiator between informed strategy and speculation.
We invite you to access the complete report to secure the detailed intelligence necessary to navigate the feed yeast market with confidence. In an industry where margins are managed through precision and foresight, having the full picture is the ultimate competitive advantage. Let our analysis be the foundation upon which your 2026 strategy is built, ensuring you are positioned not just to survive the market dynamics, but to thrive within them.
For detailed analysis of this topic, please visit the official page: Feed Yeast Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LIDAR Market Hits $299M in 2025, Projects 20.32% CAGR to $1,088M by 2032
By pmarketresearch, 2026-09-15
The LiDAR Inflection Point: Strategic Intelligence for 2026 Enterprise Decisions
The Light Detection and Ranging (LIDAR) market is no longer a speculative technology narrative reserved for R&D laboratories and venture capital pitch decks. As we move through 2026, the sector has matured into a structural infrastructure backbone for autonomous mobility, spatial intelligence, and next-generation industrial sensing. For enterprise decision-makers, the question is no longer whether to engage with LIDAR ecosystems, but how to architect supply-chain exposure, partnership strategies, and product roadmaps in a landscape defined by rapid technological convergence and shifting regulatory guardrails.
Light Detection and Ranging (LIDAR) Market
This analysis serves as a strategic precursor to our latest comprehensive market study, Light Detection and Ranging (LIDAR) Market: Global Forecast & Strategic Assessment, 2026–2032 . Below, we outline the macro forces shaping the period ahead, the operational intelligence embedded in our full report, and the competitive dynamics that will determine which organizations capture value versus those that merely observe it.
The Macro Trajectory: From Niche Sensing to Systemic Enabler
Historical performance provides the first layer of strategic confidence. Between 2020 and 2025, global LIDAR revenue expanded from approximately 162.3 million USD to 299.0 million USD, reflecting sustained triple-digit growth across discrete product cycles. That growth is not decelerating; rather, it is compounding. Our baseline projection places 2026 revenue at 364.7 million USD, scaling progressively to 1,088.2 million USD by 2032. This expansion is underpinned by a forecasted compound annual growth rate of 20.32 percent throughout the 2026–2032 forecast window, a trajectory that signals durable demand rather than a short-term procurement spike.
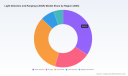
The composition of that demand tells a more nuanced story. Mechanical architectures continue to command meaningful revenue share, particularly in applications where proven reliability and established supply chains outweigh incremental form-factor advantages. At the same time, solid-state solutions are accelerating their penetration, driven by design requirements in automotive ADAS, compact robotics, and fixed infrastructure deployments. The application landscape mirrors this dual-track evolution. Automotive and advanced driver-assistance systems remain the dominant pull factor, while smart infrastructure and mapping initiatives, aerospace and defense modernization programs, and environmental and forestry monitoring verticals each contribute distinct demand rhythms that rarely align with a single procurement calendar.
Geographic distribution of revenue further illustrates the market's global character. North America, Asia Pacific, and Europe each represent substantial demand centers, with Latin America and the Middle East & Africa emerging as incremental but strategically relevant contributors. Importantly, these figures reflect integrated, end-to-end valuations rather than isolated component sales, meaning that downstream system integrators, software perception layers, and service-enabled deployment models are already being captured within the broader revenue envelope.
The 2026–2032 Forecast Lens: Why Precision Matters Now
Aggregate growth trajectories are necessary but insufficient for capital allocation and product strategy. What separates high-performing organizations in this cycle is access to granular, scenario-tested intelligence. Our full market report dissects historical baselines from 2020 through 2025 and projects forward through 2032 with methodology designed for operational decision-making rather than retrospective commentary.
Executives will find in the complete study a breakdown of type-based revenue evolution, application-specific demand momentum, and regional performance differentials that allow for portfolio stress-testing under multiple adoption curves. The report also maps concentration dynamics within the market: the top three players collectively account for roughly 35 percent of total revenue, while the top five expand that footprint to approximately 52 percent. These concentration levels are not static ceiling effects; they reflect active consolidation patterns, partnership leverage, and the capital intensity of scaling manufacturing while maintaining performance thresholds.
For supply-chain leaders, the forecast period is particularly instructive because hardware bottlenecks are not uniform across the stack. Component constraints tied to semiconductors, optical lenses, and high-precision MEMS chips have emerged as primary friction points limiting rapid production scale-up. Understanding where these constraints will persist, and which architecture types are most exposed, enables procurement teams to sequence commitments rather than react to shortages in real time. This is precisely the kind of forward visibility embedded in the full report's segment-level analysis, where type, application, and regional overlays are presented together to surface cross-dependencies that isolated dashboards routinely miss.
Wind Lidar Market
Competitive Architecture: The Players Defining the Next Cycle
The competitive field in 2026 is defined by differentiated specializations rather than undifferentiated scale. Hesai Technology, headquartered in Shanghai, continues to push solid-state automotive LiDAR sensors into high-volume production while expanding its 3D perception portfolio for autonomous mobility and robotics. Its recent manufacturing expansion into a Thailand facility, expected to come online later in 2026, signals a deliberate strategy to supply non-Chinese companies and hedge against geographic supply-chain concentration. Product-wise, Hesai has introduced the ET25 ultra-thin sensor at a 25 mm thickness for behind-windshield mounting, alongside the PandarXT 32-channel mid-range LiDAR featuring zero minimum range and self-developed ASICs. These moves illustrate a clear focus on integrating sensor form-factor constraints with proprietary silicon strategy.
Luminar Technologies, based in Orlando, Florida, remains anchored in long-range pulsed LiDAR sensors and perception systems purpose-built for Level 3+ autonomous vehicles and ADAS. Its positioning is less about volume ubiquity and more about performance thresholds where range, velocity resolution, and robustness in high-speed environments define competitive advantage. Innoviz Technologies, operating from Rosh Ha'ayin, Israel, pursues a complementary automotive-grade route, delivering high-resolution 3D perception platforms tailored for consumer vehicles and commercial applications where certification rigor and cost-performance balance are paramount.
Ouster, Inc., headquartered in San Francisco, emphasizes digital LiDAR sensors optimized for scalability across autonomous vehicles, robotics, and smart infrastructure. Its architectural philosophy centers on manufacturability and software-defined flexibility, which resonates in deployment models that require fleet-wide uniformity and lifecycle upgradability. LeddarTech, in Québec, pairs solid-state LiDAR sensors with the LeddarVision software suite, effectively offering a perception stack alongside hardware, an increasingly relevant value proposition as system integrators seek integrated ADAS and autonomous driving perception solutions rather than discrete sensor components.
MicroVision, Inc., based in Redmond, Washington, continues to advance MEMS-based LiDAR 2.0 sensors and perception solutions targeting industrial, defense, and autonomous applications. Its April 2026 launch of a Global Partner and Reseller Program reflects a deliberate acceleration strategy aimed at scaling adoption across real-world industrial and defense use cases through broader channel reach. Cepton Technologies, in San Jose, rounds out the competitive field with lidar-based solutions spanning automotive ADAS, smart cities, and industrial automation, reinforcing the multi-vertical deployment logic that characterizes mature LIDAR ecosystems.
The strategic implication for buyers and investors is clear: competitive advantage is fragmenting across architecture types, perception software maturity, manufacturing geography, and channel strategy. No single company's narrative dominates every segment, and the winners will be those whose capabilities align with specific demand profiles rather than those who chase all segments simultaneously without the infrastructure to support them.
Regulatory and Standardization Currents Reshaping Playbooks
Technology roadmaps cannot be separated from the policy environment in which they operate. In December 2025, the SAFE LiDAR Act was introduced in the 119th Congress with the intent to restrict the use of foreign adversary LiDAR within the United States. Regardless of final legislative language, the directional signal is unambiguous: procurement teams and product planners must evaluate sourcing strategies against evolving national-security criteria, particularly where end systems interface with critical infrastructure or federally regulated mobility programs.
At the same time, regulatory nuance continues to matter. A January 2025 Federal Register notice reaffirmed that LiDAR hardware is excluded from supply-chain review under the Connected Vehicles framework. This clarification creates a meaningful distinction between sensor hardware and broader vehicle connectivity obligations, but it also demands careful compliance interpretation as program boundaries evolve. Organizations that assume blanket applicability, or conversely that ignore the distinction entirely, risk misaligned sourcing or delayed program approvals.
Standardization efforts are equally consequential. Hesai co-leads the Automotive LiDAR Working Group at the International Standards Organization, where the focus is developing test methods for LiDAR performance and safety. The emergence of standardized evaluation protocols will influence benchmarking, procurement specifications, and cross-vendor comparability, gradually shifting the market from proprietary performance claims toward reproducible metrics. For engineering and quality teams, early alignment with these developing standards reduces retrofit risk in later validation cycles.
Data infrastructure developments are also reshaping downstream demand. The latest Lidar Base Specification, LBS 2025 rev. A, was released by the U.S. Geological Survey in June 2025 for the 3D Elevation Program, and in January 2026 the USGS announced FY25 3DEP data collaboration projects, including newly acquired QL 1 lidar for Palm Beach County to support a new 3DHP pilot project. These initiatives illustrate how government data programs are institutionalizing lidar as a foundational component of national spatial data infrastructure, which in turn expands procurement pathways for mapping and infrastructure monitoring providers.
Why the Full Report Is a Decision Asset, Not a Reference Document
Given the convergence of architectural differentiation, regulation, standards, and supply constraints, strategic teams need intelligence that can be operationalized rather than simply reviewed. Our complete report is structured to support that end. It provides a full historical and forecast timeline, type and application segment analysis, regional performance context, concentration metrics, and a detailed competitive landscape that includes company profiles, recent developments, and the strategic implications of those moves.
Beyond descriptive coverage, the report is built around decision utility. Procurement leaders can use the segmentation and bottleneck analysis to sequence sourcing commitments and evaluate supplier exposure. Product planners can map application momentum against architectural readiness to prioritize development investments. Strategy and corporate development teams can evaluate partnership, acquisition, and geographic expansion options against concentration dynamics and standardization trajectories. The integration of recent developments, such as Hesai's Thailand manufacturing expansion and new sensor introductions, MicroVision's partner program launch, and government data collaboration and standardization activities, ensures that the analysis reflects the market as it is being shaped in real time, not as it appeared in prior cycles.
To access the complete segmentation detail, full forecast tables, competitive profiles, and the integrated strategic recommendations that accompany them, please visit the source page at PW Consulting for the full Light Detection and Ranging (LIDAR) Market report. The macro trajectory outlined here is intended to demonstrate the analytical rigor and decision relevance of the study; the actionable architecture, segment-level intelligence, and scenario-tested guidance are delivered in full only within the complete report.
For detailed analysis of this topic, please visit the official page: Light Detection and Ranging (LIDAR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HIFU Market Hits $215M in 2025, Forecasts 7.25% CAGR to $344.8M by 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the High-Intensity Focused Ultrasound System Market: A 2026 Outlook
The High-intensity Focused Ultrasound (HIFU) System Market stands at a critical inflection point as the global healthcare landscape shifts toward non-invasive, precision-based therapeutic modalities. With a total market valuation reaching 215.0 USD Million in the base year and projected to ascend toward 344.8 USD Million by the close of the forecast window, the sector is demonstrating robust structural momentum. Our latest comprehensive market study distills this trajectory into actionable intelligence, enabling executives to navigate the complex interplay of regulatory evolution, clinical adoption, and technological differentiation that will define competitive positioning through 2032.
For strategic decision-makers operating in medtech, hospital procurement, or venture-backed healthcare innovation, this report functions as a navigation blueprint. It maps the current revenue topology, isolates the primary growth vectors, and evaluates how market participants are aligning product portfolios with emerging reimbursement signals. The analysis is structured to deliver clarity without noise, emphasizing operational readiness over superficial trend-chasing. As we enter 2026, the convergence of clinical evidence maturation, payer documentation standardization, and platform-specific regulatory clearances demands a more granular understanding of where capital, R&D, and commercial resources should be deployed.
Macro Trajectory and Growth Architecture
The historical record from 2020 through 2025 reveals a consistent upward climb, with revenue scaling from 163.15 USD Million to 215.0 USD Million. This expansion was not merely a function of incremental adoption; it reflects a structural reorientation in how health systems evaluate procedural risk, recovery timelines, and long-term patient throughput. Forecasts extending through 2032 indicate a compound annual growth rate of 7.25 percent, signaling sustained demand expansion rather than a temporary surge. The forward curve suggests that early movers who secure clinical workflow integration, streamline installation and service models, and align with payer documentation requirements will capture disproportionate share during the mid-forecast period.
Growth is being propelled by several intersecting forces. Clinicians and hospital administrators are increasingly prioritizing therapies that reduce inpatient burden, minimize collateral tissue damage, and offer repeatable treatment protocols without ionizing radiation. Simultaneously, device manufacturers are compressing form factors, enhancing imaging-fusion capabilities, and building robotic assistance layers that standardize targeting accuracy. These technological refinements are lowering the barrier to entry for new clinical sites while expanding the addressable patient population across both therapeutic and aesthetic indications. The result is a market that is widening in scope even as it deepens in technical complexity.
Report Content and Operational Utility
Our analysis is engineered to translate market signals into execution-ready insights. Rather than offering abstract commentary, the report delivers a structured dossier of operational components that senior leadership can immediately integrate into commercial planning, investment committee memos, and product roadmap reviews. The study covers the following core modules:
- Comprehensive revenue mapping across historical baselines and forward-looking forecast intervals, with explicit identification of inflection years where adoption velocity is expected to accelerate.
- End-to-end segmentation analysis that dissects market structure by clinical and commercial categories, highlighting how therapeutic platforms, aesthetic applications, and compact system architectures are carving distinct growth lanes.
- Regional deployment patterns and purchasing ecosystem characteristics, enabling localization strategies for distribution partnerships, clinical training programs, and service infrastructure planning.
- Technology and workflow evaluation frameworks that assess imaging integration, targeting precision, treatment duration, and operator dependency across competing platform types.
- Reimbursement and policy tracking modules that consolidate CPT coding references, national health system coverage decisions, and payer medical policy updates into a single decision-support environment.
- Competitive benchmarking and strategic positioning maps that evaluate product differentiation, clearance trajectories, clinical collaboration networks, and geographic footprint strength.
Each module is designed to reduce ambiguity in capital allocation and market-entry timing. For organizations evaluating expansion into new indications, the report isolates the clinical evidence thresholds and procedural familiarity curves that typically govern adoption speed. For established players refining go-to-market execution, the analysis surfaces workflow bottlenecks, service-model gaps, and training requirements that often determine realized utilization rates. The synthesis of clinical, regulatory, and commercial layers ensures that leadership can evaluate opportunities through a unified lens rather than fragmented siloed data.
Competitive Landscape and Strategic Positioning
The HIFU ecosystem is characterized by a concentrated yet dynamically evolving competitive field. Market concentration metrics indicate that a small cohort of established players commands a dominant share of total revenue, reflecting the high technical thresholds, regulatory navigation requirements, and clinical validation cycles that typically accompany focused ultrasound platform commercialization. Within this structure, differentiation is increasingly driven by indication-specific pipeline depth, imaging and workflow integration, and the ability to secure timely reimbursement alignment.
Several organizations exemplify the strategic pathways shaping the market. EDAP TMS SA has advanced its Focal One robotic HIFU system for prostate cancer focal therapy, reinforcing its position through recent imaging and workflow enhancements that received FDA 510(k) clearance, alongside France’s national universal health system reimbursement decision for the Focal One procedure. This dual momentum illustrates how product refinement and reimbursement alignment can compound commercial traction in a core urologic application. Theraclion continues to extend its footprint with the Echopulse and SONOVEIN robotic HIFU platforms, targeting non-invasive treatment pathways for thyroid nodules, breast fibroadenomas, and varicose veins, thereby broadening the indication map beyond traditional tumor ablation into benign and vascular applications.
Insightec maintains a distinctive position through its Exablate and Exablate Neuro systems, leveraging MR-guided focused ultrasound for essential tremor, Parkinson’s disease, and pain palliation. The neurological and functional applications associated with this platform highlight a growing premium segment where procedural precision and image-guided targeting command higher clinical scrutiny and specialized adoption pathways. Profound Medical Corp. contributes to the therapeutic landscape with the Sonalleve MR-HIFU platform, supporting prostate cancer ablation and osteoid osteoma treatment, while also expanding into related oncologic applications that benefit from precise thermal ablation capabilities.
Chongqing Haifu Medical Technology Co., Ltd. represents an important distribution and manufacturing axis, with JC and JC200 HIFU systems supporting non-invasive tumor ablation across liver, breast, and bone applications as well as benign conditions, backed by global distribution reach. This international footprint underscores how regional manufacturing strength and export-oriented commercial networks can influence global supply dynamics and pricing architecture. Sonablate Corp. continues to develop the Sonablate 450 HIFU system for prostate cancer treatment, supported by ongoing clinical collaborations and product distribution, reinforcing the sustained focus on urologic ablation as a foundational market pillar. Meanwhile, FUSMobile, Inc. has carved a specialized niche with the Neurolyser XR fluoroscopy-guided HIFU system for chronic low back pain treatment, recently obtaining De Novo clearance that opens a distinct pain-management pathway and demonstrates how targeted nerve-destruction applications can diversify the overall demand base.
Regulatory and Reimbursement Dynamics as Strategic Catalysts
Market expansion in focused ultrasound is increasingly contingent on the alignment between clinical evidence, procedural coding clarity, and payer acceptance. Recent developments show that reimbursement infrastructure is moving from fragmented, institution-specific decision-making toward more standardized documentation expectations. Anthem Medical Policy CG-MED-81, updated in early 2026, lists applicable CPT codes for HIFU ablation procedures, reinforcing coding visibility for commercial payers and creating a more predictable billing environment for providers. This type of policy clarity reduces administrative friction and supports broader site-level adoption, particularly for centers that depend on consistent outpatient reimbursement pathways.
At the same time, reimbursement strategy has become an active commercial priority rather than a passive compliance function. Industry participants are investing in education and documentation guidance to help clinical sites navigate coding requirements and submission accuracy. This is reflected in recent webinar initiatives focused on the evolving reimbursement landscape and the documentation needed for accurate billing, signaling that market maturity now includes payer-facing readiness as a core capability. The existence of CPT code 55880 for transrectal high-intensity focused ultrasound prostate ablation, which has supported Medicare outpatient reimbursement since 2021, further illustrates how coding stability can anchor long-term utilization patterns in a key therapeutic segment.
Regulatory milestones are also reshaping competitive timing. Recent FDA clearances for imaging and workflow enhancements, as well as De Novo clearance for nerve-targeted chronic low back pain treatment, demonstrate that the regulatory pathway is enabling both incremental platform refinement and new indication entry. In parallel, broader ecosystem developments such as the establishment of an international focused ultrasound society are helping to standardize clinical practice, convene evidence generation, and accelerate adoption through shared professional infrastructure. These dynamics suggest that the organizations most likely to compound advantage in 2026 and beyond will be those that synchronize product development with reimbursement documentation, clinical education, and professional society engagement.
High Intensity Focused Ultrasound (HIFU) Market
Implications for 2026 Decision-Making
For executives planning 2026 strategic moves, the market presents a clear mandate: prioritize positioning that aligns product capability with reimbursement readiness, clinical workflow compatibility, and indication-specific evidence maturity. The compound growth trajectory implies that demand will continue to broaden, but the pace of capture will differ substantially across segments depending on how quickly sites can integrate the technology into existing procedural pathways. Organizations that treat reimbursement and coding clarity as a core commercial pillar, rather than a downstream administrative concern, will gain faster utilization ramp and more predictable revenue conversion.
The report provides the structural context required to make these choices with confidence. It maps where concentration is highest, where emerging applications are gaining traction, and how recent regulatory and reimbursement actions are reshaping site-level purchasing behavior. By situating these insights within a forward-looking framework, the study enables leadership to identify which therapeutic platforms, aesthetic devices, and compact system architectures warrant deeper investment, partnership development, or geographic prioritization. It also supports scenario planning around clinical education, service expansion, and workflow integration, ensuring that strategic intent is matched by operational readiness.
High-intensity Focused Ultrasound System Market
Ultimately, the High-intensity Focused Ultrasound System Market is evolving from a niche therapeutic category into a broader precision-treatment ecosystem. The organizations that will define the next phase of competitive advantage are those that can read the convergence of technology, regulation, and clinical adoption with precision and act on it quickly. This research is designed to give leadership that clarity, equipping decision-makers with the context needed to convert market momentum into durable strategic positioning through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: High-intensity Focused Ultrasound System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microbial ID Market Hits $327.2M in 2025, Set to Reach $600.3M by 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Intelligence for the Microbial Identification Market Beyond 2026
The global landscape for microbial identification is undergoing a structural transformation. What was once a niche laboratory function has evolved into a critical infrastructure component for clinical diagnostics, pharmaceutical quality control, and food safety assurance. As the industry approaches the mid-2026 inflection point, the complexity of regulatory expectations, the acceleration of analytical speed, and the commercialization of rapid identification workflows are converging to reshape competitive dynamics. This article distills the strategic essence of our latest Microbial Identification Market research, designed to equip executives, procurement leaders, and product strategy teams with the contextual intelligence required to navigate the 2026-2032 horizon with confidence.
Understanding where the market is heading is no longer a luxury reserved for R&D teams. It is a boardroom imperative. The decisions being made today regarding instrumentation adoption, database licensing, service-level agreements, and regional expansion will determine whether organizations capture the compounding value of a rapidly maturing ecosystem or fall behind fragmented, slower-moving competitors. Our new analysis provides a rigorous, forward-looking framework to support those decisions, combining historical trajectory modeling, technology adoption curves, and competitive intelligence into a single actionable reference.
Market Trajectory: From Modest Growth to Sustained Expansion
The decade preceding 2026 has established a clear upward baseline for microbial identification. Revenue across the global market progressed from a foundational level in 2020 and climbed steadily through the middle of the decade, reflecting broader adoption of rapid phenotypic and genotypic identification platforms across integrated laboratory networks. By 2025, the industry reached an estimated valuation that underscored the shift from early-adopter experimentation to routine operational deployment.
Looking forward, the projection for 2026 places the market at a new threshold, with sustained momentum carrying the total addressable size through the end of the forecast window. The compound annual growth rate over the 2026-2032 period is projected at 9.07 percent, a pace that signals durable demand rather than a temporary peak. Growth will be driven by multiple reinforcing forces: the increasing integration of microbial identification into antimicrobial stewardship programs, the standardization of quality control workflows in pharmaceutical manufacturing, and the expanding expectations for traceability in food and environmental testing.
Notably, the trajectory does not follow a simple linear path. The forecast reflects periods of consolidation, technology-driven step changes, and regional adoption variation that will reward organizations capable of timing their investments to match the rhythm of clinical and industrial procurement cycles. Executives who rely on single-point estimates or static snapshots risk misallocating capital. A structured, multi-scenario view of how the market scales through 2032 is essential for capacity planning, partnership strategy, and M&A screening.
Segmentation Dynamics: Where Value Is Concentrated and Where It Is Emerging
The structure of the microbial identification market is defined by meaningful concentration in specific technology classes, application domains, and geographies. While the overall market expands, value is not distributed evenly across all categories. The research maps how distinct platforms and use cases capture disproportionate share, shaped by regulatory clearance timing, laboratory workflow compatibility, and the breadth of organism coverage each solution can support.
Technology leadership continues to be anchored by high-throughput analytical approaches that deliver rapid turnaround with minimal sample preparation. Within the broader portfolio of methods, certain categories command a larger share of the revenue pool, while complementary approaches serve specialized laboratories or regional procurement preferences. The segmentation analysis in our research dissects these balances without oversimplifying them, helping teams understand not only which categories lead today but which are gaining relative momentum as database content, automation, and software integration evolve.
Application-driven demand reveals an equally layered picture. Clinical diagnostics remains the most prominent use case, reflecting the centrality of organism identification in patient care pathways and antimicrobial susceptibility testing. Pharmaceutical manufacturing quality control represents a substantial and growing share, driven by rigorous contaminant control requirements and batch-level traceability mandates. Food safety and environmental monitoring contribute additional, structurally distinct demand streams, each with its own throughput expectations, validation requirements, and service models.
A critical strategic insight from the segmentation work is that the relative weight of each application and technology category is not static. As automated workflows mature and software layers become more deeply integrated into laboratory information systems, the practical meaning of segmentation shifts. A platform that appears dominant in one year can see its relative position adjusted by database expansion, regulatory milestones, or interoperability improvements. Our analysis tracks these dynamics in a way that lets organizations anticipate shifts rather than react to them after reallocation has already occurred.
Microbial Identification Market
Geographic deployment patterns further shape where investments will pay off most efficiently. Certain regions exhibit larger baseline demand and more mature procurement environments, while others present faster relative growth trajectories as laboratory infrastructure modernizes. The research provides regional nuance at a level of granularity that supports multi-market entry planning, distribution partnership evaluation, and localization of service offerings, while preserving the confidentiality of the exact split figures that our clients obtain in full.
Competitive Differentiation: Bruker Corporation and bioMérieux as Strategic Anchors
The competitive environment for microbial identification is concentrated, yet it is far from static. A handful of established players shape the direction of technology standards, regulatory expectations, and customer operating norms. Among them, Bruker Corporation and bioMérieux stand out as companies whose product strategies and recent milestones illustrate how leadership is being contested and defended in the current cycle.
Bruker Corporation, headquartered in Billerica, Massachusetts, has focused its identification strategy on the MALDI Biotyper CA System, leveraging FDA-cleared MALDI-TOF mass spectrometry for rapid identification of gram-positive and gram-negative bacteria, anaerobes, and yeasts from cultured isolates. The platform’s value proposition extends beyond raw identification speed; it includes MBT Compass HT CA software, which is designed to streamline laboratory workflows and reduce manual handling steps. This emphasis on workflow efficiency reflects a broader industry trend in which instrumentation must prove not only analytical performance but also operational fit within highly constrained laboratory schedules.
In October 2025, Bruker received FDA clearance for Claims 7 and 8 of the MALDI Biotyper CA System, expanding the cleared reference library to 549 species and introducing MBT FAST Shuttle US IVD and MBT Compass HT CA software. From a strategic standpoint, this clearance matters because it broadens the population of organisms that laboratories can confidently identify within a cleared workflow, potentially increasing the system’s relevance across both clinical and industrial settings. Database breadth and software integration are increasingly important differentiators, and this milestone illustrates how platform maturity can be extended without changing the underlying hardware category.
bioMérieux, based in Marcy-l’Étoile, France, pursues a similarly focused but distinct approach. Its VITEK MS PRIME and VITEK COMPACT PRO systems combine FDA 510(k)-cleared MALDI-TOF with automated identification and antimicrobial susceptibility testing workflows, targeting both clinical and industrial microbial identification. A distinguishing feature of bioMérieux’s offering is the expanded database capability for mycobacteria, molds, and resistant pathogens, which directly addresses laboratories’ need to manage organisms that are historically slower or more difficult to identify with confidence.
In March 2025, bioMérieux secured FDA 510(k) clearance and launched the VITEK COMPACT PRO ID/AST system for rapid microorganism identification and antibiotic susceptibility testing in clinical and industrial laboratories. This development reinforces the company’s positioning at the intersection of identification and downstream testing, an integration that matters to laboratories seeking to compress turnaround times while preserving interpretive context. For organizations comparing platform options, these types of integrated workflows can influence total cost of ownership, space utilization, and staffing requirements.
Both companies demonstrate that the competitive battleground is increasingly defined by cleared use cases, database coverage, software-driven efficiency, and the ability to serve multiple end-use environments without compromising validation or reproducibility. For executives evaluating vendor relationships, understanding these differential strengths is more valuable than comparing instrument lists in isolation. Our research analyzes each player’s strategic posture, recent development history, and likely direction of travel, providing the context needed to interpret vendor claims against market realities.
Regulation, Standards, and the Shaping of Market Access
Regulatory and standards frameworks are not merely compliance issues; they are market-shaping forces. In microbial identification, the interaction between clearance pathways, certification requirements, and reimbursement mechanisms influences which solutions gain commercial traction, how quickly they scale, and which laboratories are willing or able to adopt them.
One of the most consequential dynamics for the United States market is the relationship between FDA 510(k) clearance and reimbursement through CPT codes. When a microbial identification test aligns with clearance expectations and coding structures, the path from laboratory adoption to sustainable financial operation can become materially smoother. This linkage is especially important for clinical laboratories that must justify capital expenditure and recurring consumables within tightened operating budgets.
Beyond clearance, quality system expectations such as ISO 13485 certification remain central to medical-grade systems. Laboratories and procurement teams increasingly view certification as a baseline indicator of process discipline and reliability, particularly where identification results feed directly into regulated workflows. In pharmaceutical manufacturing and clinical environments, the credibility of a platform often depends as much on its quality infrastructure as on its analytical output.
Regulatory developments also intersect with broader institutional priorities such as antimicrobial stewardship. Clearance milestones for ID/AST-capable systems support laboratory use cases that help stewardship programs act on identification and susceptibility information more quickly. This alignment between technology and institutional mission can be a significant adoption driver, because it gives laboratory leadership a narrative that extends beyond instrument performance to organizational impact. These dynamics are explored in detail in the report’s market dynamics section, where regulatory events are linked to adoption consequences and commercial timing.
What the Research Delivers: Operational Intelligence for Decision-Makers
This market research is structured to function as a working strategic asset, not a static summary. It is designed for teams that need to translate market knowledge into procurement timing, product planning, regional prioritization, and competitive positioning. The report’s operational value rests on several interrelated components.
First, the report provides a full historical and forecast view of market size and growth, including the underlying trajectory that connects the 2020 baseline through the 2025 reference year and out to 2032. This multi-year structure supports capacity planning, demand forecasting, and revenue modeling with a consistent analytical basis.
Second, the segmentation analysis breaks down technology types, application areas, and regional deployment patterns in a way that allows clients to assess where opportunity is concentrated and where differentiation is most achievable. The segmentation framework is built to reveal relative positioning and growth intensity, helping teams determine whether to compete in crowded categories or pursue higher-margin, faster-growing niches.
Third, the competitive landscape assessment profiles major participants and maps their strategic moves, recent clearances, product updates, and market focus. This section is intended to support vendor evaluation, partnership screening, and competitive threat analysis. Where relevant, it also highlights how product-level developments interact with broader market trends such as database expansion, workflow automation, and cleared-use-case expansion.
Fourth, the report examines market dynamics, including regulatory drivers, reimbursement linkages, quality standards, and stewardship-related adoption pressures. By connecting policy and standards to commercial behavior, the analysis helps teams anticipate demand shifts that may not be visible in headline market size alone.
Finally, the research incorporates strategic interpretation layers that translate data into decision readiness. Rather than leaving the reader with isolated figures, it provides the reasoning needed to evaluate entry timing, regional prioritization, technology mix, and competitive exposure. The full study preserves a level of detail that enables direct application to internal models, while the present article intentionally focuses on the strategic framework and the nature of the intelligence available.
Why This Research Matters for 2026 Decisions
The 2026 decision window is particularly important because it sits at the intersection of several compounding forces. Market growth is robust enough to reward early positioning, yet fast enough that delays can result in missed share and higher acquisition costs. Technological progress is material, with cleared databases and software-driven workflows expanding the practical value of established platforms. Regulatory and reimbursement dynamics are entering a more influential phase, increasing the importance of clearance status, certification, and coding alignment in adoption decisions.
In that environment, organizations need more than a forecast number. They need a defensible view of how growth is distributed, where competitive intensity is rising, how regulation will shape access, and which vendor strategies indicate durable advantage versus short-cycle positioning. The research is built to provide that view. It supports capital allocation, vendor selection, market entry sequencing, and product roadmap planning by grounding them in a consistent, evidence-based market structure.
Executives who act on this intelligence early can shape their strategies around the market’s actual contours rather than its visible headline. That includes deciding where to compete on workflow integration, where to invest in database and coverage breadth, where to emphasize service and validation support, and where to avoid overcommitting to categories that are likely to face margin pressure or substitution risk. The report is designed to make those choices more deliberate and less reactive.
Microbial Air Samplers Market
Conclusion: Strategic Clarity for a Market in Motion
The microbial identification market is entering a phase in which analytical performance, workflow efficiency, regulatory alignment, and commercial execution will separate durable players from marginal ones. The growth trajectory through 2032, the 9.07 percent CAGR, and the multi-category concentration of demand all point to an environment rich with opportunity but demanding in execution. Organizations that understand the structure of that environment will be better placed to allocate resources, choose partners, and time their moves.
This article has outlined the strategic logic behind the new market research and described the types of insight it provides for 2026 decision-making. To obtain the complete segmentation data, forecast detail, competitive profiles, and dynamic analysis needed for internal planning, we invite you to access the full report and its supporting materials. The remainder of the market’s specific composition, regional balances, and precise category values are presented in full within the study, where they can be used directly for modeling, benchmarking, and strategic planning.
For detailed analysis of this topic, please visit the official page: Microbial Identification Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rupture Disc Market Hits $678.2M in 2025, Projects $874.6M by 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Rupture Disc Market: Navigating Growth and Compliance Through 2032
The global industrial landscape is undergoing a profound transformation, driven by tightening safety regulations, evolving material science, and an unwavering focus on operational integrity. Within this complex ecosystem, pressure relief systems remain a cornerstone of process safety management, with the rupture disc standing as a critical, non-reclosing device designed to protect equipment from exceeding allowable pressure limits. As organizations look toward the 2026 fiscal year and beyond, the ability to anticipate market shifts, understand competitive maneuvers, and align procurement strategies with regulatory trends is no longer optional—it is a strategic imperative. This analysis draws from the latest comprehensive market study on the Rupture Disc Market, offering a high-level view of the trajectory defined by data spanning from 2020 through the forecast horizon of 2032.
Market Trajectory and Macroeconomic Signals
The rupture disc market has demonstrated resilience and steady expansion over the past half-decade, reflecting the broader industrial demand for reliable pressure management solutions. Historical data from 2020 to 2025 reveals a trajectory of measured growth, with the global market valued at approximately 597.5 million USD in 2020. Despite minor fluctuations in the early years, the market strengthened through 2023 and 2024, reaching a valuation of 646.06 million USD before continuing its upward trajectory to an estimated 678.2 million USD in the 2025 base year. This historical consolidation sets the stage for an accelerating growth phase, with projections indicating a compound annual growth rate (CAGR) of 3.7 percent over the forecast period from 2026 to 2032.
By 2026, the market is anticipated to surpass the 722 million USD threshold, with growth compounding annually to reach a projected valuation of 874.6 million USD by 2032. This sustained expansion is underpinned by continuous investments in industrial infrastructure, heightened awareness regarding pressure vessel safety, and the indispensable role of rupture discs in preventing catastrophic failures across high-risk environments. For strategic planners and procurement leaders, these macro-level figures are not merely statistics; they are indicators of market maturity and opportunity. Understanding the pace and volume of this growth allows enterprises to calibrate their capacity planning, investment timelines, and risk mitigation frameworks with precision, ensuring they remain competitive in a sector that values reliability and compliance above all else.
Segmentation Dynamics: Materials and Applications Driving Demand
A deeper examination of the market structure reveals distinct preferences and performance drivers across material classifications and end-use applications, shaping the strategic landscape for manufacturers and buyers alike. The market is fundamentally bifurcated by material composition, where metallic rupture discs command a dominant share of the revenue landscape, reflecting their widespread adoption in high-pressure and high-temperature industrial environments where structural integrity and burst precision are paramount. Graphite and non-metallic variants, while representing smaller portions of the total market value, hold significant strategic importance in specialized applications involving highly corrosive media or extreme thermal conditions where metallic alternatives may be compromised. The demand for graphite solutions, in particular, underscores a growing industry need for materials that offer temperature-independent properties and resistance to chemical degradation, aligning with the operational realities of modern processing facilities.
In parallel, the application spectrum illustrates the diverse utility of rupture discs across critical industrial verticals. The oil and gas sector remains a substantial contributor to market revenue, driven by the relentless demand for overpressure protection in exploration, refining, and pipeline infrastructure. The chemical processing industry follows as another major pillar, leveraging rupture discs to maintain safety standards in reactors, storage vessels, and distillation columns where hazardous substances are handled. Meanwhile, the pharmaceutical and biotechnology segments are experiencing notable strategic relevance, fueled by stringent hygiene requirements and the adoption of sanitary designs that ensure cleanability, sterilization compatibility, and traceability. Other application areas further diversify the market, encompassing food and beverage processing, extrusion operations, and general industrial processes that require reliable pressure relief without compromising product purity or process efficiency. For decision-makers, recognizing which verticals are driving volume and which materials are gaining traction in specific process conditions is essential for tailoring product portfolios and supply chain strategies.
Regulatory Pressures and Technical Standards as Growth Catalysts
The rupture disc market is inextricably linked to an evolving regulatory environment, where compliance is not a static checkbox but a dynamic requirement that shapes product development, procurement criteria, and operational validation. Leading manufacturers are increasingly aligning their product portfolios with rigorous international standards, ensuring that their devices meet the exacting demands of modern processing facilities. Sanitary rupture discs, for instance, are being engineered to comply with ASME BPE, USP Class VI, and 3A standards, addressing the critical needs for traceability, cleanability, and sterilization in pharmaceutical and biotech environments. These compliance frameworks are not merely administrative; they directly influence the selection of disc types, the validation of installation procedures, and the long-term maintenance protocols that facilities must adhere to in order to pass regulatory audits and maintain operational licenses.
Rupture Disc Market
In the food, beverage, and pharmaceutical sectors, the emphasis on hygiene and process safety has accelerated the adoption of hygienic rupture discs that are compatible with Clean-in-Place and Sterilize-in-Place procedures, while also offering vacuum resistance necessary for sterilization conditions. Similarly, graphite-based solutions are being validated for FDA conformance in applications involving corrosive media, with material properties that remain stable across temperature variations. Beyond end-product certifications, the industry is witnessing a push toward rigorous raw material traceability and in-house lot qualification testing that exceeds standard ASME and ISO code requirements for cycle life and burst tolerance. This heightened focus on material provenance and performance verification creates a competitive differentiator for manufacturers who can demonstrate superior quality control, while simultaneously raising the bar for buyers who must ensure that their pressure relief assemblies meet both operational and regulatory benchmarks. For strategic organizations, staying ahead of these regulatory currents requires continuous engagement with industry standards, proactive collaboration with equipment suppliers, and a comprehensive understanding of how compliance mandates will evolve through the forecast period.
Competitive Landscape and Strategic Positioning
The rupture disc market is characterized by a moderately concentrated competitive environment, where a handful of established players command a significant portion of the market share, while specialized manufacturers and regional contenders compete on innovation, niche applications, and geographic reach. The collective presence of key industry participants underscores the importance of brand reputation, technical expertise, and product breadth in securing long-term customer relationships. Strategic analysis of the competitive field reveals that market leaders are increasingly differentiating themselves through targeted product expansions, enhanced catalog offerings, and the development of assembly-level solutions that simplify installation and improve overall process safety.
Several core enterprises exemplify the strategic directions shaping the market. Continental Disc Corporation, based in Liberty, Missouri, has consistently reinforced its market position by expanding its portfolio of high-performance reverse-acting and tension rupture discs, with a particular emphasis on sanitary offerings compliant with ASME BPE, USP Class VI, 3A, and ISO standards. The company's recent initiatives, including the expansion of its APX rupture disc line to accommodate larger sizes for demanding industrial applications, the launch of the HPX-CTG cartridge rupture disc assembly to streamline installation and enhance process safety, and the introduction of the APX family for high-performance overpressure protection, illustrate a clear strategic focus on delivering scalable, robust solutions that address evolving customer requirements. Fike Corporation, headquartered in Blue Springs, Missouri, has carved out a strong niche in hygienic rupture disc technology, offering designs such as the AXIUS SC, SHX, and RD540 SC, as well as extruder rupture disc devices that are compatible with CIP/SIP protocols for food, beverage, and pharmaceutical applications, while supporting both reverse-acting and forward-acting configurations to meet diverse process needs.
ZOOK Enterprises LLC, operating from Chagrin Falls, Ohio, has established itself as a global manufacturer providing metal and graphite rupture disks across reverse-acting, forward-acting, sanitary, and ultra-low or bi-directional configurations, serving a broad spectrum of industries including chemical, pharmaceutical, extrusion, and food processing. BS&B Safety Systems, based in Tulsa, Oklahoma, continues to deliver comprehensive rupture disk devices and pressure relief solutions that span industrial and process safety applications, reinforcing its role as a provider of integrated safety systems. Technetics Group, located in Los Angeles, California, brings a focus on high-precision rupture discs and engineered components that contribute to advanced pressure relief systems. Completing the competitive mosaic is FDC Co., Ltd., based in South Korea, which contributes to the global supply landscape with rupture disc products including the KSRRL series designed for industrial pressure relief applications. The presence of such diverse players highlights the importance of evaluating not just product specifications, but also the strategic alignment of each supplier with regional requirements, material capabilities, and compliance documentation.
Market concentration metrics further illuminate the competitive structure, with the top three companies collectively accounting for approximately 49.5 percent of the market, and the top five players consolidating an even larger share at roughly 65.2 percent. This concentration pattern suggests that while the market remains accessible to specialized and emerging entrants, scale, credibility, and established distribution channels play a decisive role in capturing significant market volume. For buyers and investors, understanding this concentration dynamic is critical for assessing supply chain resilience, negotiating leverage, and the potential for competitive disruption. Strategic procurement decisions must therefore weigh the advantages of working with established market leaders who offer broad portfolios and global support against the opportunities presented by specialized manufacturers who may provide tailored solutions or competitive pricing in specific segments.
Forecast Outlook and Strategic Implications for 2026 and Beyond
Looking ahead to the 2026 forecast period and the subsequent years through 2032, the rupture disc market is positioned for sustained growth, but the pathways to value capture will require nuanced strategic planning. The projected trajectory indicates that while the overall market will expand steadily, the relative performance of different materials, applications, and regions will diverge based on localized industrial activity, regulatory enforcement intensity, and the pace of technological adoption. Enterprises that proactively map their operations against these evolving dynamics will be better equipped to allocate capital, optimize inventory, and forge partnerships that enhance both safety performance and cost efficiency.
Strategically, the emphasis for 2026 should center on several key imperatives. First, organizations must deepen their understanding of material selection criteria, recognizing that the choice between metallic, graphite, and non-metallic rupture discs is not merely a technical specification but a long-term decision that affects maintenance cycles, compliance records, and operational reliability in specific media environments. Second, the growing importance of sanitary and hygienic designs across pharmaceutical, biotechnology, and food processing sectors demands that buyers and suppliers align on validation protocols, cleanability standards, and sterilization compatibility to avoid costly retrofit or compliance gaps. Third, the competitive landscape calls for a balanced sourcing strategy that acknowledges the strength of concentrated market leaders while remaining open to specialized suppliers who can deliver differentiated value in narrow but critical application niches. Fourth, the trend toward integrated assembly solutions and simplified installation methodologies points to a broader industry shift toward lifecycle value over piece-price procurement, encouraging decision-makers to evaluate total cost of ownership, installation complexity, and long-term safety performance.
Furthermore, the forecast horizon presents opportunities for organizations that can anticipate regional demand shifts and adjust their supply chains accordingly. While the analysis of regional segmentation remains a detailed component of the full market study, the overarching principle is clear: growth will not be uniform, and strategic agility will be rewarded. Companies that invest in market intelligence, maintain robust vendor evaluation frameworks, and stay attuned to regulatory developments will be positioned to navigate the complexities of the forecast period with confidence. The data projected through 2032 serves as both a benchmark and a compass, guiding stakeholders toward decisions that align with long-term industry trajectories rather than short-term fluctuations.
Conclusion: Accessing Comprehensive Intelligence for Strategic Advantage
The rupture disc market stands at the intersection of safety, compliance, and industrial growth, offering a landscape where informed decision-making can yield significant competitive and operational advantages. The macro-level data, segmentation insights, regulatory trends, and competitive dynamics outlined here represent only the introductory layer of a much deeper analytical framework. For organizations seeking to translate these high-level signals into actionable strategies for 2026 and the forecast period through 2032, a granular understanding of specific market sizes, regional contributions, application breakdowns, material performance metrics, and detailed competitor profiles is essential. Such intelligence enables precise budgeting, targeted market entry, optimized product development, and risk-aware procurement strategies that align with both immediate operational needs and long-term growth objectives.
The full market research study provides a comprehensive examination of these dimensions, offering the depth and granularity required to move beyond general trends and into the specifics that drive real-world strategic outcomes. By exploring the complete dataset, stakeholders can uncover hidden opportunities, identify potential supply chain vulnerabilities, and benchmark their positioning against the broader industry landscape. The insights contained within the full report are designed to empower executives, procurement leaders, product managers, and investors with the clarity needed to make confident, data-backed decisions in a market where precision and reliability are paramount. We invite you to access the complete study to gain the full spectrum of intelligence necessary to navigate the rupture disc market with strategic foresight and operational excellence.
Abrasive Disc Market
For detailed analysis of this topic, please visit the official page: Rupture Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Market Hits $36.9B, 9.25% CAGR to $68.49B by 2032
By pmarketresearch, 2026-09-15
Unlocking Value in a Reshaping Landscape: Strategic Imperatives for the Dental Market Through 2032
The global dental sector is navigating a period of profound transformation. Driven by an aging population, expanding insurance coverage, and rapid technological integration, the market has demonstrated remarkable resilience and growth potential. For enterprise leaders, investors, and strategic planners, understanding the trajectory of this sector is not merely an academic exercise but a critical component of capital allocation and product roadmapping for the coming years.
Our latest comprehensive market research study offers a rigorous examination of the Dental Market, providing a data-rich foundation for decision-making in 2026 and beyond. This article serves as a strategic overview, highlighting the macro trends and competitive dynamics shaping the industry, while outlining the actionable intelligence contained within our full report.
Market Trajectory and Macro Growth Signals
The historical performance of the dental sector provides a robust baseline for forecasting future demand. Our analysis tracks market performance from 2020 through 2025, capturing the recovery patterns and sustained expansion following global economic disruptions. The convergence of post-pandemic oral health awareness, rising disposable incomes in emerging economies, and the aesthetic demands of a digitally native consumer base has created a compelling growth environment.
Looking ahead, the market outlook remains exceptionally strong. Our forecasts project continued double-digit expansion over the next several years, driven by consistent demand across multiple vectors. The compound annual growth rate (CAGR) of 9.25% during the forecast period (2026-2032) underscores the sector's momentum. This growth is not linear; it is punctuated by waves of innovation, shifts in care delivery models, and evolving regulatory frameworks. For organizations strategizing for 2026, these projections offer a clear signal: the market is expanding, and the window for securing competitive advantage is open.
Revenue projections indicate a steady climb toward significant valuation milestones by the early 2030s. The trajectory suggests that cumulative reinvestment in dental infrastructure, technology, and consumables will yield substantial returns for market participants who align their strategies with these growth vectors. Understanding the magnitude of this expansion is essential for capacity planning, R&D budgeting, and M&A evaluation.
Dental Material Market
Macro Dynamics Shaping the 2026 Operating Environment
While top-line growth is attractive, success in 2026 requires a nuanced understanding of the underlying dynamics that influence margin profiles, supply chain stability, and consumer behavior. Our report dissects these forces to provide a clear picture of the operational realities facing dental enterprises.
Dental Market
Economic Pressures and Reimbursement Realities
Financial sustainability remains a central concern for practice owners and dental service organizations (DSOs). Recent data from the ADA Health Policy Institute indicates that while provider reimbursement rates remained stable in late 2025, they have not kept pace with overall inflation and rising practice expenses. This gap creates pressure on profitability, necessitating operational efficiencies and value-based service offerings. Simultaneously, material costs are rising; prices for dental equipment and supplies increased by 5% from the beginning of 2025. Navigating these cost dynamics requires precise procurement strategies and a keen eye on vendor negotiations.
Labor Market Nuances
The workforce landscape is evolving with subtle but significant shifts. As of December 2025, the total number of jobs in dental offices saw a slight monthly contraction of 0.2%, yet the year-over-year trend remained positive with a 1.3% increase. This suggests a tightening labor market where talent retention and specialized skill development are becoming critical differentiators. Organizations must consider how staffing models, training investments, and automation can mitigate labor constraints while maintaining high standards of care.
Regulatory and Ethical Clarity
The regulatory environment continues to mature, adding layers of compliance that demand attention. In May 2025, the Dental Trade Alliance issued a revised U.S. Code of Ethics, providing greater clarity on interactions between manufacturers, distributors, and dental professionals. This update reinforces the importance of transparency and ethical engagement in commercial activities. Companies that proactively align their practices with these standards not only mitigate risk but also enhance their reputation and trustworthiness within the professional community.
Competitive Landscape: Incumbents, Innovators, and Consolidation
The dental market is characterized by a mix of established global leaders, specialized innovators, and robust distribution networks. Market concentration metrics indicate a moderately consolidated environment, with the top three players holding a CR3 of 42.8% and the top five reaching a CR5 of 48.2%. This structure suggests that while scale advantages exist, there is still significant room for differentiation and niche leadership.
Several key players define the competitive arena. Dentsply Sirona Inc., headquartered in Charlotte, North Carolina, stands as a leading global manufacturer of dental equipment, implants, restorative materials, and digital solutions. Their comprehensive portfolio positions them as a central force in both clinical delivery and practice management technology. Straumann Group, based in Basel, Switzerland, remains a global leader in dental implants, prosthetics, and regenerative products, leveraging strong clinical evidence and brand equity in high-value segments.
Innovation in orthodontics and digital workflows is exemplified by Align Technology, Inc. of San Jose, California. As the developer of Invisalign clear aligners and digital orthodontics technology, Align continues to drive shifts in treatment preferences and data-driven care. Ivoclar Vivadent AG, located in Schaan, Liechtenstein, and GC Corporation of Tokyo, Japan, are pivotal players in dental materials, ceramics, and restorative products, serving the essential needs of clinical procedures across diverse geographies. Coltene Group, Kerr Corporation, and 3M Oral Care round out a formidable field of manufacturers focused on consumables, endodontics, rotary instruments, and preventive solutions.
The distribution ecosystem is equally vital. Henry Schein, Inc., Patterson Companies, Inc., and Benco Dental Supply Company form a backbone of supply chain logistics, offering supplies, equipment, and services to a vast network of dental professionals. Henry Schein and Patterson provide full-service solutions that integrate technology and practice management, while Benco serves over 30,000 professionals across the United States with a localized, responsive approach. Additionally, organizations like Yankee Dental Congress facilitate trade and supplier networks, supporting the commercial infrastructure that keeps the market vibrant.
Recent developments highlight the pace of product innovation. In 2025, COLTENE Group launched six new innovations, including HySolate Liquid Dam for advanced gingiva protection and Kenda ShapeGuard for next-generation polishing. Kerr Dental introduced next-generation shaping solutions, pre-sterilized diamond burs, and bioceramic sealers, enhancing procedural efficiency. Dentsply Sirona expanded its digital ecosystem with a new implant product selection guide on its U.S. e-commerce platform featuring the DS OmniTaper Implant. Other players like Parkell and Garrison Dental Solutions also unveiled advanced composites and matrix systems, signaling a continuous stream of incremental improvements that cumulatively raise the bar for performance and patient experience.
Strategic Implications for Enterprise Decision-Makers
For executives preparing for 2026, the interplay of growth, cost pressures, and competitive intensity demands a multifaceted strategy. Our research identifies several critical focus areas:
- Product and Portfolio Alignment: With consumables representing a significant share of revenue and equipment driving long-term value, companies must balance their portfolios to address immediate clinical needs while positioning for digital and precision advancements. Understanding the specific revenue contributions and growth rates of each segment is essential for resource allocation.
- Geographic Diversification and Local Insight: Growth opportunities vary significantly across regions. While mature markets offer stability and high per-capita spend, emerging regions present volume potential and infrastructure development needs. A granular understanding of regional market sizes, maturity levels, and consumer preferences is required to tailor go-to-market strategies effectively.
- Channel and Distribution Optimization: The role of distributors is evolving from mere logistics to value-added partner ecosystems. Leveraging the strengths of major distributors and trade networks can enhance market reach and customer engagement. Decision-makers must evaluate channel partnerships based on service quality, geographic coverage, and alignment with brand positioning.
- Innovation and Time-to-Market: The frequency of product launches among key competitors underscores the need for agile R&D and rapid commercialization. Staying ahead requires not only technological superiority but also a deep understanding of clinical workflows and practitioner pain points.
- Risk Management and Compliance: With reimbursement pressures, cost inflation, and evolving ethical codes, a proactive approach to risk is non-negotiable. Building resilience into supply chains, monitoring reimbursement trends, and adhering to the highest standards of professional conduct are foundational to long-term success.
Inside the Research: What Our Full Report Delivers
This article provides a strategic snapshot, but the depth of insight required for confident decision-making lies in our comprehensive market research report. Designed for senior leadership, strategy teams, and investors, the study offers an exhaustive analysis of the Dental Market, encompassing historical performance, detailed forecasts, and segment-level intelligence.
The report delivers actionable content across multiple dimensions:
- Market Sizing and Forecasting: We provide precise revenue estimates and growth projections spanning the base year through the forecast period of 2032. The analysis captures the full trajectory of market expansion, enabling accurate budgeting and investment planning.
- Segmentation Analysis: The research breaks down the market by region, type, and end-user, revealing the distinct performance characteristics and opportunities within each segment. This granular view allows stakeholders to identify high-growth pockets, assess competitive intensity, and prioritize markets based on revenue potential and strategic fit.
- Competitive Profiling: Detailed company profiles examine the capabilities, market positions, and recent activities of key players. Our analysis goes beyond basic descriptions to evaluate strategic moves, product launches, and positioning tactics, offering a clear map of the competitive landscape.
- Industry Dynamics and Drivers: We explore the macroeconomic, regulatory, and technological factors influencing market behavior. This includes analysis of reimbursement trends, supply chain conditions, labor dynamics, and ethical standards, providing context for interpreting market data and anticipating shifts.
- Strategic Recommendations: Synthesizing data and qualitative insights, the report offers tailored recommendations for navigating the market. Whether the goal is market entry, product development, M&A target evaluation, or operational optimization, our findings provide a structured framework for action.
We deliberately withhold the granular percentage splits and exact monetary values for specific regions, product types, and end-user categories in this public overview. These critical data points are integral to precise financial modeling and strategic planning. Access to the full report ensures that decision-makers have the complete data set needed to build robust business cases and avoid assumptions that could undermine competitive positioning.
Conclusion: Positioning for the 2026 Horizon
The Dental Market is on a robust growth trajectory, supported by favorable demographics, technological advancement, and increasing emphasis on oral health. However, the environment in 2026 presents a complex mix of opportunity and challenge. Rising costs, reimbursement gaps, labor constraints, and a competitive landscape defined by both scale players and agile innovators require a sophisticated approach to strategy.
Our market research equips organizations with the intelligence to navigate this complexity with confidence. By combining macro-level growth signals with micro-level segment analysis, competitive intelligence, and dynamic industry context, the report serves as an indispensable tool for crafting strategies that capture value and sustain advantage. We invite you to explore the full findings to unlock the detailed data and insights necessary for informed decision-making in the year ahead and throughout the forecast horizon.
For detailed analysis of this topic, please visit the official page: Dental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com