

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Phosphate Ester Market Hits $2,285.0M in 2025, Forecasted to Hit $3,298.4M by 2032

Strategic Intelligence for the Phosphate Ester Market: Navigating Growth from 2026 and Beyond
The global phosphate ester market is entering a decisive inflection point. As industrial demand reshapes around performance chemistry, regulatory tightening, and sustainability mandates, executives need more than headline figures to chart their next move. Our latest market research provides a rigorous, decision-ready assessment of the sector, grounding strategic planning in a complete historical baseline and a structured ten-year outlook. This article previews the analytical architecture of the study, explains why the 2026–2032 window matters for capital allocation and product strategy, and outlines the operational intelligence embedded in the full report.
For strategy leaders, the question is no longer whether phosphate esters will continue to matter across flame retardants, lubricants, hydraulic fluids, plasticizers, and specialty surfactants. The question is where value will concentrate, which application segments will command pricing power, and how supply-side dynamics will reshape competitive positioning. The research is built to answer those questions with granularity while keeping the focus on actionable strategy rather than static description.
A Market at Scale: Tracking the Trajectory into 2026
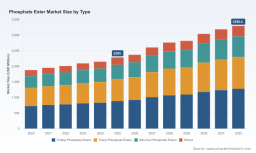
The sector has demonstrated consistent expansion across the historical review period, with total market revenue climbing from approximately 1,880 million USD in 2020 to an estimated 2,285 million USD in 2025. That progression reflects more than steady increments; it signals a market absorbing new performance requirements, replacing legacy chemistries in selective applications, and benefiting from broader industrial activity across multiple end-use verticals.
The forward view reinforces the strategic importance of this window. The market is projected to reach roughly 2,371 million USD in 2026, with continued expansion through the forecast horizon and a valuation approaching 3,298 million USD by 2032. The implied compound annual growth rate of 5.4 percent frames phosphate esters as a mature-but-energized category: growth is not explosive, but it is durable and increasingly tied to performance differentiation, formulation innovation, and regional supply reconfiguration.
For 2026 decision-making, that trajectory has direct consequences. Budget cycles, capacity planning, and partnership strategy must account for a market that is large enough to support specialized investments yet varied enough that aggregate growth can mask divergent segment fortunes. Our study treats growth as a starting point for deeper allocation logic rather than a standalone headline.
Why 2026 Is a Pivotal Planning Year
2026 functions as both a baseline and a branching point. Several forces are converging at once: evolving end-user requirements in mobility and industrial fluids, heightened scrutiny of chemical sourcing and emissions, and a competitive landscape in which scale players and specialty specialists are pursuing different value-creation models. Executives who treat the market as monolithic risk overinvesting in commoditized lanes or underweighting higher-margin application territories.
The strategic opportunity lies in understanding where the 5.4 percent trajectory is being generated and where it is likely to accelerate or compress. Some application areas benefit from regulatory-driven substitution and safety mandates; others gain from efficiency demands in lubrication and hydraulic systems; still others are shaped by formulation trends in coatings, inks, and consumer-facing formulations. The report maps these pathways in a way that supports product portfolio choices, regional prioritization, and customer engagement strategy.
Phosphate Ester Market
Equally important, the forecast period spans a decade of transition. That long view matters because phosphate ester investments often involve extended commercialization timelines, technical validation, and supply chain qualification. A 2026 decision can shape cost structure and market access well into the late 2020s. The study is designed to help leaders connect near-term actions with longer-cycle outcomes.
Inside the Report: Operational Intelligence for Strategy and Execution
The research is structured to move from market scaffolding to implementation detail. It begins with a full historical reconstruction and a disciplined forecast framework, then moves into segmentation, competitive positioning, and the operational factors that determine execution risk. The emphasis is on usable intelligence: what to monitor, what to benchmark, and where to focus commercial attention.
Key report components include:
- A complete market size and forecast framework with a decade-long view that links historical performance to forward projections, enabling scenario planning around base, upside, and constrained demand conditions.
- A structured analysis of value creation by product type and by application, showing how different segments contribute to the overall market and where differentiation, pricing behavior, and demand momentum diverge.
- Regional market assessment that examines demand centers, supply imbalances, trade exposure, and the strategic implications of shifting manufacturing and sourcing patterns.
- Competitive profiling of leading participants, with attention to product platforms, application focus, production footprint, and the ways companies are positioning for specialty growth versus scale efficiency.
- Market concentration context and the implications for pricing, negotiation leverage, and entry strategy in segments where leading suppliers hold meaningful share.
- Supply-side and feedstock dynamics, including precursor cost behavior, raw material exposure, and the operational sensitivities that influence margin stability.
- Regulatory and trade developments that alter cost structures, market access, and compliance requirements, with practical implications for sourcing and export strategy.
- Recent corporate developments that signal where industry capacity, technology, and application focus are moving, including partnerships, product launches, and acquisitions that reshape regional or segment positioning.
The report is deliberately built for cross-functional use. Corporate development teams can use the segmentation and concentration analysis to assess adjacency and acquisition logic. Commercial leaders can use the application and regional breakdowns to refine targeting and value proposition design. Operations and procurement teams can use the supply-side and regulatory elements to anticipate cost volatility and sourcing constraints.
Competitive Landscape: Scale, Specialization, and Shifting Advantage
The phosphate ester market is shaped by a mix of large diversified chemical companies and focused specialists. The strategic tension is visible in how participants allocate effort: some emphasize broad industrial fluid and flame retardant platforms, others concentrate on surfactant and additive portfolios for personal care or detergent applications, and still others anchor their offerings in fire-resistant hydraulic systems for demanding industrial and aviation environments.
The study profiles a wide set of important participants, including Clariant, Stepan Company, Eastman Chemical Company, LANXESS, Solvay, Dow, AkzoNobel, Croda International, ExxonMobil, Ashland, and Evonik Industries. Rather than treating these companies as a uniform group, the analysis distinguishes their functional positions in the market and the logic behind their product and application choices.
Several patterns are especially relevant for 2026 strategy:
- Specialty platforms are expanding around application-specific value propositions, such as phosphate esters for cleaning products, antistatic and anti-foaming functions in detergents, and multifunctional additives in inks, paints, and coatings.
- Customized formulations are becoming a competitive differentiator in lubricants, gear oils, hydraulic fluids, plasticizers, and agricultural compatibility aids, where performance tuning can support stronger customer lock-in.
- Fire-resistant hydraulic fluids remain a strategically important corner of the market, with established product lines supporting aviation and industrial applications where safety and reliability are non-negotiable.
- Eco-aligned offerings are gaining prominence as companies respond to customer sustainability expectations and broader emissions-reduction goals, creating new angles for product positioning and market entry.
- Personal care, industrial, and specialty surfactant applications continue to provide incremental growth opportunities, particularly where phosphate ester chemistry can be adapted to sensitive or high-performance formulations.
Competitive positioning is not static. Recent activity shows targeted moves in partnerships, product innovation, and regional capacity expansion. For example, Eastman Chemical Company announced a partnership with a leading automotive manufacturer to develop phosphate esters designed for electric vehicle applications. BASF SE introduced a new line of bio-based phosphate esters aimed at reducing carbon emissions in industrial applications. Huntsman Corporation completed the acquisition of a regional competitor, materially expanding its production capabilities in Asia-Pacific. These developments are not isolated headlines; they are indicators of where application demand, regional supply, and sustainability positioning are converging.
Market Dynamics: Cost, Regulation, and Supply Chain Sensitivity
Strategic planning in this market must contend with input-side volatility and policy-driven cost shifts. Precursor behavior remains an important operational variable: n-butanol prices exhibited significant volatility between 700 and 1,200 USD per metric tonne over 2022–2025, reinforcing the sensitivity of tributyl phosphate-related economics to feedstock swings. Meanwhile, tributyl phosphate prices in Asia were recorded at 2,600 USD per metric tonne in December 2025, a benchmark that reflects regional cost pressures and supply conditions relevant to procurement and pricing strategy.
Phosphonate Market
Trade policy and regulatory determinations add another layer of complexity. The US Department of Commerce determined that countervailable subsidies are being provided to producers and exporters of certain alkyl phosphate esters from the People's Republic of China, a development with direct implications for import economics, sourcing strategy, and competitive cost comparisons. In parallel, certain phosphate ester products used in nuclear applications are often subject to dual-use export control regulations in major supplier countries, which can affect distribution pathways, customer qualification, and regional market access.
These factors matter because they influence more than short-term margin. They shape where capacity is attractive, how companies configure their supply chains, and which customer segments can be served most efficiently. The report integrates these dynamics into a cohesive operating view so that strategy teams can anticipate disruption rather than react to it.
Concentration, Regional Logic, and Allocation Strategy
Market concentration provides useful context for both incumbents and new entrants. The sector is not fragmented to the point of undifferentiated competition, nor is it so concentrated that new initiatives are automatically pre-empted. That middle ground creates room for targeted positioning, especially where product performance, regulatory alignment, or regional availability can be leveraged as differentiators.
Regionally, the market’s value distribution reflects differing industrial baselines, demand structures, and trade patterns. The full report examines each major region’s role in the overall market and the strategic implications of their relative scale. Rather than presenting regional data as a static ranking, the analysis connects regional size to sourcing logic, customer density, and the competitive efforts underway to expand or defend position.
This regional view is especially important for companies evaluating production footprint, export strategy, and local supply capability. In a market where feedstock volatility, trade measures, and application-specific demand all vary by geography, regional intelligence is not optional; it is central to cost competitiveness and service reliability.
Where the Full Study Adds Value
The preview above establishes the strategic frame and the analytical rigor of the study. What it cannot do within this format is provide the complete segmentation detail, regional breakdowns, application-level comparisons, and company-specific profiles that turn insight into execution. Those elements are developed fully in the report, where they are integrated into a single decision-support structure.
The complete study enables leaders to:
- Compare contribution patterns across product types and application categories without relying on assumptions imported from unrelated chemical markets.
- Evaluate regional demand centers and supply exposure in a way that supports sourcing, capacity, and market-entry decisions.
- Benchmark competitor positioning against actual product platforms and recent strategic moves rather than broad brand reputation.
- Incorporate feedstock, regulatory, and trade developments into a practical operating plan for pricing, procurement, and compliance.
- Align product roadmap priorities with the application segments most likely to generate differentiated returns over the forecast period.
Conclusion: Turning Market Momentum into Disciplined Strategy
The phosphate ester market is moving with enough scale and enough structural variation to reward disciplined analysis. Aggregate growth provides opportunity, but value capture depends on understanding where that growth is concentrated, which application segments justify specialized investment, and how supply-side and regulatory realities shape execution.
This research is designed to help executives make those judgments with confidence. It combines historical perspective, a ten-year forecast, segmentation logic, competitive analysis, and operational context in a single framework built for 2026 planning and beyond. For leaders who need the full segmentation detail, regional interpretation, and company-level intelligence required to convert strategy into action, the complete report delivers the depth behind this preview.
For detailed analysis of this topic, please visit the official page: Phosphate Ester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com