

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
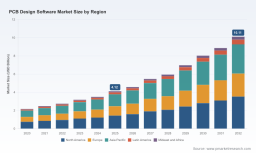
PW Consulting: PCB Design Software Market Hits $4.12 Billion in 2025, Projected to Reach $10.11 Billion by 2032

Navigating the Next Wave: Strategic Imperatives in the PCB Design Software Market (2026–2032)
Executive Summary: A Market at an Inflection Point
The global printed circuit board (PCB) design software market is entering a decisive growth phase. Drawing on historical performance from 2020 through 2025 and an extended forecast horizon stretching to 2032, the sector has demonstrated a consistent upward trajectory, moving from a baseline valuation in the low billions to a projected ten-billion-dollar milestone by the end of the forecast period. With a compound annual growth rate of 13.7%, the market is outpacing broader electronic design automation segments and signaling a structural shift in how hardware engineering teams plan, procure, and deploy design tools.
For enterprise decision-makers, engineering directors, and procurement leaders, these figures are more than macroeconomic indicators. They represent a rapidly expanding addressable market where tool selection, workflow integration, and compliance readiness directly influence product development cycles, time-to-market, and long-term competitive positioning. The PW Consulting PCB Design Software Market report translates this high-level momentum into actionable intelligence, mapping the interplay between software categories, end-use verticals, regional deployment patterns, and the competitive maneuvers shaping the next seven years.
This overview outlines the strategic architecture of the study, highlights the operational insights embedded within its chapters, and demonstrates how senior stakeholders can leverage its findings to align technology roadmaps with market realities. Core quantitative breakdowns remain reserved for the full report, ensuring that detailed segment valuations, regional revenue distributions, and granular application splits are accessed only through the complete intelligence package.
Market Trajectory and Structural Growth Drivers
Between 2020 and 2025, the PCB design software ecosystem expanded from a modest starting valuation to a mid-four-billion-dollar range, reflecting sustained demand across both commercial and industrial electronics development. The forecast period from 2026 to 2032 projects continued acceleration, with revenue expected to climb steadily toward a double-digit billion threshold by 2032. This growth is not merely cyclical; it is anchored in several compounding structural factors.
First, the proliferation of high-density interconnect designs, miniaturized form factors, and multifunction electronic assemblies is pushing design complexity beyond the capabilities of legacy standalone tools. Engineering teams increasingly require bidirectional data flow between schematic capture, layout, signal integrity analysis, and manufacturing verification. Second, the convergence of hardware and software development lifecycles is compressing design iteration windows, raising the premium on integrated suites that reduce handoff friction between electrical, mechanical, and production engineering teams. Third, supply chain volatility and component lifecycle management have elevated the importance of simulation and verification capabilities that de-risk design decisions before prototyping begins.
Regional dynamics further complicate the growth narrative. Demand generation, purchasing behavior, and deployment preferences vary significantly across geography, influenced by local electronics manufacturing density, regulatory environments, and enterprise procurement models. The report examines these regional variations through a framework that connects market size, growth velocity, and adoption maturity without reducing the analysis to superficial geographic rankings. Instead, it emphasizes how regional industrial ecosystems shape tool procurement cycles, vendor negotiation leverage, and the diffusion of advanced design capabilities across different markets.
In parallel, the market is navigating a cost-of-ownership landscape that directly affects adoption patterns. Premium enterprise tool subscriptions carry meaningful annual investment thresholds, and advanced design workflows often require corresponding upgrades to workstation infrastructure and specialized engineering talent. These dynamics create a bifurcated environment in which large OEMs and tier-one suppliers continue to invest in high-end integrated platforms, while small and mid-sized engineering teams evaluate lighter, modular, or open-source alternatives. Understanding how these cost structures influence segment penetration, upgrade cycles, and vendor value propositions is a central theme of the study.
What the Report Delivers: Operational Intelligence for Engineering and Commercial Leaders
The PW Consulting study is structured to support both strategic planning and tactical execution. Rather than functioning as a static market snapshot, it is designed as a decision-support framework that links market sizing to operational consequences for engineering organizations, software vendors, and channel partners. The report’s architecture spans several interconnected analytical dimensions.
At the core of the analysis is a disciplined examination of software categories and their respective roles in modern design workflows. The study differentiates between standalone design environments, schematic capture platforms, layout-oriented tools, simulation and analysis software, and fully integrated PCB design suites. Each category is evaluated not only in terms of market contribution, but also in relation to workflow integration, interoperability requirements, and the practical trade-offs engineers face when selecting tools for specific project profiles. This approach allows readers to understand how segmentation reflects real-world design complexity, rather than treating software categories as isolated commercial buckets.
The application dimension of the report maps software demand across major end-use verticals, including consumer electronics, telecommunications equipment, medical devices, industrial equipment, automotive components, and additional specialized sectors. For each vertical, the analysis addresses the distinct engineering constraints, compliance expectations, and lifecycle characteristics that influence tool selection. Medical device development, for example, introduces rigorous documentation and traceability requirements; automotive and industrial applications impose reliability, thermal, and signal integrity demands that shape simulation and verification priorities; telecommunications workflows increasingly intersect with high-speed signaling and density-driven layout challenges. By aligning segment analysis with these functional realities, the report helps leaders assess where advanced capabilities deliver the highest return and where streamlined toolchains may be more appropriate.
The regional dimension examines how local manufacturing bases, procurement traditions, and regulatory environments influence adoption pathways. Instead of presenting raw geographic rankings, the report contextualizes regional demand within broader industrial ecosystems, highlighting where design tool investment correlates with electronics production growth, where enterprise procurement cycles differ, and where emerging demand centers are reshaping vendor outreach strategies.
PCB Design Software Market
Beyond segmentation, the report includes detailed assessments of deployment preferences, subscription models, integration requirements, and total cost-of-ownership drivers. It also maps the competitive landscape, evaluates vendor positioning, and incorporates recent product developments and industry initiatives that signal where the market is heading. Throughout, the analysis is calibrated to support actionable planning: selecting tools, negotiating licensing terms, preparing engineering teams for regulatory shifts, and anticipating where ecosystem changes will create competitive advantage or risk.
Competitive Landscape: Positioning, Differentiation, and Recent Movements
The PCB design software market remains moderately concentrated, with the top three vendors collectively holding less than a quarter of total market share and the top five approaching but not exceeding one-third. This concentration level indicates a market that is neither fully consolidated nor highly fragmented, creating space for differentiated positioning, niche leadership, and ongoing competitive disruption. The report analyzes the principal participants in this landscape, emphasizing how each vendor’s product philosophy, target audience, and integration strategy shape its commercial trajectory.
Altium LLC has built its commercial identity around a leading integrated design environment that converges schematic capture, layout, simulation, and collaboration within a single workflow. Its positioning reflects the broader market movement toward unified platforms that reduce toolchain fragmentation, particularly for teams that value rapid iteration, accessible usability, and strong ecosystem integrations. Zuken Inc. operates with a more segmented suite strategy, offering enterprise-oriented platforms for complex subsystem and 3D layout, mainstream PCB design solutions, and specialized electrical design tools. This multi-tiered approach allows the company to address both high-complexity enterprise environments and broader mainstream design requirements, reinforcing its presence across different complexity thresholds and organizational scales.
Siemens EDA maintains a strong footprint through platforms that span design, layout, simulation, analysis, and verification. Its portfolio is closely associated with environments where design integrity, manufacturing alignment, and verification discipline are critical, making it a frequent consideration in programs that require robust analysis capabilities and tight integration with broader engineering and manufacturing workflows. Cadence Design Systems, Inc. contributes to the competitive field through platforms that increasingly emphasize AI-enabled design, layout, and analysis functions. As design complexity rises and iteration cycles compress, AI-assisted capabilities are becoming a meaningful differentiator in how tools support routability assessment, constraint management, and design optimization, positioning AI integration as a strategic axis of competition.
A distinct competitive layer includes providers of accessible or open-source-based solutions. RS Components has developed professional-grade and free EDA packages that lower entry barriers for small teams, educators, and cost-sensitive engineering groups. The KiCad Development Team continues to expand an open-source suite that supports schematic capture and PCB layout, reinforcing a community-driven model that competes indirectly with commercial vendors by shaping user expectations around accessibility, extensibility, and cost efficiency. WestDev Ltd. also participates in this ecosystem through its association with certain PCB design software solutions, adding to the diversity of vendor arrangements and licensing pathways available to buyers.
Recent industry activity underscores how competition is intensifying along both product-feature and ecosystem-dimensions. In April 2025, Zuken released an updated version of its mainstream PCB design platform with parallel library paths, AI-assisted workflows, and enhanced signal integrity and collaboration capabilities, signaling a clear push toward productivity improvements and higher-performance design support. By late 2025, the open-source community advanced its own development cadence with successive version updates to its PCB design suite, reflecting continued refinement in a segment that competes on accessibility and community momentum. At the institutional level, a major electronics association launched an introductory PCB design course in early 2026 aimed at new designers, emphasizing foundational schematic and layout skills using EDA tools. This type of workforce development initiative matters strategically because tool adoption is tightly coupled with designer familiarity, training pipelines, and the long-term diffusion of design practices across the engineering labor pool.
The report situates these developments within a wider competitive analysis that evaluates product roadmaps, enterprise sales motions, open-source influence, subscription economics, and the strategic implications of AI-enabled features. By comparing how vendors address complexity, accessibility, verification discipline, and workflow integration, the study provides a framework for assessing which competitive approaches are likely to resonate with different buyer profiles over the forecast period.
Electrical Design Software Market
Regulatory, Cost, and Deployment Dynamics Shaping Adoption
Market growth does not occur in a regulatory or operational vacuum. Several overlapping dynamics are redefining how PCB design software is evaluated, deployed, and governed. In the medical device domain, recent regulatory guidance in the United States has reinforced mandatory risk-based design controls, traceability, and documentation expectations for design processes, with alignment to updated quality management system requirements effective in early 2026. For PCB design workflows, these requirements raise the stakes on design traceability, version control, and the ability to demonstrate disciplined development pathways. Tools that support structured documentation, audit readiness, and design traceability are therefore gaining strategic importance in regulated verticals, not simply as productivity enhancers but as compliance enablers.
On the cybersecurity front, the European Union has advanced a resilience framework that requires manufacturers of digital products, including certain software offerings, to design, update, and maintain systems with cybersecurity compliance in mind. Beginning later in 2026, reporting obligations for actively exploited vulnerabilities will add a new layer of responsibility for software suppliers and enterprise users alike. These obligations influence procurement decisions by making security posture, update cadence, vulnerability management, and support commitments more relevant in vendor evaluation. For engineering organizations, this dynamic introduces a broader set of due-diligence considerations when selecting software platforms, particularly where designs interface with connected products or where corporate IP protection policies intersect with external toolchains.
Deployment preferences also remain shaped by sector-specific security and IP concerns. On-premises deployment models continue to hold strong appeal in aerospace, defense, and automotive contexts, where strict data security and intellectual property protection often outweigh the convenience of cloud-centric arrangements. This persistence of localized deployment affects licensing structures, integration strategies, IT support requirements, and the broader commercial calculus for vendors targeting high-assurance sectors. The report examines how these deployment tendencies influence vendor positioning and buyer decision-making, particularly where regulated or security-sensitive environments create long sales cycles and higher negotiation stakes.
Cost structures add another layer of strategic complexity. Enterprise-grade subscriptions can represent a material annual investment per design seat, and advanced workflows frequently require corresponding investments in workstation hardware and specialized engineering talent. These factors raise the total cost of ownership for smaller organizations and can inhibit the adoption of premium suites, even when feature requirements might otherwise justify them. As a result, procurement strategies increasingly weigh not only license pricing, but also training burdens, hardware dependencies, upgrade frequency, and the operational risk of toolchain fragmentation. The report addresses these economic pressures through a lens that connects pricing models, deployment choices, and engineering capacity constraints to practical adoption outcomes.
How to Use This Research for 2026 Decision-Making
The strategic value of the full study lies in its ability to convert market momentum into concrete planning inputs. For senior decision-makers, the report offers a structured way to evaluate tool procurement, vendor selection, workflow redesign, and workforce readiness against a realistic view of where the market is heading. It helps organizations anticipate which capabilities will become more central as design complexity rises, where integration and verification features will command premium attention, and how regulatory and security requirements will reshape evaluation criteria.
For vendors and channel partners, the analysis provides context on competitive positioning, buyer sensitivity, and the threads of differentiation that matter most across enterprise, mainstream, and accessible-tier segments. By connecting recent product releases, workforce development activity, and regulatory change to broader market dynamics, the study supports scenario planning around tool adoption, feature investment, and go-to-market strategy.
The complete report contains the detailed segment breakdowns, regional distributions, application-level market contributions, concentration analysis, and vendor-level intelligence needed for precise planning. Those granular data points are deliberately held within the full study so that decision-makers can access calibrated, context-rich intelligence without diluting the analytical framework. The overview presented here is intended to demonstrate the depth and operational relevance of the research while guiding readers toward the full report for the quantitative and strategic detail required for final investment and procurement decisions.
Conclusion: Positioning for a High-Growth, High-Complexity Decade
The PCB design software market is expanding at a pace that rewards early clarity in tool strategy, workflow integration, and compliance readiness. With sustained double-digit growth projected through the end of the decade, organizations that treat design software as a strategic infrastructure choice rather than a routine procurement item will be better positioned to manage complexity, reduce rework, and accelerate product development. The PW Consulting study translates this market opportunity into a structured intelligence base for evaluating categories, verticals, regions, vendors, and the regulatory and economic forces that shape adoption. By connecting high-level market momentum with the practical realities of engineering workflows and procurement behavior, the report equips leaders with the perspective needed to make informed decisions in a rapidly evolving landscape.
For detailed analysis of this topic, please visit the official page: PCB Design Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com