

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HIFU Market Hits $215M in 2025, Forecasts 7.25% CAGR to $344.8M by 2032

Strategic Imperatives in the High-Intensity Focused Ultrasound System Market: A 2026 Outlook
The High-intensity Focused Ultrasound (HIFU) System Market stands at a critical inflection point as the global healthcare landscape shifts toward non-invasive, precision-based therapeutic modalities. With a total market valuation reaching 215.0 USD Million in the base year and projected to ascend toward 344.8 USD Million by the close of the forecast window, the sector is demonstrating robust structural momentum. Our latest comprehensive market study distills this trajectory into actionable intelligence, enabling executives to navigate the complex interplay of regulatory evolution, clinical adoption, and technological differentiation that will define competitive positioning through 2032.
For strategic decision-makers operating in medtech, hospital procurement, or venture-backed healthcare innovation, this report functions as a navigation blueprint. It maps the current revenue topology, isolates the primary growth vectors, and evaluates how market participants are aligning product portfolios with emerging reimbursement signals. The analysis is structured to deliver clarity without noise, emphasizing operational readiness over superficial trend-chasing. As we enter 2026, the convergence of clinical evidence maturation, payer documentation standardization, and platform-specific regulatory clearances demands a more granular understanding of where capital, R&D, and commercial resources should be deployed.
Macro Trajectory and Growth Architecture
The historical record from 2020 through 2025 reveals a consistent upward climb, with revenue scaling from 163.15 USD Million to 215.0 USD Million. This expansion was not merely a function of incremental adoption; it reflects a structural reorientation in how health systems evaluate procedural risk, recovery timelines, and long-term patient throughput. Forecasts extending through 2032 indicate a compound annual growth rate of 7.25 percent, signaling sustained demand expansion rather than a temporary surge. The forward curve suggests that early movers who secure clinical workflow integration, streamline installation and service models, and align with payer documentation requirements will capture disproportionate share during the mid-forecast period.
Growth is being propelled by several intersecting forces. Clinicians and hospital administrators are increasingly prioritizing therapies that reduce inpatient burden, minimize collateral tissue damage, and offer repeatable treatment protocols without ionizing radiation. Simultaneously, device manufacturers are compressing form factors, enhancing imaging-fusion capabilities, and building robotic assistance layers that standardize targeting accuracy. These technological refinements are lowering the barrier to entry for new clinical sites while expanding the addressable patient population across both therapeutic and aesthetic indications. The result is a market that is widening in scope even as it deepens in technical complexity.
Report Content and Operational Utility
Our analysis is engineered to translate market signals into execution-ready insights. Rather than offering abstract commentary, the report delivers a structured dossier of operational components that senior leadership can immediately integrate into commercial planning, investment committee memos, and product roadmap reviews. The study covers the following core modules:
- Comprehensive revenue mapping across historical baselines and forward-looking forecast intervals, with explicit identification of inflection years where adoption velocity is expected to accelerate.
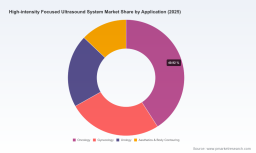
- End-to-end segmentation analysis that dissects market structure by clinical and commercial categories, highlighting how therapeutic platforms, aesthetic applications, and compact system architectures are carving distinct growth lanes.
- Regional deployment patterns and purchasing ecosystem characteristics, enabling localization strategies for distribution partnerships, clinical training programs, and service infrastructure planning.
- Technology and workflow evaluation frameworks that assess imaging integration, targeting precision, treatment duration, and operator dependency across competing platform types.
- Reimbursement and policy tracking modules that consolidate CPT coding references, national health system coverage decisions, and payer medical policy updates into a single decision-support environment.
- Competitive benchmarking and strategic positioning maps that evaluate product differentiation, clearance trajectories, clinical collaboration networks, and geographic footprint strength.
Each module is designed to reduce ambiguity in capital allocation and market-entry timing. For organizations evaluating expansion into new indications, the report isolates the clinical evidence thresholds and procedural familiarity curves that typically govern adoption speed. For established players refining go-to-market execution, the analysis surfaces workflow bottlenecks, service-model gaps, and training requirements that often determine realized utilization rates. The synthesis of clinical, regulatory, and commercial layers ensures that leadership can evaluate opportunities through a unified lens rather than fragmented siloed data.
Competitive Landscape and Strategic Positioning
The HIFU ecosystem is characterized by a concentrated yet dynamically evolving competitive field. Market concentration metrics indicate that a small cohort of established players commands a dominant share of total revenue, reflecting the high technical thresholds, regulatory navigation requirements, and clinical validation cycles that typically accompany focused ultrasound platform commercialization. Within this structure, differentiation is increasingly driven by indication-specific pipeline depth, imaging and workflow integration, and the ability to secure timely reimbursement alignment.
Several organizations exemplify the strategic pathways shaping the market. EDAP TMS SA has advanced its Focal One robotic HIFU system for prostate cancer focal therapy, reinforcing its position through recent imaging and workflow enhancements that received FDA 510(k) clearance, alongside France’s national universal health system reimbursement decision for the Focal One procedure. This dual momentum illustrates how product refinement and reimbursement alignment can compound commercial traction in a core urologic application. Theraclion continues to extend its footprint with the Echopulse and SONOVEIN robotic HIFU platforms, targeting non-invasive treatment pathways for thyroid nodules, breast fibroadenomas, and varicose veins, thereby broadening the indication map beyond traditional tumor ablation into benign and vascular applications.
Insightec maintains a distinctive position through its Exablate and Exablate Neuro systems, leveraging MR-guided focused ultrasound for essential tremor, Parkinson’s disease, and pain palliation. The neurological and functional applications associated with this platform highlight a growing premium segment where procedural precision and image-guided targeting command higher clinical scrutiny and specialized adoption pathways. Profound Medical Corp. contributes to the therapeutic landscape with the Sonalleve MR-HIFU platform, supporting prostate cancer ablation and osteoid osteoma treatment, while also expanding into related oncologic applications that benefit from precise thermal ablation capabilities.
Chongqing Haifu Medical Technology Co., Ltd. represents an important distribution and manufacturing axis, with JC and JC200 HIFU systems supporting non-invasive tumor ablation across liver, breast, and bone applications as well as benign conditions, backed by global distribution reach. This international footprint underscores how regional manufacturing strength and export-oriented commercial networks can influence global supply dynamics and pricing architecture. Sonablate Corp. continues to develop the Sonablate 450 HIFU system for prostate cancer treatment, supported by ongoing clinical collaborations and product distribution, reinforcing the sustained focus on urologic ablation as a foundational market pillar. Meanwhile, FUSMobile, Inc. has carved a specialized niche with the Neurolyser XR fluoroscopy-guided HIFU system for chronic low back pain treatment, recently obtaining De Novo clearance that opens a distinct pain-management pathway and demonstrates how targeted nerve-destruction applications can diversify the overall demand base.
Regulatory and Reimbursement Dynamics as Strategic Catalysts
Market expansion in focused ultrasound is increasingly contingent on the alignment between clinical evidence, procedural coding clarity, and payer acceptance. Recent developments show that reimbursement infrastructure is moving from fragmented, institution-specific decision-making toward more standardized documentation expectations. Anthem Medical Policy CG-MED-81, updated in early 2026, lists applicable CPT codes for HIFU ablation procedures, reinforcing coding visibility for commercial payers and creating a more predictable billing environment for providers. This type of policy clarity reduces administrative friction and supports broader site-level adoption, particularly for centers that depend on consistent outpatient reimbursement pathways.
At the same time, reimbursement strategy has become an active commercial priority rather than a passive compliance function. Industry participants are investing in education and documentation guidance to help clinical sites navigate coding requirements and submission accuracy. This is reflected in recent webinar initiatives focused on the evolving reimbursement landscape and the documentation needed for accurate billing, signaling that market maturity now includes payer-facing readiness as a core capability. The existence of CPT code 55880 for transrectal high-intensity focused ultrasound prostate ablation, which has supported Medicare outpatient reimbursement since 2021, further illustrates how coding stability can anchor long-term utilization patterns in a key therapeutic segment.
Regulatory milestones are also reshaping competitive timing. Recent FDA clearances for imaging and workflow enhancements, as well as De Novo clearance for nerve-targeted chronic low back pain treatment, demonstrate that the regulatory pathway is enabling both incremental platform refinement and new indication entry. In parallel, broader ecosystem developments such as the establishment of an international focused ultrasound society are helping to standardize clinical practice, convene evidence generation, and accelerate adoption through shared professional infrastructure. These dynamics suggest that the organizations most likely to compound advantage in 2026 and beyond will be those that synchronize product development with reimbursement documentation, clinical education, and professional society engagement.
High Intensity Focused Ultrasound (HIFU) Market
Implications for 2026 Decision-Making
For executives planning 2026 strategic moves, the market presents a clear mandate: prioritize positioning that aligns product capability with reimbursement readiness, clinical workflow compatibility, and indication-specific evidence maturity. The compound growth trajectory implies that demand will continue to broaden, but the pace of capture will differ substantially across segments depending on how quickly sites can integrate the technology into existing procedural pathways. Organizations that treat reimbursement and coding clarity as a core commercial pillar, rather than a downstream administrative concern, will gain faster utilization ramp and more predictable revenue conversion.
The report provides the structural context required to make these choices with confidence. It maps where concentration is highest, where emerging applications are gaining traction, and how recent regulatory and reimbursement actions are reshaping site-level purchasing behavior. By situating these insights within a forward-looking framework, the study enables leadership to identify which therapeutic platforms, aesthetic devices, and compact system architectures warrant deeper investment, partnership development, or geographic prioritization. It also supports scenario planning around clinical education, service expansion, and workflow integration, ensuring that strategic intent is matched by operational readiness.
High-intensity Focused Ultrasound System Market
Ultimately, the High-intensity Focused Ultrasound System Market is evolving from a niche therapeutic category into a broader precision-treatment ecosystem. The organizations that will define the next phase of competitive advantage are those that can read the convergence of technology, regulation, and clinical adoption with precision and act on it quickly. This research is designed to give leadership that clarity, equipping decision-makers with the context needed to convert market momentum into durable strategic positioning through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: High-intensity Focused Ultrasound System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com