

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rupture Disc Market Hits $678.2M in 2025, Projects $874.6M by 2032

Strategic Imperatives in the Rupture Disc Market: Navigating Growth and Compliance Through 2032
The global industrial landscape is undergoing a profound transformation, driven by tightening safety regulations, evolving material science, and an unwavering focus on operational integrity. Within this complex ecosystem, pressure relief systems remain a cornerstone of process safety management, with the rupture disc standing as a critical, non-reclosing device designed to protect equipment from exceeding allowable pressure limits. As organizations look toward the 2026 fiscal year and beyond, the ability to anticipate market shifts, understand competitive maneuvers, and align procurement strategies with regulatory trends is no longer optional—it is a strategic imperative. This analysis draws from the latest comprehensive market study on the Rupture Disc Market, offering a high-level view of the trajectory defined by data spanning from 2020 through the forecast horizon of 2032.
Market Trajectory and Macroeconomic Signals
The rupture disc market has demonstrated resilience and steady expansion over the past half-decade, reflecting the broader industrial demand for reliable pressure management solutions. Historical data from 2020 to 2025 reveals a trajectory of measured growth, with the global market valued at approximately 597.5 million USD in 2020. Despite minor fluctuations in the early years, the market strengthened through 2023 and 2024, reaching a valuation of 646.06 million USD before continuing its upward trajectory to an estimated 678.2 million USD in the 2025 base year. This historical consolidation sets the stage for an accelerating growth phase, with projections indicating a compound annual growth rate (CAGR) of 3.7 percent over the forecast period from 2026 to 2032.
By 2026, the market is anticipated to surpass the 722 million USD threshold, with growth compounding annually to reach a projected valuation of 874.6 million USD by 2032. This sustained expansion is underpinned by continuous investments in industrial infrastructure, heightened awareness regarding pressure vessel safety, and the indispensable role of rupture discs in preventing catastrophic failures across high-risk environments. For strategic planners and procurement leaders, these macro-level figures are not merely statistics; they are indicators of market maturity and opportunity. Understanding the pace and volume of this growth allows enterprises to calibrate their capacity planning, investment timelines, and risk mitigation frameworks with precision, ensuring they remain competitive in a sector that values reliability and compliance above all else.
Segmentation Dynamics: Materials and Applications Driving Demand
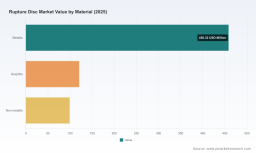
A deeper examination of the market structure reveals distinct preferences and performance drivers across material classifications and end-use applications, shaping the strategic landscape for manufacturers and buyers alike. The market is fundamentally bifurcated by material composition, where metallic rupture discs command a dominant share of the revenue landscape, reflecting their widespread adoption in high-pressure and high-temperature industrial environments where structural integrity and burst precision are paramount. Graphite and non-metallic variants, while representing smaller portions of the total market value, hold significant strategic importance in specialized applications involving highly corrosive media or extreme thermal conditions where metallic alternatives may be compromised. The demand for graphite solutions, in particular, underscores a growing industry need for materials that offer temperature-independent properties and resistance to chemical degradation, aligning with the operational realities of modern processing facilities.
In parallel, the application spectrum illustrates the diverse utility of rupture discs across critical industrial verticals. The oil and gas sector remains a substantial contributor to market revenue, driven by the relentless demand for overpressure protection in exploration, refining, and pipeline infrastructure. The chemical processing industry follows as another major pillar, leveraging rupture discs to maintain safety standards in reactors, storage vessels, and distillation columns where hazardous substances are handled. Meanwhile, the pharmaceutical and biotechnology segments are experiencing notable strategic relevance, fueled by stringent hygiene requirements and the adoption of sanitary designs that ensure cleanability, sterilization compatibility, and traceability. Other application areas further diversify the market, encompassing food and beverage processing, extrusion operations, and general industrial processes that require reliable pressure relief without compromising product purity or process efficiency. For decision-makers, recognizing which verticals are driving volume and which materials are gaining traction in specific process conditions is essential for tailoring product portfolios and supply chain strategies.
Regulatory Pressures and Technical Standards as Growth Catalysts
The rupture disc market is inextricably linked to an evolving regulatory environment, where compliance is not a static checkbox but a dynamic requirement that shapes product development, procurement criteria, and operational validation. Leading manufacturers are increasingly aligning their product portfolios with rigorous international standards, ensuring that their devices meet the exacting demands of modern processing facilities. Sanitary rupture discs, for instance, are being engineered to comply with ASME BPE, USP Class VI, and 3A standards, addressing the critical needs for traceability, cleanability, and sterilization in pharmaceutical and biotech environments. These compliance frameworks are not merely administrative; they directly influence the selection of disc types, the validation of installation procedures, and the long-term maintenance protocols that facilities must adhere to in order to pass regulatory audits and maintain operational licenses.
Rupture Disc Market
In the food, beverage, and pharmaceutical sectors, the emphasis on hygiene and process safety has accelerated the adoption of hygienic rupture discs that are compatible with Clean-in-Place and Sterilize-in-Place procedures, while also offering vacuum resistance necessary for sterilization conditions. Similarly, graphite-based solutions are being validated for FDA conformance in applications involving corrosive media, with material properties that remain stable across temperature variations. Beyond end-product certifications, the industry is witnessing a push toward rigorous raw material traceability and in-house lot qualification testing that exceeds standard ASME and ISO code requirements for cycle life and burst tolerance. This heightened focus on material provenance and performance verification creates a competitive differentiator for manufacturers who can demonstrate superior quality control, while simultaneously raising the bar for buyers who must ensure that their pressure relief assemblies meet both operational and regulatory benchmarks. For strategic organizations, staying ahead of these regulatory currents requires continuous engagement with industry standards, proactive collaboration with equipment suppliers, and a comprehensive understanding of how compliance mandates will evolve through the forecast period.
Competitive Landscape and Strategic Positioning
The rupture disc market is characterized by a moderately concentrated competitive environment, where a handful of established players command a significant portion of the market share, while specialized manufacturers and regional contenders compete on innovation, niche applications, and geographic reach. The collective presence of key industry participants underscores the importance of brand reputation, technical expertise, and product breadth in securing long-term customer relationships. Strategic analysis of the competitive field reveals that market leaders are increasingly differentiating themselves through targeted product expansions, enhanced catalog offerings, and the development of assembly-level solutions that simplify installation and improve overall process safety.
Several core enterprises exemplify the strategic directions shaping the market. Continental Disc Corporation, based in Liberty, Missouri, has consistently reinforced its market position by expanding its portfolio of high-performance reverse-acting and tension rupture discs, with a particular emphasis on sanitary offerings compliant with ASME BPE, USP Class VI, 3A, and ISO standards. The company's recent initiatives, including the expansion of its APX rupture disc line to accommodate larger sizes for demanding industrial applications, the launch of the HPX-CTG cartridge rupture disc assembly to streamline installation and enhance process safety, and the introduction of the APX family for high-performance overpressure protection, illustrate a clear strategic focus on delivering scalable, robust solutions that address evolving customer requirements. Fike Corporation, headquartered in Blue Springs, Missouri, has carved out a strong niche in hygienic rupture disc technology, offering designs such as the AXIUS SC, SHX, and RD540 SC, as well as extruder rupture disc devices that are compatible with CIP/SIP protocols for food, beverage, and pharmaceutical applications, while supporting both reverse-acting and forward-acting configurations to meet diverse process needs.
ZOOK Enterprises LLC, operating from Chagrin Falls, Ohio, has established itself as a global manufacturer providing metal and graphite rupture disks across reverse-acting, forward-acting, sanitary, and ultra-low or bi-directional configurations, serving a broad spectrum of industries including chemical, pharmaceutical, extrusion, and food processing. BS&B Safety Systems, based in Tulsa, Oklahoma, continues to deliver comprehensive rupture disk devices and pressure relief solutions that span industrial and process safety applications, reinforcing its role as a provider of integrated safety systems. Technetics Group, located in Los Angeles, California, brings a focus on high-precision rupture discs and engineered components that contribute to advanced pressure relief systems. Completing the competitive mosaic is FDC Co., Ltd., based in South Korea, which contributes to the global supply landscape with rupture disc products including the KSRRL series designed for industrial pressure relief applications. The presence of such diverse players highlights the importance of evaluating not just product specifications, but also the strategic alignment of each supplier with regional requirements, material capabilities, and compliance documentation.
Market concentration metrics further illuminate the competitive structure, with the top three companies collectively accounting for approximately 49.5 percent of the market, and the top five players consolidating an even larger share at roughly 65.2 percent. This concentration pattern suggests that while the market remains accessible to specialized and emerging entrants, scale, credibility, and established distribution channels play a decisive role in capturing significant market volume. For buyers and investors, understanding this concentration dynamic is critical for assessing supply chain resilience, negotiating leverage, and the potential for competitive disruption. Strategic procurement decisions must therefore weigh the advantages of working with established market leaders who offer broad portfolios and global support against the opportunities presented by specialized manufacturers who may provide tailored solutions or competitive pricing in specific segments.
Forecast Outlook and Strategic Implications for 2026 and Beyond
Looking ahead to the 2026 forecast period and the subsequent years through 2032, the rupture disc market is positioned for sustained growth, but the pathways to value capture will require nuanced strategic planning. The projected trajectory indicates that while the overall market will expand steadily, the relative performance of different materials, applications, and regions will diverge based on localized industrial activity, regulatory enforcement intensity, and the pace of technological adoption. Enterprises that proactively map their operations against these evolving dynamics will be better equipped to allocate capital, optimize inventory, and forge partnerships that enhance both safety performance and cost efficiency.
Strategically, the emphasis for 2026 should center on several key imperatives. First, organizations must deepen their understanding of material selection criteria, recognizing that the choice between metallic, graphite, and non-metallic rupture discs is not merely a technical specification but a long-term decision that affects maintenance cycles, compliance records, and operational reliability in specific media environments. Second, the growing importance of sanitary and hygienic designs across pharmaceutical, biotechnology, and food processing sectors demands that buyers and suppliers align on validation protocols, cleanability standards, and sterilization compatibility to avoid costly retrofit or compliance gaps. Third, the competitive landscape calls for a balanced sourcing strategy that acknowledges the strength of concentrated market leaders while remaining open to specialized suppliers who can deliver differentiated value in narrow but critical application niches. Fourth, the trend toward integrated assembly solutions and simplified installation methodologies points to a broader industry shift toward lifecycle value over piece-price procurement, encouraging decision-makers to evaluate total cost of ownership, installation complexity, and long-term safety performance.
Furthermore, the forecast horizon presents opportunities for organizations that can anticipate regional demand shifts and adjust their supply chains accordingly. While the analysis of regional segmentation remains a detailed component of the full market study, the overarching principle is clear: growth will not be uniform, and strategic agility will be rewarded. Companies that invest in market intelligence, maintain robust vendor evaluation frameworks, and stay attuned to regulatory developments will be positioned to navigate the complexities of the forecast period with confidence. The data projected through 2032 serves as both a benchmark and a compass, guiding stakeholders toward decisions that align with long-term industry trajectories rather than short-term fluctuations.
Conclusion: Accessing Comprehensive Intelligence for Strategic Advantage
The rupture disc market stands at the intersection of safety, compliance, and industrial growth, offering a landscape where informed decision-making can yield significant competitive and operational advantages. The macro-level data, segmentation insights, regulatory trends, and competitive dynamics outlined here represent only the introductory layer of a much deeper analytical framework. For organizations seeking to translate these high-level signals into actionable strategies for 2026 and the forecast period through 2032, a granular understanding of specific market sizes, regional contributions, application breakdowns, material performance metrics, and detailed competitor profiles is essential. Such intelligence enables precise budgeting, targeted market entry, optimized product development, and risk-aware procurement strategies that align with both immediate operational needs and long-term growth objectives.
The full market research study provides a comprehensive examination of these dimensions, offering the depth and granularity required to move beyond general trends and into the specifics that drive real-world strategic outcomes. By exploring the complete dataset, stakeholders can uncover hidden opportunities, identify potential supply chain vulnerabilities, and benchmark their positioning against the broader industry landscape. The insights contained within the full report are designed to empower executives, procurement leaders, product managers, and investors with the clarity needed to make confident, data-backed decisions in a market where precision and reliability are paramount. We invite you to access the complete study to gain the full spectrum of intelligence necessary to navigate the rupture disc market with strategic foresight and operational excellence.
Abrasive Disc Market
For detailed analysis of this topic, please visit the official page: Rupture Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com