

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Microbial ID Market Hits $327.2M in 2025, Set to Reach $600.3M by 2032

Navigating the Next Wave: Strategic Intelligence for the Microbial Identification Market Beyond 2026
The global landscape for microbial identification is undergoing a structural transformation. What was once a niche laboratory function has evolved into a critical infrastructure component for clinical diagnostics, pharmaceutical quality control, and food safety assurance. As the industry approaches the mid-2026 inflection point, the complexity of regulatory expectations, the acceleration of analytical speed, and the commercialization of rapid identification workflows are converging to reshape competitive dynamics. This article distills the strategic essence of our latest Microbial Identification Market research, designed to equip executives, procurement leaders, and product strategy teams with the contextual intelligence required to navigate the 2026-2032 horizon with confidence.
Understanding where the market is heading is no longer a luxury reserved for R&D teams. It is a boardroom imperative. The decisions being made today regarding instrumentation adoption, database licensing, service-level agreements, and regional expansion will determine whether organizations capture the compounding value of a rapidly maturing ecosystem or fall behind fragmented, slower-moving competitors. Our new analysis provides a rigorous, forward-looking framework to support those decisions, combining historical trajectory modeling, technology adoption curves, and competitive intelligence into a single actionable reference.
Market Trajectory: From Modest Growth to Sustained Expansion
The decade preceding 2026 has established a clear upward baseline for microbial identification. Revenue across the global market progressed from a foundational level in 2020 and climbed steadily through the middle of the decade, reflecting broader adoption of rapid phenotypic and genotypic identification platforms across integrated laboratory networks. By 2025, the industry reached an estimated valuation that underscored the shift from early-adopter experimentation to routine operational deployment.
Looking forward, the projection for 2026 places the market at a new threshold, with sustained momentum carrying the total addressable size through the end of the forecast window. The compound annual growth rate over the 2026-2032 period is projected at 9.07 percent, a pace that signals durable demand rather than a temporary peak. Growth will be driven by multiple reinforcing forces: the increasing integration of microbial identification into antimicrobial stewardship programs, the standardization of quality control workflows in pharmaceutical manufacturing, and the expanding expectations for traceability in food and environmental testing.
Notably, the trajectory does not follow a simple linear path. The forecast reflects periods of consolidation, technology-driven step changes, and regional adoption variation that will reward organizations capable of timing their investments to match the rhythm of clinical and industrial procurement cycles. Executives who rely on single-point estimates or static snapshots risk misallocating capital. A structured, multi-scenario view of how the market scales through 2032 is essential for capacity planning, partnership strategy, and M&A screening.
Segmentation Dynamics: Where Value Is Concentrated and Where It Is Emerging
The structure of the microbial identification market is defined by meaningful concentration in specific technology classes, application domains, and geographies. While the overall market expands, value is not distributed evenly across all categories. The research maps how distinct platforms and use cases capture disproportionate share, shaped by regulatory clearance timing, laboratory workflow compatibility, and the breadth of organism coverage each solution can support.
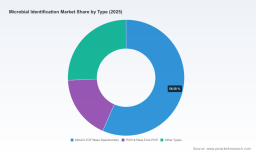
Technology leadership continues to be anchored by high-throughput analytical approaches that deliver rapid turnaround with minimal sample preparation. Within the broader portfolio of methods, certain categories command a larger share of the revenue pool, while complementary approaches serve specialized laboratories or regional procurement preferences. The segmentation analysis in our research dissects these balances without oversimplifying them, helping teams understand not only which categories lead today but which are gaining relative momentum as database content, automation, and software integration evolve.
Application-driven demand reveals an equally layered picture. Clinical diagnostics remains the most prominent use case, reflecting the centrality of organism identification in patient care pathways and antimicrobial susceptibility testing. Pharmaceutical manufacturing quality control represents a substantial and growing share, driven by rigorous contaminant control requirements and batch-level traceability mandates. Food safety and environmental monitoring contribute additional, structurally distinct demand streams, each with its own throughput expectations, validation requirements, and service models.
A critical strategic insight from the segmentation work is that the relative weight of each application and technology category is not static. As automated workflows mature and software layers become more deeply integrated into laboratory information systems, the practical meaning of segmentation shifts. A platform that appears dominant in one year can see its relative position adjusted by database expansion, regulatory milestones, or interoperability improvements. Our analysis tracks these dynamics in a way that lets organizations anticipate shifts rather than react to them after reallocation has already occurred.
Microbial Identification Market
Geographic deployment patterns further shape where investments will pay off most efficiently. Certain regions exhibit larger baseline demand and more mature procurement environments, while others present faster relative growth trajectories as laboratory infrastructure modernizes. The research provides regional nuance at a level of granularity that supports multi-market entry planning, distribution partnership evaluation, and localization of service offerings, while preserving the confidentiality of the exact split figures that our clients obtain in full.
Competitive Differentiation: Bruker Corporation and bioMérieux as Strategic Anchors
The competitive environment for microbial identification is concentrated, yet it is far from static. A handful of established players shape the direction of technology standards, regulatory expectations, and customer operating norms. Among them, Bruker Corporation and bioMérieux stand out as companies whose product strategies and recent milestones illustrate how leadership is being contested and defended in the current cycle.
Bruker Corporation, headquartered in Billerica, Massachusetts, has focused its identification strategy on the MALDI Biotyper CA System, leveraging FDA-cleared MALDI-TOF mass spectrometry for rapid identification of gram-positive and gram-negative bacteria, anaerobes, and yeasts from cultured isolates. The platform’s value proposition extends beyond raw identification speed; it includes MBT Compass HT CA software, which is designed to streamline laboratory workflows and reduce manual handling steps. This emphasis on workflow efficiency reflects a broader industry trend in which instrumentation must prove not only analytical performance but also operational fit within highly constrained laboratory schedules.
In October 2025, Bruker received FDA clearance for Claims 7 and 8 of the MALDI Biotyper CA System, expanding the cleared reference library to 549 species and introducing MBT FAST Shuttle US IVD and MBT Compass HT CA software. From a strategic standpoint, this clearance matters because it broadens the population of organisms that laboratories can confidently identify within a cleared workflow, potentially increasing the system’s relevance across both clinical and industrial settings. Database breadth and software integration are increasingly important differentiators, and this milestone illustrates how platform maturity can be extended without changing the underlying hardware category.
bioMérieux, based in Marcy-l’Étoile, France, pursues a similarly focused but distinct approach. Its VITEK MS PRIME and VITEK COMPACT PRO systems combine FDA 510(k)-cleared MALDI-TOF with automated identification and antimicrobial susceptibility testing workflows, targeting both clinical and industrial microbial identification. A distinguishing feature of bioMérieux’s offering is the expanded database capability for mycobacteria, molds, and resistant pathogens, which directly addresses laboratories’ need to manage organisms that are historically slower or more difficult to identify with confidence.
In March 2025, bioMérieux secured FDA 510(k) clearance and launched the VITEK COMPACT PRO ID/AST system for rapid microorganism identification and antibiotic susceptibility testing in clinical and industrial laboratories. This development reinforces the company’s positioning at the intersection of identification and downstream testing, an integration that matters to laboratories seeking to compress turnaround times while preserving interpretive context. For organizations comparing platform options, these types of integrated workflows can influence total cost of ownership, space utilization, and staffing requirements.
Both companies demonstrate that the competitive battleground is increasingly defined by cleared use cases, database coverage, software-driven efficiency, and the ability to serve multiple end-use environments without compromising validation or reproducibility. For executives evaluating vendor relationships, understanding these differential strengths is more valuable than comparing instrument lists in isolation. Our research analyzes each player’s strategic posture, recent development history, and likely direction of travel, providing the context needed to interpret vendor claims against market realities.
Regulation, Standards, and the Shaping of Market Access
Regulatory and standards frameworks are not merely compliance issues; they are market-shaping forces. In microbial identification, the interaction between clearance pathways, certification requirements, and reimbursement mechanisms influences which solutions gain commercial traction, how quickly they scale, and which laboratories are willing or able to adopt them.
One of the most consequential dynamics for the United States market is the relationship between FDA 510(k) clearance and reimbursement through CPT codes. When a microbial identification test aligns with clearance expectations and coding structures, the path from laboratory adoption to sustainable financial operation can become materially smoother. This linkage is especially important for clinical laboratories that must justify capital expenditure and recurring consumables within tightened operating budgets.
Beyond clearance, quality system expectations such as ISO 13485 certification remain central to medical-grade systems. Laboratories and procurement teams increasingly view certification as a baseline indicator of process discipline and reliability, particularly where identification results feed directly into regulated workflows. In pharmaceutical manufacturing and clinical environments, the credibility of a platform often depends as much on its quality infrastructure as on its analytical output.
Regulatory developments also intersect with broader institutional priorities such as antimicrobial stewardship. Clearance milestones for ID/AST-capable systems support laboratory use cases that help stewardship programs act on identification and susceptibility information more quickly. This alignment between technology and institutional mission can be a significant adoption driver, because it gives laboratory leadership a narrative that extends beyond instrument performance to organizational impact. These dynamics are explored in detail in the report’s market dynamics section, where regulatory events are linked to adoption consequences and commercial timing.
What the Research Delivers: Operational Intelligence for Decision-Makers
This market research is structured to function as a working strategic asset, not a static summary. It is designed for teams that need to translate market knowledge into procurement timing, product planning, regional prioritization, and competitive positioning. The report’s operational value rests on several interrelated components.
First, the report provides a full historical and forecast view of market size and growth, including the underlying trajectory that connects the 2020 baseline through the 2025 reference year and out to 2032. This multi-year structure supports capacity planning, demand forecasting, and revenue modeling with a consistent analytical basis.
Second, the segmentation analysis breaks down technology types, application areas, and regional deployment patterns in a way that allows clients to assess where opportunity is concentrated and where differentiation is most achievable. The segmentation framework is built to reveal relative positioning and growth intensity, helping teams determine whether to compete in crowded categories or pursue higher-margin, faster-growing niches.
Third, the competitive landscape assessment profiles major participants and maps their strategic moves, recent clearances, product updates, and market focus. This section is intended to support vendor evaluation, partnership screening, and competitive threat analysis. Where relevant, it also highlights how product-level developments interact with broader market trends such as database expansion, workflow automation, and cleared-use-case expansion.
Fourth, the report examines market dynamics, including regulatory drivers, reimbursement linkages, quality standards, and stewardship-related adoption pressures. By connecting policy and standards to commercial behavior, the analysis helps teams anticipate demand shifts that may not be visible in headline market size alone.
Finally, the research incorporates strategic interpretation layers that translate data into decision readiness. Rather than leaving the reader with isolated figures, it provides the reasoning needed to evaluate entry timing, regional prioritization, technology mix, and competitive exposure. The full study preserves a level of detail that enables direct application to internal models, while the present article intentionally focuses on the strategic framework and the nature of the intelligence available.
Why This Research Matters for 2026 Decisions
The 2026 decision window is particularly important because it sits at the intersection of several compounding forces. Market growth is robust enough to reward early positioning, yet fast enough that delays can result in missed share and higher acquisition costs. Technological progress is material, with cleared databases and software-driven workflows expanding the practical value of established platforms. Regulatory and reimbursement dynamics are entering a more influential phase, increasing the importance of clearance status, certification, and coding alignment in adoption decisions.
In that environment, organizations need more than a forecast number. They need a defensible view of how growth is distributed, where competitive intensity is rising, how regulation will shape access, and which vendor strategies indicate durable advantage versus short-cycle positioning. The research is built to provide that view. It supports capital allocation, vendor selection, market entry sequencing, and product roadmap planning by grounding them in a consistent, evidence-based market structure.
Executives who act on this intelligence early can shape their strategies around the market’s actual contours rather than its visible headline. That includes deciding where to compete on workflow integration, where to invest in database and coverage breadth, where to emphasize service and validation support, and where to avoid overcommitting to categories that are likely to face margin pressure or substitution risk. The report is designed to make those choices more deliberate and less reactive.
Microbial Air Samplers Market
Conclusion: Strategic Clarity for a Market in Motion
The microbial identification market is entering a phase in which analytical performance, workflow efficiency, regulatory alignment, and commercial execution will separate durable players from marginal ones. The growth trajectory through 2032, the 9.07 percent CAGR, and the multi-category concentration of demand all point to an environment rich with opportunity but demanding in execution. Organizations that understand the structure of that environment will be better placed to allocate resources, choose partners, and time their moves.
This article has outlined the strategic logic behind the new market research and described the types of insight it provides for 2026 decision-making. To obtain the complete segmentation data, forecast detail, competitive profiles, and dynamic analysis needed for internal planning, we invite you to access the full report and its supporting materials. The remainder of the market’s specific composition, regional balances, and precise category values are presented in full within the study, where they can be used directly for modeling, benchmarking, and strategic planning.
For detailed analysis of this topic, please visit the official page: Microbial Identification Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com