

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LIDAR Market Hits $299M in 2025, Projects 20.32% CAGR to $1,088M by 2032

The LiDAR Inflection Point: Strategic Intelligence for 2026 Enterprise Decisions
The Light Detection and Ranging (LIDAR) market is no longer a speculative technology narrative reserved for R&D laboratories and venture capital pitch decks. As we move through 2026, the sector has matured into a structural infrastructure backbone for autonomous mobility, spatial intelligence, and next-generation industrial sensing. For enterprise decision-makers, the question is no longer whether to engage with LIDAR ecosystems, but how to architect supply-chain exposure, partnership strategies, and product roadmaps in a landscape defined by rapid technological convergence and shifting regulatory guardrails.
Light Detection and Ranging (LIDAR) Market
This analysis serves as a strategic precursor to our latest comprehensive market study, Light Detection and Ranging (LIDAR) Market: Global Forecast & Strategic Assessment, 2026–2032 . Below, we outline the macro forces shaping the period ahead, the operational intelligence embedded in our full report, and the competitive dynamics that will determine which organizations capture value versus those that merely observe it.
The Macro Trajectory: From Niche Sensing to Systemic Enabler
Historical performance provides the first layer of strategic confidence. Between 2020 and 2025, global LIDAR revenue expanded from approximately 162.3 million USD to 299.0 million USD, reflecting sustained triple-digit growth across discrete product cycles. That growth is not decelerating; rather, it is compounding. Our baseline projection places 2026 revenue at 364.7 million USD, scaling progressively to 1,088.2 million USD by 2032. This expansion is underpinned by a forecasted compound annual growth rate of 20.32 percent throughout the 2026–2032 forecast window, a trajectory that signals durable demand rather than a short-term procurement spike.
The composition of that demand tells a more nuanced story. Mechanical architectures continue to command meaningful revenue share, particularly in applications where proven reliability and established supply chains outweigh incremental form-factor advantages. At the same time, solid-state solutions are accelerating their penetration, driven by design requirements in automotive ADAS, compact robotics, and fixed infrastructure deployments. The application landscape mirrors this dual-track evolution. Automotive and advanced driver-assistance systems remain the dominant pull factor, while smart infrastructure and mapping initiatives, aerospace and defense modernization programs, and environmental and forestry monitoring verticals each contribute distinct demand rhythms that rarely align with a single procurement calendar.
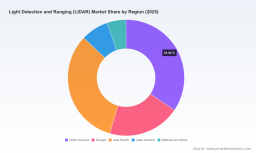
Geographic distribution of revenue further illustrates the market's global character. North America, Asia Pacific, and Europe each represent substantial demand centers, with Latin America and the Middle East & Africa emerging as incremental but strategically relevant contributors. Importantly, these figures reflect integrated, end-to-end valuations rather than isolated component sales, meaning that downstream system integrators, software perception layers, and service-enabled deployment models are already being captured within the broader revenue envelope.
The 2026–2032 Forecast Lens: Why Precision Matters Now
Aggregate growth trajectories are necessary but insufficient for capital allocation and product strategy. What separates high-performing organizations in this cycle is access to granular, scenario-tested intelligence. Our full market report dissects historical baselines from 2020 through 2025 and projects forward through 2032 with methodology designed for operational decision-making rather than retrospective commentary.
Executives will find in the complete study a breakdown of type-based revenue evolution, application-specific demand momentum, and regional performance differentials that allow for portfolio stress-testing under multiple adoption curves. The report also maps concentration dynamics within the market: the top three players collectively account for roughly 35 percent of total revenue, while the top five expand that footprint to approximately 52 percent. These concentration levels are not static ceiling effects; they reflect active consolidation patterns, partnership leverage, and the capital intensity of scaling manufacturing while maintaining performance thresholds.
For supply-chain leaders, the forecast period is particularly instructive because hardware bottlenecks are not uniform across the stack. Component constraints tied to semiconductors, optical lenses, and high-precision MEMS chips have emerged as primary friction points limiting rapid production scale-up. Understanding where these constraints will persist, and which architecture types are most exposed, enables procurement teams to sequence commitments rather than react to shortages in real time. This is precisely the kind of forward visibility embedded in the full report's segment-level analysis, where type, application, and regional overlays are presented together to surface cross-dependencies that isolated dashboards routinely miss.
Wind Lidar Market
Competitive Architecture: The Players Defining the Next Cycle
The competitive field in 2026 is defined by differentiated specializations rather than undifferentiated scale. Hesai Technology, headquartered in Shanghai, continues to push solid-state automotive LiDAR sensors into high-volume production while expanding its 3D perception portfolio for autonomous mobility and robotics. Its recent manufacturing expansion into a Thailand facility, expected to come online later in 2026, signals a deliberate strategy to supply non-Chinese companies and hedge against geographic supply-chain concentration. Product-wise, Hesai has introduced the ET25 ultra-thin sensor at a 25 mm thickness for behind-windshield mounting, alongside the PandarXT 32-channel mid-range LiDAR featuring zero minimum range and self-developed ASICs. These moves illustrate a clear focus on integrating sensor form-factor constraints with proprietary silicon strategy.
Luminar Technologies, based in Orlando, Florida, remains anchored in long-range pulsed LiDAR sensors and perception systems purpose-built for Level 3+ autonomous vehicles and ADAS. Its positioning is less about volume ubiquity and more about performance thresholds where range, velocity resolution, and robustness in high-speed environments define competitive advantage. Innoviz Technologies, operating from Rosh Ha'ayin, Israel, pursues a complementary automotive-grade route, delivering high-resolution 3D perception platforms tailored for consumer vehicles and commercial applications where certification rigor and cost-performance balance are paramount.
Ouster, Inc., headquartered in San Francisco, emphasizes digital LiDAR sensors optimized for scalability across autonomous vehicles, robotics, and smart infrastructure. Its architectural philosophy centers on manufacturability and software-defined flexibility, which resonates in deployment models that require fleet-wide uniformity and lifecycle upgradability. LeddarTech, in Québec, pairs solid-state LiDAR sensors with the LeddarVision software suite, effectively offering a perception stack alongside hardware, an increasingly relevant value proposition as system integrators seek integrated ADAS and autonomous driving perception solutions rather than discrete sensor components.
MicroVision, Inc., based in Redmond, Washington, continues to advance MEMS-based LiDAR 2.0 sensors and perception solutions targeting industrial, defense, and autonomous applications. Its April 2026 launch of a Global Partner and Reseller Program reflects a deliberate acceleration strategy aimed at scaling adoption across real-world industrial and defense use cases through broader channel reach. Cepton Technologies, in San Jose, rounds out the competitive field with lidar-based solutions spanning automotive ADAS, smart cities, and industrial automation, reinforcing the multi-vertical deployment logic that characterizes mature LIDAR ecosystems.
The strategic implication for buyers and investors is clear: competitive advantage is fragmenting across architecture types, perception software maturity, manufacturing geography, and channel strategy. No single company's narrative dominates every segment, and the winners will be those whose capabilities align with specific demand profiles rather than those who chase all segments simultaneously without the infrastructure to support them.
Regulatory and Standardization Currents Reshaping Playbooks
Technology roadmaps cannot be separated from the policy environment in which they operate. In December 2025, the SAFE LiDAR Act was introduced in the 119th Congress with the intent to restrict the use of foreign adversary LiDAR within the United States. Regardless of final legislative language, the directional signal is unambiguous: procurement teams and product planners must evaluate sourcing strategies against evolving national-security criteria, particularly where end systems interface with critical infrastructure or federally regulated mobility programs.
At the same time, regulatory nuance continues to matter. A January 2025 Federal Register notice reaffirmed that LiDAR hardware is excluded from supply-chain review under the Connected Vehicles framework. This clarification creates a meaningful distinction between sensor hardware and broader vehicle connectivity obligations, but it also demands careful compliance interpretation as program boundaries evolve. Organizations that assume blanket applicability, or conversely that ignore the distinction entirely, risk misaligned sourcing or delayed program approvals.
Standardization efforts are equally consequential. Hesai co-leads the Automotive LiDAR Working Group at the International Standards Organization, where the focus is developing test methods for LiDAR performance and safety. The emergence of standardized evaluation protocols will influence benchmarking, procurement specifications, and cross-vendor comparability, gradually shifting the market from proprietary performance claims toward reproducible metrics. For engineering and quality teams, early alignment with these developing standards reduces retrofit risk in later validation cycles.
Data infrastructure developments are also reshaping downstream demand. The latest Lidar Base Specification, LBS 2025 rev. A, was released by the U.S. Geological Survey in June 2025 for the 3D Elevation Program, and in January 2026 the USGS announced FY25 3DEP data collaboration projects, including newly acquired QL 1 lidar for Palm Beach County to support a new 3DHP pilot project. These initiatives illustrate how government data programs are institutionalizing lidar as a foundational component of national spatial data infrastructure, which in turn expands procurement pathways for mapping and infrastructure monitoring providers.
Why the Full Report Is a Decision Asset, Not a Reference Document
Given the convergence of architectural differentiation, regulation, standards, and supply constraints, strategic teams need intelligence that can be operationalized rather than simply reviewed. Our complete report is structured to support that end. It provides a full historical and forecast timeline, type and application segment analysis, regional performance context, concentration metrics, and a detailed competitive landscape that includes company profiles, recent developments, and the strategic implications of those moves.
Beyond descriptive coverage, the report is built around decision utility. Procurement leaders can use the segmentation and bottleneck analysis to sequence sourcing commitments and evaluate supplier exposure. Product planners can map application momentum against architectural readiness to prioritize development investments. Strategy and corporate development teams can evaluate partnership, acquisition, and geographic expansion options against concentration dynamics and standardization trajectories. The integration of recent developments, such as Hesai's Thailand manufacturing expansion and new sensor introductions, MicroVision's partner program launch, and government data collaboration and standardization activities, ensures that the analysis reflects the market as it is being shaped in real time, not as it appeared in prior cycles.
To access the complete segmentation detail, full forecast tables, competitive profiles, and the integrated strategic recommendations that accompany them, please visit the source page at PW Consulting for the full Light Detection and Ranging (LIDAR) Market report. The macro trajectory outlined here is intended to demonstrate the analytical rigor and decision relevance of the study; the actionable architecture, segment-level intelligence, and scenario-tested guidance are delivered in full only within the complete report.
For detailed analysis of this topic, please visit the official page: Light Detection and Ranging (LIDAR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com