

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Feed Yeast Market Hits $150M in 2025, Eyes 5.1% CAGR to 2032

Navigating Volatility and Value: A 2026 Strategic Outlook on the Global Feed Yeast Market
The global animal nutrition sector stands at a critical inflection point in 2026. As livestock producers face margin compression from fluctuating raw material costs and evolving regulatory landscapes, the demand for functional feed additives has never been more scrutinized. Feed yeast, once considered a niche supplement, has cemented its status as a cornerstone ingredient for gut health, nutrient absorption, and overall animal performance. For stakeholders operating within this ecosystem, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for sustainable growth and risk mitigation.
PW Consulting's latest comprehensive study on the Feed Yeast Market is designed to equip decision-makers with the granular intelligence required to navigate this complex environment. This article serves as a strategic preview of our findings, highlighting the macro-economic shifts, competitive dynamics, and operational realities that will define the sector from 2026 through 2032. By examining the underlying forces driving revenue progression and market concentration, we aim to demonstrate the tangible value this research brings to corporate strategy, investment planning, and supply chain optimization.
Macro-Economic Trajectory and Growth Validation
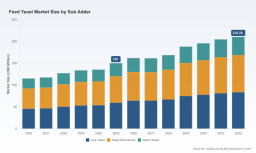
The foundational premise of any strategic investment lies in the validity of the market's growth trajectory. Our analysis tracks the market's evolution from a baseline of 115.0 million USD in 2020, reflecting a steady maturation phase. The progression to 150.0 million USD in 2025 underscores a resilient demand structure that has withstood recent global supply chain disruptions. Looking forward, the forecast period spanning 2026 to 2032 projects a continuation of this upward trend, with revenue figures anticipated to reach 210.28 million USD by 2032.
These figures represent more than simple volume expansion; they signal a structural shift in how animal nutrition is formulated. The projected Compound Annual Growth Rate (CAGR) of 5.1% during the forecast period indicates a market that is growing at a pace superior to general agricultural commodities, driven by specific value-added applications rather than bulk commodity mixing. For CFOs and strategy heads, this growth rate validates the capital expenditure required to expand production capabilities or secure long-term supply agreements. However, recognizing the top-line number is only the first step. The real strategic weight lies in understanding the velocity of growth across different product forms and animal categories, which our full report dissects in detail.
The historical data from 2020 to 2025 also reveals patterns of recovery and acceleration that are crucial for modeling future scenarios. The jump from 135.25 million USD in 2024 to 150.0 million USD in 2025 suggests a post-pandemic stabilization and a renewed focus on livestock productivity. As we move into 2026, with the market estimated at 161.77 million USD, the momentum suggests that feed yeast is transitioning from a reactive solution to a proactive standard in animal husbandry. This trajectory provides a reliable baseline for internal forecasting, reducing the uncertainty that often plagues nutritional budgeting.
Segmentation Dynamics and Application Value
While the aggregate market size tells a story of growth, the segmentation data reveals where the actual value is generated. The market is broadly categorized by product form, animal type, and geographic reach. In terms of product forms, the split between Live Yeast, Yeast Derivatives, and Spent Yeast indicates diverse utilization pathways. Yeast Derivatives currently hold a significant share, reflecting the industry's preference for stable, concentrated forms of nutrients and beta-glucans that offer consistent performance without the viability risks associated with live cultures. Live Yeast, however, remains a critical segment for probiotic applications, particularly where rumen health and microbial balance are prioritized.
In terms of animal applications, the demand is heavily weighted towards Poultry, which continues to be the dominant driver of feed yeast consumption. This aligns with the global intensification of poultry production where growth rates and feed conversion ratios are paramount. Ruminants represent a substantial secondary segment, driven by the specific need for yeast cultures that stabilize fermentation in the rumen, thereby improving milk yield and feed efficiency in cattle. Swine and Aquaculture segments, while smaller in relative revenue share, are experiencing distinct growth vectors. The aquaculture sector, in particular, is gaining traction as alternative protein sources require optimized gut health solutions to ensure survival rates and growth in intensive farming environments.
Geographically, the market exhibits a mature landscape in North America and Europe, where high regulatory standards and established livestock industries sustain stable demand. Asia Pacific presents a high-growth frontier, fueled by expanding meat consumption and modernization of farming practices in key economies. Latin America and the Mideast and Africa regions, while currently smaller in relative revenue contribution, offer potential for expansion as local production capacities increase. Our report provides a deep dive into these regional nuances, analyzing local production capabilities versus import dependency, which is critical for pricing strategy and supply chain resilience.
Competitive Intensity and Consolidation Trends
The feed yeast market is characterized by a moderately high concentration of key players, with the top three companies accounting for approximately 65% of the market revenue and the top five holding around 82%. This concentration suggests that scale, technological capability, and brand trust are significant barriers to entry. The competitive landscape includes a mix of global nutrition giants and specialized yeast producers who have leveraged their fermentation expertise to capture niche leadership positions.
Key industry participants such as Angel Yeast Co., Ltd., Alltech Inc., Lallemand Inc., and Lesaffre Group dominate the conversation through diverse strategies. Angel Yeast, based in China, leverages massive production capacity exceeding 100,000 tonnes annually to compete on scale and supply reliability, often showcasing their full range of solutions at major industry events like SPACE 2025. In contrast, companies like Alltech focus on specialized science, promoting proprietary yeast cultures like Yea-Sacc for specific rumen health benefits, maintaining authorization under strict EFSA regulations.
Feed Yeast Market
European and North American players like Leiber GmbH, Chr. Hansen A/S, and DSM-Firmenich AG bring strong heritage in fermentation and ingredient quality. Leiber's recent acquisition by Asahi Group Foods in March 2025 highlights a trend towards vertical integration and the convergence of food and feed ingredient capabilities. Meanwhile, entities like ADM Animal Nutrition and Nutreco integrate yeast solutions into broader animal nutrition portfolios, offering customers a one-stop shop for dietary requirements. The presence of companies like Novus International and AB Agri further diversifies the competitive field, ensuring that innovation remains a priority.
For new entrants or expanding players, this landscape implies that competition is not solely on price but on demonstrated efficacy, regulatory compliance, and supply chain security. Understanding the specific strengths and strategic moves of these key companies is essential for identifying partnership opportunities or anticipating market shifts. Our full report profiles each of these key players, analyzing their production capacities, recent developments, and strategic positioning to help you benchmark your organization against the market leaders.
Operational Challenges and Regulatory Headwinds
Strategic planning in 2026 must account for a dynamic regulatory and cost environment. The core ingredient, Saccharomyces cerevisiae, is subject to price volatility driven by fermentation feedstock costs. With average annual prices hovering between 800 and 1,200 USD per metric ton as of 2025, cost management becomes a critical component of margin protection. Producers with integrated fermentation infrastructure hold a distinct advantage in buffering these input costs, while downstream formulators must navigate availability risks.
Yeast Market
Regulatory frameworks are also evolving in ways that directly impact trade and product formulation. Recent trade policy shifts, such as the U.S. Executive Order of February 20, 2026, have introduced specific tariff considerations on inactive yeasts, excluding dried brewers' yeast under certain HTSUS classifications. This distinction creates a complex compliance landscape for importers and exporters, requiring precise classification to avoid unexpected cost burdens. Simultaneously, the authorization status of key products under European regulations, such as the ongoing renewals for specific yeast cultures, adds a layer of regulatory risk that must be monitored continuously.
Furthermore, the infrastructure requirements for production are non-trivial. Large-scale fermentation facilities capable of exceeding 100,000 tonnes per year are necessary to achieve the economies of scale required to compete in the global market. This barrier reinforces the dominance of established players and suggests that capacity expansions are significant strategic events. China's role as a leading production hub, with output exceeding 200,000 tonnes annually primarily for export, underscores the geopolitical and logistical dimensions of the supply chain. For businesses reliant on global sourcing, understanding these infrastructure constraints and export flows is vital for mitigating supply disruption risks.
Strategic Imperatives for 2026 and Beyond
As we look toward the forecast period ending in 2032, the strategic implications for stakeholders are clear. First, product differentiation will remain the primary lever for premium pricing. Companies that can validate the functional benefits of specific yeast strains or derivatives through robust trial data will command greater loyalty and resilience against price-based competition. Second, supply chain diversification is no longer optional. With significant production concentrated in specific regions and tariffs fluctuating, building a multi-sourced supply network is essential for continuity.
Third, regulatory intelligence must be embedded into product development cycles. The evolving landscape of tariffs, authorizations, and safety standards requires a proactive approach to compliance rather than a reactive one. Finally, the trend toward consolidation suggests that strategic partnerships or acquisitions could accelerate market access and technology acquisition. Whether through integrating acquisitions like those seen in the brewers' yeast sector or forming alliances to expand distribution networks, inorganic growth strategies will play a role alongside organic development.
Unlocking the Full Intelligence Picture
The insights presented here represent the surface of a much deeper analytical reservoir. The data points mentioned, the company profiles summarized, and the dynamics outlined are derived from a rigorous methodology that combines historical data validation, primary industry interviews, and quantitative modeling. To truly leverage this information for decision-making, a granular understanding of the segmentation splits, the detailed competitive benchmarking, and the region-specific risk assessments is required.
PW Consulting's full Feed Yeast Market Report provides this complete intelligence package. It offers the detailed revenue breakdowns by sub-category, the specific growth rates for each animal segment, and the comprehensive analysis of regulatory impacts on trade flows. It details the capacity expansions, the specific product launches, and the strategic alliances that are shaping the competitive field beyond the headlines. For executives aiming to capitalize on the projected growth to 210.28 million USD by 2032, or for investors assessing the viability of market entry, the depth of data available in the full study is the key differentiator between informed strategy and speculation.
We invite you to access the complete report to secure the detailed intelligence necessary to navigate the feed yeast market with confidence. In an industry where margins are managed through precision and foresight, having the full picture is the ultimate competitive advantage. Let our analysis be the foundation upon which your 2026 strategy is built, ensuring you are positioned not just to survive the market dynamics, but to thrive within them.
For detailed analysis of this topic, please visit the official page: Feed Yeast Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com