

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Report: Wearable Inertial Sensors Market Hits $1.45B in 2025, Projected to Reach $3.41B by 2032
By pmarketresearch, 2026-09-16
Global Wearable Inertial Sensors Market: Strategic Intelligence for 2026 and Beyond
The wearable technology landscape has transcended novelty to become a foundational layer of modern digital interaction, health monitoring, and industrial efficiency. At the heart of this transformation lies the inertial sensor ecosystem, a critical component enabling motion tracking, gesture recognition, and spatial orientation across millions of devices worldwide. Our latest comprehensive analysis, the Worldwide Wearable Inertial Sensors Market study, provides an exhaustive examination of this rapidly evolving sector. As we move through 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for stakeholders ranging from semiconductor manufacturers to healthcare providers and consumer electronics giants.
This report serves as a definitive guide for decision-makers navigating the complexities of inertial sensing technology. By integrating historical performance data with forward-looking projections, we offer a roadmap that illuminates growth vectors, competitive pressures, and regulatory shifts. The following insights distill the core findings of our research, highlighting why this intelligence is essential for crafting resilient strategies in the coming years.
Market Trajectory and Growth Dynamics
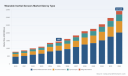
The global market for wearable inertial sensors has demonstrated remarkable resilience and expansion over the past half-decade. Historical analysis from 2020 through 2025 reveals a consistent upward trend, driven by the proliferation of smart wearables, advancements in sensor miniaturization, and increasing adoption in professional healthcare settings. In 2020, the market generated revenue of approximately 785.4 million USD. By the base year of 2025, this figure has escalated to 1,450.0 million USD, reflecting a compound annual growth rate that underscores the sector's vitality.
Looking forward, the forecast period spanning 2026 to 2032 indicates sustained momentum. Projections suggest that revenue will climb to 1,612.63 million USD in 2026, continuing its ascent to reach 3,413.25 million USD by 2032. This trajectory corresponds to a forecast CAGR of 13.01 percent, signaling that demand will outpace many traditional electronics segments. Such growth is underpinned by the convergence of consumer lifestyle changes and industrial digitallization. The expansion is not uniform; rather, it is fueled by specific technological breakthroughs and shifting application priorities that our report dissect in granular detail.
For enterprise strategists, these macro figures provide a baseline for capacity planning and investment allocation. However, the true value lies in understanding the drivers behind these numbers. The transition from basic step counting to complex motion analysis, coupled with the integration of artificial intelligence at the edge, is reshaping value chains. Our analysis delves into how these factors interact to create both opportunities and vulnerabilities for market participants.
Technology Segmentation and Hardware Foundations
The market is structurally divided by sensor type, with Inertial Measurement Units (IMUs) commanding the largest share of revenue. IMUs represent the cornerstone of modern wearable functionality, combining accelerometers, gyroscopes, and magnetometers to deliver comprehensive motion data. While standalone accelerometers and gyroscopes maintain significant presence, particularly in cost-sensitive consumer applications, the trend is overwhelmingly toward integrated solutions. Magnetometers, though smaller in revenue contribution, play a crucial role in orientation and compass-based applications, completing the sensor fusion ecosystem.
A critical theme emerging in our analysis is the dominance of MEMS-based inertial sensors supplied by major component manufacturers. Companies such as Bosch Sensortec, STMicroelectronics, and TDK InvenSense form the core hardware backbone for most wearable IMUs. Their collective focus on low power consumption and compact form factors has been instrumental in enabling the next generation of hearables, fitness trackers, and medical patches. The shift toward embedding AI processing directly within these sensors, exemplified by recent product launches like the LSM6DSV320X, marks a pivotal shift. This allows for on-device activity tracking and high-g impact measurements without relying heavily on cloud connectivity, enhancing privacy and responsiveness.
Precision remains a key differentiator, particularly for high-accuracy applications. Analog Devices, Inc. continues to develop precision inertial measurement units suitable for demanding wearable motion tracking scenarios. Meanwhile, specialized players like 2M Engineering supply wireless high-fidelity IMU motion sensing platforms tailored for researchers and OEM integration. Understanding the technological hierarchy and the specific strengths of these hardware providers is essential for supply chain optimization and product development roadmaps.
Application Verticals and Value Creation
Revenue distribution across application segments highlights the diverse utility of inertial sensors. Consumer electronics remains the largest application vertical, driven by the ubiquitous presence of smartphones, smartwatches, and fitness bands. The demand here is characterized by volume and the need for cost-effective, reliable motion sensing that supports gesture control, screen orientation, and activity monitoring.
Healthcare and medical applications represent a rapidly growing segment, valued significantly within the market structure. The integration of inertial sensors into clinical gait analysis, rehabilitation monitoring, and remote patient monitoring systems is transforming care delivery. Companies like Movella Inc. (Xsens) specialize in wearable inertial sensor systems for motion capture and biomechanics research, while Shimmer Sensing offers Verisense IMU sensors with prior CE Class I medical device certification for clinical research. These tools enable real-world movement analysis that was previously confined to laboratory settings.
Additional growth is evident in AR and VR systems, where precise head and hand tracking is essential for immersive experiences, as well as in sports and fitness training, where performance metrics drive user engagement. The ability to capture nuanced biomechanical data allows for personalized training regimens and injury prevention strategies. Our report explores how these verticals are evolving and where the highest margin opportunities exist for solution providers.
Worldwide Wearable Inertial Sensors Market
Competitive Landscape and Strategic Positioning
The market exhibits a moderate level of concentration, with the top three companies accounting for over 58 percent of the market share and the top five firms holding approximately 74 percent. This concentration indicates that while there is room for niche players, scale and technological leadership provide significant advantages. Key competitors include Bosch Sensortec GmbH, headquartered in Germany, which offers low-power smart IMUs such as the BMI270 and BMI570 optimized for wearables and gesture recognition. STMicroelectronics, based in Switzerland and France, supplies MEMS inertial sensors with embedded AI processing capabilities. TDK InvenSense, operating out of the United States, provides high-performance MEMS IMUs widely integrated into wearables and smartphones.
The competitive dynamics are further shaped by specialized firms focusing on medical and research-grade applications. Noraxon USA Inc. provides wearable inertial sensors and EMG-integrated systems for biomechanical and clinical gait analysis. BTS Bioengineering develops the G-WALK wearable inertial sensor for functional motion analysis worn around the waist. ActiGraph LLC focuses on physical activity monitoring and clinical research applications. Additionally, 221e develops miniaturized medical-grade wireless wearable IMU sensors with embedded AI for neurorehabilitation. These companies illustrate the bifurcation between mass-market component suppliers and specialized solution providers targeting high-value niches.
Recent developments underscore the pace of innovation. In May 2025, STMicroelectronics launched the LSM6DSV320X inertial measurement unit with embedded AI processing for activity tracking and high-g impact measurements. More recently, in April 2026, Wearable Devices Ltd. received a USPTO Notice of Allowance for a continuation patent covering biometric user authentication using gesture and biopotential sensors in touchless wearable interface devices. Such milestones signal the increasing sophistication of the intellectual property landscape and the convergence of security, biometrics, and motion sensing.
Regulatory Environment and Standardization
Navigating the regulatory landscape is a critical component of market strategy, particularly for entities operating in the healthcare sphere. The FDA maintains a public database of authorized sensor-based digital health technology medical devices, including non-invasive wearables such as smartwatches and patches that incorporate inertial sensors. In January 2026, the FDA issued guidance limiting regulation of low-risk non-medical grade wearable fitness devices promoting general wellness, while maintaining oversight for devices making medical claims. This distinction creates a clear pathway for consumer wellness products while imposing stricter requirements on those seeking diagnostic or therapeutic validation.
In Europe, wearable medical devices incorporating sensors are subject to the EU Medical Device Regulation (MDR) 2017/745 risk classification, alongside IEC 60601 for electrical safety, ISO 14971 for risk management, and ISO 13485 for quality management systems. Compliance with these frameworks is non-negotiable for market access in the region. Standardization efforts also play a role, as evidenced by Shimmer Research's Verisense IMU sensor receiving CE certification as a Class I medical device. These regulatory milestones not only validate specific products but also set benchmarks for the industry, influencing design choices and certification strategies for new entrants.
Strategic Imperatives for 2026 Decision-Making
As organizations formulate their strategies for the remainder of the decade, several key imperatives emerge from our analysis. First, supply chain resilience must be prioritized. Given the concentration of key component suppliers, diversification and strategic partnerships are essential to mitigate risk. Second, the integration of edge AI into sensor hardware represents a significant value-add opportunity. Products that can process motion data locally offer advantages in latency, privacy, and battery life, aligning with consumer and industrial expectations.
Third, the regulatory environment demands proactive compliance strategies. Companies aiming to capture the healthcare segment must invest early in the certification processes required by FDA and EU MDR frameworks. Conversely, those focusing on the wellness segment should leverage the favorable guidance for low-risk devices to accelerate time-to-market. Finally, geographic expansion strategies should consider the varying maturity levels of regional markets. While North America and Asia Pacific represent significant revenue bases, emerging regions offer untapped potential for targeted interventions.
The Worldwide Wearable Inertial Sensors Market report provides the detailed segmentation data, regional breakdowns, and competitor profiles necessary to execute these strategies with precision. By accessing the full intelligence contained within this study, stakeholders can move beyond high-level trends to actionable insights that drive competitive advantage.
Worldwide Automotive Inertial Systems Market
Conclusion
The wearable inertial sensors market stands at a pivotal juncture, characterized by robust growth, technological innovation, and evolving regulatory standards. The projected expansion from 1,450.0 million USD in 2025 to over 3,413.25 million USD by 2032 reflects the deepening integration of motion sensing into everyday life and professional applications. For leaders in this space, the ability to interpret these dynamics accurately is the difference between leading the market and reacting to it.
Our comprehensive study offers the depth and clarity required to navigate this complex environment. We invite you to explore the full report to access the complete dataset, including detailed segmentation splits by type, application, and region, as well as in-depth profiles of all key market players. Equip your organization with the intelligence needed to capitalize on the opportunities defining the future of wearable inertial sensing.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Inertial Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Ultrasonic Probe Covers Market Hits $229.7M in 2025, Growing at 6.5% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the Global Ultrasonic Probe Covers Market in 2026
The global healthcare landscape is undergoing a rapid transformation, driven by an aging population, increased prevalence of chronic diseases, and a heightened focus on patient safety and infection control. Within this complex ecosystem, the ultrasonic probe covers market stands as a critical niche, bridging the gap between diagnostic precision and clinical safety. As we move into 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for stakeholders ranging from medical device manufacturers to hospital procurement officers.
PW Consulting's latest Worldwide Ultrasonic Probe Covers Market study offers a comprehensive lens into this vital sector. This research is designed to equip decision-makers with the foresight needed to navigate upcoming challenges and capitalize on emerging opportunities. By analyzing historical performance and projecting future trends through 2032, this report serves as an essential roadmap for strategic planning in a regulated and competitive environment.
Macroeconomic Trajectory and Market Growth
The fundamental story of the ultrasonic probe covers market is one of steady, resilient expansion. Our analysis tracks revenue performance from the base year of 2025 back through 2020, providing a robust historical context before forecasting growth patterns into the next decade. The data indicates a consistent upward trajectory, reflecting the indispensable nature of these devices in modern medical imaging.
In 2020, the global market generated approximately 168.45 million USD. This figure experienced a notable acceleration over the following years, reaching 195.57 million USD in 2022 and surpassing 211.69 million USD in 2023. The momentum continued into the mid-2020s, with the market size reaching 229.01 million USD in 2024 and stabilizing at 229.72 million USD in 2025. Looking forward, the forecast period from 2026 to 2032 suggests sustained growth, with projected revenues climbing to 254.36 million USD in 2026. By the end of the forecast window in 2032, the market is anticipated to reach 356.99 million USD.
This expansion corresponds to a Compound Annual Growth Rate (CAGR) of 6.5 percent over the forecast period. For corporate strategists, this rate signals a healthy market environment that outpaces inflation and offers viable returns on investment. However, the path is not linear. Slight fluctuations are observable, such as the marginal adjustment between 2026 and 2027, which underscores the need for agile planning and sensitivity to external economic shocks. The overall value pool expanding from roughly 229 million USD to over 356 million USD represents a significant opportunity for value capture over the next seven years.
Product Segmentation and Material Innovation
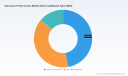
Understanding where value is generated within the market requires a deep dive into product segmentation. The market is primarily categorized by material type, reflecting the evolving priorities of clinicians and patients regarding safety and performance. The shift away from traditional materials toward advanced synthetics is a defining trend of this era.
Latex-free polyurethane has emerged as a dominant category, representing the largest share of market revenue. This preference is driven by the increasing awareness of latex allergies and the demand for higher biocompatibility. Medical-grade polyethylene also constitutes a significant portion of the landscape, offering clarity and durability. Traditional latex products maintain a presence but face headwinds from regulatory pressures and patient safety advocacy. Polyethylene covers serve as a cost-effective alternative in specific applications where extreme flexibility is less critical.
The material choice is not merely a preference but often a clinical requirement. As noted in industry guidelines, latex-free probe covers utilize medical-grade polyethylene or polyurethane films to ensure biocompatibility and optical clarity. This alignment between material science and clinical need creates a sticky demand curve that favors suppliers with robust R&D capabilities. Manufacturers who can innovate in material thickness, tactile sensitivity, and tear resistance will find themselves well-positioned to capture premium segments of the market.
Clinical Applications and Demand Drivers
The demand for ultrasonic probe covers is inextricably linked to the utilization rates of ultrasound procedures across various medical specialties. Our analysis breaks down consumption by application, revealing where the highest volume and value reside.
Obstetrics and Gynecology remains the cornerstone application for this market. The high frequency of transvaginal and transabdominal scans in prenatal care and reproductive health drives substantial volume. Given the invasive nature of many OB/GYN procedures, the requirement for sterile barriers is non-negotiable, ensuring a stable baseline demand. Radiology represents another major pillar, encompassing a broad range of diagnostic imaging scenarios where probe covers protect both the patient and the expensive transducer equipment.
Cardiology is also a significant contributor, particularly with the use of transesophageal echocardiography (TEE) probes which require specialized sheaths. Urology and Surgery and Vascular applications round out the key segments, each with specific requirements for sheath length, diameter, and lubrication. The diversity of applications suggests that no single clinical discipline dictates the entire market rhythm; rather, it is a composite of multiple healthcare workflows. CDC guidelines recommend disposable probe covers for all endocavitary ultrasound to reduce healthcare-associated infections, reinforcing the clinical mandate behind the market demand.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established players and specialized manufacturers. Concentration metrics indicate a moderately consolidated environment. The top three companies hold a combined market share of 42.15 percent, while the top five entities control 58.6 percent. This concentration suggests that while there is room for niche players, scale and distribution networks provide a distinct advantage for the market leaders.
Several key companies define the current competitive arena. CIVCO Medical Solutions, based in Coralville, IA, USA, is a prominent provider of both sterile and non-sterile disposable ultrasound probe covers. Their portfolio includes endocavity sheaths and general imaging covers compatible with major ultrasound systems. Recently, CIVCO exhibited an expanded probe cover portfolio at RSNA 2024, highlighting sterile endocavity sheaths, signaling their commitment to product expansion and visibility in key trade forums.
Parker Laboratories, located in Fairfield, NJ, USA, manufactures the Incognito probe covers and sheaths for ultrasound transducers. Their strategy emphasizes gel-free and low-profile designs aimed at enhancing infection control and user convenience. Kentec Medical, based in Bicester, Oxfordshire, UK, produces sterile single-use probe sheaths for endocavity ultrasound probes. Their focus on compliance with EU MDR and worldwide availability highlights the importance of regulatory alignment in global markets.
Sunray Medical, headquartered in Edison, NJ, USA, offers a range of ultrasound probe covers including clear-view and endovaginal types, all FDA cleared for medical use. This regulatory clearance is a critical barrier to entry and a trust signal for purchasers. ImaX Medical, based in Montreal, QC, Canada, supplies disposable probe covers for ultrasound and TEE probes, focusing on high-clarity materials for imaging. This focus on optical properties addresses the diagnostic quality concerns that sometimes arise with barrier use.
Strategic interactions among these players often occur through trade shows and product launches rather than aggressive price wars. The recent activity by CIVCO at RSNA 2024 exemplifies how companies use major industry events to showcase expanded portfolios. For new entrants or existing players looking to gain share, the competitive strategy likely hinges on regulatory compliance, material innovation, and supply chain reliability rather than volume discounting alone.
Regulatory and Reimbursement Dynamics
The operational environment for ultrasonic probe covers is heavily influenced by regulatory frameworks and reimbursement structures. These invisible forces shape product design, pricing strategies, and market access.
In terms of regulation, ultrasound probe covers are classified as Class I exempt or Class II devices requiring 510(k) clearance if sterile. This classification dictates the pathway to market. Sterile probe covers must meet ISO 11607 for packaging and ISO 11135/11137 for ethylene oxide or radiation sterilization. Compliance with these standards is not optional; it is a prerequisite for hospital procurement. The complexity of maintaining sterilization compliance across different geographic regions adds a layer of operational cost and risk that must be factored into strategic planning.
Medical Ultrasound Probe Market
Reimbursement presents a different set of challenges. There is no dedicated HCPCS code for probe covers. Instead, costs are bundled into ultrasound CPT codes such as 76817 for transvaginal procedures. This bundling means that the economic value of the probe cover is often indirect, tied to the reimbursement of the procedure itself. For providers, this can influence purchasing decisions, prioritizing cost-effective solutions that do not jeopardize procedural reimbursement rates. For manufacturers, it means that demonstrating value in terms of infection reduction or equipment protection is crucial, as the direct cost is absorbed into a broader billing code.
Worldwide Ultrasonic Probe Covers Market
Strategic Implications for 2026 Decision Makers
As we look toward 2026, the intersection of market growth, regulatory rigor, and competitive dynamics creates a specific set of strategic imperatives. The projected 6.5 percent CAGR suggests that growth is achievable, but capturing it requires precision.
First, supply chain resilience is paramount. With market concentration indicating that top players hold significant sway, smaller distributors or manufacturers must ensure they have differentiated value propositions. This could come in the form of specialized materials, faster turnaround times, or superior regulatory support. Second, infection control remains a primary driver. With CDC recommendations reinforcing the use of disposable covers for endocavitary ultrasound, the clinical argument for these products is strong. Marketing and sales efforts should align with these safety guidelines to reinforce necessity.
Third, regional nuances matter. While global aggregate data shows growth, the distribution of revenue across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa varies significantly in terms of regulatory maturity and procurement practices. North America and Europe represent large, established markets with strict compliance requirements. Asia Pacific offers volume potential with evolving standards. Understanding these regional textures is essential for market entry or expansion strategies.
Finally, the bundling of costs into CPT codes necessitates a sharp focus on total cost of ownership. Hospitals are likely to evaluate probe covers not just on unit price but on their contribution to workflow efficiency and infection prevention. Suppliers who can articulate this broader value proposition will find greater success in tenders and contract negotiations.
Conclusion: The Value of Comprehensive Intelligence
The Worldwide Ultrasonic Probe Covers Market is at an inflection point where clinical necessity, regulatory complexity, and economic opportunity converge. The data points to a market growing from approximately 229 million USD in 2025 to nearly 357 million USD by 2032. Yet, these top-line numbers only tell part of the story. The real strategic value lies in understanding the segmentation dynamics, the competitive maneuvers of key players like CIVCO and Parker Laboratories, and the regulatory hurdles that define market access.
PW Consulting's full market study delves deeper into these areas, providing granular data on regional splits, material type breakdowns, and application-specific revenue streams that are not fully disclosed in this overview. For executives planning product launches, M&A activity, or market entry strategies in 2026, access to this level of detail is indispensable. The macroeconomic trends are clear, but the microeconomic opportunities require precise navigation.
We invite industry leaders to explore the complete findings of the Worldwide Ultrasonic Probe Covers Market report. By leveraging the full scope of our research, you can transform high-level insights into actionable strategies that drive growth and ensure compliance in a rapidly evolving healthcare environment. The path to 2032 is clear, but the steps to get there require the right intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Ultrasonic Probe Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Benign Positional Vertigo Market to Hit $1,427.97M by 2032 at 5.38% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global Benign Positional Vertigo Treatment Market: Strategic Intelligence for 2026 and Beyond
The worldwide market for benign positional vertigo treatment is undergoing a structural transformation driven by aging demographics, diagnostic standardization, and a shift toward minimally invasive and home-based care pathways. For healthcare manufacturers, service providers, and investors, 2026 represents a pivotal decision window. Demand is no longer growing uniformly; it is concentrating around specific treatment modalities, clinical settings, and regional reimbursement environments. PW Consulting's latest market intelligence study maps these shifts with granular precision, converting historical trajectories and forecast pathways into actionable strategic guidance for enterprise planning, product positioning, and capital allocation.
This introduction serves as a strategic preview of the study's architecture, analytical rigor, and competitive relevance. It highlights the macro momentum shaping the sector, outlines the operational dimensions covered in the full report, and frames the competitive landscape through the lens of recent product, certification, and launch activity. The intent is to demonstrate the depth of intelligence available while reserving the most decisive segment-level and regional breakdowns for the complete publication, ensuring that decision-makers gain a credible foundation before committing to detailed procurement or investment analysis.
Market Trajectory and the 2026 Decision Window
Benign positional vertigo treatment has evolved from a fragmented clinical niche into a structured market defined by repeatable diagnostic protocols, standardized repositioning maneuvers, and growing reimbursement familiarity. Historical revenue data from 2020 through 2025 shows a steady climb, reflecting broader adoption of vestibular assessment practices, increased clinical recognition of canalith repositioning efficacy, and expanding distribution of specialized devices. The market reached an estimated 989.49 million USD by the 2025 base year, building on a consistent upward path from earlier periods.
The forecast horizon from 2026 to 2032 introduces a nuanced outlook. While the sector continues to expand at a projected compound annual growth rate of 5.38 percent, the trajectory is not linear. 2026 marks a transitional year in which certain demand patterns recalibrate as providers optimize clinical workflows, payers refine coverage expectations, and manufacturers align product roadmaps with emerging safety and usability requirements. Beyond that point, the market reaccelerates through 2032, with revenue approaching 1.43 billion USD. This shape of the curve matters for strategy: it signals that short-term planning must account for near-term stabilization, while medium-term planning should prepare for renewed volume growth tied to broader clinical adoption and device deployment.
For executives, this trajectory has three immediate implications. First, capacity and inventory decisions should be timed against the 2026 inflection rather than assumed continuous acceleration. Second, product portfolios should emphasize modalities that align with durable clinical workflows, particularly repositioning-based interventions and diagnostic verification tools. Third, regional and channel strategies must be calibrated to local reimbursement realities, because growth is not distributed evenly across care settings or geographic markets. The full study quantifies these dynamics without oversimplifying them, helping leadership avoid over-indexing on headline growth while still capturing the underlying expansion opportunity.
What the Study Delivers: Operational Intelligence for Strategy Teams
The complete market research is built for practical use. It translates high-level trends into structured frameworks that strategy, commercial, and clinical-operations teams can apply directly. The report moves beyond descriptive market sizing to examine how value is created, captured, and contested across treatment pathways, end-user settings, and regulatory environments.
Core components of the study include:
- A historical reconstruction of market revenue from 2020 through 2025, establishing a verified baseline for demand growth, adoption timing, and post-pandemic clinical normalization.
- A forward-looking forecast spanning 2026 to 2032 that isolates the pace of expansion while accounting for modality mix shifts, diagnostic verification needs, and care-setting preferences.
- A segmentation architecture that evaluates treatment types, end-user environments, and regional demand patterns, with emphasis on where adoption is consolidating and where whitespace remains.
- A competitive landscape assessment centered on device manufacturers and diagnostic solution providers that shape procurement choices, clinical workflow design, and channel access.
- An analysis of industry dynamics including regulatory classification requirements, reimbursement behavior, input cost pressures, and clinical practice standards that influence margin structures and product planning.
Each section is designed to support decision-making rather than simply describe the market. The study provides the context needed to evaluate product launch timing, distribution strategy, partnership targeting, and capital deployment. Critically, it also identifies where surface-level data can mislead. For example, total market growth can obscure the fact that certain treatment categories and care settings are carrying more weight than others, and regional performance can differ sharply depending on reimbursement familiarity and clinical workflow maturity. The full report preserves these distinctions so that users can act on differentiated insight rather than aggregate averages.
Competitive Landscape and Recent Industry Activity
The benign positional vertigo treatment market is defined by a compact set of specialist companies that compete across diagnostic verification, repositioning equipment, and supportive vestibular rehabilitation tools. Market concentration reflects this specialization. The top three participants account for approximately 34.25 percent of revenue, while the top five reach roughly 48.6 percent. This level of concentration indicates that incumbents hold meaningful advantages in clinical acceptance, channel relationships, and regulatory familiarity, but it also leaves room for targeted challengers that can differentiate through usability, portability, or workflow integration.
Several companies illustrate the strategic contours of the sector. Entellus Medical, now operating within Stryker, provides sinus dilation and ENT device platforms used in minimally invasive procedures related to repositioning maneuvers for BPPV treatment. Its recent system update in October 2024 introduced enhanced navigation capabilities for BPPV-related sinus interventions, signaling a continued push toward procedural precision and clinician-oriented device refinement. Interacoustics, based in Denmark, offers diagnostic and repositioning solutions such as the TRV Reposition Chair and video goggles used for Epley and other canalith repositioning maneuvers. In June 2024, the company secured CE Mark renewal for its reposition chair with improved patient safety features, reinforcing the importance of certified safety performance in European clinical procurement. Natus Medical, now Natus Neurology, supplies vHIT systems and videonystagmography equipment essential for diagnosis and treatment verification. Its November 2023 launch of a next-generation vHIT ultra system emphasized precise canal identification and treatment monitoring, reflecting a broader focus on diagnostic confidence as a value driver.
The landscape also includes companies extending care beyond the clinic. Bernafon, part of WS Audiology, produces vestibular testing and rehabilitation devices that support particle repositioning therapy, contributing to integrated assessment-to-rehabilitation workflows. Beurer GmbH, based in Germany, manufactures portable Epley maneuver devices and home-use vertigo treatment kits, illustrating the market's gradual expansion into patient-directed and home-care settings. These differing product philosophies matter because they address distinct purchasing drivers: hospitals and ENT clinics prioritize diagnostic certainty and procedural control, while home healthcare and physical therapy channels prioritize ease of use, training burden, and cost-effective deployment.
Competitive strategy in this market is increasingly shaped by more than product features alone. Device classification requirements influence time-to-market and compliance costs. Reimbursement norms affect procedure economics and provider adoption. Input cost volatility affects margin stability for device manufacturers. The study integrates these forces to show how competitive advantage is being constructed in practice, not just in product spec sheets. By connecting recent developments to the structural conditions that shape purchasing behavior, the report helps executives anticipate where incumbents may reinforce their positions and where new entrants or adjacent solutions could gain traction.
Market Dynamics Shaping Strategy in 2026
Beyond sizing and segmentation, the market is being shaped by a set of operational and regulatory dynamics that directly influence commercial planning. One important factor is the regulatory classification environment. In the United States, BPPV treatment devices are classified as Class II, and diagnostic videonystagmography systems as well as repositioning chairs require 510(k) clearance. This classification framework affects development timelines, evidence requirements, and the compliance burden for new entrants, while also reinforcing the position of established manufacturers with existing clearance pathways and clinical validation histories.
Reimbursement behavior is another decisive dynamic. Under Medicare Part B, the canalith repositioning procedure is reimbursed at an average of about 150 USD per session, creating a recognizable procedure economics baseline for providers. At the same time, ENT specialist reimbursement for BPPV treatments in U.S. ambulatory settings averages between 250 and 400 USD per procedure. This gap between device-supported procedure reimbursement and specialist reimbursement influences adoption decisions, service pricing, and the economic justification for investing in specialized diagnostic and repositioning equipment. Providers weigh not only clinical outcomes but also workflow efficiency and revenue realization, which means product value propositions must align with operational and financial realities, not clinical preference alone.
Input costs add a further layer of strategic relevance. Medical-grade silicone used in BPPV maneuver devices has experienced price increases in the range of 15 to 20 percent due to supply chain constraints on polymer resins. For device manufacturers and private-label producers, this creates margin pressure and procurement timing considerations. It also rewards companies that can engineer material efficiency, secure stable sourcing, or offer product designs that reduce dependency on volatile inputs. In a market where many offerings are highly specialized, even modest cost changes can affect pricing strategy and competitive positioning.
Clinical standards further constrain and shape the market. Current practice guidance does not support systemic drug therapies for BPPV; treatment remains centered on physical maneuvers and supportive vestibular rehabilitation. This reality reinforces the centrality of mechanical repositioning, diagnostic verification, and rehabilitation-focused solutions. It also means that product innovation is most durable when it improves maneuver accuracy, patient safety, clinician workflow, or home-based adherence rather than pursuing pharmacological substitution. For strategy teams, this is a critical framing device: the market's growth is tied to better execution of established non-pharmacological care, not to a shift in therapeutic class.
Worldwide Scoliosis Treatment Market
Strategic Implications for 2026 Planning
The intersection of demand trajectory, competitive concentration, regulatory classification, reimbursement patterns, and input cost pressure creates a clear strategic mandate for 2026. Companies should treat the market as a portfolio of distinct opportunities rather than a single growth story. Priorities differ by position in the value chain, but several themes apply broadly.
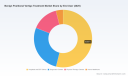
First, product and service strategies should be anchored in the care settings where adoption is most durable. Hospitals and ENT clinics continue to represent a major share of activity because they combine diagnostic capability, procedural volume, and reimbursement familiarity. Diagnostic centers and physical therapy centers contribute significant additional demand by supporting assessment and rehabilitation functions. Home healthcare remains smaller but strategically important as a channel for portable devices and patient-directed kits. Understanding the relative weight and growth behavior of each setting is essential for channel design, training investment, and pricing architecture.
Second, competitive positioning should account for the difference between diagnostic confidence and procedural utility. Some solutions win by strengthening diagnosis and treatment verification, reducing uncertainty in canal identification and repositioning outcomes. Others win by improving the practical execution of maneuvers, patient safety, or portability. The most resilient portfolios often combine both logic streams, either through internal product breadth or through partnership ecosystems. The report's competitive analysis helps identify where these value propositions are being built and where gaps remain.
Third, regional strategy should be informed by local reimbursement and clinical workflow maturity rather than assumed transferability. Demand behavior varies across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, and the full study preserves the regional distinctions that matter for market entry, distribution design, and resource allocation. Aggregate market size can suggest opportunity, but regional insight determines whether that opportunity is accessible, scalable, and economically viable in practice.
Conclusion: Why This Study Matters for Decision-Makers
The benign positional vertigo treatment market is expanding, but its value is being allocated through a complex mix of clinical standards, reimbursement logic, device regulation, and competitive specialization. That makes 2026 a year for disciplined strategy rather than broad assumptions. PW Consulting's Worldwide Benign Positional Vertigo Treatment Market study is designed to give executives the structured intelligence required to navigate that complexity with confidence.
The report provides the full historical baseline, the forecast pathway through 2032, the segmentation detail needed to prioritize modalities and channels, and the competitive context required to interpret recent product and certification activity. More importantly, it connects those data layers to the operational realities that shape adoption and margin performance. For teams evaluating product roadmaps, geographic expansion, partnership opportunities, or investment timing, this study converts market momentum into a usable strategic map.
The detailed segment-level and regional results are reserved for the full publication, where they can be examined in the depth they require. For decision-makers who need to move from awareness to action, that is where the decisive intelligence lives.
Worldwide Benign Positional Vertigo Treatment Market
For detailed analysis of this topic, please visit the official page: Worldwide Benign Positional Vertigo Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Insect Protein Market Hits $750M in 2025, Projected 14.5% CAGR to 2032
By pmarketresearch, 2026-09-16
Future-Proofing Pet Nutrition: The Strategic Imperative of Insect Protein in 2026
The global pet food industry stands at a critical inflection point. Driven by escalating consumer demand for sustainable, hypoallergenic, and nutrient-dense nutrition, insect protein has transitioned from a niche innovation to a core strategic category. For executive leadership, R&D directors, and supply chain strategists, the window to secure competitive advantage in this space is narrowing rapidly. As we move through 2026, understanding the structural shifts, regulatory accelerations, and competitive maneuvers shaping this market is no longer optional—it is a prerequisite for resilient portfolio growth.
PW Consulting’s newly released Pet Food Insect Protein Market research report provides a comprehensive, data-rich roadmap for navigating this transformation. This article serves as a strategic preview, outlining the macro trajectory, competitive architecture, and operational levers that will define industry winners in the 2026–2032 forecast period. To preserve the analytical rigor and proprietary granularity of our full dataset, we highlight the strategic contours here while reserving the precise regional allocations, application-tier breakdowns, and detailed financial modeling for the complete intelligence package.
The Macro Trajectory: Sustained Expansion and Capital Confidence
The market has demonstrated consistent, compounding growth over the past half-decade, reflecting both structural demand shifts and maturing production ecosystems. Historical valuation records show the sector expanding from approximately USD 380 million in 2020 to USD 750 million by 2025, a trajectory that underscores accelerating commercial adoption across premium and specialty segments. Looking ahead, the forecast period projects rapid convergence toward a multi-billion-dollar valuation, with the market expected to approach USD 906 million in 2026 and continue its ascent through the early 2030s.
Underlying this expansion is a forecast compound annual growth rate of 14.5 percent, a figure that positions insect protein among the fastest-scaling alternative protein categories in modern pet nutrition. Such growth velocity signals more than transient trend adoption; it reflects entrenched formulation pipelines, supply chain localization initiatives, and regulatory frameworks that are progressively de-risking ingredient procurement. For strategic planners, this CAGR implies that market share captured today will compound significantly over the next seven years, making early positioning and vertical integration critical determinants of long-term profitability.
Revenue concentration data further illuminates the market’s maturation stage. Current metrics indicate a moderately fragmented landscape, with cumulative enterprise share remaining below pivotal consolidation thresholds. This structural openness presents a distinct strategic window: organizations that move decisively on capacity scaling, regulatory compliance, and premium-brand partnerships can establish defensible positioning before market tightening narrows the field.
Insect Feed Market
Operational Architecture: What the Full Report Delivers
Our research framework is engineered to translate macro trends into executable decision matrices. The complete report delivers a multi-dimensional analysis designed for cross-functional alignment across strategy, procurement, R&D, and commercial leadership. Key deliverables include:
- Historical and Forecast Modeling: Granular volume and value trajectories spanning 2020 through 2032, enabling scenario planning for capacity investment, pricing strategy, and margin optimization.
- Ingredient-Type Stratification: Comparative analysis of primary insect protein streams, evaluating nutritional profiles, processing requirements, and formulation compatibility across dry, wet, and treat formats.
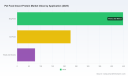
- Application-Segment Mapping: Breakdown of demand drivers across dog food, cat food, and treats/snacks, with insights into formulation intensity, premiumization trends, and pet-owner purchasing behavior.
- Regional Dynamics and Market Access: Evaluation of regulatory timelines, localized production footprints, distribution channel maturity, and cross-border ingredient compliance pathways.
- Competitive Benchmarking and Strategic Positioning: Company-level assessments covering production scale, technological differentiation, partnership ecosystems, and recent capital or facility developments.
- Regulatory and Sustainability Intelligence: Synthesis of AAFCO authorizations, European legislative allowances, lifecycle assessment metrics, and emerging certification frameworks that influence procurement eligibility and brand positioning.
Each analytical module is cross-referenced to support integrated decision-making. Whether evaluating a potential supplier partnership, planning a new product introduction, or assessing geographic expansion feasibility, the report’s architecture ensures that strategic choices are grounded in verifiable, forward-looking intelligence rather than fragmented market narratives.
Competitive Dynamics: Key Players and Strategic Maneuvers
The competitive landscape reflects a hybrid structure of specialized insect ingredient producers and agile pet food brands that have embedded insect protein into core formulations. This dual-ecosystem dynamic creates both collaboration opportunities and competitive friction, as ingredient suppliers increasingly engage in co-development agreements while brands seek exclusive supply arrangements to differentiate premium offerings.
European-origin producers have established early technical leadership, particularly in black soldier fly larvae and mealworm-derived ingredients. Companies such as Innovafeed and Protix have scaled large-format production facilities and positioned their outputs for premium pet food integration, leveraging proprietary rearing and processing methodologies that emphasize nutrient retention and batch consistency. Innovafeed’s recent operational expansions in North America signal a deliberate strategy to localize supply chains and reduce transatlantic logistics friction, while Protix has consistently reinforced its market presence through new protein line launches targeting high-end formulations.
Mealworm specialization has also reached a regulatory and commercial milestone. Ÿnsect, operating from France, supplies mealworm-based protein streams under its Sprÿng brand and achieved a defining authorization to commercialize mealworm proteins for dog food in the United States. This regulatory breakthrough not only validates mealworm nutritional profiles for canine maintenance diets but also establishes a precedent that could accelerate broader alternative-protein acceptance across North American channels. Meanwhile, US-based entities such as EnviroFlight, operating under Darling Ingredients, and Canada-focused producers like Enterra, are advancing black soldier fly ingredient portfolios specifically approved for cat and dog applications, aligning production with regional regulatory frameworks and consumer preference patterns.
Pet Food Insect Protein Market
On the brand side, companies including Yora Pet Foods, Jiminy’s, Tomojo, petgood, and Entomo Farms illustrate how insect protein has moved beyond ingredient supply into complete-diet and treat portfolios. These brands are experimenting with cricket-derived streams, black soldier fly blends, and hybrid formulations to address palatability, allergen management, and sustainability storytelling. Such diversification indicates that the application layer is evolving from early proof-of-concept toward mainstream SKU architecture, with formulation engineers increasingly treating insect protein as a functional, scalable input rather than a promotional novelty.
Regulatory Catalysts and Formulation Realities
Regulatory clarity has emerged as one of the most powerful growth accelerators in this category. In the United States, AAFCO approvals have permitted the use of black soldier fly larvae in whole dried, meal, and oil forms for adult dog maintenance pet food and treats. This authorization framework reduces procurement uncertainty for formulators and provides a compliant pathway for ingredient integration across mainstream and premium product lines. Europe, meanwhile, has established legislative allowances for black soldier fly fat and proteins in pet food formulations, creating a harmonized baseline that supports cross-border supply planning and ingredient standardization.
Beyond regulatory alignment, pricing dynamics reflect the premium positioning of insect-derived inputs. Sector analysis indicates that premium black soldier fly protein for pet food applications commands a range of approximately USD 4 to 8 per kilogram of protein, a pricing band that underscores both processing complexity and value capture potential. For procurement and margin strategy teams, this range highlights the importance of scale efficiency, yield optimization, and long-term offtake agreements in maintaining robust unit economics as demand intensifies.
Sustainability metrics are increasingly influencing procurement decisions and brand positioning. Recent certification updates, including improved sustainability scoring for European production operations, demonstrate that lifecycle performance is becoming a measurable competitive differentiator. As pet owners and retail buyers place greater weight on environmental footprints, ingredient suppliers and brand owners alike are likely to face heightened expectations around traceability, resource efficiency, and verifiable sustainability claims.
Demand-Side Shifts and Strategic Allocation
Consumer and industry behavior continues to reshape how insect protein is deployed across the value chain. Analysis suggests that over half of global insect production is now directed toward pet food applications, a structural allocation that reflects pet nutrition’s role as the primary commercialization pathway for insect-derived ingredients. This demand concentration indicates that pet food manufacturers are not merely experimenting with alternative proteins—they are actively anchoring supply relationships and formulation pipelines around them.
Premiumization remains a defining commercial theme. As brands seek to differentiate through functional nutrition, allergen-aware formulations, and sustainability credentials, insect protein provides a compelling narrative and a technically versatile ingredient base. Treats and snacks, in particular, represent an attractive vehicle for incremental adoption, offering lower formulation risk and faster speed-to-market compared with complete-diet overhauls. At the same time, ongoing advancements in palatability optimization and processing consistency are reducing historical adoption barriers, enabling broader integration across daily feeding regimens.
Why This Research Matters for 2026 Decision-Making
The 2026 landscape demands more than high-level trend awareness. It requires a precise understanding of where capacity is expanding, which regulatory pathways are opening, how ingredient pricing is likely to evolve, and which competitive moves will reshape supply security and brand differentiation. PW Consulting’s full report translates these variables into an actionable intelligence framework, enabling leadership teams to stress-test investment theses, align procurement strategies with forecast dynamics, and identify partnership or acquisition targets that complement long-term growth objectives.
Because the market is scaling at a double-digit CAGR and regulatory clarity is steadily broadening, organizations that act on detailed, verified data will be better positioned to secure favorable supply terms, capture premium-segment demand, and anticipate consolidation pressures. The complete report contains the granular regional and application-level valuations, supplier-level operational metrics, and forward scenario analyses necessary to convert strategic intent into executable plans.
Conclusion: Securing Position Before the Curve Steepens
Insect protein in pet food has crossed the threshold from emerging alternative to strategic category. The combination of sustained compound growth, accelerating regulatory authorization, expanding production footprints, and entrenched demand allocation toward pet nutrition creates a market environment where timing, data quality, and execution discipline will separate leaders from followers. PW Consulting’s Pet Food Insect Protein Market report is designed to provide the analytical depth required to navigate that environment with confidence.
For executives seeking to validate expansion plans, optimize ingredient sourcing, or benchmark competitive positioning, the full dataset offers the granularity necessary to make informed, forward-looking decisions. We invite strategy, procurement, and commercial leaders to access the complete research for detailed segmentation valuation, competitive profiling, and scenario-based forecasting that will directly inform 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pet Food Insect Protein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global ASRS Market to Hit $20.08B by 2032, Driven by 8.21% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperative: Navigating the Automated Storage Retrieval System Market in 2026
The global intralogistics landscape is undergoing a structural transformation, driven by the convergence of labor scarcity, e-commerce velocity, and technological maturity. For executives planning capital allocation in 2026, understanding the Automated Storage Retrieval System (AS/RS) market is no longer a niche engineering consideration—it is a board-level strategic priority. This article serves as a precursor to PW Consulting's latest comprehensive market research, designed to equip decision-makers with the contextual framework needed to interpret the full intelligence report.
As organizations move from pilot projects to scaled deployment, the ability to discern genuine growth trajectories from market noise is critical. The following analysis synthesizes macroeconomic data, competitive dynamics, and operational drivers to outline why this market warrants immediate attention.
Market Trajectory and Economic Significance
The historical performance of the AS/RS sector indicates a robust and accelerating adoption curve. Over the past five years, the global market has demonstrated resilience against supply chain disruptions, evolving from a consolidated revenue base to a significantly expanded operational footprint. Current market valuation estimates place the 2026 revenue at approximately 12.1 billion USD, reflecting a cumulative growth trend that has been consistent since 2020.
Looking toward the end of the forecast period, projections suggest the market will surpass the 20 billion USD milestone by 2032. This expansion is underpinned by a compound annual growth rate (CAGR) of roughly 8.21 percent across the 2026 to 2032 forecast horizon. Such growth rates signal a market moving beyond early adoption into a mainstream infrastructure phase, where automation is becoming a default requirement rather than a competitive differentiator.
Several macroeconomic factors are fueling this trajectory. According to recent data from the U.S. Bureau of Labor Statistics, warehouse automation is being accelerated by labor shortages, with 600,000 unfilled positions projected for 2026. Simultaneously, a PwC intralogistics study indicates that modern e-commerce growth requires AS/RS throughput exceeding 1,000 picks per hour, a benchmark that manual operations struggle to meet consistently. These pressures are forcing capital investment into automated solutions that maximize density and speed without proportional increases in human labor.
Operational Dynamics and Supply Chain Context
While demand signals are strong, the procurement environment in 2026 presents a complex mix of cost pressures and technological enablers. Decision-makers must balance the urgency of automation against the volatility of input costs. For instance, the World Steel Association reported in March 2025 that steel coil prices for structural frames in AS/RS rose 12 percent to 850 USD per ton due to supply chain disruptions. This input cost volatility can impact the total cost of ownership for large-scale installations, necessitating careful vendor negotiation and timing strategies.
Conversely, technological cost reductions are improving the economic case for specific system types. BloombergNEF noted in January 2025 that Li-ion battery prices for AS/RS shuttles declined 15 percent to 120 USD per kWh in 2025. This reduction lowers the operational expenditure for battery-dependent shuttle and bot-based systems, potentially shifting the preference toward flexible, mobile automation solutions over fixed infrastructure in certain applications.
Regulatory compliance also remains a critical consideration, particularly for operations expanding into or within Europe. The European Commission updated the EU Machinery Directive 2006/42/EC in 2024, mandating enhanced safety sensors for AS/RS stacker cranes. Compliance with these updated standards is not merely a legal checkbox but a factor that influences system design, integration costs, and vendor selection. Companies must ensure their chosen partners are aligned with these newer safety protocols to avoid retrofitting costs later.
Key Drivers Influencing Investment
- Labor Economics: Rising wage pressures and unfilled positions in key logistics hubs are making the ROI calculation for automation more favorable.
- Throughput Requirements: The shift toward same-day and next-day delivery expectations is pushing throughput requirements beyond manual capabilities.
- Space Optimization: Urban land costs are driving the need for vertical storage solutions and high-density cubing technologies.
- Regulatory Safety: New safety mandates are standardizing sensor integration, influencing the baseline specification for new installations.
Competitive Landscape and Strategic Positioning
The AS/RS market is characterized by a mix of established industrial giants and specialized technology innovators. Market concentration data suggests a moderately fragmented landscape, with the top three competitors holding approximately 31.4 percent of the market share and the top five controlling around 46.8 percent. This structure implies that while scale players dominate significant portions of the market, there is ample room for specialized providers to capture value in niche applications or specific geographies.
Leaders in the space are diversifying their portfolios to address varying density and throughput needs. Dematic, headquartered in Atlanta, GA, remains a global leader in automated storage and retrieval systems including shuttle-based, crane-based, and mini-load solutions. At ProMat 2025 in March 2025, Dematic showcased next-generation AutoStore Fusion AS/RS with enhanced robot density, signaling a push toward higher capacity within smaller footprints.
Swisslog, based in Buchs, Switzerland, continues to innovate in high-density storage with solutions like AutoStore, CarryPick, and Matrix. In January 2025, they launched the CarryPick Edge AS/RS specifically for cold storage with -30°C capability, addressing the stringent requirements of temperature-controlled logistics. Meanwhile, Daifuku from Osaka, Japan, leverages strong ties in the automotive sector, recently delivering ETV OS pallet shuttle AS/RS to Toyota's North American parts center in November 2024.
Worldwide Automated Storage Retrieval System Market
European manufacturers are also aggressively expanding their technological edges. KION Group, through its Linde Material Handling brand in Wiesbaden, Germany, delivers AutoStore-integrated and stacker crane AS/RS through STILL and Linde brands. Jungheinrich of Hamburg presented new shuttle-based AS/RS at LogiMAT 2024 with AI-optimized throughput, highlighting the industry's shift toward software-defined hardware performance. SSI Schaefer, based in Neunkirchen, Germany, continues to optimize retail and pharma storage with Weasel shuttle and Miniload solutions, recently appointing a new distributor for Weasel AS/RS in the Southeast Asia region to expand their geographic reach.
Specialized players are carving out distinct value propositions. AutoStore in Stavanger, Norway, pioneers cubic grid-based AS/RS with R5 robots for ultra-dense storage, particularly in e-commerce and wholesale. TGW Logistics in Wels, Austria, focuses on e-fulfillment with their PickCenter and FlashPick solutions for modular shuttle and tote-based automation. WITRON in Parkstein, Germany, designs OPM AS/RS for grocery retail with high-speed tote and tray handling, while Interlake Mecalux in Barcelona supports food and beverage sectors with Easy WMS-integrated stacker cranes. Murata Machinery from Kyoto adds depth in the semiconductor and automotive industries with their VANTIQ mini-load and pallet systems.
Vendor Selection Considerations
- Technology Fit: Evaluate whether shuttle, crane, or cube-based systems align with your SKU profile and throughput needs.
- Geographic Support: Consider vendor presence in key operational regions, as seen with SSI Schaefer's recent Southeast Asia expansion.
- Industry Specifics: Certain vendors offer specialized adaptations, such as Swisslog's cold storage capabilities or Daifuku's automotive pedigree.
- Integration Ecosystem: Assess the compatibility of AS/RS hardware with existing Warehouse Management Systems (WMS) and software layers.
Segmentation Insights and Application Diversity
The AS/RS market is not monolithic; it is defined by diverse technology types and end-user applications, each with distinct growth drivers. Understanding the broad allocation of market activity helps in benchmarking organizational strategy against industry trends. However, precise quantitative splits require deeper analysis available in the full report.
In terms of technology types, the market encompasses a wide spectrum ranging from traditional Unit Load systems to advanced Mini Load solutions. Vertical Lift Modules (VLMs) and Shuttle and Bot-based Systems represent significant segments, catering to different density and speed requirements. Carousels also maintain a presence in specific operational contexts. The choice between these types often depends on the physical characteristics of the goods being stored and the required access frequency.
End-user diversification is equally critical. While E-commerce and Retail drive a substantial portion of demand due to the need for rapid order fulfillment, other sectors are adopting AS/RS at varying paces. Food and Beverages, Automotive, Healthcare and Pharmaceuticals, and Manufacturing sectors all contribute to the overall market volume. Each industry presents unique challenges, such as hygiene standards in pharma, traceability in automotive, or temperature control in food logistics.
Regional dynamics also play a pivotal role in shaping market opportunities. Activity is distributed across major economic zones including Asia Pacific, Europe, North America, and the Rest of World. Each region exhibits different adoption rates influenced by local labor costs, infrastructure maturity, and regulatory environments. For a detailed understanding of regional performance metrics and specific application share, stakeholders are encouraged to consult the complete dataset in the full research publication.
Conclusion and Call to Action
The Automated Storage Retrieval System market in 2026 presents a landscape of significant opportunity tempered by complex operational and economic variables. The projected growth to over 20 billion USD by 2032 underscores the long-term viability of automation investments. However, success depends on navigating the nuances of technology selection, vendor capabilities, and external cost drivers.
Strategic decisions made in this market will define operational efficiency for the next decade. To support these critical decisions, PW Consulting has compiled a detailed Worldwide Automated Storage Retrieval System Market report. This document provides the granular data, segmentation breakdowns, and competitive analysis necessary to move from high-level strategy to executable planning.
We invite industry leaders, investors, and supply chain executives to access the full report for comprehensive intelligence. The detailed insights contained within will enable you to validate assumptions, benchmark against peers, and secure a competitive advantage in the evolving world of intralogistics automation.
Worldwide Warehouse Automated Sorting System Market
For detailed analysis of this topic, please visit the official page: Worldwide Automated Storage Retrieval System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Sunlight Simulators Market to Reach $890.52M by 2032 at 7.0% CAGR
By pmarketresearch, 2026-09-16
Global Sunlight Simulators Market: Strategic Intelligence for Enterprise Decision-Making in 2026
Introduction: Navigating Solar Simulation Amidst Technological Transition
The global demand for precise, reproducible, and spectrally accurate sunlight simulation has entered a phase of accelerated maturation. As photovoltaic manufacturing scales, next-generation tandem and perovskite architectures mature, and cross-industry applications in aerospace, biotechnology, and materials testing expand, organizations face increasingly complex procurement and R&D strategy choices. Our newly released Worldwide Sunlight Simulators Market study delivers a comprehensive, data-driven foundation for enterprise decision-makers operating in 2026 and beyond.
This executive overview distills the core strategic themes, competitive architectures, and operational imperatives that will shape capital allocation, technology roadmapping, and partnership strategies. By mapping historical trajectories against forward-looking forecast horizons, the report equips leadership teams with actionable intelligence while preserving the granular analytical depth required for precise market navigation.
Macro Market Trajectory and Structural Growth Dynamics
The sunlight simulators market has demonstrated consistent expansion over the historical evaluation window, building from approximately 395.4 million USD in 2020 to an estimated 554.57 million USD in 2025. This baseline reflects sustained investment in standardized testing infrastructure, regulatory compliance frameworks, and research-grade optical instrumentation. Looking ahead, the forecast period extending through 2032 projects a steady compound annual growth rate of 7.0 percent, culminating in a market valuation approaching 890.52 million USD.
Such growth is not homogenous. Demand acceleration is being shaped by the interplay of three structural forces: the proliferation of high-throughput module qualification lines, the transition from legacy continuous-spectrum illumination technologies toward spectrally tunable solid-state architectures, and the broadening of application mandates beyond traditional photovoltaic qualification. Organizations that rely on static market assumptions risk misaligning procurement cycles, R&D budgets, and capacity planning with the actual pace of segment-level demand migration.
Strategic planning in 2026 must therefore account for the divergence between headline growth and segment-specific velocity. Forecasting models embedded in this study isolate these dynamics, enabling readers to distinguish between incremental market expansion and structural technology substitution events that will redefine procurement requirements, vendor evaluation criteria, and facility investment timelines.
Research and Testing Applications: The Demand Anchor
Photovoltaic module testing continues to function as the primary demand engine for sunlight simulation infrastructure. Qualification workflows, manufacturing line verification, and performance certification depend on repeatable illumination conditions that meet stringent international standards. As cell architectures grow more complex—incorporating tandem stacks, heterojunction designs, and advanced anti-reflective or passivation coatings—testing protocols increasingly require adjustable spectral output, uniform irradiance across large areas, and precise thermal management during measurement cycles.
Beyond solar energy, secondary application verticals are contributing incremental but strategically significant growth. Aerospace and defense organizations utilize solar simulation for optical sensor calibration, environmental exposure verification, and materials durability assessment under controlled solar spectra. Materials and cosmetics testing laboratories leverage standardized illumination for photostability evaluation, weathering simulation, and formulation screening. Concurrently, biotechnology and agriculture applications are expanding the use case envelope for controlled-spectrum exposure in plant physiology research, photobiological assays, and controlled-environment agricultural prototyping.
Understanding how spending patterns distribute across these application domains is essential for equipment manufacturers, laboratory operators, and supply chain planners. The study delineates how application-specific requirements influence light source selection, classification thresholds, and automation integration, ensuring that procurement strategies are aligned with actual usage intensity rather than generalized market narratives.
Technology Architecture and Light Source Evolution
The technological composition of the sunlight simulators market reflects an ongoing architectural debate between established xenon lamp platforms and emerging LED-based simulation systems. LED-based simulators have gained prominence through their spectral tunability, extended operational lifetimes, reduced thermal footprints, and compatibility with automated testing environments. These attributes align with high-throughput manufacturing lines and research workflows that demand rapid reconfiguration between spectral profiles such as AM0, AM1.5G, and customized band-limited outputs.
Xenon lamp-based simulators retain relevance in scenarios requiring high-intensity flash or continuous-spectrum outputs that historically align with specific qualification standards and legacy test infrastructure. In parallel, metal halide and complementary light source configurations serve niche requirements where particular spectral characteristics, illumination geometries, or cost considerations dictate equipment selection. The market is not experiencing a simple substitution effect; rather, it is evolving into a multi-technology landscape in which end users select platforms based on application class, testing cadence, spectral fidelity requirements, and total cost of ownership over the equipment lifecycle.
A critical strategic consideration is how classification standards influence purchasing behavior. Equipment rated across Class A, A+, and A+++ parameters must satisfy defined criteria for spectral match, temporal stability, and spatial uniformity. Organizations evaluating capital expenditures need clarity on which classification tier matches their regulatory obligations, internal quality thresholds, and future technology roadmap. The report examines these technical differentiators through a commercial lens, connecting laboratory performance specifications with procurement economics and vendor evaluation frameworks.
Geographic Distribution and Regional Demand Drivers
Regional demand patterns reflect differences in manufacturing density, research infrastructure investment, regulatory environments, and energy policy momentum. Asia Pacific represents a substantial share of current market activity, supported by concentrated photovoltaic manufacturing ecosystems, expanding research institutions, and large-scale module qualification operations. North America and Europe maintain robust demand driven by advanced research programs, aerospace and defense testing requirements, pharmaceutical and cosmetics photostability workflows, and sustained investment in next-generation photovoltaic technologies.
The Rest of World segment, while smaller in absolute terms, reflects emerging testing infrastructure development and regional qualification center expansion. Enterprises operating across multiple jurisdictions must account for variations in standards adoption, service network availability, calibration support, and equipment localization requirements. Regional procurement strategies that ignore local service ecosystems or compliance nuances often encounter longer deployment cycles, higher validation costs, and greater operational risk.
Our geographic analysis avoids simplistic ranking narratives. Instead, it examines how regional manufacturing footprints, export qualification requirements, and localized testing mandates shape equipment specification decisions, vendor selection criteria, and after-sales service expectations. This framing enables multinational operators to design region-specific deployment strategies rather than applying uniform procurement templates across diverse markets.
Competitive Landscape: Differentiation, M&A, and Capability Consolidation
The competitive environment is defined by a concentrated but diversifying vendor base. The top five participants collectively account for approximately 48.7 percent of market revenue, while the top three hold roughly 31.4 percent, indicating a landscape where established leaders retain meaningful share but face rising pressure from specialized innovators and capability expansions through acquisition.
Several participants illustrate the strategic directions shaping the market. G2V Optics Inc. has built its positioning around advanced tunable LED solar simulators, including the Pico and Sunbrick series, with Class AAA and A+A+A+ configurations designed to replicate AM0 through AM1.5G spectra. Its emphasis on long LED lifetime and automation support appeals to research, photovoltaic, aerospace, and photochemistry applications requiring repeatable spectral control.
Eternal Sun has positioned itself as a leading provider of solar module testing equipment, offering steady-state LED solar simulators with A+A+A+ class performance alongside SPIRE Xenon-based flash solar simulators for IV testing of PV modules. Its support for tandem and perovskite technologies, combined with temperature control capabilities, reflects alignment with evolving cell architectures and qualification demands.
Avalon ST has focused on long-pulse, high-accuracy large-area LED solar simulators under its Nexun series, with A+ to A+++ classifications targeting photovoltaic and spatial industry applications, including perovskite, HJT, and AM0 testing. Its 2025 acquisition of PASAN SA represents a notable consolidation move, integrating LED-based solar simulation expertise with xenon-based simulators and precision measurement systems to broaden PV metrology offerings. This type of capability combination illustrates how vendors are seeking to serve customers across multiple light source architectures rather than competing within a single technology niche.
Newport Corporation provides the Sol series of arc lamp and LED solar simulators with compliance to ASTM, IEC, and JIS standards, including UV Sol-UV models for varied illumination areas and material testing applications. Solar Light Company, LLC delivers precision research-grade solar simulators aligned with ISO, FDA, JCIA, COLIPA, ASTM, and IEC standards, with strong recognition in SPF testing laboratories and light sciences applications. Abet Technologies, Inc. offers compliant simulators spanning 150W to 3kW, including the SunLite line for solar cell testing across DSSC, perovskite, silicon, and thin film technologies. Sciencetech Inc. complements this landscape with customized and standard simulators, including high-flux models for research applications in photovoltaics and related fields.
These profiles underscore a market in which competitive advantage is increasingly determined by application coverage, standards compliance breadth, spectral customization capability, and the ability to support automation and temperature-controlled testing workflows. Recent activity, such as the 2025 consolidation involving Avalon ST and the 2024 high-flux installation milestone achieved by Sciencetech Inc., signals an industry that is actively reshaping its capability base to match the requirements of advanced cell technologies and high-throughput testing environments.
Strategic Value of the Report for Enterprise Decision-Making
This study is designed to convert market complexity into operational clarity. It provides decision-makers with a structured framework for evaluating technology roadmaps, procurement timing, vendor qualification, and investment prioritization. The analysis is built to support multiple organizational functions, including R&D strategy, manufacturing operations, quality and compliance teams, procurement, and corporate development.
Key deliverables and practical contents include:
Worldwide Sunlight Simulators Market
- A full historical reconstruction from 2020 through 2025, paired with a forecast trajectory extending to 2032, enabling sensitivity analysis around adoption velocity, technology mix shifts, and demand elasticity.
- Segment-level evaluation across light source architectures, application categories, and regional demand structures, with interpretive guidance on how each dimension influences purchasing requirements and vendor selection.
- Competitive profiling of leading manufacturers, including headquarters location, product architecture, standards compliance, application focus, and recent strategic developments, supporting benchmarking and partnership assessment.
- Analysis of market concentration metrics and implications for supplier negotiation, switching costs, and technology roadmap dependency.
- Contextual interpretation of industry dynamics affecting procurement cycles, validation requirements, and service infrastructure expectations.
- Decision-oriented frameworks for aligning equipment classification, spectral customization needs, illumination area requirements, and automation readiness with actual operational use cases.
This multidimensional structure allows readers to move beyond top-line market sizing and into the operational logic that determines where value is created or lost. Procurement leaders can use the analysis to time capital expenditures against anticipated technology mix transitions. R&D managers can map spectral and classification requirements to upcoming cell or material programs. Corporate development teams can evaluate acquisition targets and partnership opportunities based on capability complementarity rather than revenue scale alone.
Forward Outlook for 2026 and Beyond
The next phase of market development will likely be shaped by the continued integration of LED-based tunability with high-accuracy large-area illumination, the expansion of flash and steady-state solutions for advanced tandem and perovskite module testing, and the growing importance of precision measurement ecosystems that accompany solar simulation hardware. As qualification standards evolve and product architectures become more spectrally and thermally demanding, equipment selection will increasingly hinge on lifecycle performance, automation compatibility, and vendor-supported calibration and service networks.
Enterprises that establish clear internal definitions of required spectral match, temporal stability, spatial uniformity, and application coverage will be better positioned to navigate vendor offerings without over-specifying or under-equipping their testing infrastructure. At the same time, organizations operating across multiple verticals should expect to manage a more diversified equipment portfolio, balancing high-throughput manufacturing requirements against research-grade flexibility and specialized compliance demands.
This report provides the analytical scaffolding needed to make those decisions with confidence. It combines historical market reconstruction, forward-looking demand modeling, technology architecture assessment, and competitive capability mapping into a single strategic reference point for 2026 planning cycles.
Conclusion
The worldwide sunlight simulators market is entering a period in which growth, technology differentiation, and application expansion will jointly determine competitive outcomes. Enterprise leaders who rely on aggregate market narratives alone risk misjudging where demand is actually intensifying, which technological pathways will dominate specific use cases, and how vendor capabilities are consolidating to serve advanced testing requirements.
Our full market study delivers the granular segmentation, competitive benchmarking, regional interpretation, and forward forecast detail necessary to translate strategic intent into executable plans. To access the complete dataset, segmentation analysis, competitive profiles, and scenario-based forecast frameworks that support precise procurement, R&D, and investment decisions, refer to the full report through our official research portal.
Aviation Simulators Market
For detailed analysis of this topic, please visit the official page: Worldwide Sunlight Simulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Potassium Carbonate Hydrate Market Hits $479.77M in 2025, Set to Reach $648.54M by 2032 at 4.4% CAGR
By pmarketresearch, 2026-09-16
Navigating the Evolving Landscape of Potassium Carbonate Hydrate: Strategic Insights for 2026 and Beyond
The global potassium carbonate hydrate market is entering a pivotal phase defined by steady structural growth, shifting regulatory frameworks, and intensifying competition across key industrial verticals. As we advance into 2026, corporate decision-makers across manufacturing, supply chain, and procurement functions require more than high-level forecasts. They need a granular, actionable intelligence framework that maps historical trajectories, anticipates macroeconomic and policy inflection points, and decodes the competitive maneuvering of leading producers. Our newly published Worldwide Potassium Carbonate Hydrate Market research study delivers precisely that. Designed as a strategic compass rather than a static dataset, this report equips executives with the analytical depth required to optimize sourcing strategies, evaluate market entry opportunities, and align capital allocation with emerging demand cycles.
Over the past half-decade, the sector has demonstrated remarkable resilience amid fluctuating feedstock costs, regional energy constraints, and evolving compliance mandates. From 2020 through 2025, global revenue expanded from approximately 382.45 million USD to 479.77 million USD, reflecting a compound trajectory that underscores the material's indispensable role across glass and ceramics, agrochemicals, food processing, and specialty chemical synthesis. Looking ahead to the 2026 to 2032 forecast window, the market is projected to reach 502.78 million USD in the current year, with sustained momentum carrying valuation toward 648.54 million USD by the close of the forecast period. This expansion is underpinned by a consistent compound annual growth rate of 4.4%, signaling a moderately paced but structurally robust upward curve. For strategic planners, these figures are not merely retrospective milestones; they represent baseline parameters against which capacity investments, pricing strategies, and regional allocation decisions must be calibrated.
Strategic Forecast Architecture: Mapping 2026 to 2032
The credibility of any market intelligence asset lies in its ability to translate macroeconomic indicators into operational foresight. This report constructs a multi-layered forecasting architecture that accounts for historical consumption patterns, production economics, and forward-looking demand triggers. The base year of 2025 anchors a robust back-casting methodology, ensuring that incremental year-over-year movements reflect authentic market dynamics rather than statistical smoothing. As the analysis progresses through 2026, 2027, and beyond, the model incorporates sensitivity variables tied to feedstock availability, energy pricing volatility, and regulatory compliance costs. Executives will find particular value in how the forecast isolates inflection points where supply chain bottlenecks or policy shifts could materially alter regional supply-demand equilibriums. By treating the 4.4% CAGR not as a static promise but as a dynamic range modulated by real-world variables, the study empowers leadership teams to stress-test their strategic assumptions against plausible disruption scenarios.
Supply Chain Architecture and Production Economics
Understanding the potassium carbonate hydrate value chain requires a clear grasp of how raw material inputs translate into finished grades ready for industrial, food, or pharmaceutical deployment. The production pathway typically begins with potassium hydroxide derived from potash, which reacts with carbon dioxide in controlled carbonation environments. Notably, this process frequently involves carbon capture mechanisms that initially yield the hydrated form, K2CO3·1.5H2O, before targeted dehydration steps produce anhydrous variants for specialized applications. This technical nuance carries direct implications for energy intensity, capital expenditure, and regional cost competitiveness. Facilities integrated with upstream chlor-alkali operations benefit from feedstock synergies, while standalone producers must navigate broader commodity market exposures. Pricing dynamics in late 2025 further illustrate the geography-driven cost landscape. In Northeast Asia, hydrated potassium carbonate traded around 1.17 USD per kilogram, supported by firm upstream potassium hydroxide costs and consistent pull from specialty glass and ceramics manufacturers. Across Europe, prices climbed to approximately 1.70 USD per kilogram, reflecting higher energy and natural gas expenditures that directly pressure energy-intensive carbonation processes, alongside robust demand from pharmaceutical and detergent sectors. These regional differentials are not transient anomalies; they represent structural pricing layers that procurement and manufacturing strategists must factor into long-term contract negotiations and plant location evaluations.
Regulatory and Compliance Inflection Points
Regulatory shifts are rapidly transitioning from peripheral considerations to central strategic variables. Beginning January 1, 2026, potassium carbonate has been added to the Internal Revenue Service taxable chemical substances list under Superfund tax rules, a development triggered by the fact that taxable chemicals constitute more than twenty percent by weight in its predominant production methodology. This classification introduces new compliance cost considerations that will ripple through production economics, particularly for facilities operating at scale or those navigating multi-jurisdictional supply networks. Simultaneously, the material remains under review within the USDA National Organic Program sunset process, with ongoing evaluation slated for 2027 regarding its continued allowance in organic crop production as a synthetic substance. For agrochemical and food processing stakeholders, the trajectory of this review carries tangible implications for formulation strategies, certification pathways, and downstream market access. The report dissects these regulatory currents with precision, mapping how compliance timelines intersect with production planning, supply chain diversification, and product portfolio positioning. Executives who anticipate regulatory friction rather than react to it will secure decisive cost and market access advantages.
Competitive Landscape and Strategic Positioning
Global Market Concentration and Strategic Holdings
The potassium carbonate hydrate sector exhibits moderate concentration, with the top three players collectively capturing approximately 42.8 percent of market revenue and the top five expanding that share to 58.5 percent. This structure indicates a landscape where scale advantages, integrated production capabilities, and diversified application portfolios create meaningful competitive moats, while still leaving substantial room for specialized producers and regional champions to carve out defensible niches. Strategic positioning in this environment demands more than volume expansion; it requires alignment between grade specialization, geographic reach, and application-specific technical support.
Potassium Formate Market
Key Players and Strategic Profiles
Armand Products Company, headquartered in Muscle Shoals, Alabama, stands as a world leader in potassium carbonate production, operating large-scale manufacturing capacity that ships both anhydrous and hydrated grades globally across industrial, food, and specialty applications. Its ISO 9001:2015 certified facility underscores a commitment to standardized quality control that resonates strongly with regulated end markets. Vynova Group, anchored by Belgium-based operations, supplies multiple grades in crystalline granulated, powder, and hydrated forms to European and worldwide markets, with dedicated applications spanning food, pharmaceutical, agrochemical, and cocoa processing sectors. Its multi-format capability positions the company as a flexible supplier capable of addressing highly specific formulation requirements. INEOS KOH operates across the USA and Europe, producing liquid potassium carbonate at a forty-seven percent solution concentration using upstream potassium hydroxide from its chlor-alkali plant. This integration supports demanding use cases in video glass manufacturing, animal feed additives, and polymer catalysts, where consistent chemical delivery and volume reliability are paramount. Hawkins, Inc., based in the USA, manufactures high-purity liquid potassium carbonate at the same forty-seven percent concentration, targeting agriculture, printed circuit board production, food preservation, and oil industry applications. Its focus on purity and liquid-form convenience addresses specialized processing environments where handling efficiency and chemical precision directly influence downstream performance. UNID Company Ltd., headquartered in Seoul, South Korea, operates as a major Asian producer within its inorganic chemicals division, leveraging significant production capacity to serve both domestic and export markets. Evonik Industries AG, the Germany-based global specialty chemicals company, produces potassium carbonate for a broad spectrum of industrial applications, drawing on its advanced chemical engineering infrastructure to support performance-driven formulations. AGC Inc., also known as AGC Chemicals, is headquartered in Japan and supplies high-purity potassium carbonate specifically tailored for ceramics, glass, and other specialty applications where material consistency and trace impurity control are non-negotiable. Altair Chimica SpA, an Italian producer, operates alongside caustic potash and other inorganic chemicals, offering European buyers integrated sourcing options that reduce supply chain fragmentation. In China, Zhejiang Dayang Biotech Group Co. Ltd. has established itself as a significant manufacturer and exporter with broad domestic and international supply reach, while Wentong Potassium Salt Group, operating under Qinghai Yanhu, focuses on high-purity potassium carbonate grades and has pursued capacity expansions specifically targeted at electronics and industrial uses. Together, these players illustrate a competitive ecosystem where scale, purity, regional proximity, and application specialization intersect in complex ways. The report provides detailed comparative analytics that reveal how each enterprise is positioning itself to capture value across grade segments, geographic corridors, and end-use verticals.
Report Architecture: Operational Intelligence for Decision Makers
The Worldwide Potassium Carbonate Hydrate Market study is engineered for immediate operational relevance. Beyond macroeconomic forecasting, the report delivers a structured breakdown of market segmentation that maps revenue distribution across grades, applications, and regions, enabling procurement teams to identify concentration risks and supply diversification pathways. The grade analysis distinguishes between industrial, food, and pharmaceutical categories, highlighting how purity thresholds, certification requirements, and pricing premiums shape margin structures and competitive dynamics. Application-level evaluation traces how demand from glass and ceramics, agrochemicals and fertilizers, food processing, chemical intermediates, and other verticals interacts with production capacity, seasonal consumption cycles, and substitution risks. Geographic coverage extends across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, providing context on regional supply-demand balances, logistics considerations, and localized pricing behaviors without reducing the narrative to static percentage breakdowns. Competitive profiling synthesizes facility capabilities, certification footprints, product format portfolios, and strategic expansions into actionable benchmarking frameworks. The report also integrates scenario analysis modules that allow executive teams to model the financial and operational impact of regulatory adjustments, feedstock volatility, and demand acceleration or deceleration across the forecast window. By aligning quantitative baselines with qualitative strategic context, the study functions as a decision-support platform that can be deployed across planning, sourcing, and market-entry workstreams.
Strategic Imperatives for Corporate Leadership
As the market navigates the 2026 to 2032 horizon, leadership teams must translate intelligence into action across several interconnected fronts. First, procurement strategies should account for the widening regional price differentials and the structural energy cost pressures that influence European and Northeast Asian supply economics, particularly when negotiating multi-year supply agreements. Second, regulatory preparedness must become a core competency, with compliance teams tracking the Superfund taxable chemical classification and the ongoing USDA organic program review to anticipate cost adjustments and formulation constraints before they disrupt procurement cycles. Third, competitive positioning demands clarity on grade specialization and application focus, as margin profiles diverge sharply between bulk industrial supply and high-purity pharmaceutical or specialty glass requirements. Fourth, capacity planning and geographic diversification should be evaluated against regional concentration patterns and logistics resilience, ensuring that supply networks can absorb localized disruptions without compromising delivery reliability. Finally, strategic partnerships and supplier evaluations should be grounded in a detailed understanding of each major producer's technical capabilities, certification status, and expansion trajectories, enabling more precise vendor selection and long-term collaboration frameworks.
Worldwide Potassium Carbonate Hydrate Market
The Worldwide Potassium Carbonate Hydrate Market research study is designed to serve as the foundational intelligence asset for these strategic priorities. By combining rigorous historical analysis, transparent forecasting methodology, segmentation insights, and competitive profiling, the report provides a comprehensive view of where the market stands, how it is likely to evolve, and what decisions will separate resilient operators from reactive followers. Executives who engage with the full spectrum of findings will be better positioned to allocate capital efficiently, negotiate from a position of informed strength, and anticipate the regulatory and competitive shifts that will define the next phase of market development. To access the complete segmentation breakdowns, detailed company benchmarking, regional pricing trajectories, and scenario modeling tools that underpin these insights, we invite you to explore the full report through our official portal and integrate this intelligence directly into your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Potassium Carbonate Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Sonobuoy Launcher Market to Hit $530.14M by 2032, Growing at 5.46% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence in the Deep Blue: Navigating the Global Sonobuoy Launcher Market in 2026
The undersea warfare landscape is undergoing a profound transformation. As naval powers prioritize anti-submarine warfare (ASW) capabilities to counter evolving underwater threats, the mechanisms by which airborne assets deploy surveillance equipment have become critical nodes in the defense supply chain. The Worldwide Sonobuoy Launcher Market represents more than just a component segment; it is the enabling interface between maritime patrol platforms and the acoustic sensors essential for detecting modern submarines. For defense executives, procurement officers, and strategic investors, understanding the trajectory of this market is no longer optional—it is imperative for capitalizing on emerging opportunities and mitigating supply chain risks in Fiscal Year 2026 and beyond.
In this complex environment, generic market observations are insufficient. Decision-makers require granular intelligence that connects macroeconomic trends, technological shifts, and competitive maneuvering. PW Consulting is proud to introduce our latest comprehensive study, designed to equip stakeholders with the actionable intelligence needed to navigate this specialized sector. This introduction outlines the strategic value of the research, highlighting the market's current momentum, the competitive dynamics shaping the industry, and the specific operational content included in our full report.
Worldwide Sonobuoy Launcher Market
Market Trajectory and Economic Context
The sonobuoy launcher sector has demonstrated resilient growth over the past five years, driven by sustained defense spending and the modernization of ASW fleets. According to our analysis, the global market revenue has shown a consistent upward trajectory, with historical performance reflecting the steady demand for airborne ASW capabilities. The market valuation stood at approximately $346.93 million in 2024, progressing to an estimated $365.4 million in 2025. This growth is not merely linear; it reflects the increasing complexity of naval missions and the necessity for reliable deployment systems for A-size, F-size, and G-size sonobuoys.
The forecast period from 2026 to 2032 indicates a robust expansion path. Our models project the market will reach approximately $408.79 million in 2026, signaling a significant step up in procurement and modernization cycles. Looking further ahead, the compound annual growth rate (CAGR) is calculated at 5.46 percent. This rate underscores a mature yet steadily growing industry, fueled by the replacement of legacy systems and the integration of new platforms.
- Revenue Momentum: The transition from 2025 to 2026 reflects a critical inflection point where multiple naval programs converge.
- Long-Term Outlook: Projections extend through 2032, offering visibility into long-term R&D and production planning.
- Currency and Scale: All financial data is presented in USD Million, ensuring consistency for international benchmarking.
This macroeconomic backdrop provides the necessary context for understanding vendor performance and contract opportunities. However, the aggregate numbers only tell part of the story. The distribution of revenue across different launcher technologies, platforms, and geographic regions reveals where the true value lies and which segments are primed for disruption. Our full report dissects these segments without exposing the detailed figures here, inviting readers to access the complete dataset for precise benchmarking.
Technology Segmentation and Platform Integration
The market is characterized by a diverse array of launcher technologies, each suited to specific operational requirements and platform constraints. Pneumatic systems remain a dominant force, valued for their reliability and reloadability during flight operations. Gravity and rotary mechanisms offer alternative deployment profiles, while pyrotechnic solutions cater to specialized rapid-release scenarios. The choice of launcher type is inextricably linked to the host platform, whether it be a high-altitude maritime patrol aircraft, a low-and-slow ASW helicopter, or emerging unmanned aerial systems.
Platform integration is a key driver of demand. Maritime patrol aircraft continue to represent the largest share of deployment activity, given their endurance and sensor capacity. ASW helicopters provide essential low-altitude coverage, while unmanned aerial vehicles are increasingly being explored for expendable sensor delivery. Surface vessels also contribute to the ecosystem, albeit to a lesser extent in the airborne launcher context. The interplay between platform availability and launcher compatibility creates a complex matrix of requirements. Our report analyzes these dynamics in depth, evaluating how shifts in platform procurement—such as the continued acquisition of P-8A Poseidon aircraft or MH-60 helicopters—ripple through the launcher supply chain.
Competitive Landscape: Key Players and Strategic Positionings
The competitive environment is moderately concentrated, with a few major players commanding significant market share. This structure offers stability but also presents barriers to entry for smaller firms. The leading companies are not merely manufacturers; they are system integrators deeply embedded in naval aviation programs. Understanding their specific capabilities, recent contract wins, and technological roadmaps is essential for assessing supplier risk and partnership potential.
L3Harris Technologies stands out as a key contributor, designing and manufacturing pneumatic-powered sonobuoy launching systems. Their portfolio includes the Sonobuoy Rotary Launch System (SRL), capable of holding ten A-size sonobuoys with a launch capability every three seconds, and the Sonobuoy Single Launch System (SSL) for single A-, F-, or G-size units. These systems are reloadable in flight and suited for maritime patrol aircraft such as the P-8A. L3Harris maintains full-rate production and has a proven flight heritage. Recent developments, including a prominent contract award in December 2025 related to advanced systems and a sole-source contract in January 2024 for the P-8A Poseidon Sonobuoy Rotary Launcher Lower Tray Retrofit, highlight their entrenched position in critical U.S. Navy programs.
Ultra Maritime, based in the UK, provides sonobuoy systems and associated launcher technologies. They are actively developing next-generation multistatic sonobuoys compatible with existing naval launcher infrastructure, including P-8A platforms. In April 2026, Ultra Maritime was awarded a sole source firm-fixed-price contract for Low Rate Initial Production of AN/SSQ-125B sonobuoys, supporting integration with existing naval launcher systems. This contract underscores the ongoing relevance of launcher compatibility even as sonobuoy technology evolves.
Lockheed Martin remains involved in sonobuoy programs and upgrades to related launcher systems, such as the MK36 Super Hercules, to enhance performance and range in ASW applications. Thales Group develops multi-platform sonobuoy launchers adaptable to frigates, corvettes, and helicopters, alongside advanced sonobuoys like SonoFlash with extended detection range and multistatic capabilities. Sparton Corporation, now part of Elbit Systems, manufactures sonobuoys with extensive deployment history and supports associated launching systems for air-to-sea deployment.
Missile Decoy Launcher System Market
The market also includes specialized and niche players who offer tailored solutions. Alkan S.A. in France specializes in sonobuoy launcher solutions for naval and aircraft platforms. JSK Naval Support Inc. in Canada provides niche launcher solutions tailored to specific mission requirements and platform integration. Geospectrum Technologies Inc. focuses on launcher systems with an emphasis on acoustic technology and underwater surveillance. Marshall Aerospace and Defence Group delivers launch carousel assemblies and related components, while MES S.p.A. produces light stores dispensing units and composite launch tubes for sonobuoy and similar expendable stores.
Our report provides a detailed competitive benchmarking analysis, evaluating each firm's market share relative to the competitive landscape. The market concentration is significant, with the top three players holding a substantial portion of the revenue and the top five commanding a dominant share. This structure influences pricing power, supply chain resilience, and the pace of innovation. Stakeholders must understand these dynamics to negotiate effectively or identify potential gaps in the market for new entrants.
Industry Dynamics and Emerging Trends
Several macro trends and regulatory developments are reshaping the sonobuoy launcher market. The U.S. Navy's FY2026 budget continues to support sonobuoy programs across P-8, P-3, and H-60 platforms. There is a strong emphasis on maintaining a healthy industrial base through multiple qualified vendors for sonobuoy and associated launcher components. This policy environment favors established players while creating opportunities for secondary suppliers to qualify for niches.
Technological evolution is also a major driver. The integration of sonobuoy launchers with unmanned platforms is gaining traction. The U.S. Navy's SBIR Topic N251-016, released in December 2024, highlights the development of expendable sonobuoy-launched UAVs for ASW cued search from P-8A launcher infrastructure. This convergence of unmanned systems and traditional launcher architecture represents a frontier for innovation and potential market expansion. Additionally, raw material considerations remain relevant. Sonobuoy launch containers and related structures historically utilize aluminum cylinders and composite materials for launch tubes to achieve lightweight, durable performance under air-deployed conditions. Fluctuations in material costs or supply constraints can impact production timelines and pricing.
Geopolitical factors further influence demand. A rising focus on anti-submarine warfare capabilities drives demand for sonobuoy launchers in naval modernization programs, particularly in North America and allied nations operating P-8A and MH-60 platforms. Regional security concerns and the need to counter advanced submarine threats in key maritime corridors are prompting governments to invest in robust ASW architectures. These geopolitical currents ensure that demand for reliable launcher systems remains a priority for defense budgets globally.
Inside the Report: Operational Content and Analytical Tools
The Worldwide Sonobuoy Launcher Market report is structured to provide maximum utility for strategic planning. It goes beyond descriptive statistics to offer analytical frameworks that support decision-making. The report includes a comprehensive overview of the market ecosystem, covering definitions, scope, and key product classifications. It details the segmentation by region, type, and platform, allowing readers to isolate specific areas of interest.
A major component of the study is the competitive landscape analysis. Each key company is profiled with information on headquarters, product offerings, recent contract awards, and strategic initiatives. These profiles are supported by data on market share and concentration, providing context for competitive intensity. The report also examines the value chain, from raw material suppliers of aluminum and composites to the integrators and end-users within naval organizations.
Furthermore, the analysis incorporates a review of industry dynamics, including regulatory frameworks, technological trends, and macroeconomic factors. The historical data from 2020 to 2025 is presented to establish baselines, and the forecast data through 2032 offers a forward-looking perspective. Methodologies are clearly outlined to ensure transparency and reliability. Stakeholders can use this information to validate internal forecasts, identify supplier risks, and explore potential partnership opportunities.
Our research emphasizes actionable insights. For procurement professionals, the report highlights vendor capabilities and contract trends that can inform sourcing strategies. For investors, the growth projections and segment analysis help assess the viability of market entry or expansion. For defense planners, the technological and platform integration details support requirements definition and capability planning. The report is designed to be a reference tool that can be consulted repeatedly as the market evolves.
Strategic Recommendations for 2026 Decision-Makers
Based on the prevailing market signals, organizations should consider several strategic priorities. First, maintaining visibility into the status of key platform programs is essential. The P-8A Poseidon and H-60 helicopter fleets are central to launcher demand, and any changes in procurement rates or retrofit requirements will directly impact the market. Second, monitoring the progress of unmanned integration is critical. The potential for sonobuoy-launched UAVs could alter the requirements for launcher infrastructure and create new niches for specialized components. Third, supply chain resilience should be a focus. Given the concentration of the market and the emphasis on qualified vendors, ensuring access to reliable suppliers and understanding the material dependencies of launcher systems is vital for operational continuity.
Finally, stakeholders should engage with the full intelligence available in our research. While this introduction highlights the key themes, the detailed segmentation data, market size breakdowns, and competitive share analysis are available in the complete report. Access to this granular level of detail is necessary for precise valuation, risk assessment, and strategic positioning.
Conclusion: Accessing Comprehensive Market Intelligence
The Worldwide Sonobuoy Launcher Market is at a juncture where sustained growth meets technological evolution and shifting strategic priorities. The revenue trajectory, competitive concentration, and emerging trends all point to a market that is vital for modern naval capabilities. However, navigating this market requires more than a high-level overview. It demands deep, data-driven insights that reveal the nuances of segmentation, the specifics of vendor performance, and the probabilities of future growth.
PW Consulting's new market research report provides the depth and rigor required for informed decision-making in 2026. By combining historical analysis with forward-looking forecasts and detailed competitive profiling, the study offers a complete view of the landscape. We invite defense executives, strategic planners, and industry leaders to explore the full findings to unlock the intelligence needed to drive success. The complete dataset, including regional and segment-specific figures, is available for download. Access the source webpage today to obtain the full report and ensure your organization is equipped with the insights necessary to thrive in this dynamic market.
For detailed analysis of this topic, please visit the official page: Worldwide Sonobuoy Launcher Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com