

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Ultrasonic Probe Covers Market Hits $229.7M in 2025, Growing at 6.5% CAGR to 2032

Strategic Horizons: Navigating the Global Ultrasonic Probe Covers Market in 2026
The global healthcare landscape is undergoing a rapid transformation, driven by an aging population, increased prevalence of chronic diseases, and a heightened focus on patient safety and infection control. Within this complex ecosystem, the ultrasonic probe covers market stands as a critical niche, bridging the gap between diagnostic precision and clinical safety. As we move into 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for stakeholders ranging from medical device manufacturers to hospital procurement officers.
PW Consulting's latest Worldwide Ultrasonic Probe Covers Market study offers a comprehensive lens into this vital sector. This research is designed to equip decision-makers with the foresight needed to navigate upcoming challenges and capitalize on emerging opportunities. By analyzing historical performance and projecting future trends through 2032, this report serves as an essential roadmap for strategic planning in a regulated and competitive environment.
Macroeconomic Trajectory and Market Growth
The fundamental story of the ultrasonic probe covers market is one of steady, resilient expansion. Our analysis tracks revenue performance from the base year of 2025 back through 2020, providing a robust historical context before forecasting growth patterns into the next decade. The data indicates a consistent upward trajectory, reflecting the indispensable nature of these devices in modern medical imaging.
In 2020, the global market generated approximately 168.45 million USD. This figure experienced a notable acceleration over the following years, reaching 195.57 million USD in 2022 and surpassing 211.69 million USD in 2023. The momentum continued into the mid-2020s, with the market size reaching 229.01 million USD in 2024 and stabilizing at 229.72 million USD in 2025. Looking forward, the forecast period from 2026 to 2032 suggests sustained growth, with projected revenues climbing to 254.36 million USD in 2026. By the end of the forecast window in 2032, the market is anticipated to reach 356.99 million USD.
This expansion corresponds to a Compound Annual Growth Rate (CAGR) of 6.5 percent over the forecast period. For corporate strategists, this rate signals a healthy market environment that outpaces inflation and offers viable returns on investment. However, the path is not linear. Slight fluctuations are observable, such as the marginal adjustment between 2026 and 2027, which underscores the need for agile planning and sensitivity to external economic shocks. The overall value pool expanding from roughly 229 million USD to over 356 million USD represents a significant opportunity for value capture over the next seven years.
Product Segmentation and Material Innovation
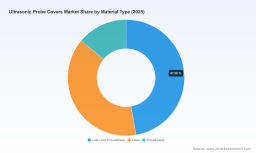
Understanding where value is generated within the market requires a deep dive into product segmentation. The market is primarily categorized by material type, reflecting the evolving priorities of clinicians and patients regarding safety and performance. The shift away from traditional materials toward advanced synthetics is a defining trend of this era.
Latex-free polyurethane has emerged as a dominant category, representing the largest share of market revenue. This preference is driven by the increasing awareness of latex allergies and the demand for higher biocompatibility. Medical-grade polyethylene also constitutes a significant portion of the landscape, offering clarity and durability. Traditional latex products maintain a presence but face headwinds from regulatory pressures and patient safety advocacy. Polyethylene covers serve as a cost-effective alternative in specific applications where extreme flexibility is less critical.
The material choice is not merely a preference but often a clinical requirement. As noted in industry guidelines, latex-free probe covers utilize medical-grade polyethylene or polyurethane films to ensure biocompatibility and optical clarity. This alignment between material science and clinical need creates a sticky demand curve that favors suppliers with robust R&D capabilities. Manufacturers who can innovate in material thickness, tactile sensitivity, and tear resistance will find themselves well-positioned to capture premium segments of the market.
Clinical Applications and Demand Drivers
The demand for ultrasonic probe covers is inextricably linked to the utilization rates of ultrasound procedures across various medical specialties. Our analysis breaks down consumption by application, revealing where the highest volume and value reside.
Obstetrics and Gynecology remains the cornerstone application for this market. The high frequency of transvaginal and transabdominal scans in prenatal care and reproductive health drives substantial volume. Given the invasive nature of many OB/GYN procedures, the requirement for sterile barriers is non-negotiable, ensuring a stable baseline demand. Radiology represents another major pillar, encompassing a broad range of diagnostic imaging scenarios where probe covers protect both the patient and the expensive transducer equipment.
Cardiology is also a significant contributor, particularly with the use of transesophageal echocardiography (TEE) probes which require specialized sheaths. Urology and Surgery and Vascular applications round out the key segments, each with specific requirements for sheath length, diameter, and lubrication. The diversity of applications suggests that no single clinical discipline dictates the entire market rhythm; rather, it is a composite of multiple healthcare workflows. CDC guidelines recommend disposable probe covers for all endocavitary ultrasound to reduce healthcare-associated infections, reinforcing the clinical mandate behind the market demand.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established players and specialized manufacturers. Concentration metrics indicate a moderately consolidated environment. The top three companies hold a combined market share of 42.15 percent, while the top five entities control 58.6 percent. This concentration suggests that while there is room for niche players, scale and distribution networks provide a distinct advantage for the market leaders.
Several key companies define the current competitive arena. CIVCO Medical Solutions, based in Coralville, IA, USA, is a prominent provider of both sterile and non-sterile disposable ultrasound probe covers. Their portfolio includes endocavity sheaths and general imaging covers compatible with major ultrasound systems. Recently, CIVCO exhibited an expanded probe cover portfolio at RSNA 2024, highlighting sterile endocavity sheaths, signaling their commitment to product expansion and visibility in key trade forums.
Parker Laboratories, located in Fairfield, NJ, USA, manufactures the Incognito probe covers and sheaths for ultrasound transducers. Their strategy emphasizes gel-free and low-profile designs aimed at enhancing infection control and user convenience. Kentec Medical, based in Bicester, Oxfordshire, UK, produces sterile single-use probe sheaths for endocavity ultrasound probes. Their focus on compliance with EU MDR and worldwide availability highlights the importance of regulatory alignment in global markets.
Sunray Medical, headquartered in Edison, NJ, USA, offers a range of ultrasound probe covers including clear-view and endovaginal types, all FDA cleared for medical use. This regulatory clearance is a critical barrier to entry and a trust signal for purchasers. ImaX Medical, based in Montreal, QC, Canada, supplies disposable probe covers for ultrasound and TEE probes, focusing on high-clarity materials for imaging. This focus on optical properties addresses the diagnostic quality concerns that sometimes arise with barrier use.
Strategic interactions among these players often occur through trade shows and product launches rather than aggressive price wars. The recent activity by CIVCO at RSNA 2024 exemplifies how companies use major industry events to showcase expanded portfolios. For new entrants or existing players looking to gain share, the competitive strategy likely hinges on regulatory compliance, material innovation, and supply chain reliability rather than volume discounting alone.
Regulatory and Reimbursement Dynamics
The operational environment for ultrasonic probe covers is heavily influenced by regulatory frameworks and reimbursement structures. These invisible forces shape product design, pricing strategies, and market access.
In terms of regulation, ultrasound probe covers are classified as Class I exempt or Class II devices requiring 510(k) clearance if sterile. This classification dictates the pathway to market. Sterile probe covers must meet ISO 11607 for packaging and ISO 11135/11137 for ethylene oxide or radiation sterilization. Compliance with these standards is not optional; it is a prerequisite for hospital procurement. The complexity of maintaining sterilization compliance across different geographic regions adds a layer of operational cost and risk that must be factored into strategic planning.
Medical Ultrasound Probe Market
Reimbursement presents a different set of challenges. There is no dedicated HCPCS code for probe covers. Instead, costs are bundled into ultrasound CPT codes such as 76817 for transvaginal procedures. This bundling means that the economic value of the probe cover is often indirect, tied to the reimbursement of the procedure itself. For providers, this can influence purchasing decisions, prioritizing cost-effective solutions that do not jeopardize procedural reimbursement rates. For manufacturers, it means that demonstrating value in terms of infection reduction or equipment protection is crucial, as the direct cost is absorbed into a broader billing code.
Worldwide Ultrasonic Probe Covers Market
Strategic Implications for 2026 Decision Makers
As we look toward 2026, the intersection of market growth, regulatory rigor, and competitive dynamics creates a specific set of strategic imperatives. The projected 6.5 percent CAGR suggests that growth is achievable, but capturing it requires precision.
First, supply chain resilience is paramount. With market concentration indicating that top players hold significant sway, smaller distributors or manufacturers must ensure they have differentiated value propositions. This could come in the form of specialized materials, faster turnaround times, or superior regulatory support. Second, infection control remains a primary driver. With CDC recommendations reinforcing the use of disposable covers for endocavitary ultrasound, the clinical argument for these products is strong. Marketing and sales efforts should align with these safety guidelines to reinforce necessity.
Third, regional nuances matter. While global aggregate data shows growth, the distribution of revenue across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa varies significantly in terms of regulatory maturity and procurement practices. North America and Europe represent large, established markets with strict compliance requirements. Asia Pacific offers volume potential with evolving standards. Understanding these regional textures is essential for market entry or expansion strategies.
Finally, the bundling of costs into CPT codes necessitates a sharp focus on total cost of ownership. Hospitals are likely to evaluate probe covers not just on unit price but on their contribution to workflow efficiency and infection prevention. Suppliers who can articulate this broader value proposition will find greater success in tenders and contract negotiations.
Conclusion: The Value of Comprehensive Intelligence
The Worldwide Ultrasonic Probe Covers Market is at an inflection point where clinical necessity, regulatory complexity, and economic opportunity converge. The data points to a market growing from approximately 229 million USD in 2025 to nearly 357 million USD by 2032. Yet, these top-line numbers only tell part of the story. The real strategic value lies in understanding the segmentation dynamics, the competitive maneuvers of key players like CIVCO and Parker Laboratories, and the regulatory hurdles that define market access.
PW Consulting's full market study delves deeper into these areas, providing granular data on regional splits, material type breakdowns, and application-specific revenue streams that are not fully disclosed in this overview. For executives planning product launches, M&A activity, or market entry strategies in 2026, access to this level of detail is indispensable. The macroeconomic trends are clear, but the microeconomic opportunities require precise navigation.
We invite industry leaders to explore the complete findings of the Worldwide Ultrasonic Probe Covers Market report. By leveraging the full scope of our research, you can transform high-level insights into actionable strategies that drive growth and ensure compliance in a rapidly evolving healthcare environment. The path to 2032 is clear, but the steps to get there require the right intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Ultrasonic Probe Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com