

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Wearable Inertial Sensors Market Hits $1.45B in 2025, Projected to Reach $3.41B by 2032

Global Wearable Inertial Sensors Market: Strategic Intelligence for 2026 and Beyond
The wearable technology landscape has transcended novelty to become a foundational layer of modern digital interaction, health monitoring, and industrial efficiency. At the heart of this transformation lies the inertial sensor ecosystem, a critical component enabling motion tracking, gesture recognition, and spatial orientation across millions of devices worldwide. Our latest comprehensive analysis, the Worldwide Wearable Inertial Sensors Market study, provides an exhaustive examination of this rapidly evolving sector. As we move through 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for stakeholders ranging from semiconductor manufacturers to healthcare providers and consumer electronics giants.
This report serves as a definitive guide for decision-makers navigating the complexities of inertial sensing technology. By integrating historical performance data with forward-looking projections, we offer a roadmap that illuminates growth vectors, competitive pressures, and regulatory shifts. The following insights distill the core findings of our research, highlighting why this intelligence is essential for crafting resilient strategies in the coming years.
Market Trajectory and Growth Dynamics
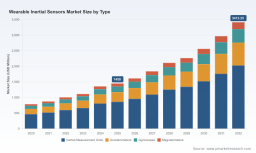
The global market for wearable inertial sensors has demonstrated remarkable resilience and expansion over the past half-decade. Historical analysis from 2020 through 2025 reveals a consistent upward trend, driven by the proliferation of smart wearables, advancements in sensor miniaturization, and increasing adoption in professional healthcare settings. In 2020, the market generated revenue of approximately 785.4 million USD. By the base year of 2025, this figure has escalated to 1,450.0 million USD, reflecting a compound annual growth rate that underscores the sector's vitality.
Looking forward, the forecast period spanning 2026 to 2032 indicates sustained momentum. Projections suggest that revenue will climb to 1,612.63 million USD in 2026, continuing its ascent to reach 3,413.25 million USD by 2032. This trajectory corresponds to a forecast CAGR of 13.01 percent, signaling that demand will outpace many traditional electronics segments. Such growth is underpinned by the convergence of consumer lifestyle changes and industrial digitallization. The expansion is not uniform; rather, it is fueled by specific technological breakthroughs and shifting application priorities that our report dissect in granular detail.
For enterprise strategists, these macro figures provide a baseline for capacity planning and investment allocation. However, the true value lies in understanding the drivers behind these numbers. The transition from basic step counting to complex motion analysis, coupled with the integration of artificial intelligence at the edge, is reshaping value chains. Our analysis delves into how these factors interact to create both opportunities and vulnerabilities for market participants.
Technology Segmentation and Hardware Foundations
The market is structurally divided by sensor type, with Inertial Measurement Units (IMUs) commanding the largest share of revenue. IMUs represent the cornerstone of modern wearable functionality, combining accelerometers, gyroscopes, and magnetometers to deliver comprehensive motion data. While standalone accelerometers and gyroscopes maintain significant presence, particularly in cost-sensitive consumer applications, the trend is overwhelmingly toward integrated solutions. Magnetometers, though smaller in revenue contribution, play a crucial role in orientation and compass-based applications, completing the sensor fusion ecosystem.
A critical theme emerging in our analysis is the dominance of MEMS-based inertial sensors supplied by major component manufacturers. Companies such as Bosch Sensortec, STMicroelectronics, and TDK InvenSense form the core hardware backbone for most wearable IMUs. Their collective focus on low power consumption and compact form factors has been instrumental in enabling the next generation of hearables, fitness trackers, and medical patches. The shift toward embedding AI processing directly within these sensors, exemplified by recent product launches like the LSM6DSV320X, marks a pivotal shift. This allows for on-device activity tracking and high-g impact measurements without relying heavily on cloud connectivity, enhancing privacy and responsiveness.
Precision remains a key differentiator, particularly for high-accuracy applications. Analog Devices, Inc. continues to develop precision inertial measurement units suitable for demanding wearable motion tracking scenarios. Meanwhile, specialized players like 2M Engineering supply wireless high-fidelity IMU motion sensing platforms tailored for researchers and OEM integration. Understanding the technological hierarchy and the specific strengths of these hardware providers is essential for supply chain optimization and product development roadmaps.
Application Verticals and Value Creation
Revenue distribution across application segments highlights the diverse utility of inertial sensors. Consumer electronics remains the largest application vertical, driven by the ubiquitous presence of smartphones, smartwatches, and fitness bands. The demand here is characterized by volume and the need for cost-effective, reliable motion sensing that supports gesture control, screen orientation, and activity monitoring.
Healthcare and medical applications represent a rapidly growing segment, valued significantly within the market structure. The integration of inertial sensors into clinical gait analysis, rehabilitation monitoring, and remote patient monitoring systems is transforming care delivery. Companies like Movella Inc. (Xsens) specialize in wearable inertial sensor systems for motion capture and biomechanics research, while Shimmer Sensing offers Verisense IMU sensors with prior CE Class I medical device certification for clinical research. These tools enable real-world movement analysis that was previously confined to laboratory settings.
Additional growth is evident in AR and VR systems, where precise head and hand tracking is essential for immersive experiences, as well as in sports and fitness training, where performance metrics drive user engagement. The ability to capture nuanced biomechanical data allows for personalized training regimens and injury prevention strategies. Our report explores how these verticals are evolving and where the highest margin opportunities exist for solution providers.
Worldwide Wearable Inertial Sensors Market
Competitive Landscape and Strategic Positioning
The market exhibits a moderate level of concentration, with the top three companies accounting for over 58 percent of the market share and the top five firms holding approximately 74 percent. This concentration indicates that while there is room for niche players, scale and technological leadership provide significant advantages. Key competitors include Bosch Sensortec GmbH, headquartered in Germany, which offers low-power smart IMUs such as the BMI270 and BMI570 optimized for wearables and gesture recognition. STMicroelectronics, based in Switzerland and France, supplies MEMS inertial sensors with embedded AI processing capabilities. TDK InvenSense, operating out of the United States, provides high-performance MEMS IMUs widely integrated into wearables and smartphones.
The competitive dynamics are further shaped by specialized firms focusing on medical and research-grade applications. Noraxon USA Inc. provides wearable inertial sensors and EMG-integrated systems for biomechanical and clinical gait analysis. BTS Bioengineering develops the G-WALK wearable inertial sensor for functional motion analysis worn around the waist. ActiGraph LLC focuses on physical activity monitoring and clinical research applications. Additionally, 221e develops miniaturized medical-grade wireless wearable IMU sensors with embedded AI for neurorehabilitation. These companies illustrate the bifurcation between mass-market component suppliers and specialized solution providers targeting high-value niches.
Recent developments underscore the pace of innovation. In May 2025, STMicroelectronics launched the LSM6DSV320X inertial measurement unit with embedded AI processing for activity tracking and high-g impact measurements. More recently, in April 2026, Wearable Devices Ltd. received a USPTO Notice of Allowance for a continuation patent covering biometric user authentication using gesture and biopotential sensors in touchless wearable interface devices. Such milestones signal the increasing sophistication of the intellectual property landscape and the convergence of security, biometrics, and motion sensing.
Regulatory Environment and Standardization
Navigating the regulatory landscape is a critical component of market strategy, particularly for entities operating in the healthcare sphere. The FDA maintains a public database of authorized sensor-based digital health technology medical devices, including non-invasive wearables such as smartwatches and patches that incorporate inertial sensors. In January 2026, the FDA issued guidance limiting regulation of low-risk non-medical grade wearable fitness devices promoting general wellness, while maintaining oversight for devices making medical claims. This distinction creates a clear pathway for consumer wellness products while imposing stricter requirements on those seeking diagnostic or therapeutic validation.
In Europe, wearable medical devices incorporating sensors are subject to the EU Medical Device Regulation (MDR) 2017/745 risk classification, alongside IEC 60601 for electrical safety, ISO 14971 for risk management, and ISO 13485 for quality management systems. Compliance with these frameworks is non-negotiable for market access in the region. Standardization efforts also play a role, as evidenced by Shimmer Research's Verisense IMU sensor receiving CE certification as a Class I medical device. These regulatory milestones not only validate specific products but also set benchmarks for the industry, influencing design choices and certification strategies for new entrants.
Strategic Imperatives for 2026 Decision-Making
As organizations formulate their strategies for the remainder of the decade, several key imperatives emerge from our analysis. First, supply chain resilience must be prioritized. Given the concentration of key component suppliers, diversification and strategic partnerships are essential to mitigate risk. Second, the integration of edge AI into sensor hardware represents a significant value-add opportunity. Products that can process motion data locally offer advantages in latency, privacy, and battery life, aligning with consumer and industrial expectations.
Third, the regulatory environment demands proactive compliance strategies. Companies aiming to capture the healthcare segment must invest early in the certification processes required by FDA and EU MDR frameworks. Conversely, those focusing on the wellness segment should leverage the favorable guidance for low-risk devices to accelerate time-to-market. Finally, geographic expansion strategies should consider the varying maturity levels of regional markets. While North America and Asia Pacific represent significant revenue bases, emerging regions offer untapped potential for targeted interventions.
The Worldwide Wearable Inertial Sensors Market report provides the detailed segmentation data, regional breakdowns, and competitor profiles necessary to execute these strategies with precision. By accessing the full intelligence contained within this study, stakeholders can move beyond high-level trends to actionable insights that drive competitive advantage.
Worldwide Automotive Inertial Systems Market
Conclusion
The wearable inertial sensors market stands at a pivotal juncture, characterized by robust growth, technological innovation, and evolving regulatory standards. The projected expansion from 1,450.0 million USD in 2025 to over 3,413.25 million USD by 2032 reflects the deepening integration of motion sensing into everyday life and professional applications. For leaders in this space, the ability to interpret these dynamics accurately is the difference between leading the market and reacting to it.
Our comprehensive study offers the depth and clarity required to navigate this complex environment. We invite you to explore the full report to access the complete dataset, including detailed segmentation splits by type, application, and region, as well as in-depth profiles of all key market players. Equip your organization with the intelligence needed to capitalize on the opportunities defining the future of wearable inertial sensing.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Inertial Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com