

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Benign Positional Vertigo Market to Hit $1,427.97M by 2032 at 5.38% CAGR

Navigating the Global Benign Positional Vertigo Treatment Market: Strategic Intelligence for 2026 and Beyond
The worldwide market for benign positional vertigo treatment is undergoing a structural transformation driven by aging demographics, diagnostic standardization, and a shift toward minimally invasive and home-based care pathways. For healthcare manufacturers, service providers, and investors, 2026 represents a pivotal decision window. Demand is no longer growing uniformly; it is concentrating around specific treatment modalities, clinical settings, and regional reimbursement environments. PW Consulting's latest market intelligence study maps these shifts with granular precision, converting historical trajectories and forecast pathways into actionable strategic guidance for enterprise planning, product positioning, and capital allocation.
This introduction serves as a strategic preview of the study's architecture, analytical rigor, and competitive relevance. It highlights the macro momentum shaping the sector, outlines the operational dimensions covered in the full report, and frames the competitive landscape through the lens of recent product, certification, and launch activity. The intent is to demonstrate the depth of intelligence available while reserving the most decisive segment-level and regional breakdowns for the complete publication, ensuring that decision-makers gain a credible foundation before committing to detailed procurement or investment analysis.
Market Trajectory and the 2026 Decision Window
Benign positional vertigo treatment has evolved from a fragmented clinical niche into a structured market defined by repeatable diagnostic protocols, standardized repositioning maneuvers, and growing reimbursement familiarity. Historical revenue data from 2020 through 2025 shows a steady climb, reflecting broader adoption of vestibular assessment practices, increased clinical recognition of canalith repositioning efficacy, and expanding distribution of specialized devices. The market reached an estimated 989.49 million USD by the 2025 base year, building on a consistent upward path from earlier periods.
The forecast horizon from 2026 to 2032 introduces a nuanced outlook. While the sector continues to expand at a projected compound annual growth rate of 5.38 percent, the trajectory is not linear. 2026 marks a transitional year in which certain demand patterns recalibrate as providers optimize clinical workflows, payers refine coverage expectations, and manufacturers align product roadmaps with emerging safety and usability requirements. Beyond that point, the market reaccelerates through 2032, with revenue approaching 1.43 billion USD. This shape of the curve matters for strategy: it signals that short-term planning must account for near-term stabilization, while medium-term planning should prepare for renewed volume growth tied to broader clinical adoption and device deployment.
For executives, this trajectory has three immediate implications. First, capacity and inventory decisions should be timed against the 2026 inflection rather than assumed continuous acceleration. Second, product portfolios should emphasize modalities that align with durable clinical workflows, particularly repositioning-based interventions and diagnostic verification tools. Third, regional and channel strategies must be calibrated to local reimbursement realities, because growth is not distributed evenly across care settings or geographic markets. The full study quantifies these dynamics without oversimplifying them, helping leadership avoid over-indexing on headline growth while still capturing the underlying expansion opportunity.
What the Study Delivers: Operational Intelligence for Strategy Teams
The complete market research is built for practical use. It translates high-level trends into structured frameworks that strategy, commercial, and clinical-operations teams can apply directly. The report moves beyond descriptive market sizing to examine how value is created, captured, and contested across treatment pathways, end-user settings, and regulatory environments.
Core components of the study include:
- A historical reconstruction of market revenue from 2020 through 2025, establishing a verified baseline for demand growth, adoption timing, and post-pandemic clinical normalization.
- A forward-looking forecast spanning 2026 to 2032 that isolates the pace of expansion while accounting for modality mix shifts, diagnostic verification needs, and care-setting preferences.
- A segmentation architecture that evaluates treatment types, end-user environments, and regional demand patterns, with emphasis on where adoption is consolidating and where whitespace remains.
- A competitive landscape assessment centered on device manufacturers and diagnostic solution providers that shape procurement choices, clinical workflow design, and channel access.
- An analysis of industry dynamics including regulatory classification requirements, reimbursement behavior, input cost pressures, and clinical practice standards that influence margin structures and product planning.
Each section is designed to support decision-making rather than simply describe the market. The study provides the context needed to evaluate product launch timing, distribution strategy, partnership targeting, and capital deployment. Critically, it also identifies where surface-level data can mislead. For example, total market growth can obscure the fact that certain treatment categories and care settings are carrying more weight than others, and regional performance can differ sharply depending on reimbursement familiarity and clinical workflow maturity. The full report preserves these distinctions so that users can act on differentiated insight rather than aggregate averages.
Competitive Landscape and Recent Industry Activity
The benign positional vertigo treatment market is defined by a compact set of specialist companies that compete across diagnostic verification, repositioning equipment, and supportive vestibular rehabilitation tools. Market concentration reflects this specialization. The top three participants account for approximately 34.25 percent of revenue, while the top five reach roughly 48.6 percent. This level of concentration indicates that incumbents hold meaningful advantages in clinical acceptance, channel relationships, and regulatory familiarity, but it also leaves room for targeted challengers that can differentiate through usability, portability, or workflow integration.
Several companies illustrate the strategic contours of the sector. Entellus Medical, now operating within Stryker, provides sinus dilation and ENT device platforms used in minimally invasive procedures related to repositioning maneuvers for BPPV treatment. Its recent system update in October 2024 introduced enhanced navigation capabilities for BPPV-related sinus interventions, signaling a continued push toward procedural precision and clinician-oriented device refinement. Interacoustics, based in Denmark, offers diagnostic and repositioning solutions such as the TRV Reposition Chair and video goggles used for Epley and other canalith repositioning maneuvers. In June 2024, the company secured CE Mark renewal for its reposition chair with improved patient safety features, reinforcing the importance of certified safety performance in European clinical procurement. Natus Medical, now Natus Neurology, supplies vHIT systems and videonystagmography equipment essential for diagnosis and treatment verification. Its November 2023 launch of a next-generation vHIT ultra system emphasized precise canal identification and treatment monitoring, reflecting a broader focus on diagnostic confidence as a value driver.
The landscape also includes companies extending care beyond the clinic. Bernafon, part of WS Audiology, produces vestibular testing and rehabilitation devices that support particle repositioning therapy, contributing to integrated assessment-to-rehabilitation workflows. Beurer GmbH, based in Germany, manufactures portable Epley maneuver devices and home-use vertigo treatment kits, illustrating the market's gradual expansion into patient-directed and home-care settings. These differing product philosophies matter because they address distinct purchasing drivers: hospitals and ENT clinics prioritize diagnostic certainty and procedural control, while home healthcare and physical therapy channels prioritize ease of use, training burden, and cost-effective deployment.
Competitive strategy in this market is increasingly shaped by more than product features alone. Device classification requirements influence time-to-market and compliance costs. Reimbursement norms affect procedure economics and provider adoption. Input cost volatility affects margin stability for device manufacturers. The study integrates these forces to show how competitive advantage is being constructed in practice, not just in product spec sheets. By connecting recent developments to the structural conditions that shape purchasing behavior, the report helps executives anticipate where incumbents may reinforce their positions and where new entrants or adjacent solutions could gain traction.
Market Dynamics Shaping Strategy in 2026
Beyond sizing and segmentation, the market is being shaped by a set of operational and regulatory dynamics that directly influence commercial planning. One important factor is the regulatory classification environment. In the United States, BPPV treatment devices are classified as Class II, and diagnostic videonystagmography systems as well as repositioning chairs require 510(k) clearance. This classification framework affects development timelines, evidence requirements, and the compliance burden for new entrants, while also reinforcing the position of established manufacturers with existing clearance pathways and clinical validation histories.
Reimbursement behavior is another decisive dynamic. Under Medicare Part B, the canalith repositioning procedure is reimbursed at an average of about 150 USD per session, creating a recognizable procedure economics baseline for providers. At the same time, ENT specialist reimbursement for BPPV treatments in U.S. ambulatory settings averages between 250 and 400 USD per procedure. This gap between device-supported procedure reimbursement and specialist reimbursement influences adoption decisions, service pricing, and the economic justification for investing in specialized diagnostic and repositioning equipment. Providers weigh not only clinical outcomes but also workflow efficiency and revenue realization, which means product value propositions must align with operational and financial realities, not clinical preference alone.
Input costs add a further layer of strategic relevance. Medical-grade silicone used in BPPV maneuver devices has experienced price increases in the range of 15 to 20 percent due to supply chain constraints on polymer resins. For device manufacturers and private-label producers, this creates margin pressure and procurement timing considerations. It also rewards companies that can engineer material efficiency, secure stable sourcing, or offer product designs that reduce dependency on volatile inputs. In a market where many offerings are highly specialized, even modest cost changes can affect pricing strategy and competitive positioning.
Clinical standards further constrain and shape the market. Current practice guidance does not support systemic drug therapies for BPPV; treatment remains centered on physical maneuvers and supportive vestibular rehabilitation. This reality reinforces the centrality of mechanical repositioning, diagnostic verification, and rehabilitation-focused solutions. It also means that product innovation is most durable when it improves maneuver accuracy, patient safety, clinician workflow, or home-based adherence rather than pursuing pharmacological substitution. For strategy teams, this is a critical framing device: the market's growth is tied to better execution of established non-pharmacological care, not to a shift in therapeutic class.
Worldwide Scoliosis Treatment Market
Strategic Implications for 2026 Planning
The intersection of demand trajectory, competitive concentration, regulatory classification, reimbursement patterns, and input cost pressure creates a clear strategic mandate for 2026. Companies should treat the market as a portfolio of distinct opportunities rather than a single growth story. Priorities differ by position in the value chain, but several themes apply broadly.
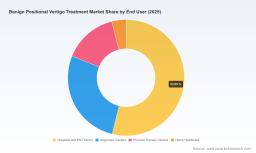
First, product and service strategies should be anchored in the care settings where adoption is most durable. Hospitals and ENT clinics continue to represent a major share of activity because they combine diagnostic capability, procedural volume, and reimbursement familiarity. Diagnostic centers and physical therapy centers contribute significant additional demand by supporting assessment and rehabilitation functions. Home healthcare remains smaller but strategically important as a channel for portable devices and patient-directed kits. Understanding the relative weight and growth behavior of each setting is essential for channel design, training investment, and pricing architecture.
Second, competitive positioning should account for the difference between diagnostic confidence and procedural utility. Some solutions win by strengthening diagnosis and treatment verification, reducing uncertainty in canal identification and repositioning outcomes. Others win by improving the practical execution of maneuvers, patient safety, or portability. The most resilient portfolios often combine both logic streams, either through internal product breadth or through partnership ecosystems. The report's competitive analysis helps identify where these value propositions are being built and where gaps remain.
Third, regional strategy should be informed by local reimbursement and clinical workflow maturity rather than assumed transferability. Demand behavior varies across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, and the full study preserves the regional distinctions that matter for market entry, distribution design, and resource allocation. Aggregate market size can suggest opportunity, but regional insight determines whether that opportunity is accessible, scalable, and economically viable in practice.
Conclusion: Why This Study Matters for Decision-Makers
The benign positional vertigo treatment market is expanding, but its value is being allocated through a complex mix of clinical standards, reimbursement logic, device regulation, and competitive specialization. That makes 2026 a year for disciplined strategy rather than broad assumptions. PW Consulting's Worldwide Benign Positional Vertigo Treatment Market study is designed to give executives the structured intelligence required to navigate that complexity with confidence.
The report provides the full historical baseline, the forecast pathway through 2032, the segmentation detail needed to prioritize modalities and channels, and the competitive context required to interpret recent product and certification activity. More importantly, it connects those data layers to the operational realities that shape adoption and margin performance. For teams evaluating product roadmaps, geographic expansion, partnership opportunities, or investment timing, this study converts market momentum into a usable strategic map.
The detailed segment-level and regional results are reserved for the full publication, where they can be examined in the depth they require. For decision-makers who need to move from awareness to action, that is where the decisive intelligence lives.
Worldwide Benign Positional Vertigo Treatment Market
For detailed analysis of this topic, please visit the official page: Worldwide Benign Positional Vertigo Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com