

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Commercial Vehicle Power Steering Pump Market to Grow 5.85% CAGR to $8,084.85M by 2032
By pmarketresearch, 2026-09-16
Navigating the Shift: Why the Commercial Vehicle Power Steering Pump Market Demands Strategic Attention in 2026
The commercial vehicle landscape is undergoing a quiet but decisive transformation. Where brute mechanical force once dictated steering architecture, today’s OEMs are prioritizing energy efficiency, electronic integration, and compliance with tightening emissions mandates. At the center of this evolution sits the power steering pump—a component that has transitioned from a standard hydraulic accessory to a strategic node in vehicle dynamics, fuel economy, and electro hydraulic system architecture. For supply chain leaders, mobility investors, and tier-one strategists, understanding where this market is heading is no longer optional. It is a prerequisite for positioning ahead of the 2026–2032 cycle.
Our newly released Commercial Vehicle Power Steering Pump Market study delivers a structured, decision-ready view of this landscape. Rather than offering a static snapshot, the analysis is built to support scenario planning, portfolio evaluation, and competitive positioning as the sector moves through its next phase of consolidation and technology migration.
A Market Built on Measured Growth and Functional Transition
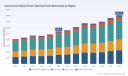
The commercial vehicle power steering pump market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately USD 4.1 billion in 2020 to an estimated USD 5.4 billion in 2025. That trajectory reflects more than volume growth; it signals a structural shift in how commercial fleets balance performance, operating cost, and regulatory exposure. Looking forward, the market is projected to advance at a compound annual growth rate of 5.85 percent across the 2026–2032 forecast horizon, reaching a valuation close to USD 8.1 billion by 2032.
Commercial Vehicle Power Steering Pump Market
This pace is neither explosive nor incremental in a vacuum. It is shaped by overlapping forces: the continued deployment of medium and heavy commercial platforms, the gradual substitution of traditional hydraulic assemblies with electro hydraulic and variable-displacement alternatives, and the pressure on manufacturers to reduce parasitic engine loads without compromising steering feel or safety. For decision-makers, the implication is clear. Growth in this segment will increasingly reward players who can align product roadmaps with efficiency benchmarks, electronics readiness, and regional compliance requirements rather than those who compete solely on volume or legacy supplier relationships.
What the Study Delivers: An Operational Lens on a Complex Ecosystem
The report is designed as a working reference for teams that need to translate market signals into sourcing, R&D, pricing, and partnership decisions. It combines historical reconstruction with forward-looking scenario analysis, giving readers a base year of 2025 and a forecast window extending through 2032. The structure supports both strategic overview and tactical interrogation, allowing users to examine demand drivers, product migration paths, and the competitive mechanics that shape supplier leverage.
Key analytical dimensions include:
Worldwide Automotive Power Steering Market
- Demand architecture across commercial vehicle segments , examining how light commercial vehicles, heavy commercial trucks, and buses/coaches place different performance, durability, and packaging requirements on steering pump systems.
- Product-type evolution , contrasting conventional hydraulic power steering pumps with electro hydraulic variants as OEMs pursue energy recovery, power-on-demand functionality, and reduced idle load.
- Regional demand distribution , mapping how mature commercial vehicle markets and high-volume manufacturing corridors differ in adoption timing, procurement behavior, and technology acceptance.
- Competitive intensity and supplier positioning , evaluating concentration patterns, differentiation levers, and the strategic moves that define current market leadership.
- Input cost and regulatory sensitivity , assessing how metal pricing volatility and emissions-driven mandates alter cost structures and accelerate the case for more efficient steering architectures.
- Recent product and technology milestones , capturing the launches, showcases, and system-level innovations that indicate where incumbent suppliers are placing their bets.
Each section is built to be actionable. Historical series provide a calibration baseline. Forecast logic ties together vehicle production assumptions, component substitution trends, and efficiency requirements. Competitive profiling goes beyond nameplate recognition to examine how suppliers are structuring their portfolios for medium and heavy commercial applications. The result is a research instrument that can support procurement hedging, engineering prioritization, M&A screening, and regional entry planning without requiring the reader to assemble disparate data points from multiple sources.
Competitive Landscape: Concentration, Differentiation, and the Push Toward Efficiency
The commercial vehicle power steering pump space is not a fragmented commodity market. It is a concentrated arena where technical differentiation, application expertise, and integration capability determine bargaining power. Current market concentration indicators point to a moderately consolidated environment, with the leading trio of suppliers accounting for a substantial share of revenue and the top five players extending that footprint further. In practical terms, this means scale, portfolio breadth, and proximity to OEM platform decisions still matter enormously.
Several established players illustrate the strategic directions shaping the segment. German suppliers continue to reinforce the link between steering hydraulics and vehicle-level efficiency. Bosch has built a recognizable position around hydraulic and electro hydraulic power steering systems for medium and heavy commercial vehicles, including variable displacement pump technology designed to reduce consumption. Its recent showcasing of a fourth-generation electro hydraulic steering system for commercial trucks—emphasizing ADAS compatibility and power-on-demand operation—signals a clear move toward steering architectures that interact more closely with advanced driver assistance and electronic control layers. Earlier presentations of electro hydraulic generations for heavy vehicles, with production timing aligned to the mid-2024 cycle, reinforce a sustained push into more integrated steering solutions.
ZF Friedrichshafen AG occupies a similarly influential position, offering ball-and-nut power steering systems and energy-efficient hydraulic pump variants alongside advanced electro hydraulic options for trucks and buses. Its portfolio reflects the broader industry tension between maintaining hydraulic performance expectations and lowering energy draw across duty cycles. Across the Atlantic, Nexteer Automotive has sharpened its focus on hydraulic power steering systems and pumps optimized for fuel efficiency and advanced driver assistance in heavy-duty trucks and commercial vehicles. Recent activity underscores that focus: a rear-wheel steering system developed to improve maneuverability in heavy vehicles, and a high-output electrified power steering solution targeting increased steering assist capacity for larger commercial platforms. These moves highlight how steering is being treated less as an isolated component category and more as part of a vehicle maneuverability and control strategy.
The landscape also includes suppliers with specialized engineering angles. Evamo has emphasized variable displacement vane pumps and electro hydraulic power steering pumps for medium to heavy commercial vehicles, with a stated emphasis on efficiency and CO₂ reduction—an increasingly relevant framing as fleet operators and regulators scrutinize total energy consumption. JTEKT Corporation supplies variable-flow steering pumps and hydraulic power steering solutions across commercial and light commercial applications, while Astemo has concentrated on power steering pumps with cast aluminum housing designed for commercial vehicle durability and efficiency. Concentric AB has taken a different route, developing electro hydraulic steering pumps for hybrid, fuel cell, and electric trucks and buses, directly addressing the displacement of conventional engine-driven pumps as powertrain architectures diversify. Maval Industries rounds out the field with power steering pumps and gears tailored to heavy-duty commercial and truck applications.
Together, these profiles reveal a market where competitive advantage is increasingly tied to efficiency claims, electronics compatibility, packaging for heavy-duty use, and the ability to support OEM transitions toward electrified or hybrid commercial platforms. The report examines these positions in greater depth, including how recent product activity is reshaping procurement conversations and where supplier vulnerability may emerge as regulations and powertrain mixes shift.
Industry Dynamics: Regulation, Input Costs, and the Efficiency Imperative
External pressures are not peripheral to this market; they are actively reordering priorities. Regulatory direction is one of the most consequential. European policy proposals targeting substantial carbon emission reductions for new heavy-duty commercial vehicles by 2030 are accelerating the search for components that contribute to lower overall energy consumption. In that context, a power steering pump is no longer judged only by steering performance. It is increasingly evaluated for parasitic load, duty-cycle efficiency, and compatibility with electrified or hybrid drivetrains.
Compliance expectations are also tightening on the operational side. Inspection-oriented regulations such as FMCSA Regulation 393.209, which requires commercial vehicle power steering systems to remain leak-free during inspections, reinforce the importance of reliability and sealing integrity in heavy-duty applications. For suppliers and fleet operators alike, this creates a dual mandate: improve efficiency without sacrificing durability or regulatory conformance.
Input cost volatility adds another layer of complexity. Fluctuations in aluminum and steel prices directly influence manufacturing economics for metal-housed power steering pumps, particularly where castings and structural components constitute a meaningful share of bill-of-materials cost. In an environment where procurement teams are already balancing performance upgrades against cost control, raw material exposure can determine margin resilience and pricing strategy. The research integrates these dynamics to help readers evaluate where cost risk is likely to concentrate and how suppliers may respond through design optimization, material strategy, or portfolio segmentation.
Why the 2026 Decision 윈도우 Requires a Deeper Read
The forecast period beginning in 2026 is not simply another year in a growth curve. It is a point where several trajectories converge: the maturation of electro hydraulic offerings, the continued presence of hydraulic pumps in cost-sensitive and high-duty applications, and the increasing need for steering systems that can coexist with ADAS features and alternative powertrains. In that environment, decisions made on the basis of aggregate market size alone will be insufficient.
Companies that want to act with confidence need to understand how demand is distributed across commercial vehicle types, which product types are gaining or losing relative share, where regional procurement patterns favor local content or imported systems, and how the leading suppliers are positioning their roadmaps against efficiency and electrification pressures. They also need a realistic view of competitive concentration: in a market where the leading suppliers hold a sizable revenue share, entry, expansion, or renegotiation strategies must account for the fact that incumbents are not standing still.
This is precisely the gap the full study is built to fill. The published analysis preserves the strategic framing outlined here while extending into the level of detail required for internal planning: scenario assumptions, segment-level demand logic, supplier positioning, technology migration patterns, and the cost and regulatory variables that shape near-term competitiveness.
Target Audience and Use Cases
The report is intended for teams that need a credible, structured foundation for commercial vehicle steering market decisions. Typical applications include:
- Component sourcing and procurement strategy , where understanding demand trends and supplier concentration supports supplier evaluation, negotiation stance, and risk diversification.
- R&D and product planning , where the shift between hydraulic and electro hydraulic solutions, variable displacement architectures, and electronics integration informs engineering priorities.
- Competitive and market intelligence , where recent product showcases, launches, and system-level announcements are placed in context rather than read as isolated press milestones.
- Investment screening and portfolio review , where market size, growth trajectory, concentration, and regulatory exposure help frame attractiveness and risk.
- Regional expansion or market-entry assessment , where demand distribution and application mix provide a starting point for more detailed local analysis.
Final Perspective: From Aggregate Growth to Strategic Positioning
The commercial vehicle power steering pump market is moving on a foundation of steady expansion, but its real story lies in the forces reshaping how value is created within that growth. Efficiency expectations, regulatory direction, powertrain diversification, and the steady integration of steering with broader vehicle electronics are all pushing suppliers and buyers toward more differentiated, more technically grounded decisions. In a market where the top suppliers already hold a meaningful revenue share and recent product activity points toward higher functionality and lower parasitic loss, the winners will be those who can interpret the signals early and align their strategies accordingly.
The full study translates that landscape into a usable intelligence platform. To access the complete segmentation logic, regional and application-level demand context, supplier competitive assessment, and forecast detail needed for 2026 planning, request the full report through our official research portal.
For detailed analysis of this topic, please visit the official page: Commercial Vehicle Power Steering Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heated Fabric Market to Hit $1.29B by 2032, 13.62% CAGR
By pmarketresearch, 2026-09-16
Beyond Warmth: Strategic Intelligence for the Global Heated Fabric Market (2026–2032)
The heated fabric market has evolved from a niche innovation into a critical component of the broader smart textiles ecosystem. As we move through 2026, companies across automotive, medical, apparel, and industrial sectors are facing a pivotal question: how to navigate a landscape defined by rapid technological iteration, shifting raw material dynamics, and intensifying competition. PW Consulting's latest Worldwide Heated Fabric Market research report offers a comprehensive strategic roadmap for stakeholders seeking to capitalize on this momentum. This introduction outlines the critical market dynamics, competitive forces, and actionable intelligence contained within our analysis, demonstrating why this study is essential for informed decision-making in the coming years.
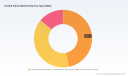
Worldwide Heated Fabric Market
The Trajectory of Thermal Textiles: A Macro View
The global heated fabric market has demonstrated robust growth over the past half-decade, transitioning from experimental prototypes to mass-market adoption. Our analysis traces this evolution from 2020 through the base year of 2025, projecting a clear trajectory of expansion that extends through the forecast period ending in 2032. In 2020, the market was valued at approximately USD 278.4 million. By 2025, this figure had climbed to USD 528.2 million, reflecting a compound annual growth rate that underscores the accelerating demand for temperature-regulating textiles.
Looking ahead, the forecast period from 2026 to 2032 signals sustained momentum. The market is projected to reach USD 595.65 million in 2026, growing steadily to exceed USD 1.29 billion by 2032. This growth is underpinned by a CAGR of 13.62 percent, a rate that places heated fabrics among the faster-growing segments within the functional textiles sector. For corporate strategists, this trajectory suggests that heated fabrics are no longer a speculative venture but a viable growth vector requiring serious investment and strategic planning. However, understanding the aggregate numbers is only the first step. The true value lies in dissecting the drivers, constraints, and segmentation nuances that will determine which players capture market share and which risk obsolescence.
Key Value Drivers and Emerging Constraints
Several interconnected factors are fueling this expansion. First, the proliferation of electric vehicles and the demand for energy-efficient cabin solutions are reshaping the automotive interiors segment. Consumers increasingly expect personalized comfort, and heated surfaces offer a low-energy alternative to traditional air heating systems. Second, the medical and healthcare sector continues to leverage heated textiles for therapeutic applications, patient warming, and wearable health monitoring, driven by an aging global population and rising chronic care needs. Third, the apparel and footwear industry is witnessing a surge in performance-oriented heated gear for outdoor enthusiasts and workers in extreme environments, supported by advancements in battery technology and flexible power sources.
Conversely, challenges persist. Supply chain volatility for specialized conductive materials, regulatory compliance across diverse geographic markets, and the need for durable, washable, and safe heating elements require careful navigation. Our report dedicates significant attention to these dynamics, providing a balanced view of the opportunities and risks that define the current landscape.
Upstream Ecosystem: Raw Materials and Component Innovation
The performance and cost structure of heated fabrics are inextricably linked to the upstream supply of conductive materials. Our analysis incorporates critical data on the broader conductive textiles market, which serves as a foundational input for heated fabric manufacturing. In 2026, the conductive textiles segment was valued at approximately USD 4.2 billion and is projected to reach USD 8.5 billion by 2033, indicating a robust supply ecosystem that will support heated fabric innovation. Additionally, the electrically conductive fabric market, a specialized subset essential for heating elements, was valued at roughly USD 430.76 million in 2025, with strong growth fueled by metal-coated, silver-plated, and carbon-based yarns.
Material science breakthroughs are also reshaping the competitive frontier. The integration of graphene and other nanomaterials into conductive textiles has enabled significant performance enhancements. Innovations allowing low graphene loading levels as minimal as 2 to 4 grams per square meter are facilitating the production of lightweight, flexible, and uniformly heating fabrics. These advancements reduce material costs while improving durability and comfort, opening new possibilities for applications ranging from consumer wearables to industrial protective gear. Our report examines how these material trends influence cost structures, product differentiation, and time-to-market for heated fabric solutions.
Segmentation Dynamics: Decoding Application and Technology Splits
The heated fabric market is not a monolith; it is a mosaic of distinct segments with varying growth rates, customer requirements, and competitive intensities. Our report provides a granular breakdown of the market by type, application, and region, offering the granularity needed to identify high-value niches and allocate resources effectively.
In terms of technology, the market encompasses carbon-based heating textiles, metal-based heating textiles, and conductive polymer textiles. Each technology presents unique trade-offs in terms of flexibility, heating speed, energy efficiency, washability, and cost. Carbon-based solutions, for instance, are gaining traction for their durability and uniform heat distribution, while metal-based variants offer rapid heat-up times for specific industrial and medical uses. Conductive polymers represent an emerging frontier with potential for greater design flexibility and integration into smart textile systems.
Application-wise, the market spans apparel and footwear, medical and healthcare, automotive interiors, home textiles, and industrial and military uses. Apparel and footwear remain a dominant force, driven by outdoor recreation and performance wear. Medical and healthcare applications benefit from steady demand for therapeutic and comfort solutions. Automotive interiors are experiencing a transformation as automakers seek sustainable, energy-efficient comfort features. Home textiles and industrial/military segments, while smaller in relative terms, offer specialized opportunities for high-margin, customized solutions. Our analysis avoids generic summaries, instead delivering detailed insights into the revenue contributions, growth trajectories, and strategic priorities within each segment, enabling clients to pinpoint where their capabilities align with market demand.
Regional dynamics further complicate the picture. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct regulatory environments, consumer preferences, and manufacturing capabilities. Our report maps these regional variations, highlighting where market maturity, growth potential, and competitive pressures converge. This geographic intelligence is vital for companies planning market entry, expansion, or supply chain optimization.
Competitive Landscape: Key Players and Strategic Moves
The heated fabric market is characterized by a mix of specialized textile manufacturers, technology innovators, and established industrial players. Understanding the strategies, capabilities, and recent moves of these key companies is essential for benchmarking and competitive positioning. Our report profiles several leaders who are shaping the industry's direction.
- Embro GmbH (Germany): A specialist in custom-designed heated textiles, heating fleeces, heating mats, and smart e-textiles leveraging technical embroidery. Their products serve industrial, automotive, medical, apparel, and OEM applications, with a focus on flexible, washable, series-production ready heating elements made in Germany. In April 2026, Embro GmbH achieved a significant milestone with the launch of VDE-certified heating elements and flexible heating mats and tapes, reinforcing their commitment to cost-effective, high-quality series production for industrial and apparel markets. This certification enhances their credibility in European markets where electrical safety and quality assurance are paramount.
- Gustav Gerster GmbH & Co. KG (Gerster TechTex) (Germany): This company produces functional heated textiles utilizing carbon fiber and copper solutions. Their offerings are distinguished by short heat-up times, even temperature distribution, high drapeability, and seamless integration into technical textile applications. Gerster TechTex's expertise positions them as a key supplier for applications requiring reliable, uniform heating in demanding environments.
- LOOMIA Technologies Inc. (USA): Based in Brooklyn, New York, LOOMIA develops soft, flexible e-textile solutions, including the Loomia Electronic Layer (LEL) and the Gentoo Heater. Their focus spans automotive interiors, wearables, medical applications, and extreme-cold environments down to minus 60 degrees Celsius. In January 2025, LOOMIA introduced the Gentoo Textile Heater, a TPU-based resistive heater developed in collaboration with AFFOA, designed for gloves and extreme-cold gear. More recently, in February 2026, LOOMIA emphasized the application of their heated fabric technology in automotive interiors, highlighting energy-efficient, sustainable, and seamless integration into vehicle designs. These moves underscore LOOMIA's strategy to expand into high-growth sectors while leveraging material innovation for extreme conditions.
- QuantumTex (UMATECO / QuantumTex International Ltd.) (Taiwan): QuantumTex is a manufacturer of patented wearable heated textile products, including heated apparel, gloves, headwear, and footwear. They provide one-stop design-to-shipping services for heated clothing systems, offering a vertically integrated approach that appeals to brands seeking streamlined development and production. Their focus on consumer-facing heated apparel positions them at the intersection of fashion and function.
- Rockleigh Industries Inc. (USA): Rockleigh is developing graphene-based conductive heating textiles that utilize minimal graphene loading of 2 to 4 grams per square meter. This approach yields lightweight, flexible, and uniform-heating fabrics suitable for a variety of heating applications. Their emphasis on nanomaterial efficiency aligns with broader industry trends toward performance enhancement and cost optimization through advanced materials.
Beyond individual company profiles, our report analyzes the market concentration structure. The top three companies account for approximately 34.2 percent of the market, while the top five hold a combined share of 49.5 percent. This moderate concentration indicates a fragmented yet competitive landscape where innovation, niche specialization, and strategic partnerships can yield significant advantages. We examine how these players are competing on technology, cost, certification, and application expertise, providing a framework for assessing competitive threats and collaboration opportunities.
Inside the Report: Actionable Intelligence for Decision-Makers
PW Consulting's Worldwide Heated Fabric Market report is designed to be a practical tool for strategic planning, not just a collection of statistics. The report delivers a wealth of actionable content, including:
- Historical and Forecast Data: Detailed revenue figures from 2020 through 2032, presented in USD million, enabling trend analysis, baseline setting, and future projection. This longitudinal view helps clients distinguish between cyclical fluctuations and structural growth.
- Segmentation Analysis: Comprehensive breakdowns by region, type, and application, revealing the relative size, growth rates, and strategic importance of each segment. This allows for targeted market entry strategies, product portfolio optimization, and resource allocation.
- Competitive Profiling: In-depth assessments of key companies, including their product offerings, recent developments, technological strengths, and market positioning. This intelligence supports competitive benchmarking, partnership evaluation, and threat assessment.
- Industry Context and Dynamics: Analysis of raw material trends, regulatory factors, technological advancements, and application-specific demands. For instance, the report integrates data on conductive textile valuations, VDE certification relevance, and graphene integration breakthroughs to provide a holistic view of the ecosystem.
- Strategic Recommendations: Insights tailored for manufacturers, brands, investors, and suppliers, helping them identify high-potential applications, anticipate supply chain shifts, and align R&D efforts with market needs.
The report is structured to answer critical questions: Which segments offer the highest growth potential? How are material innovations reshaping cost and performance? What certifications and standards are becoming mandatory in key regions? How are leading companies differentiating themselves? By addressing these questions with data-driven rigor, the report equips stakeholders with the clarity needed to act decisively.
Why This Report Matters for 2026 Decision-Making
In a market growing at a CAGR of 13.62 percent and projected to surpass USD 1.29 billion by 2032, the window for strategic positioning is opening but will not remain open indefinitely. Companies that delay investment in heated fabric capabilities risk ceding ground to agile competitors and new entrants. Conversely, those that act with informed precision can secure advantages in technology, supply chain, and customer relationships.
This report is particularly timely given the confluence of trends in 2026. The automotive sector's push for energy-efficient interiors, the medical industry's demand for advanced therapeutic textiles, and the consumer market's appetite for performance wear are all converging to create a fertile environment for heated fabrics. Simultaneously, upstream material developments, such as graphene-based solutions and conductive fabric market expansion, are lowering barriers to innovation while raising the bar for performance. Regulatory developments, including certification standards like VDE, are shaping market access and consumer trust. Our report synthesizes these interlocking factors into a coherent strategic narrative.
Worldwide Heated Socks Market
Furthermore, the moderate market concentration suggests that there is still room for differentiation and niche dominance. Companies that can leverage specialized technologies, secure key certifications, and forge strong partnerships with end-users in high-value applications will be well-positioned to capture disproportionate share. The report provides the analytical foundation to identify those applications, assess competitive intensity, and evaluate the feasibility of entry or expansion.
Conclusion: Turning Insight into Advantage
The Worldwide Heated Fabric Market is at an inflection point. Growth is robust, innovation is accelerating, and competition is intensifying. Success in this environment requires more than intuition; it demands rigorous analysis, forward-looking perspective, and a clear understanding of where value is being created and captured. PW Consulting's latest market research delivers precisely that: a comprehensive, data-rich, and strategically oriented guide to navigating the heated fabric landscape from 2026 through 2032.
We invite you to explore the full report to access the detailed segmentation data, competitive profiles, regional breakdowns, and strategic insights that will inform your next moves. Whether you are a manufacturer evaluating new product lines, a brand seeking to integrate heated features, an investor assessing opportunities, or a supplier aligning with market demand, this report provides the intelligence you need to make confident, evidence-based decisions. The heated fabric revolution is underway; ensure your strategy is built on the deepest available insight.
For detailed analysis of this topic, please visit the official page: Worldwide Heated Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cooling Mattress Topper Market to Hit $2,619.92M by 2032 at 8.16% CAGR
By pmarketresearch, 2026-09-16
# Strategic Intelligence for a Warming World: Navigating the 2026-2032 Growth Trajectory of the Global Cooling Mattress Topper Market
Executive Overview: The Imperative for Strategic Foresight
The global sleep technology landscape is undergoing a profound transformation driven by converging forces of climate variability, heightened health consciousness, and rapid material innovation. For corporate strategists, investors, and product development leaders, the cooling mattress topper segment represents a high-velocity market where first-mover advantages in thermal regulation technology are rapidly translating into durable market share. PW Consulting's latest worldwide market intelligence report delivers a comprehensive, data-grounded assessment of this evolving sector, specifically engineered to inform executive decision-making throughout the 2026 strategic planning cycle and beyond.
As market participants navigate an increasingly competitive environment, the ability to accurately forecast demand elasticity, track material cost trajectories, and anticipate regulatory shifts has become a non-negotiable competency. This report provides the analytical architecture required to move beyond reactive positioning and toward proactive portfolio optimization. By synthesizing historical performance data with forward-looking scenario modeling, the publication equips leaders with the clarity needed to allocate capital efficiently, refine go-to-market architectures, and identify whitespace opportunities before they are captured by incumbent rivals.
Macroeconomic Trajectory and Long-Term Growth Signals
Historical valuation patterns across the 2020-2025 evaluation window reveal a consistent upward demand curve, underscoring the transition of cooling mattress toppers from a niche comfort accessory to a mainstream sleep optimization essential. The market has demonstrated robust expansion momentum, with revenue figures reflecting sustained consumer willingness to invest in premium thermal management solutions. Looking ahead, the forecast horizon spanning 2026 through 2032 projects a compound annual growth rate of 8.16 percent, signaling a maturation phase characterized by broader demographic penetration and institutional retail adoption.
Revenue scale continues to accelerate as the category establishes deeper distribution networks and gains credibility within the broader sleep wellness ecosystem. The baseline valuation for the current reporting year anchors at approximately 1,509.30 million USD, with near-term projections indicating a crossover above the 1,650 million USD threshold in 2026. Subsequent annual estimates illustrate a compounding expansion trajectory, culminating in a projected valuation approaching 2,620 million USD by the close of the forecast period. This growth profile reflects not only baseline demand recovery but also structural shifts in purchasing behavior, where temperature regulation is increasingly treated as a fundamental requirement rather than a discretionary upgrade.
Key Growth Catalysts Shaping the 2026 Outlook
Multiple interconnected drivers are accelerating category expansion. Rising awareness of sleep quality and temperature regulation continues to convert casual mattress owners into active buyers of cooling enhancement products. Simultaneously, raw material innovation has elevated performance benchmarks for heat dissipation. Gel-infused formulations and phase change material (PCM) technologies now dominate cooling mattress topper formulations, delivering measurable improvements in thermal conductivity and moisture management. These material advancements have reduced the performance gap between passive cooling solutions and active temperature control systems, broadening the addressable consumer base.
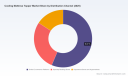
Worldwide Cooling Mattress Topper Market
Regulatory and quality assurance frameworks have also matured, reinforcing consumer confidence in premium sleep accessories. CertiPUR-US certification has become a standard benchmark for memory foam cooling mattress toppers, ensuring low VOC emissions and adherence to stringent safety protocols. This standardization has lowered consumerhesitation around foam-based cooling products and enabled brands to differentiate through verified material transparency. As compliance expectations evolve, companies that integrate certified material sourcing into their supply chain architecture are positioned to capture premium price segments and secure retail partnerships that prioritize product safety credentials.
Competitive Dynamics and Strategic Positioning Framework
The competitive landscape is defined by a moderately concentrated market structure, where leading participants leverage proprietary material science, specialized distribution agreements, and targeted branding to secure footholds across distinct consumer segments. Market concentration metrics indicate that the top three players command a combined share of approximately 19.45 percent, while the top five collectively account for roughly 27.6 percent of total category revenue. This fragmentation above the top tier suggests a highly dynamic environment where regional specialists, direct-to-consumer digital brands, and technology-enabled startups continuously challenge established incumbents through product differentiation and agile supply chain execution.
Strategic positioning in this arena increasingly hinges on the intersection of material innovation, thermal performance claims, and channel accessibility. Incumbent manufacturers are expanding their thermal management portfolios by embedding proprietary cooling fabrics, copper-infused matrices, and graphite-enhanced memory foam architectures into their topper lines. These technological enhancements are frequently paired with cool-to-the-touch surface engineering and pressure-relief compositions designed to deliver simultaneous thermal and ergonomic benefits. Meanwhile, emerging and mid-tier competitors are pursuing specialized niches, including organic material formulations, dual-zone active air regulation, and water-based circulation systems capable of maintaining precise temperature ranges throughout the sleep cycle.
The competitive intensity underscores the necessity of granular technology benchmarking and lifecycle cost analysis. Brands that rely exclusively on generic cooling claims face growing pressure from competitors who validate performance through structured testing protocols and transparent material disclosures. Conversely, companies that integrate certified safety standards, sustainable sourcing narratives, and demonstrable heat dissipation metrics into their product architecture are better positioned to command retail shelf presence and sustain consumer loyalty in a crowded marketplace.
Distribution Architecture and Channel Evolution
Channel strategy remains a decisive variable in capturing category growth. The market distribution network is structured around three primary pathways: online e-commerce platforms, specialty bedding retailers, and department stores alongside hypermarket outlets. Digital marketplaces have emerged as the dominant acquisition channel, benefiting from streamlined product discovery, detailed specification pages, and consumer review ecosystems that accelerate purchase decisions. The visibility and convenience of direct digital purchasing have fundamentally altered how cooling toppers are discovered, evaluated, and adopted, particularly among younger demographics and urban consumers who prioritize home delivery and flexible return policies.
Specialty bedding stores continue to serve as high-trust validation environments, where tactile evaluation and expert consultation reinforce premium positioning. Customers visiting these locations often seek hands-on verification of cooling performance, pressure distribution, and material breathability before committing to higher price points. Department stores and hypermarkets, meanwhile, provide mass-market accessibility and promotional velocity, though they typically cater to entry-level or mid-tier product tiers where price sensitivity outweighs specialized thermal performance expectations.
The coexistence of these channels creates a multi-tiered go-to-market landscape where brand architecture must align with channel-specific consumer expectations. E-commerce strategies favor detailed educational content, comparative thermal performance data, and subscription or bundle offers, while specialty retail requires in-store merchandising that emphasizes material quality and verified comfort claims. Companies that fail to calibrate their channel messaging and inventory allocation risk diluting perceived value or missing high-intent purchase moments in digitally driven conversion funnels.
Segmentation Architecture and Innovation Vectors
The cooling mattress topper category is segmented across material types, geographic demand clusters, and distribution pathways, each presenting distinct growth dynamics and strategic execution requirements. Material segmentation remains the most critical axis for product development and pricing strategy, as thermal performance, durability, and manufacturing complexity vary significantly across formulations. Gel-infused memory foam continues to lead in market penetration, supported by established manufacturing infrastructure and broad consumer recognition. Phase change materials and active cooling systems represent high-growth innovation vectors, appealing to performance-conscious buyers willing to invest in advanced temperature regulation. Natural latex and breathable fiber alternatives attract consumers seeking organic or hypoallergenic attributes without sacrificing airflow and moisture management.
Regional demand patterns reflect varying climate profiles, purchasing power distributions, and retail maturity levels. North American, European, and Asia-Pacific markets each exhibit distinct consumption behaviors shaped by local climate conditions, sleep culture preferences, and channel development. The spread of cooling topper adoption across these regions is not uniform, with certain markets demonstrating accelerated uptake due to heightened heat exposure, urbanization-driven housing configurations, and expanding e-commerce penetration. Latin American and Middle Eastern and African markets present emerging opportunity zones where climate adaptation needs intersect with rising middle-class consumption, though execution requires localized pricing strategies and distribution partnerships tailored to fragmented retail landscapes.
Because segmentation shapes everything from manufacturing scale to promotional messaging, the report isolates the interplay between material performance tiers, regional demand elasticity, and channel accessibility. Readers seeking precise revenue contributions by geography, material class, or sales pathway will find the full segmentation breakdown essential for market-entry modeling and capacity planning.
What the Report Delivers: Actionable Intelligence for Executive Teams
PW Consulting's Worldwide Cooling Mattress Topper Market research is structured to provide immediate operational utility across multiple business functions. The analysis integrates historical valuation data, forward-looking growth projections, and competitive benchmarking into a cohesive strategic framework. Key deliverables include:
- Comprehensive market sizing across the 2020-2032 timeline, with baseline valuations and year-by-year revenue projections expressed in USD million, enabling accurate capacity planning and revenue forecasting.
- Forecasting models calibrated to an 8.16 percent compound annual growth trajectory, allowing leadership teams to stress-test product roadmaps, channel investment priorities, and regional expansion assumptions.
- Technology and material trend analysis covering gel-infused foams, phase change materials, active cooling systems, and breathable natural alternatives, with implications for supply chain sourcing and performance positioning.
- Competitive profiling of major industry participants, highlighting product architecture, thermal innovation claims, and strategic differentiation pathways across premium, mid-tier, and technology-forward offerings.
- Channel dynamics assessment examining the role of digital platforms, specialty retailers, and mass-market outlets in shaping consumer acquisition, price realization, and brand visibility.
- Regulatory and certification context, including CertiPUR-US compliance considerations and material safety expectations that influence product design, retail eligibility, and consumer trust.
The publication is designed for cross-functional application, supporting executive strategy sessions, product development prioritization, investor communications, and competitive response planning. By aligning macro-level market trajectory with actionable segmentation and competitive intelligence, the report enables decision-makers to translate market growth into executable commercial strategy.
Recent Market Activity and Forward-Looking Signals
Market momentum remains active, with product launches and technology introductions signaling sustained innovation intensity. Recent industry activity illustrates how manufacturers are accelerating release cycles to capture attention among heat-sensitive sleepers and performance-driven buyers. In April 2026, for example, a notable product launch introduced a newly engineered cooling mattress topper line targeting uninterrupted thermal comfort for hot sleepers, reinforcing the broader trend toward specialized cooling architectures and full-body temperature management. Such developments highlight the pace at which competitors are iterating on cooling performance claims, surface materials, and user-adjustable thermal controls.
These market movements carry strategic implications for incumbents and new entrants alike. Faster innovation cadences compress the window for competitor response, making it critical for companies to maintain agile product development pipelines, monitor patent and material sourcing trends, and evaluate consumer feedback loops in real time. At the same time, the proliferation of cooling technologies raises the bar for differentiation, as buyers increasingly expect verifiable performance benefits rather than generic comfort narratives. Companies that align their launch strategies with clear thermal value propositions, credible certification standards, and targeted channel deployment will be best positioned to convert market momentum into sustainable share gains.
Strategic Conclusions for 2026 Planning
The cooling mattress topper market stands at an inflection point where structural demand growth intersects with rapid material innovation and intensifying competitive activity. The projected expansion trajectory through 2032 indicates that thermal regulation products will continue transitioning from peripheral accessories to core components of the sleep wellness category. For organizations operating in bedding, sleep technology, retail, or consumer goods, the strategic question is no longer whether to participate in this segment, but how to position product portfolios, supply chains, and channel strategies to capture disproportionate value.
Success in this environment requires disciplined market intelligence that bridges historical performance, forward-looking growth modeling, and competitive execution realities. Leaders must evaluate material sourcing resilience, assess channel alignment, and calibrate pricing architectures against evolving consumer expectations for cooling performance and safety compliance. They must also monitor the accelerating cadence of product introductions, as innovation velocity increasingly determines visibility, credibility, and share retention.
Mattress Toppers Market
The complete dataset, detailed segmentation breakdowns, competitive benchmarks, and scenario-based growth modeling contained in this report provide the analytical foundation required to make those decisions with precision. Organizations seeking to translate category growth into actionable strategy are encouraged to access the full research publication for comprehensive intelligence tailored to executive planning, market-entry evaluation, and long-term portfolio optimization.
For detailed analysis of this topic, please visit the official page: Worldwide Cooling Mattress Topper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aircraft Pressurisation Systems Market to Hit $12,977.42M by 2032 at 6.32% CAGR
By pmarketresearch, 2026-09-16
Decoding the Sky: Strategic Imperatives in the Global Aircraft Pressurisation Systems Market (2026–2032)
As commercial aviation enters a new phase of fleet renewal, fleet expansion, and architectural transformation, the humble yet critical aircraft pressurisation system has moved from a purely engineering concern to a strategic boardroom topic. In an industry where reliability, weight, fuel burn, and cabin environment quality directly shape profitability and passenger retention, mastering the dynamics of cabin pressure control is no longer optional. The Worldwide Aircraft Pressurisation Systems Market research published by PW Consulting provides decision-makers with a structured, data-rich view of how this subsystem is evolving, who is shaping its trajectory, and where the most consequential value creation opportunities will emerge through 2032.
This insight is designed as a strategic companion to that report. It distills the macro trajectory, competitive architecture, and operational themes that matter most for 2026 planning cycles—without giving away the granular segmentation that makes the full study a practical tool for sourcing, programme management, and investment prioritisation.
Why Pressurisation Systems Now Matter More Than Ever
Pressurisation is not simply a comfort feature; it is a regulatory and operational backbone that governs how high an aircraft can fly, how efficiently it breathes, and how safely it manages decompression events. As airframe manufacturers pursue aerodynamic efficiency at higher cruise altitudes, as airlines seek smoother fuel economics, and as defence and business aviation operators push platform envelopes, the pressurisation chain—outflow valves, cabin pressure controllers, safety and bulkhead valves, sensors, and actuators—must deliver more performance with less weight, less maintenance, and greater integration with flight management logic.
The global market for aircraft pressurisation systems has been expanding steadily on the back of rising air traffic, fleet modernisation, and tighter safety expectations. After a market size of roughly USD 6.1 billion in 2020, the sector climbed through the pandemic recovery years and reached approximately USD 8.45 billion in 2025. The forward arc continues to steepen: the base year is 2025 and the forecast runs from 2026 through 2032, with a compound annual growth rate of approximately 6.32%. By the end of the forecast horizon, revenue scale is projected to approach nearly USD 13.0 billion. These are not just growth figures for prognostication; they frame budgeting, capacity planning, and supplier negotiations for the next seven years of airframe programmes, retrofit campaigns, and fleet sustainment.
What makes this trajectory strategically interesting is not the headline alone. It is the way growth is skewed by product architecture, fleet composition, and regulatory pressure—and exactly where those skews occur is the intelligence that programme managers, procurement teams, and investment committees need before locking in multi-year commitments.
Market Size, Growth Trajectory, and What It Means for 2026 Decisions
The most useful way to read the market roadmap is as a sequence of decision triggers rather than a flat line.
-
Recovery-to-expansion inflection: The step from 2024 to 2025 reflects the deepening impact of production ramp-ups and the return of wider utilisation patterns across passenger and cargo platforms. For 2026 planning, this means demand visibility is improving, but timing discipline still matters—especially where programmes nest pressurisation hardware into new delivery slots.
-
Forecast momentum: The projected expansion from about USD 9.15 billion in 2026 to nearly USD 12.98 billion by 2032 signals a durable, above-trend environment for pressurisation content. Organisations that treat this as a stable tailwind can better align engineering roadmaps, spare parts inventories, and MRO partnerships.
-
Risk windows: Growth concentrated in the outer years also means that early movers in technology adoption, certification support, and retrofit readiness can secure stronger positioning before the market becomes crowded. Conversely, late adopters face more competition for slots in key platforms and more pressure on margins.
Because pressurisation systems sit at the intersection of safety regulation, environmental control, and power architecture, the “how” of growth will matter as much as the “how much.” That is precisely why the report crosses functional boundaries, linking market sizing to component logic, aircraft type economics, geographic concentration, and the competitive moves that define who wins content shares.
Segment Architecture: Where Value Is Being Created
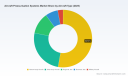
The market breaks down across three analytical dimensions that shape procurement strategy and product roadmaps: parts of the world, aircraft types, and system components. The report treats each dimension as a lens for understanding where content intensity is rising, where consolidation is strongest, and where the next wave of specification decisions is likely to occur.
Regional Concentration and Demand Drivers
Demand is spread across multiple geographies, but it is far from uniform. North America remains a central hub of content demand, reflecting both domestic airframe activity and the export footprint of aircraft programmes, defence platforms, and business aviation. Europe follows as a structurally important region, anchored by OEM ecosystems and a dense network of retrofit and support operations. Asia Pacific stands out for its growth potential, propelled by rising air traffic, expanding fleet modernisation, and the localisation of supply chains around key airframe and engine programmes. The Middle East and Africa and Latin America together add additional layers of demand, often tied to specific fleet renewal cycles and niche platform requirements.
Rather than treating geography as a static backdrop, the analysis shows how regional demand patterns influence supplier positioning, after-sales service strategies, and the timing of content wins. The full report unpacks these dynamics with segmentation detail that procurement and business development teams can use to calibrate regional go-to-market plans.
Aircraft Type Economics and Programme Strategy
Pressurisation content does not scale linearly with aircraft size or mission type. Narrow-body aircraft command the largest share of market content, consistent with their volume role in global airline operations and the breadth of pressurisation hardware required across high-cycle fleets. Wide-body aircraft carry a differentiated content profile, where system complexity, stages, and integration constraints elevate the importance of reliability and serviceability. Regional jets, business jets, and military aircraft each bring specialised requirements—shorter field performance, reduced maintenance footprints, mission-specific pressure management, and platform-specific certification logic—that translate into distinct margins, content densities, and supplier selection criteria.
The strategic takeaway is that aircraft type is not just a classification; it is a demand filter that determines which components, which suppliers, and which technology paths matter most. Programme teams evaluating pressurisation content for a new platform or a retrofit campaign must look beyond overall market growth and examine how the mix of aircraft types is shifting under them.
Component-Level Logic: The Real Battleground
At the most actionable level, pressurisation value is split across key components and subsystems: outflow valves, cabin pressure controllers, safety and bulkhead valves, and sensors and actuators. Each of these categories carries different technical risk, different upgrade cycles, and different competitive dynamics.
-
Outflow valves remain central to pressure management, and they are a natural focal point for weight reduction, reliability improvement, and control integration.
-
Cabin pressure controllers increasingly function as the logic layer of the system, where algorithmic performance, health monitoring, and interface with flight management systems shape pilot workload and operational robustness.
-
Safety and bulkhead valves are fundamental to compliance and failure management, making them a steady but technically demanding content area.
-
Sensors and actuators represent the connective tissue between control logic and physical actuation, with growing relevance as architectures move toward electric and more-electric solutions.
Understanding the relative content weight of these categories is essential for sourcing strategy. It helps planners infer where substitution risk is highest, where integration value is greatest, and where suppliers can differentiate through digital features rather than mechanical performance alone. The complete report details the component-level splits that underpin these conclusions.
Regulation, Technology, and the Reshaping of Demand
No pressurisation strategy is complete without regulatory and architectural context. Safety requirements establish the floor, while technology trends define the ceiling for performance and cost.
Regulatory Dynamics as Market Forces
Pressurisation systems operate under a strict overlay of certification and operational requirements. Cabin pressure management must maintain protected conditions under normal operations and limit occupant exposure in the event of failure. For large aeroplanes, the design basis requires that the pressurisation system minimise the time occupants are exposed to cabin altitudes above 8,000 feet, while also addressing decompression scenarios. Redundancy is built into the logic through requirements for pressure relief arrangements, ensuring that positive pressure differentials are automatically limited and that safety is preserved even if one valve becomes unavailable.
These rules are not static background; they influence design choices, qualification effort, and the cost of programme entry. As regulatory expectations continue to evolve around cabin environment quality and contamination risk, suppliers and operators alike must anticipate not just current compliance but the direction of tightening scrutiny on air quality, fume event management, and contaminant monitoring. That forward-looking compliance posture is increasingly a competitive differentiator in sourcing decisions.
From Bleed Air to More-Electric Architectures
A defining technology shift is the movement toward more-electric aircraft architectures, where electric compressors and electrically driven pressurisation subsystems can replace or supplement traditional bleed air arrangements. This transition is being pursued for several reasons: fuel efficiency, system simplification, reduced dependence on engine architecture, and lowered potential for contamination pathways associated with bleed air. At the same time, it introduces new engineering requirements around electrical power management, thermal integration, and health monitoring.
For pressurisation suppliers, this evolution is both an opportunity and a test. Companies that can offer electric cabin pressure control subsystems with integrated health monitoring, reduced maintenance burden, and lower installation complexity are well positioned for next-generation platforms and retrofit campaigns. The report evaluates how far this transition has progressed and where the balance between pneumatic and electric solutions is likely to sit across different aircraft categories.
Competitive Landscape: Who Sets the Pace
The pressurisation market is characterised by a small group of large, well-established players, with meaningful concentration among the top firms. This concentration matters because it shapes pricing power, technology leadership, certification readiness, and the ability to support global fleets at scale. The report quantifies this concentration and then drills into the companies that define it.
Several global suppliers sit at the centre of this ecosystem.
-
Honeywell Aerospace provides cabin pressure control systems including its fourth-generation digital cabin pressure control system, which is built around brushless DC technology, meaningful weight reduction, and enhanced reliability. The breadth of its application coverage—from large air transport to regional, business, military, and general aviation platforms—makes it a reference point for digital pressurisation control. A product brochure released in early 2025 underlined weight reduction and reliability as core differentiators, reinforcing a narrative that has clear resonance in both new aircraft and retrofit discussions.
-
Collins Aerospace, part of RTX offers integrated air management solutions that include cabin pressurisation and control, with outflow valves, cabin pressure controllers, and safety valves available in both electric and pneumatic configurations. Its coverage across commercial, military, fixed-wing, and helicopter platforms makes it a broad-spectrum contender in the pressurisation value chain. A next-generation cabin pressure control system introduced in 2024 emphasised enhanced health monitoring and longer service intervals, pointing toward the serviceability and uptime arguments that increasingly influence airline purchasing criteria.
-
Safran Group supplies cabin pressure control systems focused on accurate, automatic pressurisation with fully automatic operation designed to reduce pilot workload. Its emphasis on proprietary controller algorithms and internal test labs for performance verification and certification highlights the role of software-defined control and in-house qualification capability in maintaining competitive differentiation.
-
Liebherr-Aerospace delivers integrated air management systems that incorporate cabin pressure control as part of broader bleed air, air conditioning, and environmental control solutions for commercial and business aircraft programmes. Its strength lies in the integration perspective—positioning pressurisation not as an isolated component but as part of a complete environmental architecture.
The competitive field also includes several strategic specialists and component-focused firms.
-
ACE Thermal Systems, under Signia Aerospace , specialises in automated cabin pressurisation systems with an auto-schedule controller that integrates with flight management systems, reducing pilot input and trimming weight and installation costs for advanced aircraft performance requirements. This positions the company at the interface of automation and programme cost-efficiency.
-
Aeronamic develops electric cabin pressurisation systems and high-speed electric compressors with oil-less air-foil bearings, aligned with more-electric and electric aircraft concepts. Its inclusion of smoke evacuation and health monitoring illustrates how pressurisation subsystems are being reimagined as multi-function, safety-integrated solutions.
-
Moog Inc. provides components and valves for environmental control and life support systems that support cabin pressurisation, including high-pressure oxygen isolation valves and low-pressure cabin atmosphere control valves. Its role underscores how component-level precision and fluid/gas management expertise remain vital to the overall system.
-
Parker Aerospace, part of Parker Hannifin , supplies bleed air control systems and components supporting cabin pressurisation, with valves and electronic controllers for flow and temperature management in turboprop and other aircraft. This reflects the continued relevance of bleed air management even as electric architectures expand.
The competitive story is not only about who has the largest share; it is about who is advancing the right combination of weight reduction, automation, health monitoring, electric integration, and certification depth at the right moment in the aircraft cycle. The report maps these capabilities against the market structure so that readers can see where each competitor is strongest and where headroom remains.
What the Report Delivers for Operational Decision-Making
This market research is built to support real operating decisions, not just strategic narrative. It is structured to be usable across several planning horizons and functional teams.
-
Sizing and forecasting: The report provides market size and forecast data across the relevant timeline, enabling demand planning for content, components, and aftermarket support. Because pressurisation is tied to fleet mix and programme timing, the forecast logic is presented so that users can test assumptions about new aircraft deliveries, retrofits, and replacement cycles.
-
Segmentation clarity: Regional, aircraft-type, and component-level segmentation is provided to help readers identify where content growth is concentrated and where the economics differ most. The intention is to support sourcing decisions, pricing strategy, and business development targeting with a clear map of the opportunity landscape.
-
Competitive profiling: Detailed company profiles and recent developments give readers a practical view of supplier positioning, product evolution, and move timing. Rather than treating competitors as static names, the analysis connects product releases and technology claims to the broader market direction.
-
Regulatory and technology integration: The report folds in the regulatory and architectural context so that compliance and technology trends are evaluated as part of the market dynamic, not as separate commentary. This makes it easier to judge how technology shifts such as electric pressurisation and cabin environment quality concerns will alter content demand over time.
-
Strategic synthesis: Above all, the report translates market data into decision frameworks—where to invest in capability, where to watch substitution risk, where to align aftermarket planning, and where to position for programme wins in an increasingly concentrated market.
These elements are designed to work together. A procurement lead can use the segmentation detail to refine vendor shortlists; a business development team can use the competitive profiles to identify white space and timing; an engineering manager can use the technology and regulatory context to anticipate qualification effort and architecture trade-offs; and an investor or strategist can use the forecast arc to understand where value creation is likely to concentrate.
Reading the Signals for 2026 and Beyond
Several strategic signals stand out when the market is read as a whole.
First, pressurisation content demand is on a durable growth path, but the shape of that growth is uneven across platforms and regions. This means the highest-value moves will come from understanding the mix, not just the total. Organisations that map their own pipeline to the underlying aircraft-type and regional patterns will be better placed to anticipate content timing and avoid over-committing to segments with thinner economics.
Second, technology differentiation is increasingly tied to digital and electric capabilities. Weight reduction, brushless and electric actuation, automated control logic, health monitoring, and integration with flight management systems are all coming into sharper focus as platforms pursue more-electric architectures and operators push for lower maintenance burden. Suppliers and platform teams alike need to decide how aggressively to invest in these directions, because the transition is not uniform across the fleet.
Third, regulation remains a powerful driver of design discipline and long-term demand. Cabin altitude protection, pressure relief redundancy, and ongoing attention to air quality and contamination risk create both a compliance floor and a pressure to improve. As expectations around cabin environment quality evolve, pressurisation and environmental control become even more central to platform value propositions.
Fourth, market concentration means competitive positioning matters. With a meaningful share held by a small group of large players, access to content, certification support, and aftermarket presence is not equally distributed. This does not make the market inaccessible to smaller or specialist firms, but it does raise the importance of clear differentiation—whether through electric compression technology, automation, integration breadth, or targeted niche platforms.
Aviation Oxygen Systems Market
Conclusion: From Market Intelligence to Boardroom Action
The Worldwide Aircraft Pressurisation Systems Market research is built for the moment when strategic questions outpace general industry commentary. It takes a market that is often discussed in parts—components, platforms, regions, regulations—and turns it into a single, decision-ready view of where demand is going, who is shaping it, and what that means for 2026 planning.
The headline figures tell a compelling story: a market that has grown from around USD 6.1 billion in 2020 to about USD 8.45 billion in 2025, with a forecast rise to roughly USD 9.15 billion in 2026 and continued expansion toward nearly USD 13.0 billion by 2032 at a CAGR of approximately 6.32%. But the strategic value lies beneath the totals—in the component logic, aircraft-type economics, regional concentration, regulatory drivers, and competitive moves that determine which organisations capture value and which merely observe it.
For executives, procurement teams, programme managers, and investors who need a sharper lens on this subsystem, the full report provides the segmentation detail, company-level intelligence, and forecast reasoning required to move from observation to action. The market is expanding, the technology is evolving, and the competitive field is consolidating around integrated, digital, and increasingly electric solutions. The organisations that decode these patterns early will be the ones best positioned to win content, manage risk, and shape their pressurisation strategy for the decade ahead.
Worldwide Aircraft Pressurisation Systems Market
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Pressurisation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gluten-Free Baking Flour Market to Reach $9.12 Billion by 2032 at 8.35% CAGR
By pmarketresearch, 2026-09-16
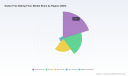
The Strategic Imperative: Navigating the Gluten-Free Baking Flour Market in 2026
The global gluten-free baking flour market has transitioned from a niche consumer segment to a mainstream pillar of food and beverage strategy. As we enter 2026, corporate decision-makers face a landscape defined by accelerating product innovation, stringent regulatory oversight, and shifting distribution paradigms. Our latest comprehensive study delivers the analytical rigor required to navigate this transformation, offering a detailed view of market trajectories, competitive dynamics, and operational imperatives that will shape the next wave of enterprise growth.
For executives, procurement leaders, and R&D strategists, the question is no longer whether gluten-free baking flours represent a viable expansion avenue, but how to position portfolios against a backdrop of structural demand growth and intensifying competition. This introductory piece outlines the strategic architecture of our research, highlights the macro drivers powering the sector, and provides a preview of the actionable intelligence embedded within our full 2026 market assessment. Readers seeking granular segmentation metrics, proprietary forecasting models, and company-level financial benchmarks are invited to access the complete report for end-to-end strategic planning.
Macro Trajectory: Sustained Expansion and Structural Demand Drivers
The historical footprint of the gluten-free baking flour market reveals a clear and consistent upward trajectory. From a baseline valuation of approximately 3.5 billion USD in 2020, the sector has demonstrated annual expansion that has consistently outperformed broader food ingredient benchmarks. By 2025, market valuation reached a pivotal inflection point, surpassing 5.2 billion USD, as consumer adoption, retail assortment breadth, and manufacturer capacity investments converged to reinforce momentum.
Looking ahead, our baseline forecast paints a robust picture of long-term value creation. Revenue projections indicate sustained annual growth that will push the total market valuation beyond 9 billion USD by the close of the forecast horizon in 2032. This expansion is underpinned by a compound annual growth rate of 8.35 percent, reflecting a blend of volume-driven consumer uptake, premiumization within specific flour categories, and the progressive integration of gluten-free formulations into broader retail and foodservice offerings.
Several structural forces are converging to sustain this trajectory. Dietary preference shifts continue to normalize gluten-free consumption beyond medically mandated populations, with wellness-driven consumers, food-sensitive demographics, and label-conscious households expanding the addressable base. Simultaneously, manufacturers have invested heavily in formulation science, improving texture, sensory appeal, and processing reliability, which has lowered historical barriers to repeat purchase and mainstream shelf placement. Supply chain maturation and ingredient availability improvements further reinforce scalability, while digital commerce channels continue to accelerate product discovery and direct-to-consumer testing cycles.
For enterprise strategy, this macro backdrop carries clear implications. Demand growth is no longer dependent on a single consumer archetype or retail format. Instead, it reflects a diversified consumption ecosystem where bakery brands, private-label operators, ingredient suppliers, and foodservice operators each contribute to volume expansion. Our research dissects these interlocking demand streams to help organizations identify the highest-probability growth vectors and align capacity, marketing, and product development accordingly.
Architecture of the Study: Operational Intelligence for 2026 Decision-Making
A market research report is only as valuable as its ability to translate observation into action. Our publication is structured around a set of operational pillars designed to serve different functional teams within the enterprise. Rather than offering a high-level narrative, the study delivers granular, testable, and immediately applicable intelligence that supports budgeting, forecasting, competitive positioning, and risk management.
Worldwide Gluten-free Baking Mixes Market
At the core of the study is a multi-year historical reconstruction (spanning 2020 through 2025) paired with a forward-looking forecast window extending to 2032. This temporal architecture enables clients to validate past assumptions, measure deviation from prior projections, and anchor 2026 planning cycles in empirically grounded growth curves. The analysis also integrates ingredient-level context, including the role of staple base flours in formulation strategy, price differentials within premium versus standard ingredient tiers, and the implications of raw material availability on product economics.
Beyond top-line valuation, the study maps the ecosystem of commercial pathways. It examines how distribution architectures have evolved, where volume concentration persists, and how retail execution, e-commerce acceleration, and specialty retail positioning interact to shape accessibility. Regulatory context is also woven into the narrative framework, with particular attention to labeling compliance thresholds, cross-contact prevention expectations, and the operational burden these requirements place on manufacturing facilities, quality teams, and brand communications.
Gluten-Free Baking Flour Market
To ensure practical relevance, the report includes scenario-ready analytical tools. These are designed to help teams model the impact of input cost variability, assess the sensitivity of portfolio performance to channel mix shifts, and evaluate the strategic trade-offs between premiumization and mass-market accessibility. The objective is not simply to describe the market, but to equip leaders with a structured framework for testing assumptions before committing capital.
Throughout the document, data is presented with discipline. Percentage splits, regional revenue shares, and specific segment valuations are reserved for the full reference edition, enabling the complete study to function as a secure internal planning asset. This controlled disclosure model ensures that clients who acquire the report receive comprehensive analytical depth without dilution, while public-facing summaries preserve strategic ambiguity and encourage deeper engagement with the full dataset.
Competitive Landscape: Established Incumbents and Emerging Positioning Tactics
The competitive architecture of the gluten-free baking flour market is defined by a mix of consumer-facing brands, ingredient and commodity-scale suppliers, and specialty formulation specialists. This layered structure creates a highly interactive environment where upstream ingredient availability, midstream formulation capability, and downstream brand positioning all influence market share dynamics.
Among the most visible consumer-facing players, several organizations have built recognizable positions through dedicated gluten-free manufacturing infrastructure and formulation parity with conventional baking expectations. Companies offering 1-to-1 substitution blends, specialty grain combinations, and certified production environments have capitalized on consumer demand for convenience and baking predictability. In parallel, large diversified food manufacturers have advanced accessibility by embedding gluten-free baking solutions within established retail brands, expanding shelf visibility and leveraging existing distribution footprints.
On the ingredient and supply side, major commodity and specialty grain operators continue to play an essential role. Their bulk supply capabilities, starch and rice-based ingredient portfolios, and commercial baking ingredient programs support downstream manufacturing at scale. These suppliers are particularly influential for private-label development, foodservice applications, and mid-tier brands that depend on reliable raw material access and formulation support. Specialty milling and ancient grain-focused operators further enrich the ecosystem by introducing texture-forward blends and retail-oriented baking mixes that differentiate on perceived quality and ingredient narrative.
Market concentration data indicates that consolidated leadership exists but remains measured. The competitive field is not dominated by a single monolithic entity; rather, it features a distribution of strength across consumer brands, ingredient suppliers, and formulation specialists. This dispersed structure creates opportunities for targeted positioning, whether through innovation in premium blends, expansion into underserved retail formats, or strategic cost optimization in high-volume base ingredients.
Recent operational events also underscore the importance of process integrity. A notable 2025 recall involving voluntary action related to undeclared allergen cross-exposure highlights the persistent sensitivity of the category to quality control, labeling accuracy, and manufacturing discipline. For brands and ingredient suppliers alike, compliance is not merely a regulatory formality; it is a market trust mechanism that directly affects retail relationships, consumer confidence, and long-term portfolio resilience.
The strategic takeaway for 2026 is that competitive advantage will increasingly derive from a combination of formulation reliability, regulatory readiness, supply consistency, and channel execution. Our full study evaluates these variables at the company and portfolio level, providing context that supports benchmarking, partnership assessment, and competitive threat mapping.
Regulatory and Supply Chain Dynamics: Risk, Compliance, and Formulation Strategy
The regulatory environment continues to shape the commercial reality of gluten-free baking flours in both subtle and structural ways. Labeling standards that define permissible gluten thresholds remain a baseline requirement for market entry and sustained shelf eligibility. Beyond the headline compliance number, manufacturers must also contend with operational expectations around cross-contact prevention, facility segregation, and documentation rigor. Attention to these practices is intensifying, and comment periods and regulatory engagement in 2026 signal continued scrutiny of manufacturing controls that affect product integrity.
For R&D and quality functions, this environment reinforces the value of formulation discipline and traceability. The category’s dependence on base ingredients with distinct functional properties means that substitution decisions, blending ratios, and processing conditions carry both sensory and compliance implications. Ingredient selection also has direct economic consequences. Premium-tier materials can command meaningful price premiums and may deliver superior texture outcomes, but they also introduce cost volatility that must be managed through portfolio architecture, sourcing strategy, and consumer value communication.
Supply chain considerations extend further into the raw material ecosystem. Base ingredient markets associated with common gluten-free blends exhibit their own size, growth patterns, and end-use dynamics. White rice flour, for example, maintains prominence in many formulations because of its neutral flavor profile and functional compatibility, while almond-based ingredients occupy a distinct premium niche with texture and cost characteristics that influence product positioning. Understanding these dynamics is essential for organizations that aim to develop blends that are both commercially attractive and economically sustainable across fluctuating input conditions.
The interplay between regulatory expectations, ingredient economics, and consumer quality expectations creates a demanding optimization problem. Our study addresses this by connecting compliance frameworks to formulation choices, channel economics, and brand communication strategy. Rather than treating regulation as an external constraint alone, the analysis frames it as a strategic design parameter that can differentiate compliant, credible products in a crowded market.
Implications for 2026 Strategy: Portfolio Positioning, Channel Mix, and Capital Allocation
As enterprises plan for the remainder of 2026 and beyond, the gluten-free baking flour market rewards organizations that integrate demand forecasting with operational realism. Several strategic priorities stand out.
First, portfolio architecture must reflect the reality that consumer expectations have expanded beyond simple gluten removal. Products that deliver baking reliability, sensory parity, and ingredient transparency are better positioned to command repeat purchase and premium price acceptance. At the same time, mass-market accessibility remains a growth engine. The most resilient strategies often combine a premium flank with a scalable core offering, supported by clear brand hierarchy and distinct formulation value propositions.
Second, channel strategy should be treated as a growth variable rather than a static deployment plan. Retail execution, e-commerce discovery, and specialty store presence each serve different consumer journeys and margin profiles. Understanding where volume concentrates, how digital channels accelerate trial, and how retail breadth translates into repeat purchasing enables more precise resource allocation. Organizations that map channel economics to product tiers can better balance coverage, availability, and margin protection.
Third, sourcing and formulation strategy must be aligned with both cost discipline and quality assurance. Ingredient volatility, premium material pricing differentials, and process controls all influence margin performance and brand trust. Companies that build flexibility into supplier relationships, establish formulation guardrails, and maintain rigorous compliance documentation are better equipped to manage disruption and sustain shelf eligibility.
Fourth, competitive strategy requires disciplined monitoring of both consumer brands and upstream ingredient suppliers. Because the market spans formulation specialists, diversified food manufacturers, and commodity-scale suppliers, competitive threat and partnership opportunities can emerge from multiple directions. Strategic planning should therefore incorporate benchmarking, capability assessment, and scenario testing to determine where to compete, where to collaborate, and where operational efficiencies can be captured.
Finally, 2026 planning should treat the forecast horizon as a decision framework rather than a fixed prediction. Growth trajectories, input markets, regulatory discussion, and channel evolution all carry uncertainty. Organizations that build scenario-based models around base, upside, and downside assumptions will be better prepared to adjust capacity commitments, marketing investment, and product launches as conditions evolve.
Conclusion: From Market Intelligence to Strategic Execution
The gluten-free baking flour market in 2026 presents a rare combination of scale, momentum, and strategic complexity. Demand is structurally supported, formulation capability has matured, and competitive intensity continues to reward organizations that can align product quality, compliance integrity, supply reliability, and channel execution. At the same time, the category’s breadth and dynamism require deeper intelligence than headline figures can provide.
This overview has been designed to demonstrate the caliber and scope of our research while preserving the specific analytical assets that make the full report an operational asset. Detailed segmentation metrics, regional and channel-level revenue distributions, source-specific evaluations, and company-level competitive profiling are integrated throughout the complete study, providing the depth necessary for confident internal planning. Those metrics are intentionally withheld here to preserve the report’s strategic distinction and to guide decision-makers toward the full edition for precision benchmarking and multi-year forecasting.
For organizations preparing capital allocation decisions, product roadmap reviews, sourcing strategy revisions, or competitive positioning refreshes, our 2026 Gluten-Free Baking Flour Market study offers a structured, evidence-based foundation. The full report delivers the data density, analytical context, and scenario-ready frameworks needed to convert market awareness into executable strategy. Access the complete publication to obtain the detailed intelligence required to plan with confidence across the remainder of the forecast horizon and beyond.
For detailed analysis of this topic, please visit the official page: Gluten-Free Baking Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Vibration Isolation Market to Reach $8.2B by 2032, Growing at 6.51% CAGR
By pmarketresearch, 2026-09-16
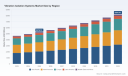
Navigating Precision: Strategic Intelligence for the Global Vibration Isolation Systems Market Through 2032
In an industrial landscape increasingly defined by nanometer-level manufacturing tolerances, stringent operator safety regulations, and the relentless push toward automation, vibration isolation has evolved from a passive engineering afterthought into a critical strategic infrastructure component. The Worldwide Vibration Isolation Systems Market is currently experiencing a period of disciplined growth, propelled by cross-sectoral demands for precision, compliance, and operational longevity. Our latest comprehensive research publication, Worldwide Vibration Isolation Systems Market , offers a rigorously structured blueprint for navigating this evolving ecosystem. Designed for executive leadership, R&D directors, procurement strategists, and competitive intelligence teams, this study translates macroeconomic trajectories, regulatory shifts, and technological inflection points into actionable decision frameworks for the 2026–2032 horizon.
The market's foundational trajectory reflects a steady compound annual growth rate of 6.51 percent throughout the forecast period, building upon a robust historical baseline that tracks consistent capital allocation and engineering modernization across multiple industrial verticals. Revenue in the base year of 2025 reached a substantial inflection point, continuing an upward momentum that positions the sector for sustained expansion into the next decade. Rather than relying on speculative projections, this analysis anchors its forward-looking models in empirically validated consumption patterns, capacity utilization data, and capital expenditure cycles. The result is a reliability-focused intelligence asset that enables stakeholders to align product roadmaps, supply chain configurations, and geographic prioritization with measurable market realities.
Market Architecture and Structural Demand Drivers
The contemporary vibration isolation ecosystem is shaped by an intersection of engineering precision requirements, material science advancements, and evolving compliance mandates. Raw material dynamics play an increasingly pivotal role in cost architecture and supplier negotiation strategies. Recent supply chain assessments indicate that natural rubber benchmark pricing has experienced notable year-over-year appreciation, driven by weather-related agricultural disruptions across Southeast Asian production hubs. Concurrently, synthetic elastomer markets have demonstrated relative price stabilization, supported by consistent petrochemical feedstock availability. These material flow fluctuations directly influence isolator manufacturing economics, forcing OEMs and tier-one suppliers to recalibrate inventory hedging, alternative material qualification, and proprietary compound development timelines.
Regulatory evolution further compounds the strategic complexity of market participation. Updated international vibration severity standards introduced measurement thresholds that mandate stricter velocity limitations for industrial machinery classifications. Simultaneously, the European Union's recent machinery directive framework has enforced tighter operator exposure limits, effectively raising the compliance floor for equipment deployed across manufacturing, energy generation, and heavy industrial environments. These regulatory catalysts are not merely compliance checkboxes; they represent structural demand accelerators that compel end-users to retrofit legacy installations and integrate higher-performance isolation architectures during new facility builds.
The report dissects these macro drivers through a multi-layered analytical lens, mapping how regulatory thresholds interact with sector-specific performance requirements. By isolating the causal relationships between compliance mandates, equipment lifecycle cycles, and procurement decision-making units, the study provides a clear framework for anticipating demand surges, evaluating retrofit versus greenfield investment ratios, and positioning product portfolios ahead of regulatory enforcement timelines.
Technological Divergence and Application Intelligence
Vibration isolation technology has bifurcated into distinct performance paradigms, each serving specialized operational environments with unique engineering constraints. Passive isolation architectures continue to dominate volume deployment, leveraging mature elastomeric formulations, mechanical spring geometries, and optimized structural damping characteristics to address broad-spectrum industrial requirements. These systems benefit from established supply chains, predictable lifecycle costs, and widespread engineering familiarity, making them the default choice for high-volume machinery, HVAC infrastructure, and conventional manufacturing equipment.
Active and semi-active isolation platforms, meanwhile, represent the high-growth frontier of the market. Utilizing real-time sensor feedback, adaptive damping media, and magnetorheological or pneumatic actuation mechanisms, these systems deliver dynamic disturbance cancellation capable of protecting ultra-sensitive instrumentation, precision manufacturing stages, and advanced research environments from low-frequency structural transmission. Recent industry milestones underscore the velocity of this technological maturation. Notable advancements include the introduction of hybrid elastomer-air spring isolators engineered specifically for precision manufacturing floors, the certification of adaptive fluid-based isolation platforms under updated quality management standards, and the demonstration of next-generation low-frequency damping materials at premier vibration engineering conferences. Additionally, hybrid composite pad architectures tailored for high-load industrial compressors have gained visibility through major industrial trade exhibitions, signaling cross-pollination between heavy machinery requirements and cleanroom-grade isolation performance.
Application-side demand patterns reveal a highly segmented consumption profile. Semiconductor and electronics manufacturing continues to drive some of the most stringent isolation specifications, where sub-micron process stability depends on eliminating micro-vibrational noise from substrate handling, lithography stages, and inspection equipment. Healthcare and life sciences environments impose parallel requirements, particularly in diagnostic imaging suites, bioprocessing containment zones, and precision laboratory instrumentation, where signal integrity and operator safety are equally paramount. Aerospace and defense applications maintain a steady demand curve driven by ground testing infrastructure, propulsion system validation, and sensitive avionics calibration environments. Precision industrial and automotive sectors leverage isolation architectures for high-tonnage presses, generator arrays, and powertrain validation rigs, while scientific research and academic laboratories increasingly specify custom-tuned isolation platforms for advanced microscopy, quantum measurement apparatus, and nanomechanical testing facilities. The research comprehensively maps these application vectors, evaluating procurement cadence, specification complexity, and technology adoption sensitivity without exposing granular volumetric allocations that are reserved for the full analytical dataset.
Worldwide Vibration Isolation Systems Market
Competitive Landscape and Strategic Positioning
The market's competitive architecture reflects a blend of entrenched engineering conglomerates, specialized elastomer innovators, and region-focused solution providers. Leading participants maintain competitive advantage through proprietary material formulations, application-specific tuning expertise, and deep integration with end-user engineering workflows. Swedish industrial technology groups have expanded their isolation portfolios across marine, aerospace, and heavy machinery domains, leveraging advanced elastomeric mounting systems and anti-vibration platform designs. American specialty manufacturers have reinforced their positions in automotive, defense, and heavy equipment segments through viscoelastic damping technologies, hydraulic isolation mounts, and custom-engineered isolator platforms. Austrian material science specialists continue to differentiate through proprietary elastomer-based structural damping solutions deployed in building infrastructure, rail networks, and industrial machinery. French engineering organizations contribute complementary technology lines spanning rubber-metal mounting configurations, wire rope isolators, and active control architectures, with dedicated sub-brands focusing on industrial press isolation, generator stabilization, and precision machinery support.
Additional competitive activity spans North American, European, and Asian manufacturing ecosystems, with participants delivering laminated fabric damping solutions, modular isolation assemblies, machinery leveling systems, and hydraulic chassis isolation platforms. Japanese industrial component leaders emphasize rubber isolator networks, air spring architectures, and comprehensive noise-vibration-harshness solutions for construction equipment and rail applications, while major tire and materials corporations extend their isolation expertise into seismic bearing systems, industrial plant stabilization, and earthquake-resilient machinery foundations. The competitive intensity in this space is moderated by a moderately concentrated market structure, where top-tier participants collectively command a significant but non-dominant share, leaving substantial room for regional differentiation, application-specific specialization, and technology-led market entry.
Our analysis evaluates competitive positioning across multiple strategic dimensions, including technology roadmapping, certification trajectories, supply chain resilience, and cross-sectoral application expansion. Recent corporate developments, including certification renewals for adaptive isolation platforms, trade show demonstrations of low-frequency damping innovations, and product launches targeting hybrid isolation architectures, are contextualized within broader market signaling patterns. These events are not isolated product announcements; they represent strategic indicators of where engineering investment is flowing, which performance thresholds are becoming commercially viable, and how incumbents are defending or expanding their addressable footprints. The full report provides detailed competitor profiling, capability benchmarking, and strategic response mapping, enabling organizations to identify partnership opportunities, anticipate competitive countermeasures, and refine go-to-market positioning.
Regulatory Catalysts, Supply Chain Realities, and Risk Navigation
Strategic market participation requires a clear understanding of the regulatory and material risk vectors that shape procurement cycles and engineering specifications. Beyond the aforementioned vibration severity updates and operator exposure directives, compliance frameworks are increasingly demanding traceability, performance verification, and lifecycle documentation for isolation components deployed in regulated environments. This document-driven compliance burden elevates the importance of supplier qualification rigor, quality management certification, and long-term material availability commitments. Procurement teams are consequently placing greater weight on supplier stability, formulation transparency, and documented testing protocols when evaluating isolation system partners.
Simultaneously, raw material supply volatility introduces pricing uncertainty that can compress margins or delay project timelines if not proactively managed. Organizations that integrate material price forecasting, alternative compound qualification, and multi-source procurement strategies into their isolation architecture planning will secure measurable cost and schedule advantages. The research publication addresses these dynamics through scenario-based sensitivity modeling, evaluating how fluctuations in elastomer pricing, petrochemical feedstock availability, and logistics constraints influence total cost of ownership across different isolation configurations. By separating transient price noise from structural material demand shifts, the study equips decision-makers with the analytical discipline needed to negotiate contracts, hedge inventory exposure, and align engineering specifications with realistic supply conditions.
What the Full Report Delivers
While this overview establishes the strategic perimeter of the market opportunity, the complete research publication delivers a granular, execution-ready intelligence package designed for cross-functional deployment. Stakeholders who access the full dataset will gain access to:
- Comprehensive market sizing and forward-looking revenue projections calibrated across multiple forecast intervals, enabling capital allocation planning and growth target validation
- Detailed segmentation analysis across isolation technology architectures, application environments, and geographic consumption patterns, providing the structural visibility required for product portfolio alignment and regional sales resource deployment
- Competitive benchmarking frameworks that evaluate market positioning, technology specialization, and strategic maneuvering across leading participants, facilitating competitive response planning and partnership identification
- Regulatory impact mapping that translates updated vibration severity standards and machinery exposure directives into procurement timelines, specification requirements, and retrofit demand projections
- Material cost and supply chain sensitivity analysis that connects raw material price trajectories to isolator manufacturing economics, helping procurement and engineering teams optimize specification choices and sourcing strategies
- Recent industry development tracking that contextualizes product launches, certification milestones, and conference demonstrations within broader technology adoption cycles and competitive signaling patterns
- Strategic recommendation modules that translate analytical findings into actionable guidance for R&D prioritization, market entry evaluation, capacity planning, and commercial positioning
The report is structured to serve multiple organizational functions simultaneously. Executive leadership can utilize the macro trajectory analysis and regulatory impact assessments to validate long-term investment theses and geographic expansion priorities. Engineering and product management teams can leverage segmentation depth and technology positioning frameworks to refine specification roadmaps and identify performance gaps in existing solution portfolios. Commercial and sales leadership can apply competitive positioning insights and application demand mapping to optimize territory planning, vertical-specific messaging, and customer engagement strategies. Procurement and supply chain stakeholders can draw on material cost sensitivity analysis and supplier qualification frameworks to strengthen sourcing resilience and negotiate from an informed position.
Strategic Imperatives for 2026 Decision-Making
The vibration isolation market does not reward reactive positioning. Organizations that treat isolation systems as commoditized accessories risk underperformance in precision-sensitive applications, compliance exposure in regulated environments, and margin erosion in material-volatile procurement cycles. Conversely, firms that integrate vibration control strategy into broader engineering, compliance, and commercial planning will capture disproportionate value from the sector's disciplined growth trajectory. The six-percent-plus compound growth rate projected through the early 2030s is not merely a statistical indicator; it reflects a structural realignment of industrial priorities toward stability, precision, and operator protection. Capital expenditure programs, regulatory enforcement timelines, and technology maturation curves are synchronizing in a way that creates clear windows of opportunity for suppliers, system integrators, and end-users who act with analytical clarity.
Our research publication is designed to convert that opportunity into executable strategy. By revealing the market's structural architecture, competitive undercurrents, regulatory catalysts, and material reality checks, the study provides the evidentiary foundation required for confident decision-making in 2026 and beyond. The macro trajectory, segmentation dimensions, competitive intelligence, and application-specific demand mapping presented here represent only the analytical perimeter. The complete intelligence framework, including granular regional consumption breakdowns, application-level revenue distributions, technology-segment growth differentials, and detailed competitor strategy assessments, is reserved for the full report.
Seismic Isolation Systems Market
Organizations seeking to align product development pipelines, refine commercial positioning, optimize procurement strategies, or evaluate market entry pathways will find that the depth of analysis required for high-stakes planning extends well beyond aggregated market summaries. The full publication delivers that depth, structured for immediate integration into strategic planning cycles, investment committee briefings, and cross-functional execution roadmaps. Precision engineering, regulatory compliance, and material supply resilience will continue to define competitive advantage in this sector. Access to the complete research dataset ensures that your organization navigates those variables with verified intelligence rather than directional assumption.
For detailed analysis of this topic, please visit the official page: Worldwide Vibration Isolation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Vacuum Ovens Market Hits $296M in 2025, Projects 4.81% CAGR to 2032
By pmarketresearch, 2026-09-16
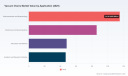
Strategic Horizons 2026: Navigating Growth in the Global Vacuum Ovens Market
Executive Summary: A Market at an Inflection Point
The global vacuum ovens market stands at a critical juncture as we move through 2026. For strategic planners, procurement officers, and R&D directors, understanding the trajectory of this equipment sector is no longer optional—it is a prerequisite for operational resilience. Our latest research, Worldwide Vacuum Ovens Market, provides a comprehensive forensic analysis of the industry landscape, offering the intelligence necessary to navigate the complexities of the forecast period extending through 2032.
The urgency for updated market intelligence stems from a confluence of factors: shifting regulatory frameworks, evolving energy efficiency standards, and a resurgent demand for precision drying and baking-out processes across high-stakes industries. Companies that rely on outdated data risk misalignment with supply chain realities and competitive dynamics. This research is designed to bridge that gap, transforming raw data into actionable strategy.
Market Trajectory and Growth Dynamics
The financial outlook for the vacuum ovens sector indicates steady, compounding growth. Our analysis tracks the market evolution from a base year of 2025, projecting forward to 2032. The historical data from 2020 to 2025 reveals a market that has demonstrated resilience despite global supply chain disruptions. Starting from a valuation of approximately 236.4 million USD in 2020, the sector has navigated fluctuations to reach an estimated 296.0 million USD by 2025.
Looking ahead, the momentum continues. The market is projected to inch toward 299.72 million USD in 2026, marking the beginning of a significant expansion phase. Over the forecast period, the market value is expected to climb substantially, reaching 411.25 million USD by 2032. This trajectory reflects a Compound Annual Growth Rate of 4.81 percent. While this rate may appear moderate in isolation, within the context of specialized laboratory and industrial equipment, it signifies a healthy, sustained demand driven by underlying technological and industrial shifts rather than speculative bubbles.
- Historical Resilience: The market absorbed shocks between 2020 and 2025, stabilizing significantly by 2024.
- Forecast Confidence: The growth path from 2026 to 2032 suggests consistent capital investment in drying technologies.
- Value Expansion: The nearly doubling of market value over the forecast horizon indicates expanding capacity and higher value unit sales.
Segmentation Overview: Type, Application, and Regional Nuances
Understanding where and how this growth occurs is vital for targeted strategy. Our report dissects the market into critical dimensions without overwhelming the decision-maker with noise. A fundamental split exists between Benchtop Vacuum Ovens and Floor-standing Vacuum Ovens. These segments serve distinct needs; benchtop units cater to high-volume laboratory workflows requiring precision and footprint efficiency, while floor-standing models address industrial-scale processing demands where throughput is paramount.
On the application front, the demand drivers are diverse. Pharmaceuticals and Biotechnology represent a cornerstone of demand, relying on vacuum ovens for moisture removal and drying of temperature-sensitive samples. Simultaneously, the Electronics and Semiconductors sector utilizes these systems for critical outgassing testing and bake-out processes to prevent contamination in sensitive materials. Aerospace and Defense, along with Academic and Research Institutes, round out the core application bases, each imposing unique regulatory and performance requirements on equipment manufacturers.
Regional analysis in the report highlights distinct maturity levels across geographies. North America and Europe maintain strong footholds rooted in established industrial bases, while Asia Pacific shows significant volume potential driven by expanding manufacturing clusters. Latin America and the Middle East and Africa present emerging opportunities where infrastructure development is accelerating equipment adoption. The report provides a detailed breakdown of these regional dynamics to help stakeholders prioritize geographic focus.
- Equipment Configuration: Strategies must differ between supporting modular benchtop units versus large capacity floor-standing infrastructure.
- Sector-Specific Needs: Regulatory compliance for pharmaceuticals differs vastly from the performance criteria required in aerospace defense.
- Geographic Prioritization: Resource allocation should reflect the maturity and growth potential of specific regional markets.
Competitive Landscape: Key Players and Strategic Positioning
The market is characterized by a mix of established European engineering firms, specialized American manufacturers, and emerging players expanding their footprint. Understanding the competitive hierarchy is essential for benchmarking and partnership strategies. Our report profiles the key entities shaping the industry, analyzing their product portfolios, geographic strengths, and technological differentiators.
Among the notable leaders, BINDER GmbH and Memmert GmbH + Co. KG stand out for their specialized focus on vacuum drying ovens with precise temperature control and energy-efficient vacuum pumps. These German manufacturers emphasize safety features and versatility across flammable and non-flammable solvents. In the North American market, companies like Terra Universal, Inc. and WEISS TECHNIK NORTH AMERICA, INC. provide critical environment-compatible equipment and ISO 9001 certified solutions for aerospace and automotive sectors.
Other significant contributors include Across International and Cascade TEK, which focus on large capacity models and automated high-vacuum processes for laboratory and industrial use. BEING Scientific Inc. offers distribution-focused solutions for temperature-sensitive samples, while Italvacuum S.r.l. brings over 75 years of vacuum technology experience to chemical and pharmaceutical production. T-M Vacuum Products, Inc. and Carbolite Gero cater to specialized high-temperature and thin film deposition applications, serving niche but high-value segments.
The competitive structure shows a moderately concentrated landscape. The top three companies hold a combined market share of 28.5 percent, while the top five control 41.2 percent. This fragmentation suggests room for niche players to thrive while indicating that partnerships or consolidation could reshape the top tier in the coming years.
Worldwide Vacuum Ovens Market
- Technology Leadership: Leaders differentiate through energy efficiency, automated cycles, and material compatibility.
- Regional Strength: Competitors leverage regional headquarters to serve local regulatory and service needs.
- Consolidation Potential: The market concentration ratios suggest potential for M&A activity or strategic alliances.
Industry Dynamics: Materials, Regulations, and Standards
Strategic decision-making requires awareness of the external forces pressuring the market. Raw material costs, specifically stainless steel, play a pivotal role in manufacturing economics. The global stainless steel market, a primary material for vacuum oven chambers, is projected to grow significantly through 2036. With prices remaining range-bound in early 2026, manufacturers must navigate volatility linked to nickel, chromium, and energy costs. Our report integrates these material trends to help forecast cost structures accurately.
Regulatory compliance is another critical vector. Vacuum ovens must adhere to rigorous safety and electromagnetic compatibility standards to access international markets. Standards such as ISO 12100 for machinery safety, IEC 60204-1 for low voltage, and EN 61000-6-2 for EMC are non-negotiable for global market access. Furthermore, technical standards like ASTM E595 govern outgassing testing in vacuum environments, directly impacting processes for electronics and sensitive materials. Companies must ensure their product lines align with these evolving requirements to avoid market exclusion.
Energy efficiency is emerging as a key differentiator. Advanced vacuum insulation technologies are being explored to meet stricter maximum energy consumption limits in both domestic and industrial processing equipment. This shift drives innovation in oven design, favoring manufacturers who can demonstrate lower operational costs over the equipment lifecycle.
- Material Supply Chain: Stainless steel pricing and availability directly influence COGS and margin structures.
- Compliance Horizon: Adherence to ISO, IEC, and ASTM standards is a barrier to entry and a license to operate.
- Sustainability Pressures: Energy-efficient designs are becoming a competitive advantage in procurement decisions.
Recent Developments and Event Intelligence
The market is also influenced by real-time industry activities and trade engagements. Our research incorporates recent developments to capture the pulse of the sector. For instance, industry players actively participated in major trade shows such as the 18th International Vacuum Exhibition held in Shanghai in September 2025, showcasing vacuum drying and related technologies. Such events serve as barometers for technological adoption and regional interest.
Additionally, specific company activities highlight sector focus areas. In April 2026, TAV Vacuum Furnaces presented on optimizing vacuum furnace design for efficient heat treatment at HEAT TREAT MEXICO, signaling continued innovation in thermal processing. Prior to that, Italvacuum S.r.l. showcased vacuum drying equipment for pharmaceutical production at Interphex 2025 in April 2025. These engagements underscore the importance of face-to-face technical validation and the ongoing push toward specialized production capabilities.
Monitoring these events allows stakeholders to gauge competitor focus and emerging technology trends before they appear in annual financial reports.
Strategic Value for 2026 Decision Making
Why does this market research matter specifically for 2026? Because the decisions made this year will reverberate through the supply chain until 2032. Whether you are evaluating vendor partnerships, planning capital expenditure for new laboratory infrastructure, or assessing market entry opportunities, the granular insights provided in this report are indispensable.
We move beyond generic estimates to provide the operational intelligence needed to mitigate risk. By understanding the segmentation splits, competitive positioning, and regulatory headwinds, organizations can allocate resources more effectively. The report serves as a single source of truth, consolidating historical data, forecast models, and qualitative industry analysis into a cohesive strategic document.
For investors, the growth trajectory offers confidence in sector stability. For manufacturers, the competitive landscape analysis reveals whitespace opportunities. For end-users, the segmentation details ensure procurement aligns with specific technical requirements.
- Risk Mitigation: Data-driven insights reduce uncertainty in long-term planning.
- Opportunity Identification: Clear segmentation highlights underserved niches and growth vectors.
- Benchmarking: Competitive profiles allow for realistic assessment of market position.
Conclusion: Accessing the Full Intelligence
The Worldwide Vacuum Ovens Market research is more than a data table; it is a strategic roadmap for navigating a sector defined by precision, compliance, and steady growth. The macro trends are clear, but the true value lies in the detailed segmentation, company-level analysis, and dynamic industry context that cannot be fully enumerated in a summary overview.
Vacuum Atmosphere Furnace Market
To fully leverage the 4.81 percent CAGR opportunity and understand the specific revenue contributions of each region and application type, stakeholders require access to the complete dataset and methodology. The insights discussed here represent the foundation of a much deeper analytical framework designed to support complex decision-making processes.
We invite strategic leaders to explore the full scope of this analysis. Access the complete report to unlock the detailed breakdowns of regional revenues, type-specific growth rates, and comprehensive competitor profiling that will drive your 2026 strategy forward.
For detailed analysis of this topic, please visit the official page: Worldwide Vacuum Ovens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Specialty Ink Revenue Hits $4,522.38M in 2025, Projected 5.24% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the 2026 Landscape: Strategic Intelligence for the Worldwide Specialty Ink Market
The specialty ink industry is undergoing a structural transformation defined by regulatory pressure, raw material volatility, and shifting demand patterns across high-growth applications. For executives navigating procurement, product development, and market expansion in 2026, surface-level market commentary is no longer sufficient. PW Consulting's latest Worldwide Specialty Ink Market research delivers the operative intelligence required to convert macroeconomic signals into actionable commercial strategy.
This briefing provides a strategic overview of the market direction, the operational depth embedded in the full study, and the competitive intelligence framework designed to support board-level decision-making throughout the forecast horizon.
A Market in Structural Transition: The 2026–2032 Trajectory
The specialty ink sector has demonstrated consistent growth momentum across the historical review period, culminating in a total revenue base of approximately 4.52 billion USD in 2025. Building on this foundation, the market is projected to expand steadily through the end of the decade, reaching a valuation of roughly 6.47 billion USD by 2032. This represents a forecast compound annual growth rate of 5.24 percent, a trajectory that underscores durable demand for high-performance, functional, and sustainable ink formulations across both mature and emerging industrial verticals.
It is critical to interpret this growth not as a uniform expansion but as a reallocation of value across product architectures, geographic operating environments, and end-use sectors. The 2026 landscape introduces cross-currents that demand precise segmentation intelligence. Rising pigment and raw material costs are compressing margins and forcing formulation adaptations. Simultaneously, regulatory developments are reshaping compliance requirements for packaging, industrial marking, and consumer-facing applications. Understanding where value is shifting and which technological adaptations command premium positioning requires a granular, data-anchored view that general market commentary cannot provide.
This research distills those dynamics into a clearly structured analytical framework, enabling leadership teams to prioritize investment, assess supplier risk, and align product roadmaps with the most defensible growth pockets across the 2032 horizon.
What the Report Delivers: Operational Intelligence for Executive Decision-Making
The 2026 Worldwide Specialty Ink Market study is designed as a practical decision-support instrument rather than a static market summary. It integrates historical performance data, forward-looking projections, and qualitative market intelligence into a cohesive analytical architecture that can be deployed across commercial, operational, and strategic functions.
Core Analytical Components
- Historical Baseline and Forecast Architecture: A detailed reconstruction of market performance from 2020 through 2025, anchored to a rigorously validated baseline, paired with an explicit 2026–2032 forecast period. This structure allows teams to benchmark internal performance against documented industry trends and stress-test growth assumptions.
- Full Segmentation Mapping: Comprehensive segmentation across product type categories, application verticals, and regional operating environments. Rather than relying on aggregate demand signals, the report isolates the distinct demand drivers, competitive intensity, pricing behaviors, and adoption curves within each segment, giving stakeholders the resolution needed to identify where strategic focus will yield the highest return.
- Competitive Positioning and Market Structure Analysis: An in-depth evaluation of consolidation patterns, market share distribution, and strategic maneuvering among key global and regional players. The study examines how leading manufacturers are differentiating through formulation innovation, sustainability certifications, supply chain resilience, and targeted capacity adjustments, providing a benchmark for competitive positioning.
- Technology and Formulation Landscape: An assessment of the technological shifts reshaping specialty ink portfolios, including the growing significance of UV-curable and energy-curable systems, conductive and functional ink architectures, and specialty formulations engineered for security, color performance, and environmental compliance.
- Regulatory and Raw Material Risk Mapping: A synthesized view of the external pressures currently affecting the industry, from feedstock price volatility and logistics constraints to evolving regulatory frameworks governing chemical substances, packaging safety, and emissions control. This dimension is integrated directly into the forecast logic rather than treated as a standalone appendix.
Practical Deployment for 2026 Planning
The report is structured to support multiple internal workflows. Commercial teams can use the segmentation data to refine territory prioritization and customer targeting. R&D and product management teams can align development pipelines with the highest-potential formulation categories and application trends. Procurement and supply chain leaders can incorporate the market structure and raw material risk dimensions into sourcing strategies and supplier negotiations. Executive leadership can rely on the consolidated market trajectory and competitive analysis to frame capital allocation, partnership decisions, and strategic contingencies.
By presenting macro trends alongside segment-level logic, the study ensures that strategy is informed by both the scale of the opportunity and the specifics of where that opportunity is concentrated.
Worldwide Specialty Ink Market
Competitive Dynamics: Leadership in a Consolidating Market
The worldwide specialty ink market remains moderately to highly consolidated, with the top firms holding a combined share that reflects the scale advantages, formulation expertise, and global distribution networks required to compete at the highest tier. This concentration does not imply a static environment. Rather, it indicates a market in which competitive differentiation is increasingly determined by formulation capability, compliance readiness, and operational agility in the face of input cost volatility.
Leading global players profiled in the study represent a diverse but overlapping field of capability centers. Organizations such as Sun Chemical, operating under DIC Corporation's broader industrial footprint, maintain extensive portfolios spanning digital, UV-curable, low-migration, packaging, and functional inks for security and high-performance applications. Flint Group continues to anchor its strength in flexographic, gravure, and energy-curable formulations for packaging, labels, and commercial printing. Siegwerk emphasizes sustainable, low-migration UV and LED-curable solutions with particular focus on food-contact suitability and flexible packaging. Toyo Ink SC Holdings and Sakata INX extend the influence of Japanese formulation expertise across gravure, flexo, digital, and functional ink categories, while INX International Ink Co. and Fujifilm Ink Solutions Group contribute advanced inkjet and specialty platforms with sustainability-oriented development priorities.
Further down the segmentation spectrum, specialists such as Avient Specialty Inks, Nazdar Ink Technologies, Marabu, Wikoff Color Corporation, Zeller+Gmelin, Hubergroup, and T&K TOKA illustrate the breadth of application-specific and process-specific expertise that sustains competitive intensity across screen, digital, offset, and industrial marking niches. The presence of both broad-line global suppliers and focused specialty manufacturers creates a dynamic environment in which innovation, customization, and regional responsiveness all play central roles.
Recent Competitive Movements Shaping 2026
The competitive field is also being reshaped by concrete operational and market-facing actions taken in late 2025 and early 2026. Several major manufacturers have moved to adjust pricing structures in response to escalating raw material, logistics, and energy costs. In March 2026, Sun Chemical implemented price increases and surcharges across all product divisions, citing geopolitical developments in the Middle East and their impact on energy markets, logistics, and chemical feedstock availability. Around the same period, Flint Group raised prices across packaging ink and coating products due to rising raw material and intermediate costs, transportation pressures, longer lead times, supplier force majeure events, and higher energy expenses.
Beyond pricing, players are investing in formulation credentials and capacity readiness that reinforce long-term positioning. Toyo Ink's Toyochem division secured INGEDE Deinkability Certification for its mineral-oil-free inks in January 2026, a move with clear implications for packaging recyclability and sustainability-based procurement requirements. Earlier, in November 2025, Toyo Ink India expanded its liquid ink production capacity by 1.5 times, illustrating how regional capacity investments are being used to support localized demand and supply resilience. In July 2025, Sun Chemical introduced SunCure Advance ECO UV Inks designed for high-speed presses, reflecting the ongoing push to align curing technology with productivity demands and sustainability goals.
These actions illustrate a broader pattern: competitive advantage in 2026 is being built through the intersection of pricing discipline, certified sustainability performance, capacity alignment, and formulation innovation. The full competitive analysis in the report provides deeper evaluation of how these moves affect market share trajectories, segment positioning, and supplier selection dynamics.
Regulatory, Sourcing, and Cost Pressures Defining the 2026 Operating Environment
Executive strategy for the specialty ink market cannot be separated from the external environment. In 2026, several overlapping pressures are influencing formulation strategies, cost structures, and compliance roadmaps across the industry.
Raw material volatility remains a persistent concern. Rising pigment and input costs are placing pressure on manufacturers to balance margin preservation with competitive pricing, and this environment is intensifying the importance of feedstock diversification, formulation efficiency, and supplier relationship management. The disruption of chemical feedstock flows linked to Middle East conflict has contributed to price volatility and has played a direct role in triggering ink price increases and surcharges across multiple product categories.
Regulatory trajectories are similarly reshaping the operating baseline. The EPA draft Risk Management Rule for CI Pigment Violet 29 has continued through 2026 following industry comments submitted in early 2025, signaling ongoing scrutiny of specific pigment substances. In parallel, Health Canada and Environment and Climate Change Canada published a proposed approach for risk management of PFAS substances in 2025, expanding the compliance landscape for formulators serving or anticipating North American requirements. Meanwhile, US EPA strengthened standards for synthetic organic chemical plants in April 2024, reducing emissions of toxic air pollutants and affecting the production cost dynamics of organic pigments.
Specialty Paper Market
Together, these forces are pushing the industry toward greater formulation transparency, substitution readiness, and proactive compliance planning. The full study integrates these dynamics into the forecast and segmentation logic so that leadership teams can anticipate where regulatory and sourcing pressures will alter competitive conditions, segment attractiveness, and procurement strategy over the forecast period.
Strategic Priorities for Specialty Ink Leadership in 2026
Given the market trajectory and operating environment, several strategic priorities emerge for organizations operating in or adjacent to the specialty ink value chain:
- Sharpen segment-level focus: Aggregate growth can obscure where value is genuinely migrating. Leaders should use segment-level intelligence to determine which product types and application verticals offer the strongest combination of demand resilience, margin potential, and defensible differentiation.
- Strengthen supply and formulation resilience: With raw material volatility and feedstock disruption affecting cost and availability, suppliers and downstream buyers alike need robust contingency planning, multi-source strategies, and formulation flexibility to manage near-term shocks without compromising performance standards.
- Embed sustainability and compliance into product strategy: Certification achievement, deinkability performance, low-migration formulations, and readiness for evolving chemical regulations are no longer optional differentiators. They are becoming prerequisites for participation in high-value packaging, healthcare, electronics, and industrial applications.
- Monitor competitive signaling closely: Pricing actions, capacity expansions, and product launches in 2025 and 2026 reflect deliberate positioning in response to market stress and opportunity. Tracking these moves at a granular level allows organizations to anticipate shifts in supplier behavior, regional availability, and segment competition.
- Use the forecast horizon for proactive planning: The 2026–2032 forecast period offers a structured window for aligning capital allocation, R&D investment, sales coverage, and partnership strategy with the most credible market direction rather than reactive short-term indicators.
From Strategic Direction to Decision-Ready Intelligence
The Worldwide Specialty Ink Market research is built to convert complex market signals into a usable strategic architecture. It combines a validated historical baseline, an explicit 2026–2032 forecast, full segmentation coverage, competitive analysis, and externally driven risk mapping into a single decision-oriented study. For organizations seeking to align commercial planning, product development, sourcing, and market positioning with the most credible trajectory for the specialty ink sector, the report provides the resolution necessary to move beyond approximation.
Detailed segmentation sizing, regional breakdowns, application-specific demand logic, and company-level competitive evaluation are presented in full within the complete study. Readers seeking the complete intelligence package can access the full report and supporting data structures through the market research portal.
For leadership teams preparing for 2026 and the years that follow, the strategic question is no longer whether the specialty ink market is growing, but where value is concentrating, which capabilities will command premium positioning, and how external pressures will reshape competitive advantage. This research is designed to answer those questions with the analytical discipline required for high-consequence commercial decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Specialty Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com