

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Commercial Vehicle Power Steering Pump Market to Grow 5.85% CAGR to $8,084.85M by 2032

Navigating the Shift: Why the Commercial Vehicle Power Steering Pump Market Demands Strategic Attention in 2026
The commercial vehicle landscape is undergoing a quiet but decisive transformation. Where brute mechanical force once dictated steering architecture, today’s OEMs are prioritizing energy efficiency, electronic integration, and compliance with tightening emissions mandates. At the center of this evolution sits the power steering pump—a component that has transitioned from a standard hydraulic accessory to a strategic node in vehicle dynamics, fuel economy, and electro hydraulic system architecture. For supply chain leaders, mobility investors, and tier-one strategists, understanding where this market is heading is no longer optional. It is a prerequisite for positioning ahead of the 2026–2032 cycle.
Our newly released Commercial Vehicle Power Steering Pump Market study delivers a structured, decision-ready view of this landscape. Rather than offering a static snapshot, the analysis is built to support scenario planning, portfolio evaluation, and competitive positioning as the sector moves through its next phase of consolidation and technology migration.
A Market Built on Measured Growth and Functional Transition
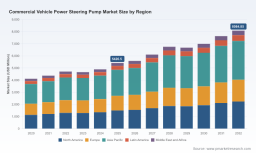
The commercial vehicle power steering pump market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately USD 4.1 billion in 2020 to an estimated USD 5.4 billion in 2025. That trajectory reflects more than volume growth; it signals a structural shift in how commercial fleets balance performance, operating cost, and regulatory exposure. Looking forward, the market is projected to advance at a compound annual growth rate of 5.85 percent across the 2026–2032 forecast horizon, reaching a valuation close to USD 8.1 billion by 2032.
Commercial Vehicle Power Steering Pump Market
This pace is neither explosive nor incremental in a vacuum. It is shaped by overlapping forces: the continued deployment of medium and heavy commercial platforms, the gradual substitution of traditional hydraulic assemblies with electro hydraulic and variable-displacement alternatives, and the pressure on manufacturers to reduce parasitic engine loads without compromising steering feel or safety. For decision-makers, the implication is clear. Growth in this segment will increasingly reward players who can align product roadmaps with efficiency benchmarks, electronics readiness, and regional compliance requirements rather than those who compete solely on volume or legacy supplier relationships.
What the Study Delivers: An Operational Lens on a Complex Ecosystem
The report is designed as a working reference for teams that need to translate market signals into sourcing, R&D, pricing, and partnership decisions. It combines historical reconstruction with forward-looking scenario analysis, giving readers a base year of 2025 and a forecast window extending through 2032. The structure supports both strategic overview and tactical interrogation, allowing users to examine demand drivers, product migration paths, and the competitive mechanics that shape supplier leverage.
Key analytical dimensions include:
Worldwide Automotive Power Steering Market
- Demand architecture across commercial vehicle segments , examining how light commercial vehicles, heavy commercial trucks, and buses/coaches place different performance, durability, and packaging requirements on steering pump systems.
- Product-type evolution , contrasting conventional hydraulic power steering pumps with electro hydraulic variants as OEMs pursue energy recovery, power-on-demand functionality, and reduced idle load.
- Regional demand distribution , mapping how mature commercial vehicle markets and high-volume manufacturing corridors differ in adoption timing, procurement behavior, and technology acceptance.
- Competitive intensity and supplier positioning , evaluating concentration patterns, differentiation levers, and the strategic moves that define current market leadership.
- Input cost and regulatory sensitivity , assessing how metal pricing volatility and emissions-driven mandates alter cost structures and accelerate the case for more efficient steering architectures.
- Recent product and technology milestones , capturing the launches, showcases, and system-level innovations that indicate where incumbent suppliers are placing their bets.
Each section is built to be actionable. Historical series provide a calibration baseline. Forecast logic ties together vehicle production assumptions, component substitution trends, and efficiency requirements. Competitive profiling goes beyond nameplate recognition to examine how suppliers are structuring their portfolios for medium and heavy commercial applications. The result is a research instrument that can support procurement hedging, engineering prioritization, M&A screening, and regional entry planning without requiring the reader to assemble disparate data points from multiple sources.
Competitive Landscape: Concentration, Differentiation, and the Push Toward Efficiency
The commercial vehicle power steering pump space is not a fragmented commodity market. It is a concentrated arena where technical differentiation, application expertise, and integration capability determine bargaining power. Current market concentration indicators point to a moderately consolidated environment, with the leading trio of suppliers accounting for a substantial share of revenue and the top five players extending that footprint further. In practical terms, this means scale, portfolio breadth, and proximity to OEM platform decisions still matter enormously.
Several established players illustrate the strategic directions shaping the segment. German suppliers continue to reinforce the link between steering hydraulics and vehicle-level efficiency. Bosch has built a recognizable position around hydraulic and electro hydraulic power steering systems for medium and heavy commercial vehicles, including variable displacement pump technology designed to reduce consumption. Its recent showcasing of a fourth-generation electro hydraulic steering system for commercial trucks—emphasizing ADAS compatibility and power-on-demand operation—signals a clear move toward steering architectures that interact more closely with advanced driver assistance and electronic control layers. Earlier presentations of electro hydraulic generations for heavy vehicles, with production timing aligned to the mid-2024 cycle, reinforce a sustained push into more integrated steering solutions.
ZF Friedrichshafen AG occupies a similarly influential position, offering ball-and-nut power steering systems and energy-efficient hydraulic pump variants alongside advanced electro hydraulic options for trucks and buses. Its portfolio reflects the broader industry tension between maintaining hydraulic performance expectations and lowering energy draw across duty cycles. Across the Atlantic, Nexteer Automotive has sharpened its focus on hydraulic power steering systems and pumps optimized for fuel efficiency and advanced driver assistance in heavy-duty trucks and commercial vehicles. Recent activity underscores that focus: a rear-wheel steering system developed to improve maneuverability in heavy vehicles, and a high-output electrified power steering solution targeting increased steering assist capacity for larger commercial platforms. These moves highlight how steering is being treated less as an isolated component category and more as part of a vehicle maneuverability and control strategy.
The landscape also includes suppliers with specialized engineering angles. Evamo has emphasized variable displacement vane pumps and electro hydraulic power steering pumps for medium to heavy commercial vehicles, with a stated emphasis on efficiency and CO₂ reduction—an increasingly relevant framing as fleet operators and regulators scrutinize total energy consumption. JTEKT Corporation supplies variable-flow steering pumps and hydraulic power steering solutions across commercial and light commercial applications, while Astemo has concentrated on power steering pumps with cast aluminum housing designed for commercial vehicle durability and efficiency. Concentric AB has taken a different route, developing electro hydraulic steering pumps for hybrid, fuel cell, and electric trucks and buses, directly addressing the displacement of conventional engine-driven pumps as powertrain architectures diversify. Maval Industries rounds out the field with power steering pumps and gears tailored to heavy-duty commercial and truck applications.
Together, these profiles reveal a market where competitive advantage is increasingly tied to efficiency claims, electronics compatibility, packaging for heavy-duty use, and the ability to support OEM transitions toward electrified or hybrid commercial platforms. The report examines these positions in greater depth, including how recent product activity is reshaping procurement conversations and where supplier vulnerability may emerge as regulations and powertrain mixes shift.
Industry Dynamics: Regulation, Input Costs, and the Efficiency Imperative
External pressures are not peripheral to this market; they are actively reordering priorities. Regulatory direction is one of the most consequential. European policy proposals targeting substantial carbon emission reductions for new heavy-duty commercial vehicles by 2030 are accelerating the search for components that contribute to lower overall energy consumption. In that context, a power steering pump is no longer judged only by steering performance. It is increasingly evaluated for parasitic load, duty-cycle efficiency, and compatibility with electrified or hybrid drivetrains.
Compliance expectations are also tightening on the operational side. Inspection-oriented regulations such as FMCSA Regulation 393.209, which requires commercial vehicle power steering systems to remain leak-free during inspections, reinforce the importance of reliability and sealing integrity in heavy-duty applications. For suppliers and fleet operators alike, this creates a dual mandate: improve efficiency without sacrificing durability or regulatory conformance.
Input cost volatility adds another layer of complexity. Fluctuations in aluminum and steel prices directly influence manufacturing economics for metal-housed power steering pumps, particularly where castings and structural components constitute a meaningful share of bill-of-materials cost. In an environment where procurement teams are already balancing performance upgrades against cost control, raw material exposure can determine margin resilience and pricing strategy. The research integrates these dynamics to help readers evaluate where cost risk is likely to concentrate and how suppliers may respond through design optimization, material strategy, or portfolio segmentation.
Why the 2026 Decision 윈도우 Requires a Deeper Read
The forecast period beginning in 2026 is not simply another year in a growth curve. It is a point where several trajectories converge: the maturation of electro hydraulic offerings, the continued presence of hydraulic pumps in cost-sensitive and high-duty applications, and the increasing need for steering systems that can coexist with ADAS features and alternative powertrains. In that environment, decisions made on the basis of aggregate market size alone will be insufficient.
Companies that want to act with confidence need to understand how demand is distributed across commercial vehicle types, which product types are gaining or losing relative share, where regional procurement patterns favor local content or imported systems, and how the leading suppliers are positioning their roadmaps against efficiency and electrification pressures. They also need a realistic view of competitive concentration: in a market where the leading suppliers hold a sizable revenue share, entry, expansion, or renegotiation strategies must account for the fact that incumbents are not standing still.
This is precisely the gap the full study is built to fill. The published analysis preserves the strategic framing outlined here while extending into the level of detail required for internal planning: scenario assumptions, segment-level demand logic, supplier positioning, technology migration patterns, and the cost and regulatory variables that shape near-term competitiveness.
Target Audience and Use Cases
The report is intended for teams that need a credible, structured foundation for commercial vehicle steering market decisions. Typical applications include:
- Component sourcing and procurement strategy , where understanding demand trends and supplier concentration supports supplier evaluation, negotiation stance, and risk diversification.
- R&D and product planning , where the shift between hydraulic and electro hydraulic solutions, variable displacement architectures, and electronics integration informs engineering priorities.
- Competitive and market intelligence , where recent product showcases, launches, and system-level announcements are placed in context rather than read as isolated press milestones.
- Investment screening and portfolio review , where market size, growth trajectory, concentration, and regulatory exposure help frame attractiveness and risk.
- Regional expansion or market-entry assessment , where demand distribution and application mix provide a starting point for more detailed local analysis.
Final Perspective: From Aggregate Growth to Strategic Positioning
The commercial vehicle power steering pump market is moving on a foundation of steady expansion, but its real story lies in the forces reshaping how value is created within that growth. Efficiency expectations, regulatory direction, powertrain diversification, and the steady integration of steering with broader vehicle electronics are all pushing suppliers and buyers toward more differentiated, more technically grounded decisions. In a market where the top suppliers already hold a meaningful revenue share and recent product activity points toward higher functionality and lower parasitic loss, the winners will be those who can interpret the signals early and align their strategies accordingly.
The full study translates that landscape into a usable intelligence platform. To access the complete segmentation logic, regional and application-level demand context, supplier competitive assessment, and forecast detail needed for 2026 planning, request the full report through our official research portal.
For detailed analysis of this topic, please visit the official page: Commercial Vehicle Power Steering Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com