

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Vibration Isolation Market to Reach $8.2B by 2032, Growing at 6.51% CAGR

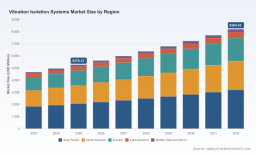
Navigating Precision: Strategic Intelligence for the Global Vibration Isolation Systems Market Through 2032
In an industrial landscape increasingly defined by nanometer-level manufacturing tolerances, stringent operator safety regulations, and the relentless push toward automation, vibration isolation has evolved from a passive engineering afterthought into a critical strategic infrastructure component. The Worldwide Vibration Isolation Systems Market is currently experiencing a period of disciplined growth, propelled by cross-sectoral demands for precision, compliance, and operational longevity. Our latest comprehensive research publication, Worldwide Vibration Isolation Systems Market , offers a rigorously structured blueprint for navigating this evolving ecosystem. Designed for executive leadership, R&D directors, procurement strategists, and competitive intelligence teams, this study translates macroeconomic trajectories, regulatory shifts, and technological inflection points into actionable decision frameworks for the 2026–2032 horizon.
The market's foundational trajectory reflects a steady compound annual growth rate of 6.51 percent throughout the forecast period, building upon a robust historical baseline that tracks consistent capital allocation and engineering modernization across multiple industrial verticals. Revenue in the base year of 2025 reached a substantial inflection point, continuing an upward momentum that positions the sector for sustained expansion into the next decade. Rather than relying on speculative projections, this analysis anchors its forward-looking models in empirically validated consumption patterns, capacity utilization data, and capital expenditure cycles. The result is a reliability-focused intelligence asset that enables stakeholders to align product roadmaps, supply chain configurations, and geographic prioritization with measurable market realities.
Market Architecture and Structural Demand Drivers
The contemporary vibration isolation ecosystem is shaped by an intersection of engineering precision requirements, material science advancements, and evolving compliance mandates. Raw material dynamics play an increasingly pivotal role in cost architecture and supplier negotiation strategies. Recent supply chain assessments indicate that natural rubber benchmark pricing has experienced notable year-over-year appreciation, driven by weather-related agricultural disruptions across Southeast Asian production hubs. Concurrently, synthetic elastomer markets have demonstrated relative price stabilization, supported by consistent petrochemical feedstock availability. These material flow fluctuations directly influence isolator manufacturing economics, forcing OEMs and tier-one suppliers to recalibrate inventory hedging, alternative material qualification, and proprietary compound development timelines.
Regulatory evolution further compounds the strategic complexity of market participation. Updated international vibration severity standards introduced measurement thresholds that mandate stricter velocity limitations for industrial machinery classifications. Simultaneously, the European Union's recent machinery directive framework has enforced tighter operator exposure limits, effectively raising the compliance floor for equipment deployed across manufacturing, energy generation, and heavy industrial environments. These regulatory catalysts are not merely compliance checkboxes; they represent structural demand accelerators that compel end-users to retrofit legacy installations and integrate higher-performance isolation architectures during new facility builds.
The report dissects these macro drivers through a multi-layered analytical lens, mapping how regulatory thresholds interact with sector-specific performance requirements. By isolating the causal relationships between compliance mandates, equipment lifecycle cycles, and procurement decision-making units, the study provides a clear framework for anticipating demand surges, evaluating retrofit versus greenfield investment ratios, and positioning product portfolios ahead of regulatory enforcement timelines.
Technological Divergence and Application Intelligence
Vibration isolation technology has bifurcated into distinct performance paradigms, each serving specialized operational environments with unique engineering constraints. Passive isolation architectures continue to dominate volume deployment, leveraging mature elastomeric formulations, mechanical spring geometries, and optimized structural damping characteristics to address broad-spectrum industrial requirements. These systems benefit from established supply chains, predictable lifecycle costs, and widespread engineering familiarity, making them the default choice for high-volume machinery, HVAC infrastructure, and conventional manufacturing equipment.
Active and semi-active isolation platforms, meanwhile, represent the high-growth frontier of the market. Utilizing real-time sensor feedback, adaptive damping media, and magnetorheological or pneumatic actuation mechanisms, these systems deliver dynamic disturbance cancellation capable of protecting ultra-sensitive instrumentation, precision manufacturing stages, and advanced research environments from low-frequency structural transmission. Recent industry milestones underscore the velocity of this technological maturation. Notable advancements include the introduction of hybrid elastomer-air spring isolators engineered specifically for precision manufacturing floors, the certification of adaptive fluid-based isolation platforms under updated quality management standards, and the demonstration of next-generation low-frequency damping materials at premier vibration engineering conferences. Additionally, hybrid composite pad architectures tailored for high-load industrial compressors have gained visibility through major industrial trade exhibitions, signaling cross-pollination between heavy machinery requirements and cleanroom-grade isolation performance.
Application-side demand patterns reveal a highly segmented consumption profile. Semiconductor and electronics manufacturing continues to drive some of the most stringent isolation specifications, where sub-micron process stability depends on eliminating micro-vibrational noise from substrate handling, lithography stages, and inspection equipment. Healthcare and life sciences environments impose parallel requirements, particularly in diagnostic imaging suites, bioprocessing containment zones, and precision laboratory instrumentation, where signal integrity and operator safety are equally paramount. Aerospace and defense applications maintain a steady demand curve driven by ground testing infrastructure, propulsion system validation, and sensitive avionics calibration environments. Precision industrial and automotive sectors leverage isolation architectures for high-tonnage presses, generator arrays, and powertrain validation rigs, while scientific research and academic laboratories increasingly specify custom-tuned isolation platforms for advanced microscopy, quantum measurement apparatus, and nanomechanical testing facilities. The research comprehensively maps these application vectors, evaluating procurement cadence, specification complexity, and technology adoption sensitivity without exposing granular volumetric allocations that are reserved for the full analytical dataset.
Worldwide Vibration Isolation Systems Market
Competitive Landscape and Strategic Positioning
The market's competitive architecture reflects a blend of entrenched engineering conglomerates, specialized elastomer innovators, and region-focused solution providers. Leading participants maintain competitive advantage through proprietary material formulations, application-specific tuning expertise, and deep integration with end-user engineering workflows. Swedish industrial technology groups have expanded their isolation portfolios across marine, aerospace, and heavy machinery domains, leveraging advanced elastomeric mounting systems and anti-vibration platform designs. American specialty manufacturers have reinforced their positions in automotive, defense, and heavy equipment segments through viscoelastic damping technologies, hydraulic isolation mounts, and custom-engineered isolator platforms. Austrian material science specialists continue to differentiate through proprietary elastomer-based structural damping solutions deployed in building infrastructure, rail networks, and industrial machinery. French engineering organizations contribute complementary technology lines spanning rubber-metal mounting configurations, wire rope isolators, and active control architectures, with dedicated sub-brands focusing on industrial press isolation, generator stabilization, and precision machinery support.
Additional competitive activity spans North American, European, and Asian manufacturing ecosystems, with participants delivering laminated fabric damping solutions, modular isolation assemblies, machinery leveling systems, and hydraulic chassis isolation platforms. Japanese industrial component leaders emphasize rubber isolator networks, air spring architectures, and comprehensive noise-vibration-harshness solutions for construction equipment and rail applications, while major tire and materials corporations extend their isolation expertise into seismic bearing systems, industrial plant stabilization, and earthquake-resilient machinery foundations. The competitive intensity in this space is moderated by a moderately concentrated market structure, where top-tier participants collectively command a significant but non-dominant share, leaving substantial room for regional differentiation, application-specific specialization, and technology-led market entry.
Our analysis evaluates competitive positioning across multiple strategic dimensions, including technology roadmapping, certification trajectories, supply chain resilience, and cross-sectoral application expansion. Recent corporate developments, including certification renewals for adaptive isolation platforms, trade show demonstrations of low-frequency damping innovations, and product launches targeting hybrid isolation architectures, are contextualized within broader market signaling patterns. These events are not isolated product announcements; they represent strategic indicators of where engineering investment is flowing, which performance thresholds are becoming commercially viable, and how incumbents are defending or expanding their addressable footprints. The full report provides detailed competitor profiling, capability benchmarking, and strategic response mapping, enabling organizations to identify partnership opportunities, anticipate competitive countermeasures, and refine go-to-market positioning.
Regulatory Catalysts, Supply Chain Realities, and Risk Navigation
Strategic market participation requires a clear understanding of the regulatory and material risk vectors that shape procurement cycles and engineering specifications. Beyond the aforementioned vibration severity updates and operator exposure directives, compliance frameworks are increasingly demanding traceability, performance verification, and lifecycle documentation for isolation components deployed in regulated environments. This document-driven compliance burden elevates the importance of supplier qualification rigor, quality management certification, and long-term material availability commitments. Procurement teams are consequently placing greater weight on supplier stability, formulation transparency, and documented testing protocols when evaluating isolation system partners.
Simultaneously, raw material supply volatility introduces pricing uncertainty that can compress margins or delay project timelines if not proactively managed. Organizations that integrate material price forecasting, alternative compound qualification, and multi-source procurement strategies into their isolation architecture planning will secure measurable cost and schedule advantages. The research publication addresses these dynamics through scenario-based sensitivity modeling, evaluating how fluctuations in elastomer pricing, petrochemical feedstock availability, and logistics constraints influence total cost of ownership across different isolation configurations. By separating transient price noise from structural material demand shifts, the study equips decision-makers with the analytical discipline needed to negotiate contracts, hedge inventory exposure, and align engineering specifications with realistic supply conditions.
What the Full Report Delivers
While this overview establishes the strategic perimeter of the market opportunity, the complete research publication delivers a granular, execution-ready intelligence package designed for cross-functional deployment. Stakeholders who access the full dataset will gain access to:
- Comprehensive market sizing and forward-looking revenue projections calibrated across multiple forecast intervals, enabling capital allocation planning and growth target validation
- Detailed segmentation analysis across isolation technology architectures, application environments, and geographic consumption patterns, providing the structural visibility required for product portfolio alignment and regional sales resource deployment
- Competitive benchmarking frameworks that evaluate market positioning, technology specialization, and strategic maneuvering across leading participants, facilitating competitive response planning and partnership identification
- Regulatory impact mapping that translates updated vibration severity standards and machinery exposure directives into procurement timelines, specification requirements, and retrofit demand projections
- Material cost and supply chain sensitivity analysis that connects raw material price trajectories to isolator manufacturing economics, helping procurement and engineering teams optimize specification choices and sourcing strategies
- Recent industry development tracking that contextualizes product launches, certification milestones, and conference demonstrations within broader technology adoption cycles and competitive signaling patterns
- Strategic recommendation modules that translate analytical findings into actionable guidance for R&D prioritization, market entry evaluation, capacity planning, and commercial positioning
The report is structured to serve multiple organizational functions simultaneously. Executive leadership can utilize the macro trajectory analysis and regulatory impact assessments to validate long-term investment theses and geographic expansion priorities. Engineering and product management teams can leverage segmentation depth and technology positioning frameworks to refine specification roadmaps and identify performance gaps in existing solution portfolios. Commercial and sales leadership can apply competitive positioning insights and application demand mapping to optimize territory planning, vertical-specific messaging, and customer engagement strategies. Procurement and supply chain stakeholders can draw on material cost sensitivity analysis and supplier qualification frameworks to strengthen sourcing resilience and negotiate from an informed position.
Strategic Imperatives for 2026 Decision-Making
The vibration isolation market does not reward reactive positioning. Organizations that treat isolation systems as commoditized accessories risk underperformance in precision-sensitive applications, compliance exposure in regulated environments, and margin erosion in material-volatile procurement cycles. Conversely, firms that integrate vibration control strategy into broader engineering, compliance, and commercial planning will capture disproportionate value from the sector's disciplined growth trajectory. The six-percent-plus compound growth rate projected through the early 2030s is not merely a statistical indicator; it reflects a structural realignment of industrial priorities toward stability, precision, and operator protection. Capital expenditure programs, regulatory enforcement timelines, and technology maturation curves are synchronizing in a way that creates clear windows of opportunity for suppliers, system integrators, and end-users who act with analytical clarity.
Our research publication is designed to convert that opportunity into executable strategy. By revealing the market's structural architecture, competitive undercurrents, regulatory catalysts, and material reality checks, the study provides the evidentiary foundation required for confident decision-making in 2026 and beyond. The macro trajectory, segmentation dimensions, competitive intelligence, and application-specific demand mapping presented here represent only the analytical perimeter. The complete intelligence framework, including granular regional consumption breakdowns, application-level revenue distributions, technology-segment growth differentials, and detailed competitor strategy assessments, is reserved for the full report.
Seismic Isolation Systems Market
Organizations seeking to align product development pipelines, refine commercial positioning, optimize procurement strategies, or evaluate market entry pathways will find that the depth of analysis required for high-stakes planning extends well beyond aggregated market summaries. The full publication delivers that depth, structured for immediate integration into strategic planning cycles, investment committee briefings, and cross-functional execution roadmaps. Precision engineering, regulatory compliance, and material supply resilience will continue to define competitive advantage in this sector. Access to the complete research dataset ensures that your organization navigates those variables with verified intelligence rather than directional assumption.
For detailed analysis of this topic, please visit the official page: Worldwide Vibration Isolation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com