

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gluten-Free Baking Flour Market to Reach $9.12 Billion by 2032 at 8.35% CAGR

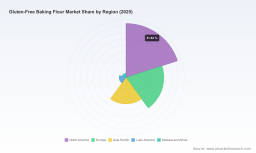
The Strategic Imperative: Navigating the Gluten-Free Baking Flour Market in 2026
The global gluten-free baking flour market has transitioned from a niche consumer segment to a mainstream pillar of food and beverage strategy. As we enter 2026, corporate decision-makers face a landscape defined by accelerating product innovation, stringent regulatory oversight, and shifting distribution paradigms. Our latest comprehensive study delivers the analytical rigor required to navigate this transformation, offering a detailed view of market trajectories, competitive dynamics, and operational imperatives that will shape the next wave of enterprise growth.
For executives, procurement leaders, and R&D strategists, the question is no longer whether gluten-free baking flours represent a viable expansion avenue, but how to position portfolios against a backdrop of structural demand growth and intensifying competition. This introductory piece outlines the strategic architecture of our research, highlights the macro drivers powering the sector, and provides a preview of the actionable intelligence embedded within our full 2026 market assessment. Readers seeking granular segmentation metrics, proprietary forecasting models, and company-level financial benchmarks are invited to access the complete report for end-to-end strategic planning.
Macro Trajectory: Sustained Expansion and Structural Demand Drivers
The historical footprint of the gluten-free baking flour market reveals a clear and consistent upward trajectory. From a baseline valuation of approximately 3.5 billion USD in 2020, the sector has demonstrated annual expansion that has consistently outperformed broader food ingredient benchmarks. By 2025, market valuation reached a pivotal inflection point, surpassing 5.2 billion USD, as consumer adoption, retail assortment breadth, and manufacturer capacity investments converged to reinforce momentum.
Looking ahead, our baseline forecast paints a robust picture of long-term value creation. Revenue projections indicate sustained annual growth that will push the total market valuation beyond 9 billion USD by the close of the forecast horizon in 2032. This expansion is underpinned by a compound annual growth rate of 8.35 percent, reflecting a blend of volume-driven consumer uptake, premiumization within specific flour categories, and the progressive integration of gluten-free formulations into broader retail and foodservice offerings.
Several structural forces are converging to sustain this trajectory. Dietary preference shifts continue to normalize gluten-free consumption beyond medically mandated populations, with wellness-driven consumers, food-sensitive demographics, and label-conscious households expanding the addressable base. Simultaneously, manufacturers have invested heavily in formulation science, improving texture, sensory appeal, and processing reliability, which has lowered historical barriers to repeat purchase and mainstream shelf placement. Supply chain maturation and ingredient availability improvements further reinforce scalability, while digital commerce channels continue to accelerate product discovery and direct-to-consumer testing cycles.
For enterprise strategy, this macro backdrop carries clear implications. Demand growth is no longer dependent on a single consumer archetype or retail format. Instead, it reflects a diversified consumption ecosystem where bakery brands, private-label operators, ingredient suppliers, and foodservice operators each contribute to volume expansion. Our research dissects these interlocking demand streams to help organizations identify the highest-probability growth vectors and align capacity, marketing, and product development accordingly.
Architecture of the Study: Operational Intelligence for 2026 Decision-Making
A market research report is only as valuable as its ability to translate observation into action. Our publication is structured around a set of operational pillars designed to serve different functional teams within the enterprise. Rather than offering a high-level narrative, the study delivers granular, testable, and immediately applicable intelligence that supports budgeting, forecasting, competitive positioning, and risk management.
Worldwide Gluten-free Baking Mixes Market
At the core of the study is a multi-year historical reconstruction (spanning 2020 through 2025) paired with a forward-looking forecast window extending to 2032. This temporal architecture enables clients to validate past assumptions, measure deviation from prior projections, and anchor 2026 planning cycles in empirically grounded growth curves. The analysis also integrates ingredient-level context, including the role of staple base flours in formulation strategy, price differentials within premium versus standard ingredient tiers, and the implications of raw material availability on product economics.
Beyond top-line valuation, the study maps the ecosystem of commercial pathways. It examines how distribution architectures have evolved, where volume concentration persists, and how retail execution, e-commerce acceleration, and specialty retail positioning interact to shape accessibility. Regulatory context is also woven into the narrative framework, with particular attention to labeling compliance thresholds, cross-contact prevention expectations, and the operational burden these requirements place on manufacturing facilities, quality teams, and brand communications.
Gluten-Free Baking Flour Market
To ensure practical relevance, the report includes scenario-ready analytical tools. These are designed to help teams model the impact of input cost variability, assess the sensitivity of portfolio performance to channel mix shifts, and evaluate the strategic trade-offs between premiumization and mass-market accessibility. The objective is not simply to describe the market, but to equip leaders with a structured framework for testing assumptions before committing capital.
Throughout the document, data is presented with discipline. Percentage splits, regional revenue shares, and specific segment valuations are reserved for the full reference edition, enabling the complete study to function as a secure internal planning asset. This controlled disclosure model ensures that clients who acquire the report receive comprehensive analytical depth without dilution, while public-facing summaries preserve strategic ambiguity and encourage deeper engagement with the full dataset.
Competitive Landscape: Established Incumbents and Emerging Positioning Tactics
The competitive architecture of the gluten-free baking flour market is defined by a mix of consumer-facing brands, ingredient and commodity-scale suppliers, and specialty formulation specialists. This layered structure creates a highly interactive environment where upstream ingredient availability, midstream formulation capability, and downstream brand positioning all influence market share dynamics.
Among the most visible consumer-facing players, several organizations have built recognizable positions through dedicated gluten-free manufacturing infrastructure and formulation parity with conventional baking expectations. Companies offering 1-to-1 substitution blends, specialty grain combinations, and certified production environments have capitalized on consumer demand for convenience and baking predictability. In parallel, large diversified food manufacturers have advanced accessibility by embedding gluten-free baking solutions within established retail brands, expanding shelf visibility and leveraging existing distribution footprints.
On the ingredient and supply side, major commodity and specialty grain operators continue to play an essential role. Their bulk supply capabilities, starch and rice-based ingredient portfolios, and commercial baking ingredient programs support downstream manufacturing at scale. These suppliers are particularly influential for private-label development, foodservice applications, and mid-tier brands that depend on reliable raw material access and formulation support. Specialty milling and ancient grain-focused operators further enrich the ecosystem by introducing texture-forward blends and retail-oriented baking mixes that differentiate on perceived quality and ingredient narrative.
Market concentration data indicates that consolidated leadership exists but remains measured. The competitive field is not dominated by a single monolithic entity; rather, it features a distribution of strength across consumer brands, ingredient suppliers, and formulation specialists. This dispersed structure creates opportunities for targeted positioning, whether through innovation in premium blends, expansion into underserved retail formats, or strategic cost optimization in high-volume base ingredients.
Recent operational events also underscore the importance of process integrity. A notable 2025 recall involving voluntary action related to undeclared allergen cross-exposure highlights the persistent sensitivity of the category to quality control, labeling accuracy, and manufacturing discipline. For brands and ingredient suppliers alike, compliance is not merely a regulatory formality; it is a market trust mechanism that directly affects retail relationships, consumer confidence, and long-term portfolio resilience.
The strategic takeaway for 2026 is that competitive advantage will increasingly derive from a combination of formulation reliability, regulatory readiness, supply consistency, and channel execution. Our full study evaluates these variables at the company and portfolio level, providing context that supports benchmarking, partnership assessment, and competitive threat mapping.
Regulatory and Supply Chain Dynamics: Risk, Compliance, and Formulation Strategy
The regulatory environment continues to shape the commercial reality of gluten-free baking flours in both subtle and structural ways. Labeling standards that define permissible gluten thresholds remain a baseline requirement for market entry and sustained shelf eligibility. Beyond the headline compliance number, manufacturers must also contend with operational expectations around cross-contact prevention, facility segregation, and documentation rigor. Attention to these practices is intensifying, and comment periods and regulatory engagement in 2026 signal continued scrutiny of manufacturing controls that affect product integrity.
For R&D and quality functions, this environment reinforces the value of formulation discipline and traceability. The category’s dependence on base ingredients with distinct functional properties means that substitution decisions, blending ratios, and processing conditions carry both sensory and compliance implications. Ingredient selection also has direct economic consequences. Premium-tier materials can command meaningful price premiums and may deliver superior texture outcomes, but they also introduce cost volatility that must be managed through portfolio architecture, sourcing strategy, and consumer value communication.
Supply chain considerations extend further into the raw material ecosystem. Base ingredient markets associated with common gluten-free blends exhibit their own size, growth patterns, and end-use dynamics. White rice flour, for example, maintains prominence in many formulations because of its neutral flavor profile and functional compatibility, while almond-based ingredients occupy a distinct premium niche with texture and cost characteristics that influence product positioning. Understanding these dynamics is essential for organizations that aim to develop blends that are both commercially attractive and economically sustainable across fluctuating input conditions.
The interplay between regulatory expectations, ingredient economics, and consumer quality expectations creates a demanding optimization problem. Our study addresses this by connecting compliance frameworks to formulation choices, channel economics, and brand communication strategy. Rather than treating regulation as an external constraint alone, the analysis frames it as a strategic design parameter that can differentiate compliant, credible products in a crowded market.
Implications for 2026 Strategy: Portfolio Positioning, Channel Mix, and Capital Allocation
As enterprises plan for the remainder of 2026 and beyond, the gluten-free baking flour market rewards organizations that integrate demand forecasting with operational realism. Several strategic priorities stand out.
First, portfolio architecture must reflect the reality that consumer expectations have expanded beyond simple gluten removal. Products that deliver baking reliability, sensory parity, and ingredient transparency are better positioned to command repeat purchase and premium price acceptance. At the same time, mass-market accessibility remains a growth engine. The most resilient strategies often combine a premium flank with a scalable core offering, supported by clear brand hierarchy and distinct formulation value propositions.
Second, channel strategy should be treated as a growth variable rather than a static deployment plan. Retail execution, e-commerce discovery, and specialty store presence each serve different consumer journeys and margin profiles. Understanding where volume concentrates, how digital channels accelerate trial, and how retail breadth translates into repeat purchasing enables more precise resource allocation. Organizations that map channel economics to product tiers can better balance coverage, availability, and margin protection.
Third, sourcing and formulation strategy must be aligned with both cost discipline and quality assurance. Ingredient volatility, premium material pricing differentials, and process controls all influence margin performance and brand trust. Companies that build flexibility into supplier relationships, establish formulation guardrails, and maintain rigorous compliance documentation are better equipped to manage disruption and sustain shelf eligibility.
Fourth, competitive strategy requires disciplined monitoring of both consumer brands and upstream ingredient suppliers. Because the market spans formulation specialists, diversified food manufacturers, and commodity-scale suppliers, competitive threat and partnership opportunities can emerge from multiple directions. Strategic planning should therefore incorporate benchmarking, capability assessment, and scenario testing to determine where to compete, where to collaborate, and where operational efficiencies can be captured.
Finally, 2026 planning should treat the forecast horizon as a decision framework rather than a fixed prediction. Growth trajectories, input markets, regulatory discussion, and channel evolution all carry uncertainty. Organizations that build scenario-based models around base, upside, and downside assumptions will be better prepared to adjust capacity commitments, marketing investment, and product launches as conditions evolve.
Conclusion: From Market Intelligence to Strategic Execution
The gluten-free baking flour market in 2026 presents a rare combination of scale, momentum, and strategic complexity. Demand is structurally supported, formulation capability has matured, and competitive intensity continues to reward organizations that can align product quality, compliance integrity, supply reliability, and channel execution. At the same time, the category’s breadth and dynamism require deeper intelligence than headline figures can provide.
This overview has been designed to demonstrate the caliber and scope of our research while preserving the specific analytical assets that make the full report an operational asset. Detailed segmentation metrics, regional and channel-level revenue distributions, source-specific evaluations, and company-level competitive profiling are integrated throughout the complete study, providing the depth necessary for confident internal planning. Those metrics are intentionally withheld here to preserve the report’s strategic distinction and to guide decision-makers toward the full edition for precision benchmarking and multi-year forecasting.
For organizations preparing capital allocation decisions, product roadmap reviews, sourcing strategy revisions, or competitive positioning refreshes, our 2026 Gluten-Free Baking Flour Market study offers a structured, evidence-based foundation. The full report delivers the data density, analytical context, and scenario-ready frameworks needed to convert market awareness into executable strategy. Access the complete publication to obtain the detailed intelligence required to plan with confidence across the remainder of the forecast horizon and beyond.
For detailed analysis of this topic, please visit the official page: Gluten-Free Baking Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com