

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Specialty Ink Revenue Hits $4,522.38M in 2025, Projected 5.24% CAGR Through 2032

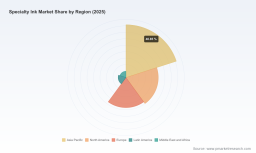
Navigating the 2026 Landscape: Strategic Intelligence for the Worldwide Specialty Ink Market
The specialty ink industry is undergoing a structural transformation defined by regulatory pressure, raw material volatility, and shifting demand patterns across high-growth applications. For executives navigating procurement, product development, and market expansion in 2026, surface-level market commentary is no longer sufficient. PW Consulting's latest Worldwide Specialty Ink Market research delivers the operative intelligence required to convert macroeconomic signals into actionable commercial strategy.
This briefing provides a strategic overview of the market direction, the operational depth embedded in the full study, and the competitive intelligence framework designed to support board-level decision-making throughout the forecast horizon.
A Market in Structural Transition: The 2026–2032 Trajectory
The specialty ink sector has demonstrated consistent growth momentum across the historical review period, culminating in a total revenue base of approximately 4.52 billion USD in 2025. Building on this foundation, the market is projected to expand steadily through the end of the decade, reaching a valuation of roughly 6.47 billion USD by 2032. This represents a forecast compound annual growth rate of 5.24 percent, a trajectory that underscores durable demand for high-performance, functional, and sustainable ink formulations across both mature and emerging industrial verticals.
It is critical to interpret this growth not as a uniform expansion but as a reallocation of value across product architectures, geographic operating environments, and end-use sectors. The 2026 landscape introduces cross-currents that demand precise segmentation intelligence. Rising pigment and raw material costs are compressing margins and forcing formulation adaptations. Simultaneously, regulatory developments are reshaping compliance requirements for packaging, industrial marking, and consumer-facing applications. Understanding where value is shifting and which technological adaptations command premium positioning requires a granular, data-anchored view that general market commentary cannot provide.
This research distills those dynamics into a clearly structured analytical framework, enabling leadership teams to prioritize investment, assess supplier risk, and align product roadmaps with the most defensible growth pockets across the 2032 horizon.
What the Report Delivers: Operational Intelligence for Executive Decision-Making
The 2026 Worldwide Specialty Ink Market study is designed as a practical decision-support instrument rather than a static market summary. It integrates historical performance data, forward-looking projections, and qualitative market intelligence into a cohesive analytical architecture that can be deployed across commercial, operational, and strategic functions.
Core Analytical Components
- Historical Baseline and Forecast Architecture: A detailed reconstruction of market performance from 2020 through 2025, anchored to a rigorously validated baseline, paired with an explicit 2026–2032 forecast period. This structure allows teams to benchmark internal performance against documented industry trends and stress-test growth assumptions.
- Full Segmentation Mapping: Comprehensive segmentation across product type categories, application verticals, and regional operating environments. Rather than relying on aggregate demand signals, the report isolates the distinct demand drivers, competitive intensity, pricing behaviors, and adoption curves within each segment, giving stakeholders the resolution needed to identify where strategic focus will yield the highest return.
- Competitive Positioning and Market Structure Analysis: An in-depth evaluation of consolidation patterns, market share distribution, and strategic maneuvering among key global and regional players. The study examines how leading manufacturers are differentiating through formulation innovation, sustainability certifications, supply chain resilience, and targeted capacity adjustments, providing a benchmark for competitive positioning.
- Technology and Formulation Landscape: An assessment of the technological shifts reshaping specialty ink portfolios, including the growing significance of UV-curable and energy-curable systems, conductive and functional ink architectures, and specialty formulations engineered for security, color performance, and environmental compliance.
- Regulatory and Raw Material Risk Mapping: A synthesized view of the external pressures currently affecting the industry, from feedstock price volatility and logistics constraints to evolving regulatory frameworks governing chemical substances, packaging safety, and emissions control. This dimension is integrated directly into the forecast logic rather than treated as a standalone appendix.
Practical Deployment for 2026 Planning
The report is structured to support multiple internal workflows. Commercial teams can use the segmentation data to refine territory prioritization and customer targeting. R&D and product management teams can align development pipelines with the highest-potential formulation categories and application trends. Procurement and supply chain leaders can incorporate the market structure and raw material risk dimensions into sourcing strategies and supplier negotiations. Executive leadership can rely on the consolidated market trajectory and competitive analysis to frame capital allocation, partnership decisions, and strategic contingencies.
By presenting macro trends alongside segment-level logic, the study ensures that strategy is informed by both the scale of the opportunity and the specifics of where that opportunity is concentrated.
Worldwide Specialty Ink Market
Competitive Dynamics: Leadership in a Consolidating Market
The worldwide specialty ink market remains moderately to highly consolidated, with the top firms holding a combined share that reflects the scale advantages, formulation expertise, and global distribution networks required to compete at the highest tier. This concentration does not imply a static environment. Rather, it indicates a market in which competitive differentiation is increasingly determined by formulation capability, compliance readiness, and operational agility in the face of input cost volatility.
Leading global players profiled in the study represent a diverse but overlapping field of capability centers. Organizations such as Sun Chemical, operating under DIC Corporation's broader industrial footprint, maintain extensive portfolios spanning digital, UV-curable, low-migration, packaging, and functional inks for security and high-performance applications. Flint Group continues to anchor its strength in flexographic, gravure, and energy-curable formulations for packaging, labels, and commercial printing. Siegwerk emphasizes sustainable, low-migration UV and LED-curable solutions with particular focus on food-contact suitability and flexible packaging. Toyo Ink SC Holdings and Sakata INX extend the influence of Japanese formulation expertise across gravure, flexo, digital, and functional ink categories, while INX International Ink Co. and Fujifilm Ink Solutions Group contribute advanced inkjet and specialty platforms with sustainability-oriented development priorities.
Further down the segmentation spectrum, specialists such as Avient Specialty Inks, Nazdar Ink Technologies, Marabu, Wikoff Color Corporation, Zeller+Gmelin, Hubergroup, and T&K TOKA illustrate the breadth of application-specific and process-specific expertise that sustains competitive intensity across screen, digital, offset, and industrial marking niches. The presence of both broad-line global suppliers and focused specialty manufacturers creates a dynamic environment in which innovation, customization, and regional responsiveness all play central roles.
Recent Competitive Movements Shaping 2026
The competitive field is also being reshaped by concrete operational and market-facing actions taken in late 2025 and early 2026. Several major manufacturers have moved to adjust pricing structures in response to escalating raw material, logistics, and energy costs. In March 2026, Sun Chemical implemented price increases and surcharges across all product divisions, citing geopolitical developments in the Middle East and their impact on energy markets, logistics, and chemical feedstock availability. Around the same period, Flint Group raised prices across packaging ink and coating products due to rising raw material and intermediate costs, transportation pressures, longer lead times, supplier force majeure events, and higher energy expenses.
Beyond pricing, players are investing in formulation credentials and capacity readiness that reinforce long-term positioning. Toyo Ink's Toyochem division secured INGEDE Deinkability Certification for its mineral-oil-free inks in January 2026, a move with clear implications for packaging recyclability and sustainability-based procurement requirements. Earlier, in November 2025, Toyo Ink India expanded its liquid ink production capacity by 1.5 times, illustrating how regional capacity investments are being used to support localized demand and supply resilience. In July 2025, Sun Chemical introduced SunCure Advance ECO UV Inks designed for high-speed presses, reflecting the ongoing push to align curing technology with productivity demands and sustainability goals.
These actions illustrate a broader pattern: competitive advantage in 2026 is being built through the intersection of pricing discipline, certified sustainability performance, capacity alignment, and formulation innovation. The full competitive analysis in the report provides deeper evaluation of how these moves affect market share trajectories, segment positioning, and supplier selection dynamics.
Regulatory, Sourcing, and Cost Pressures Defining the 2026 Operating Environment
Executive strategy for the specialty ink market cannot be separated from the external environment. In 2026, several overlapping pressures are influencing formulation strategies, cost structures, and compliance roadmaps across the industry.
Raw material volatility remains a persistent concern. Rising pigment and input costs are placing pressure on manufacturers to balance margin preservation with competitive pricing, and this environment is intensifying the importance of feedstock diversification, formulation efficiency, and supplier relationship management. The disruption of chemical feedstock flows linked to Middle East conflict has contributed to price volatility and has played a direct role in triggering ink price increases and surcharges across multiple product categories.
Regulatory trajectories are similarly reshaping the operating baseline. The EPA draft Risk Management Rule for CI Pigment Violet 29 has continued through 2026 following industry comments submitted in early 2025, signaling ongoing scrutiny of specific pigment substances. In parallel, Health Canada and Environment and Climate Change Canada published a proposed approach for risk management of PFAS substances in 2025, expanding the compliance landscape for formulators serving or anticipating North American requirements. Meanwhile, US EPA strengthened standards for synthetic organic chemical plants in April 2024, reducing emissions of toxic air pollutants and affecting the production cost dynamics of organic pigments.
Specialty Paper Market
Together, these forces are pushing the industry toward greater formulation transparency, substitution readiness, and proactive compliance planning. The full study integrates these dynamics into the forecast and segmentation logic so that leadership teams can anticipate where regulatory and sourcing pressures will alter competitive conditions, segment attractiveness, and procurement strategy over the forecast period.
Strategic Priorities for Specialty Ink Leadership in 2026
Given the market trajectory and operating environment, several strategic priorities emerge for organizations operating in or adjacent to the specialty ink value chain:
- Sharpen segment-level focus: Aggregate growth can obscure where value is genuinely migrating. Leaders should use segment-level intelligence to determine which product types and application verticals offer the strongest combination of demand resilience, margin potential, and defensible differentiation.
- Strengthen supply and formulation resilience: With raw material volatility and feedstock disruption affecting cost and availability, suppliers and downstream buyers alike need robust contingency planning, multi-source strategies, and formulation flexibility to manage near-term shocks without compromising performance standards.
- Embed sustainability and compliance into product strategy: Certification achievement, deinkability performance, low-migration formulations, and readiness for evolving chemical regulations are no longer optional differentiators. They are becoming prerequisites for participation in high-value packaging, healthcare, electronics, and industrial applications.
- Monitor competitive signaling closely: Pricing actions, capacity expansions, and product launches in 2025 and 2026 reflect deliberate positioning in response to market stress and opportunity. Tracking these moves at a granular level allows organizations to anticipate shifts in supplier behavior, regional availability, and segment competition.
- Use the forecast horizon for proactive planning: The 2026–2032 forecast period offers a structured window for aligning capital allocation, R&D investment, sales coverage, and partnership strategy with the most credible market direction rather than reactive short-term indicators.
From Strategic Direction to Decision-Ready Intelligence
The Worldwide Specialty Ink Market research is built to convert complex market signals into a usable strategic architecture. It combines a validated historical baseline, an explicit 2026–2032 forecast, full segmentation coverage, competitive analysis, and externally driven risk mapping into a single decision-oriented study. For organizations seeking to align commercial planning, product development, sourcing, and market positioning with the most credible trajectory for the specialty ink sector, the report provides the resolution necessary to move beyond approximation.
Detailed segmentation sizing, regional breakdowns, application-specific demand logic, and company-level competitive evaluation are presented in full within the complete study. Readers seeking the complete intelligence package can access the full report and supporting data structures through the market research portal.
For leadership teams preparing for 2026 and the years that follow, the strategic question is no longer whether the specialty ink market is growing, but where value is concentrating, which capabilities will command premium positioning, and how external pressures will reshape competitive advantage. This research is designed to answer those questions with the analytical discipline required for high-consequence commercial decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Specialty Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com