

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global Pet Food Delivery Revenue Hits $6.48B in 2025, Projected 10.51% CAGR to $13B by 2032
By pmarketresearch, 2026-09-16
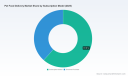
Global Pet Food Delivery Market 2026: Strategic Imperatives in a High-Growth Subscription Economy
The worldwide pet food delivery market has transitioned from a discretionary convenience to a core distribution channel for the broader pet care industry. Over the past half-decade, structural shifts in consumer purchasing behavior, advancements in cold-chain logistics, and the maturation of recurring revenue models have fundamentally reshaped how pet nutrition reaches households. For executives, investors, and category managers navigating 2026, understanding the mechanics of this shift is no longer optional. It is a prerequisite for capital allocation, supply chain redesign, and competitive positioning.
This deep-dive analysis draws from our newly released Worldwide Pet Food Delivery Market research to outline the strategic landscape shaping the 2026–2032 forecast period. Rather than offering a superficial overview, the study dissects the operational, regulatory, and competitive forces driving sustained expansion. Below, we preview the critical insights that matter most for enterprise decision-making, while preserving the granular segmentation, pricing architectures, and regional breakdowns exclusively available in the full report.
Market Trajectory: A Decade of Accelerating Adoption and Forecasts Through 2032
The market's historical trajectory reflects a compounding adoption curve that accelerated sharply between 2020 and 2025. Revenue expanded from approximately 3,520.45 million USD in 2020 to 6,480.0 million USD by 2025, signaling a structural migration away from episodic, in-store purchasing toward recurring, digitally mediated fulfillment. This momentum carries directly into the forecast window: the market is projected to reach 7,184.13 million USD in 2026 and continue scaling toward 13,043.27 million USD by 2032.
The compound annual growth rate of 10.51% across the 2026–2032 horizon underscores a market that is compounding rather than merely recovering. Several underlying drivers sustain this trajectory. First, the normalization of subscription-based consumption has reduced purchase friction and elevated customer lifetime value across demographic segments. Second, premiumization trends in pet humanization have shifted spend toward specialized, fresh, and veterinarian-endorsed formulations that align naturally with recurring delivery models. Third, logistics networks have matured enough to support cold-chain and temperature-controlled fulfillment at scale, unlocking product categories that were previously constrained by retail shelf limitations.
For strategic planners, the forecast period presents both expansion opportunity and execution risk. Companies that treat delivery as a pure distribution add-on will likely cede share to operators who have embedded fulfillment architecture into their brand identity, pricing strategy, and unit economics. The full report quantifies the inflection points across product formats, subscription maturity curves, and geographic adoption differentials, enabling leadership teams to calibrate investment timing rather than react to market shifts after they materialize.
Structural Shifts Reshaping Delivery Economics and Consumer Behavior
The pet food delivery ecosystem is being reengineered by intersecting forces that alter cost structures, compliance requirements, and competitive moats. Understanding these dynamics is essential for scenario planning in 2026.
Regulatory Compliance as a Competitive Filter
Regulatory frameworks have moved from background compliance to front-line strategic considerations. In the European Union, Regulation (EU) 2023/2345 mandates clear nutritional labeling on all pet food packaging, including products sold through delivery channels, with compliance effective from January 2024. This requirement compels operators to align packaging, digital product pages, and fulfillment documentation with standardized transparency expectations. Meanwhile, in the United States, the FDA continues to require AAFCO nutrient profile compliance across delivery channels, with 2025 updates refining taurine level requirements to support cardiac health. These updates directly affect formulation strategies, supplier qualification, and quality assurance workflows for brands distributing through subscription or direct-to-consumer pipelines.
Operators that treat regulatory adherence as a periodic checklist often face costly rework, delayed listings, or formulation adjustments late in the product lifecycle. By contrast, organizations that integrate compliance architecture into product development and logistics planning can reduce time-to-market friction and strengthen consumer trust through transparent nutritional communication.
Input Cost Volatility and Supply Chain Configuration
Ingredient pricing and trade policy remain central to margin management. Global corn prices, a foundational input across multiple pet food categories, averaged 198 USD per metric ton in the fourth quarter of 2025 amid relatively stable supply conditions. While short-term stability provides planning visibility, the broader procurement environment remains sensitive to agricultural output variability, energy costs, and regional trade dynamics.
Compounding this sensitivity, US-China tariffs on pet food imports remain at 25% under Section 301, directly affecting delivery supply chains that rely on Asian-sourced ingredients or intermediate components. For operators with cross-border sourcing footprints, the tariff structure influences supplier diversification strategy, domestic manufacturing investment, and inventory positioning. Companies that proactively map ingredient origin, lead-time variability, and tariff exposure can build more resilient procurement architectures, while those with concentrated sourcing may encounter margin compression or fulfillment delays during trade policy shifts.
Segmentation Architecture: Food Type and Subscription Models
The market's composition reflects a divergence between traditional shelf-stable formats and the rapidly expanding premium fresh segment. Dry pet food continues to represent a substantial share of delivered volume, supported by established brand portfolios and efficient logistics economics. Wet pet food maintains a strong presence among consumers prioritizing moisture content, palatability, and specific dietary needs. Fresh and customized food has emerged as the most strategically dynamic category, driven by humanization trends, veterinary-backed formulation narratives, and the operational fit between subscription frequency and refrigerated fulfillment.
On the commercial model side, the market demonstrates a clear tilt toward recurring revenue. Subscription-based delivery accounts for a majority share of market value, reflecting the durability of autoship programs, personalized replenishment schedules, and loyalty-linked fulfillment incentives. One-time purchase transactions remain relevant, particularly for trial purchases, supplementary items, and same-day urgency fulfillment, but they generally contribute less to long-term retention economics. The strategic implication is consistent across categories: companies that can synchronize product design, packaging, and logistics with subscription cadence are better positioned to stabilize demand forecasting, reduce customer acquisition amortization, and build defensible retention loops.
The full report provides a detailed breakdown of these splits and their interaction with pricing tiers, channel mix, and regional purchasing patterns. This level of segmentation detail is critical for operators evaluating whether to expand into fresh formats, adjust autoship incentives, or restructure fulfillment partnerships.
Competitive Landscape: Leadership, Positioning, and Recent Strategic Moves
The competitive environment is defined by a mix of large-scale omnichannel retailers, e-commerce platforms, and specialized direct-to-consumer brands. Market concentration reflects meaningful share held by a limited group of scaled players, with the top three firms capturing approximately 32.4% of market revenue and the top five reaching roughly 45.6%. This concentration indicates that scale advantages in logistics, brand portfolio breadth, and customer data infrastructure matter significantly, while still leaving room for specialized operators that compete on formulation quality, personalization, and category expertise.
Scaled Retail and E-Commerce Platforms
Chewy, headquartered in Plantation, FL, remains a leading online retailer for direct-to-consumer pet food delivery. Its autoship subscription covers dry kibble, wet food, treats, and raw diets across major brands such as Purina and Blue Buffalo. In October 2025, Chewy expanded its fresh pet food line with refrigerated delivery options in partnership with PetSmart Ventures, signaling an intent to deepen its presence in higher-complexity fulfillment categories while leveraging external venture alignment for capability acceleration.
Petco, based in San Diego, CA, provides nationwide pet food delivery through its Vital Care subscription and same-day options, carrying premium brands including Hill's Science Diet and Wellness. In September 2025, Petco introduced unlimited free pet food delivery for Vital Care members, covering more than 5,000 SKUs. This move illustrates how subscription health and fulfillment incentives are being used to reinforce membership economics and reduce churn through perceived value expansion.
PetSmart, headquartered in Phoenix, AZ, offers delivery via its Autoship program with free shipping on orders over 49 USD, incorporating fresh and frozen meals from partners such as JustFoodForDogs. Its strategy highlights the continued relevance of brick-and-mortar-anchored brands extending into recurring digital fulfillment, using partner networks to broaden premium offerings without vertically building every capability in-house.
Amazon, headquartered in Seattle, WA, delivers pet food through Subscribe & Save and Prime fast shipping, featuring private-label brands like Wag! alongside third-party kibble options. Its advantages stem from nationwide fulfillment density, customer reach, and the ability to bundle pet food delivery into broader household subscription ecosystems. For competing brands, Amazon's presence raises the baseline for delivery speed, pricing transparency, and convenience expectations.
Instacart, based in San Francisco, CA, delivers pet food from grocery chains such as Kroger and Costco within hours, supporting same-day pet supply fulfillment. Its role in the market is distinct: rather than operating as a dedicated pet brand, it functions as an on-demand bridge between traditional grocery inventory and immediate household need, capturing urgency-driven purchases and expanding the definition of delivery beyond subscription replenishment.
Specialized Fresh and Direct-to-Consumer Operators
HelloFresh's pet division, operating from Berlin, Germany, manages The Farmer's Dog brand for fresh, human-grade pet food delivered weekly via subscription boxes in the US. In June 2025, The Farmer's Dog opened a new production facility in Columbus, OH to increase fresh pet food delivery capacity by 50%, reinforcing the strategic importance of production scale in sustaining growth for fresh-format subscription brands.
Ollie, headquartered in New York, NY, operates a direct-to-consumer fresh pet food delivery service that customizes recipes based on pet profiles and ships nationwide. Its positioning demonstrates how personalization and veterinary-aligned nutrition narratives can differentiate subscription offerings in a category where consumers are increasingly attentive to ingredient transparency and individual pet needs.
Pet Food Market
Nom Nom, based in San Francisco, CA, delivers veterinarian-formulated fresh pet meals monthly, focusing on nutritionally complete wet food portions. Its approach underscores the continued relevance of formulation expertise and portion design as differentiators, particularly for consumers seeking structured nutritional completeness rather than generalized premium branding.
Collectively, these competitive profiles reveal a marketplace where advantage is increasingly determined by the integration of formulation capability, recurring delivery economics, cold-chain execution, and customer retention design. The full report extends this analysis with a structured competitive benchmarking framework, examining positioning across fulfillment speed, brand portfolio breadth, subscription architecture, and regional service coverage.
What the Full Report Delivers for 2026 Decision-Making
This preview establishes the strategic terrain, but the operational and quantitative depth required for planning resides in the complete research package. The Worldwide Pet Food Delivery Market study is designed to support concrete decisions across strategy, operations, finance, and marketing functions. The report moves beyond high-level sizing to provide an actionable framework for evaluating where to invest, what to optimize, and how to respond to competitive and regulatory pressure.
Inside the full report, readers will find:
- A comprehensive market model spanning historical performance from 2020 to 2025 and a detailed forecast through 2032, anchored in consistent methodology and expressed in USD million.
- Segment-level analysis across food type categories and commercial delivery models, revealing how product format and subscription structure interact with growth dynamics and unit economics.
- Regional evaluation covering North America, Europe, Asia Pacific, and the Rest of the World, with context on adoption maturity, service density, and category preferences that shape localized go-to-market strategy.
- Competitive profiling of key market participants, including operating models, brand portfolios, fulfillment approaches, and recent strategic developments that indicate near-term trajectory.
- Structural market dynamics, including regulatory requirements, ingredient cost context, and trade policy exposure, integrated into the broader interpretation of market opportunity and risk.
- Strategic implications for subscription design, fresh-format expansion, supply chain configuration, and competitive positioning, enabling leadership teams to translate market data into operational priorities.
The purpose of this document is to demonstrate the rigor and applicability of the research while preserving the specific segmentation figures, regional revenue breakdowns, and detailed company-level indicators for the full report. Those data points matter because they convert broad market momentum into actionable investment logic. A company evaluating entry into fresh pet food delivery, for example, needs more than overall growth trends; it needs to understand how category economics vary by format, how subscription retention differs across customer profiles, and how regulatory and sourcing constraints shape feasible operating models in specific markets.
Conclusion: Positioning for the Next Phase of Market Expansion
The worldwide pet food delivery market is entering a phase where growth is increasingly determined by execution quality rather than category tailwinds alone. The forecast trajectory to 2032 points to continued expansion, but the companies that capture disproportionate value will be those that align subscription design, fulfillment capability, formulation strategy, and compliance discipline into a coherent operating model.
For 2026 planning, the strategic questions are already taking shape. How should a brand balance dry, wet, and fresh offerings within its delivery portfolio? What subscription incentives genuinely improve retention without eroding margin? Where do sourcing and tariff exposures create vulnerability, and how should procurement architecture adapt? Which competitive positions are defendable in a market where scale and specialization both matter?
These questions require more than directional insight. They require segment-level quantification, regional nuance, and competitive context that can be directly mapped to operational decisions. The complete Worldwide Pet Food Delivery Market research is built to provide that intelligence, giving executives a structured foundation for investment prioritization, channel strategy, and long-range planning.
Worldwide Pet Food Delivery Market
The market's next chapter will reward organizations that treat delivery not as a tactical channel, but as a strategic system. For decision-makers preparing for 2026, the full report offers the depth required to move from awareness to action with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Food Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Yeast Derivatives Market to Reach $4,775.66M by 2032, Growing at 7.0% CAGR
By pmarketresearch, 2026-09-16
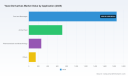
Strategic Intelligence for the Yeast Derivatives Market: Navigating Growth from 2026 to 2032
The global yeast derivatives market stands at a pivotal inflection point. As manufacturers, formulators, and ingredient suppliers recalibrate their portfolios for the next decade, the need for precise, forward-looking intelligence has never been more acute. Our latest Worldwide Yeast Derivatives Market research report delivers a comprehensive, data-grounded view of an industry that is expanding steadily while undergoing rapid structural transformation. This briefing synthesizes the report’s core findings to equip executive teams, commercial strategists, and R&D leaders with the strategic context required to make informed decisions in 2026 and beyond.
Drawing on a multi-year historical baseline and an extended forecast horizon through 2032, the analysis captures both the steady momentum of established value chains and the disruptive forces reshaping supply networks, product formulations, and competitive positioning. Rather than offering static snapshots, the study maps the mechanics of growth: how raw material economics influence production viability, how regulatory frameworks shape application boundaries, and how consolidation and product innovation are redrawing the competitive map.
Macro Trajectory and Forward Outlook
The market has demonstrated consistent expansion across the historical review period, moving from approximately 2,120 million USD in 2020 to an estimated 2,974 million USD by 2025. This trajectory reflects sustained demand across food and beverage formulation, animal nutrition, and an expanding suite of pharmaceutical and biotechnological applications. Building on this base, the forecast period projects a compound annual growth rate of roughly 7.0 percent, with global revenue expected to progress from the 3,163 million USD range in 2026 toward higher plateaus as the decade advances.
Such headline figures, however, only tell part of the story. The true strategic signal lies in the underlying dispersion of growth drivers. Demand is not expanding uniformly; it is being pulled by specific functional requirements, reformulation trends, and regional supply chain recalibrations. The report deconstructs these dynamics across multiple lenses, allowing decision-makers to distinguish between cyclical surges and structural shifts. In an environment where capital allocation and capacity planning require precision, understanding which segments will absorb incremental volume and which will face margin compression is essential.
For organizations evaluating 2026 priorities, the forecast framing is particularly valuable. It situates near-term investment horizons within a longer arc of market maturation, helping leaders differentiate between opportunistic short-term moves and durable competitive advantages. The analysis also highlights the influence of upstream feedstock dynamics on production economics. Molasses remains the primary substrate for yeast cultivation and derivative manufacturing. Pricing volatility, compositional variability, and seasonal availability all feed directly into cost structures and yield efficiency. Recent market observations place molasses pricing in the US market around 295 USD per metric ton during late 2025, reflecting relatively stable supply from sugar processing channels. Yet the sensitivity of yeast growth productivity to substrate fluctuations means that forward-looking procurement and hedging strategies are becoming integral to maintaining cost competitiveness.
Yeast Market
Report Architecture and Actionable Deliverables
The research is structured to support practical decision-making across commercial, operational, and strategic functions. Rather than presenting isolated statistics, the report integrates quantitative sizing with qualitative scenario analysis to help teams stress-test assumptions and align cross-functional roadmaps.
Key components of the study include:
- Detailed segmentation views that break down market value by product type, application, and geographic region, enabling targeted portfolio assessment and go-to-market positioning.
- Comparative analysis of growth vectors, including the relative contribution of mainstream applications versus higher-value niche uses, with attention to formulation trends and ingredient substitution patterns.
- Supply-side evaluation covering production capacity trends, facility expansion activity, and the operational implications of substrate cost movements on derivative manufacturing.
- Regulatory and compliance mapping, including the role of food safety classification frameworks in shaping market access, formulation limits, and product positioning across major jurisdictions.
- Competitive landscape profiling that examines concentration dynamics, strategic moves, and the positioning of leading multinational and regional players.
- Forecast sensitivity and scenario discussion to support sensitivity testing around demand elasticity, input cost variance, and capacity utilization.
Throughout the report, analysts avoid oversimplified aggregations. Instead, the methodology prioritizes transparency around assumptions, data sources, and segmentation logic. This approach allows readers to trace how conclusions are derived and to adapt the insights to their own operational contexts. For instance, a formulation company seeking clean-label alternatives can use the application-level analysis to gauge adoption velocity and pricing tolerance, while a producer evaluating capacity additions can draw on the type-level and regional breakdowns to identify demand pockets with the strongest pull.
Competitive Landscape and Strategic Concentration
The yeast derivatives sector is characterized by a blend of established global incumbents, specialized ingredient specialists, and regionally anchored producers that have expanded their footprints through investment and acquisition. Market concentration metrics indicate a moderately consolidated environment, with the top three players accounting for a significant share of total industry revenue and the top five firms representing a substantial majority. This concentration has implications for pricing power, supply reliability, and the pace at which innovation diffuses through the value chain.
Among the organizations profiled in the study, several stand out for their strategic breadth and active portfolio management. Lesaffre Group, headquartered in France, operates as a global leader across yeast and derivative categories, including extracts, autolysates, beta-glucans, and nucleotides for food, feed, and nutrition applications. Its recent expansion through a major acquisition of a controlling stake in Biorigin’s relevant business unit underscores a deliberate push to strengthen capacity in yeast-derived savory ingredients and specialty solutions. Angel Yeast Co., Ltd., based in China, has been scaling its international footprint while deepening R&D in fermentation technology. The company’s recent product launches introduce yeast-based flavor variants with floral and buttery profiles aimed at natural flavor enhancement, complementing a concurrent capacity expansion initiative for specialty products in China.
Lallemand Inc. of Canada continues to emphasize yeast derivatives spanning extracts, cell wall components, and bioactive compounds for baking, brewing, animal nutrition, and human health, maintaining a recognized presence in probiotic and specialty yeast solutions. On the savory flavor side, Associated British Foods plc through its subsidiary operations focuses on yeast extracts and autolysates that serve taste enhancement and nutritional functions in food processing. Koninklijke DSM N.V., now operating under the DSM-Firmenich framework in the Netherlands, supplies high-purity extracts and functional components across nutrition, food, and biotechnology applications. Kerry Group plc in Ireland contributes yeast extracts as natural flavor enhancers and umami ingredients, aligning with reformulation trends that favor clean-label and plant-compatible taste solutions. Leiber GmbH in Germany specializes in brewers’ yeast derivatives, cell walls, and extracts for food, feed, and pharmaceutical-grade contexts, while Alltech Inc. in the United States supplies extracts and cell wall products with a strong orientation toward animal nutrition and feed additives.
Additional notable participants include Chr. Hansen A/S, now integrated within Novonesis, which develops microbial solutions and yeast derivatives for food cultures and natural ingredients; AB Mauri, which concentrates on baking and specialty yeast derivatives with global production capabilities; and Pak Group in Turkey, which produces yeast and derivatives for baking and industrial applications with a regional and export-oriented strategy. Together, these organizations illustrate the diversity of positioning within the market: some compete primarily on scale and supply reliability, others on functional specificity or application-focused innovation.
Recent Industry Moves Shaping the 2026 Landscape
Strategic activity over the past year signals a market in motion. Consolidation and capability-building transactions are accelerating as companies seek to secure access to differentiated ingredients, expand production capacity, and deepen application expertise. In mid-2025, a major European yeast and derivatives leader completed a transaction to acquire a controlling interest in a business unit focused on yeast-derived savory ingredients, reinforcing its ability to serve flavor and specialty solution demand. Around the same time, a leading Chinese producer introduced a new line of yeast-based flavor variants designed to broaden natural taste options, reflecting continued investment in formulation innovation. By the end of 2025, that same organization had initiated trial production at a new specialty plant designed to support higher-volume output of targeted product lines.
Separately, a prominent brewers’ yeast specialist was acquired by a global food group to expand its international presence and broaden access to derivative-based applications across food and feed channels. These moves collectively highlight three themes that the report examines in greater depth: the premiumization of functional ingredients, the geographic rebalancing of supply capacity, and the growing importance of differentiated taste and nutrition attributes in end-product formulation.
Regulatory and Standards Frameworks as Market Enablers and Constraints
Regulatory classification and safety recognition play a defining role in how yeast derivatives are positioned and adopted. In the United States, yeast extracts are generally recognized as safe for use as flavoring agents and nutrient enhancers in food products, providing a relatively stable pathway for inclusion in a wide range of applications. In Europe, producers operate under stringent food additive oversight and benefit from Qualified Presumption of Safety status for Saccharomyces-based products, which supports market access while also requiring rigorous documentation and quality assurance practices. These frameworks are not merely compliance hurdles; they shape formulation strategies, labeling approaches, and the speed at which new ingredients can be introduced to specific categories.
The report’s regulatory review connects these standards to commercial implications, including the relative ease of market entry for certain derivative types, the potential for reformulation-driven demand shifts, and the operational requirements that differentiate commodity-grade offerings from higher-specification functional ingredients. For suppliers and buyers alike, understanding how regulatory environments vary by region and application is a prerequisite for reliable forecasting and product planning.
Segmentation Insights Without Compromising Analytical Depth
To support precise decision-making, the study provides segmentation views across product types, applications, and regions. In terms of product categories, yeast extracts represent the largest share of market value, followed by autolyzed yeast, yeast cell wall ingredients, and other derivative types. Each category carries distinct functional attributes and application relevance: extracts are widely utilized for flavor and nutrition enhancement, autolyzed forms serve both taste and functional roles, cell wall components are valued in animal nutrition and specialized health applications, and other derivative types address niche formulation needs.
Application-wise, food and beverages dominate total market value, reflecting the breadth of formulation use cases and the ongoing push toward natural taste and texture improvement. Animal feed forms the second major application channel, driven by nutritional additives and functional feed ingredients. Pharmaceuticals and biotechnology account for a smaller but strategically important share, with growth tied to specialized functional components and high-purity requirements. A remaining set of applications encompasses additional industrial and specialty uses.
Regionally, Europe, North America, and Asia Pacific each represent substantial portions of total market value, with Latin America and the Middle East and Africa contributing complementary demand. The report examines these regional profiles not as static shares but as evolving ecosystems shaped by local formulation habits, procurement structures, regulatory environments, and capacity distribution. For 2026 planning, these regional nuances matter: growth opportunities are rarely uniform, and the most effective strategies typically align product positioning and supply planning with regional demand characteristics rather than relying on global averages alone.
Strategic Implications for 2026 Decision-Making
The convergence of sustained top-line growth, active consolidation, raw material sensitivity, and regulatory clarity creates a market environment where informed differentiation can yield durable advantages. The report is designed to help organizations translate market intelligence into concrete actions across several strategic dimensions.
First, portfolio and product strategy can be sharpened by understanding how demand is distributed across categories and applications. Companies can prioritize incremental investment in segments where functional benefits align with end-market reformulation trends, while selectively managing exposure to segments facing cost pressure or substitution risk. Second, supply chain and procurement planning can be strengthened by incorporating substrate cost dynamics and capacity expansion timelines into scenario models, reducing the likelihood of margin surprises. Third, competitive positioning can be refined by mapping how leading players are aligning production footprint, innovation pipelines, and application expertise, enabling more targeted differentiation rather than broad-based competition.
Finally, the forecast period through 2032 provides a long-enough horizon to evaluate capacity decisions, partnership opportunities, and innovation roadmaps against realistic demand trajectories. In a market where multiple routes to growth exist, the ability to distinguish between high-conviction opportunities and marginal gains is a decisive advantage.
This Worldwide Yeast Derivatives Market research report offers the analytical foundation required to make those distinctions with confidence. By combining rigorous sizing, segmentation logic, competitive profiling, and forward-looking scenario discussion, it equips commercial and strategic teams to act decisively in 2026 and to prepare for the structural shifts that will define the remainder of the decade. For the complete dataset, detailed segmentation tables, company profiles, and region-specific forecasts, please access the full report through our official publication page.
Worldwide Yeast Derivatives Market
For detailed analysis of this topic, please visit the official page: Worldwide Yeast Derivatives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Calming Food Market Hits $415M in 2025, 7.95% CAGR to 2032
By pmarketresearch, 2026-09-16
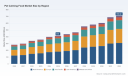
Strategic Intelligence for the Pet Calming Food Market: Navigating Growth and Competition in 2026
The global pet care industry is undergoing a profound transformation driven by the humanization of animals and a heightened focus on welfare beyond basic nutrition. Among the most dynamic segments emerging from this shift is the market for pet calming food and supplements. As anxiety management becomes a priority for pet owners, companies must navigate a complex landscape of ingredient innovation, regulatory compliance, and intensifying competition. Our latest market research report provides a comprehensive analysis of this sector, offering the strategic depth required for informed decision-making throughout the forecast period.
For executives planning capital allocation and product development strategies in 2026, understanding the trajectory of this market is essential. Below, we examine the key structural trends, competitive dynamics, and regulatory frameworks that will define the industry. This preview highlights the analytical rigor of our full study while demonstrating why our proprietary data is critical for maintaining a competitive edge.
Market Trajectory and Structural Growth Drivers
The pet calming food and supplements market has demonstrated consistent resilience and expansion over the past five years. Historical data reveals a steady upward trajectory, reflecting the sustained demand for functional pet nutrition aimed at behavioral health. As we move from the base year into the forecast horizon, the market is positioned to reach new valuation milestones driven by increased consumer awareness and premiumization trends.
Our analysis projects that the global market revenue will continue to expand through the end of the forecast period. This growth is not merely a continuation of past trends but is underpinned by specific structural drivers including the rise of veterinary prescription diets integrating calming ingredients and the mainstreaming of over-the-counter wellness chews. The compound annual growth rate indicates a healthy expansion pace that invites both established players and new entrants to capture value.
- Historical market valuation has shown robust progression, moving from early 2020 levels to significant valuation by the base year.
- The forecast period anticipates a notable acceleration in revenue generation, reflecting broader adoption of calming solutions.
- Key growth catalysts include the increasing prevalence of separation anxiety in pets and the growing willingness of owners to invest in preventive mental health solutions for their companions.
Ingredient Innovation and Product Form Diversification
The formulation landscape of pet calming foods is evolving rapidly. Manufacturers are moving beyond single-ingredient solutions to develop complex blends that target multiple pathways of stress response. Our report details the shifting preferences in product forms, highlighting how texture, palatability, and ease of administration influence consumer purchasing decisions.
Soft chews have emerged as a dominant format due to their high palatability and ability to mask functional ingredients effectively. This segment is gaining substantial share as owners prefer treats that pets enjoy while delivering therapeutic benefits. Concurrently, traditional formats such as treats and biscuits remain relevant, particularly for owners seeking shelf-stable options. Liquids and powders are also gaining traction, especially in veterinary contexts or for pets with specific dietary restrictions.
Pet Food Market
- Soft chews represent a leading share of the product form segmentation, driven by convenience and pet acceptance.
- Treats and biscuits continue to serve as a staple category, often leveraging familiar flavor profiles to enhance consumer trust.
- Liquids and powders offer specialized applications, particularly in formulations requiring precise dosing or integration into wet food diets.
On the ingredient front, the market is seeing a convergence of natural botanicals and scientifically backed compounds. L-theanine derived from green tea is widely utilized for its calming properties without sedation. L-tryptophan serves as a precursor to serotonin, supporting mood regulation. The inclusion of adaptogens such as KSM-66 ashwagandha is gaining momentum, supported by species-specific clinical backing. Herbal ingredients like chamomile and valerian root remain popular for their natural appeal, aligning with the clean label movement that dominates premium pet nutrition.
Competitive Landscape and Strategic Positioning
The competitive environment in the pet calming food market is characterized by a mix of multinational corporations and agile specialty brands. Market concentration analysis reveals that while the top players hold significant share, a substantial portion of the market remains fragmented, allowing for niche innovation and regional expansion. Our report provides a granular assessment of how these companies are leveraging product portfolios, distribution networks, and scientific credibility to differentiate themselves.
Nestlé Purina PetCare, headquartered in St. Louis, Missouri, exemplifies the strategy of integrating calming solutions within a broader veterinary and nutritional ecosystem. Their Pro Plan Veterinary Supplements Calming Care probiotic supplement highlights the trend toward science-backed formulations that address gut-brain axis interactions, positioning the brand as a trusted authority in behavioral health.
Zesty Paws, based in Orlando, Florida, has established a strong presence in the consumer direct space with products like Calming Bites and Advanced Calming Bites. Their approach emphasizes ingredient transparency and consumer education, appealing to owners seeking natural support for stress and anxiety relief in dogs.
Pet Honesty, operating in the USA, has carved a niche by specializing in hemp-based calming chews and supplements that utilize natural ingredients such as valerian root and chamomile. Their product line caters to the growing demand for plant-derived solutions, aligning with wellness trends that span both human and pet nutrition.
Boops Pets has recently demonstrated aggressive innovation with the launch of KSM-66 Ashwagandha Calming Soft Chews for dogs. This product leverages adaptogens and is formulated with species-specific clinical backing for stress relief. The launch underscores the importance of third-party auditing and quality assurance, as evidenced by NASC compliance, which is becoming a critical differentiator in a market sensitive to safety and efficacy claims.
Virbac, with global operations and US headquarters in Texas, markets Anxitane with L-theanine, showcasing the veterinary channel's role in distributing clinically recognized ingredients. Their strategy reflects a focus on professional endorsement and efficacy validation.
NaturVet, associated with GARMON CORP., offers a broad portfolio of calming treats and supplements for pet anxiety management, targeting a wide range of価格 points and pet needs. Ceva Animal Health, based in France with global operations, provides pheromone-based calming solutions and relaxing snacks, illustrating the diversification of modalities beyond ingestion-based products to include environmental and sensory interventions.
Recent developments highlight the pace of activity in this sector. In March 2026, Boops Pets launched its KSM-66 Ashwagandha Calming Soft Chews, emphasizing NASC-audited quality and clinical backing. In April 2026, Kradle announced a nationwide retail launch of Daily Calming Chews, Calming Bliss Bars, and Nighttime Calming Chews at Petco stores, signaling the expansion of calming products into major retail channels and the introduction of format variations such as bars to capture additional consumption occasions.
Regulatory Environment and Industry Dynamics
Regulatory compliance is a cornerstone of market stability and consumer trust in the pet calming food sector. Products are regulated as food under AAFCO and FDA guidelines, which imposes strict requirements on labeling accuracy and safety standards while prohibiting disease treatment claims. This framework necessitates careful communication strategies to ensure that marketing messages align with regulatory boundaries, focusing on support and wellness rather than therapeutic outcomes.
Quality assurance mechanisms are increasingly visible to consumers and retailers. The NASC Quality Seal is utilized by manufacturers as a marker of third-party auditing and quality assurance, providing reassurance regarding ingredient purity and manufacturing practices. As recalls can impact brand reputation and market confidence, adherence to rigorous standards is not only a compliance obligation but a strategic imperative. For instance, industry reports noted a voluntary recall of certain soft chew products in April 2025 due to potential contamination risks, underscoring the importance of supply chain control and batch testing in maintaining market integrity.
Strategic Imperatives for 2026 and Beyond
For companies operating in or entering the pet calming food market, the path to value creation requires a multifaceted strategy. First, product development must be grounded in scientific validation and ingredient efficacy. Investments in clinical backing, such as species-specific studies for adaptogens or amino acids, can command premium pricing and foster deeper consumer trust. Second, distribution channel optimization is critical. The expansion of calming products into mass retail and veterinary channels presents opportunities for scale, but requires distinct branding and educational approaches tailored to each channel's decision-makers and end users.
Third, regulatory agility and quality transparency should be embedded in corporate culture. Proactive compliance with AAFCO and FDA guidelines, coupled with visible quality certifications like the NASC Quality Seal, can mitigate risk and enhance brand equity. Fourth, monitoring the competitive landscape is essential. With brands like Nestlé Purina, Zesty Paws, Pet Honesty, Boops Pets, Virbac, NaturVet, and Ceva Animal Health all competing on different axes of innovation, price, and channel access, companies must identify their unique value proposition and defend it through consistent execution.
Finally, understanding the segmentation of the market by region and pet type is vital for resource allocation. While global trends provide a macro view, regional preferences, regulatory nuances, and pet ownership demographics can vary significantly. Our full report provides the detailed breakdowns necessary to tailor strategies to specific markets, including insights into the relative performance of dogs versus cats and the varying demands across geographic zones.
Pet Calming Food Market
Why This Report Is Essential for Decision-Makers
The pet calming food market is at a pivotal moment where growth potential intersects with increasing complexity. Companies that rely on fragmented data or generic industry summaries risk misallocating resources or missing emerging opportunities. Our market research report delivers the precision and depth required to navigate this environment with confidence. It covers historical performance, forecast trajectories, segmentation analysis, competitive profiling, and regulatory context, all synthesized to support strategic planning for 2026 and the years ahead.
Readers seeking to unlock the full value of this analysis are encouraged to access the complete report. The detailed breakdowns of market size by region, product form, and application, along with comprehensive company profiles, recent developments, and dynamic industry intelligence, are available in the full publication. This preview illustrates the quality and scope of our research, but the actionable intelligence needed for precise budgeting, product roadmap planning, and competitive response resides in the complete dataset and expert commentary provided in the final deliverable.
For detailed analysis of this topic, please visit the official page: Pet Calming Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Data Center Optical Module Market to Hit $47.9B by 2032 at 16.48% CAGR
By pmarketresearch, 2026-09-16
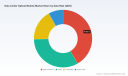
Strategic Intelligence for the AI Infrastructure Era: Inside the Worldwide Data Center Optical Module Market to 2032
The modern data center is no longer a static repository of information. It has evolved into a high-performance computational engine, driving artificial intelligence training, real-time inference, and hyperscale cloud workloads that demand unprecedented bandwidth and energy efficiency. At the heart of this transformation lies the optical module, the critical interface that enables high-speed, low-latency connectivity across server racks, inter-facility links, and global networks. As enterprises navigate the complex intersection of AI adoption, power constraints, and geopolitical supply chain shifts, strategic decisions regarding optical connectivity infrastructure have become a defining competitive differentiator.
PW Consulting presents a comprehensive market research study, the Worldwide Data Center Optical Module Market, designed to equip executive leadership, procurement strategists, and industry investors with the actionable intelligence required to navigate this dynamic landscape from 2026 through 2032. This analysis offers a rigorous, data-driven examination of market trajectories, segmentation dynamics, competitive positioning, and the macro forces reshaping the optical interconnect ecosystem.
A Market Accelerating Beyond Traditional Growth Trajectories
The global market for data center optical modules has entered a period of sustained, high-velocity expansion, fundamentally outpacing historical growth patterns observed in earlier telecom and enterprise networking cycles. Historical data from 2020 through 2025 establishes a clear compound growth narrative, with revenue expanding from approximately 7,520 million USD to over 16,479 million USD by the base year of 2025. This trajectory reflects the rapid deployment of higher-speed interconnects driven by hyperscale cloud expansion, enterprise digital transformation, and the initial wave of AI cluster deployments.
Looking forward, the forecast period spanning 2026 to 2032 projects a steep acceleration, with the market anticipated to reach nearly 47,939 million USD by the terminal forecast year. This expansion is underpinned by a compound annual growth rate of 16.48 percent over the forecast horizon, a figure that underscores the structural, rather than cyclical, nature of current demand. The growth is not merely an extension of existing trends but a reflection of a fundamental architectural shift: the migration from 100G and 400G interconnects toward 800G, 1.6T, and beyond, coupled with the scaling of AI-driven computational infrastructure that requires dense, high-bandwidth fabric connectivity.
The Strategic Imperative for Decision-Makers in 2026
For enterprise architects, supply chain leaders, and capital allocators, the optical module market represents a critical nexus where technology roadmaps, cost structures, and risk management converge. In 2026, several overlapping forces elevate the strategic importance of this market intelligence:
- AI Infrastructure Scaling: The rollout of next-generation AI training and inference clusters demands interconnect solutions that can sustain multi-terabit throughput while minimizing latency and power consumption. Optical module selection directly influences overall system performance, thermal profiles, and total cost of ownership.
- Energy and Operational Cost Pressures: Electricity expenses typically consume around 40 percent of a large data center’s operating budget, amounting to approximately 7.4 million USD annually for large-scale operations. As data center electricity consumption in the United States reached 176 TWh in 2023, representing 4.4 percent of total U.S. electricity, and is projected to surge to between 325 and 580 TWh by 2028, the energy efficiency of optical transceivers and their associated signal processing architectures has become a board-level concern.
- Power Grid and Infrastructure Constraints: U.S. utility companies plan to invest 1.4 trillion USD over the next five years to update the power grid, driven in part by surging data center electricity demand. This infrastructure evolution will influence site selection, capacity planning, and the feasibility of large-scale optical interconnect deployments in key regional hubs.
- Geopolitical and Regulatory Complexity: U.S. export controls apply to advanced semiconductors, high-bandwidth memory, and related items used in data centers supporting AI model training or inference, particularly targeting certain countries. Simultaneously, governments are implementing data sovereignty laws and strategies to ensure control over data and AI infrastructure, influencing data center deployment patterns and optical connectivity requirements across regions.
These dynamics create a decision environment where intuition and legacy procurement models are insufficient. Leaders require granular visibility into how different data rate tiers, transmission distances, protocol ecosystems, and regional demand profiles will evolve, alongside a clear understanding of which suppliers are positioned to deliver scalable, compliant, and technically advanced solutions.
Coherent Optical Module Market
What This Research Delivers: A Practical Blueprint for Action
The Worldwide Data Center Optical Module Market report is structured to translate complex market data into operational guidance. Beyond macroeconomic sizing and growth forecasts, the study provides a detailed segmentation framework that enables stakeholders to evaluate demand across multiple dimensions critical to procurement, product planning, and investment strategy.
The analysis examines the market by region, capturing the distinct demand characteristics, infrastructure maturity, and deployment priorities that shape optical module consumption across North America, Asia Pacific, Europe, Latin America, and the Middle East and Africa. It further dissects the market by data rate, mapping the transition from legacy below-100G deployments through 100G/200G, 400G, and the rapidly expanding 800G and above segments that are redefining high-performance data center fabrics. Transmission distance segmentation distinguishes between short-reach intra-rack and direct-attach applications and intermediate/long-reach solutions that support data center interconnect, metro, and long-haul architectures. Protocol-level analysis clarifies the relative contributions of Ethernet, InfiniBand, and Fibre Channel and other standards, providing insight into the technology paths preferred by different workload profiles and customer segments.
In addition to segmentation, the report delivers a comprehensive competitive landscape assessment. It profiles the strategic positioning, product portfolios, and recent developments of leading market participants, including InnoLight Technology, Coherent Corp., Lumentum Holdings, Eoptolink Technology, Accelink Technologies, Broadcom, Cisco Systems, Applied Optoelectronics, Sumitomo Electric Industries, Hisense Broadband, Marvell Technology, and Fujitsu Optical Components. The analysis evaluates how these firms are responding to the AI-driven demand surge, the pace of their product commercialization, and the implications of their manufacturing and supply chain footprints for buyers and partners.
Recent industry developments illustrate the pace of innovation and commercial activity shaping the market. In April 2026, Applied Optoelectronics received a new upsized 71 million USD order for 800G single-mode data center transceivers from a major hyperscale customer for AI workloads, signaling the scale of demand and the strategic importance of high-volume, high-speed transceiver supply. In March 2026, Marvell Technology expanded its 1.6T optical DSP platform portfolio with new 3nm solutions, including Ara X, Ara T, Petra, and Aquila M, for AI data center connectivity, now sampling to customers. Also in March, Kyocera Corporation developed a pluggable optoelectronic module supporting PCIe 6.0 for high-speed, power-efficient AI data centers, to be exhibited at OFC 2026, while Semtech showcased 1.6T optical interconnect demonstrations and launched new 224 Gbps per lane TIAs and drivers for LPO and LRO architectures. Earlier, in July 2025, Universal Scientific Industrial announced the upcoming release of a next-generation 1.6T optical module for AI and high-performance computing data centers. These milestones reflect an industry in active transition, with multiple technology pathways and supplier capabilities competing for dominance in the next-generation interconnect landscape.
Navigating Competition, Concentration, and Supply Chain Realities
The competitive structure of the global data center optical module market reflects a blend of established multinational component suppliers, specialized transceiver manufacturers, and semiconductor firms extending into photonic integration. Market concentration metrics indicate that the top three players account for approximately 48.25 percent of total revenue, while the top five capture around 64.12 percent. This level of concentration suggests a market where scale, manufacturing capability, and long-term supplier relationships confer meaningful advantages, yet it also leaves substantial room for specialized players and regional participants to compete on technology differentiation, cost, and customer intimacy.
For buyers, this competitive environment carries several practical implications. First, the breadth of available solutions across data rates, transmission distances, and protocols means that procurement strategies must align technical requirements with supplier capabilities and roadmaps. Second, the concentration of revenue among leading suppliers underscores the importance of diversification, supply chain resilience, and contingency planning, particularly in a context where export controls and data sovereignty regulations may affect the availability of advanced components in certain geographies. Third, the rapid iteration of product generations, from 800G to 1.6T and beyond, demands that organizations maintain visibility into supplier development pipelines, sampling timelines, and manufacturing capacity to avoid bottlenecks as AI and high-performance computing deployments scale.
Worldwide Data Center Optical Module Market
Energy, Infrastructure, and the Broader Ecosystem Constraints
The optical module market does not operate in isolation. It is embedded within a broader data center ecosystem where power availability, thermal management, and total cost of ownership exert direct influence on technology selection and deployment economics. The fact that electricity expenses typically consume around 40 percent of a large data center’s operating budget, coupled with projected consumption growth to 325 to 580 TWh by 2028, makes energy efficiency a central criterion in evaluating optical interconnect options. Solutions that reduce power per bit, simplify thermal management, or enable higher density without proportional energy increases will increasingly command preference in procurement decisions.
At the same time, the need for grid modernization, with U.S. utility companies planning to invest 1.4 trillion USD over the next five years, highlights the infrastructural constraints that may shape where and how large-scale optical connectivity deployments can be sustained. Enterprises and cloud providers must factor these constraints into capacity planning, site selection, and the timing of interconnect upgrades. In parallel, regulatory frameworks, including U.S. export controls on advanced semiconductors and related items used in AI data centers, and the proliferation of data sovereignty mandates, add layers of complexity to cross-border supply chains and regional deployment strategies. Organizations that proactively map these constraints against their optical interconnect requirements will be better positioned to mitigate risk and maintain operational continuity.
Why the 2026 Outlook Demands a Forward-Looking Intelligence Framework
As the market advances toward the 2032 forecast horizon, the interplay of technology, cost, regulation, and demand will continue to evolve at a pace that challenges static planning assumptions. The projected expansion to nearly 47,939 million USD by 2032, supported by a 16.48 percent CAGR, signals that optical connectivity will remain a central enabler of data center growth, AI infrastructure scaling, and enterprise digital transformation. However, the distribution of that growth across regions, data rates, transmission distances, and protocols will not be uniform, and the competitive dynamics among suppliers will shift as new product generations, manufacturing investments, and regulatory developments take effect.
Organizations that treat optical module strategy as an afterthought risk facing escalating costs, performance limitations, and supply disruptions. Conversely, those that invest in rigorous market intelligence, align procurement roadmaps with technology trajectories, and incorporate energy, regulatory, and geographic factors into their decision frameworks will gain a measurable advantage in cost efficiency, deployment speed, and strategic flexibility.
Accessing the Full Strategic Picture
This overview provides a structured glimpse into the scope, methodology, and strategic relevance of the Worldwide Data Center Optical Module Market research. It highlights the macroeconomic arc of the market, the segmentation dimensions that matter most to decision-makers, the competitive players shaping the landscape, and the broader ecosystem forces that will influence deployment economics and supply chain resilience. Yet the full value of the study lies in its detailed segmentation data, granular regional and application insights, and comprehensive supplier analysis, which together enable precise scenario planning, benchmarking, and investment prioritization.
For executives, procurement leaders, and investors seeking to secure a decisive advantage in the AI and data center infrastructure race, the complete report offers the depth and specificity required to move from broad awareness to actionable strategy. We invite you to access the full Worldwide Data Center Optical Module Market study to obtain the comprehensive intelligence, detailed data tables, and strategic recommendations that will inform your 2026 decisions and long-term planning through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Data Center Optical Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Micro Perforated Sleeves Market to Reach $777.74M by 2032, 5.85% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for a Breathing Market: Inside the Worldwide Micro Perforated Sleeves Industry (2026-2032)
The global packaging landscape is undergoing a quiet but decisive transformation. As retailers, brand owners, and regulators converge on a single mandate—extend shelf life, reduce food loss, and comply with tightening sustainability frameworks—the demand for controlled-breathability formats has moved from niche experimentation to mainstream procurement. Micro perforated sleeves sit precisely at this intersection. They are no longer just a technical accessory for fresh produce; they are becoming a strategic enabler of supply-chain efficiency, consumer experience, and regulatory resilience.
PW Consulting's latest research, Worldwide Micro Perforated Sleeves Market, was built to help executives navigate this inflection point with precision rather than speculation. Spanning historical analysis from 2020 through the base year of 2025 and extending forecast visibility to 2032, the study translates macro momentum into operational intelligence. Below is a strategic preview of what the report delivers, why it matters for 2026 decision-making, and how leadership teams can convert its findings into competitive advantage.
Why Micro Perforated Sleeves Matter Now
The category's growth is not accidental. It is the product of three reinforcing forces: material science maturation, retail sustainability mandates, and the economics of spoilage reduction. Micro perforation—achieved through hot-needle punching, laser cauterization, or precision die configurations—creates uniform micro-holes that regulate gas exchange without compromising structural integrity or brand presentation. For fresh fruits and vegetables, bakery and confectionery, and floriculture, this means extended freshness windows, fewer rejected units, and a packaging format that can align with recyclable mono-material streams.
The industry context is equally telling. Major retailers across Europe and North America are integrating breathable micro-perforated films into their fresh produce and bakery assortments to cut plastic waste and food loss under internal sustainability mandates. Simultaneously, regulatory architectures such as the EU's Packaging and Packaging Waste Regulation (PPWR) and Extended Producer Responsibility (EPR) schemes are increasing financial accountability for packaging waste. These frameworks do not merely penalize; they incentivize formats that reduce spoilage and support recyclability. In this environment, micro perforated sleeves transition from a cost line to a compliance and margin lever.
Yet the operational reality is nuanced. Raw material volatility remains a persistent variable. For example, BOPP film pricing in the United States reached levels around 2,216 USD/MT in December 2025, with a Q1 2026 outlook trending toward 2,312 USD/MT amid shifting regional supply dynamics. In parallel, polypropylene pricing in key Asian markets climbed to approximately 8,797 CNY/T as of late April 2026, reflecting ongoing feedstock-driven fluctuations across polyolefin-based packaging films. These movements matter because the category is predominantly manufactured from BOPP, CPP, LDPE, LLDPE, HDPE, and other polyolefin films. Decision-makers cannot treat material pricing as a back-office concern; it is a front-line strategic input that shapes sourcing contracts, product mix, and regional deployment.
Market Trajectory: Reading the Signal Behind the Numbers
The market's trajectory from 2020 to 2032 tells a story of recovery, acceleration, and maturation. Revenue expanded from 393.2 million USD in 2020 to 429.51 million USD in 2021, then to 449.55 million USD in 2022 as supply chains stabilized and breathability-driven applications gained traction. The base year of 2025 registers 522.4 million USD, reflecting a market that has absorbed post-pandemic normalization and is now advancing on the strength of application adoption and regulatory tailwinds. The forecast arc continues upward, reaching 555.78 million USD in 2026 and progressing to 615.54 million USD in 2027, with growth continuing through 2032 at 777.74 million USD.
This path is not linear, and that is precisely why executive attention is required. The compound annual growth rate of 5.85 percent across the 2026-2032 forecast window signals steady, structurally supported expansion rather than cyclical overheat. For strategists, this implies a market where disciplined capacity planning, material procurement, and application-specific positioning will separate outperformers from laggards. The report's value lies in decoding where that growth concentrates, which applications are pulling demand, and how regional dynamics shape go-to-market timing.
Importantly, the study deliberately avoids flattening the category into a single narrative. Growth is uneven across film types, end-use segments, and geographies, and each variation carries distinct commercial implications. BOPP film and CPP film continue to anchor large shares of the material mix, while PE film and emerging bio-plastics represent differentiated opportunities tied to recyclability goals and regional supply conditions. On the application side, fresh fruits and vegetables command the largest demand pull, bakery and confectionery follows as a high-visibility growth lane, and floriculture maintains a specialized but resilient position. Regional distribution reflects a mature and diversified footprint, with Europe, Asia Pacific, and North America each presenting distinct procurement rhythms, regulatory pressures, and retail adoption curves, while Latin America and the Middle East and Africa offer earlier-stage but strategically relevant expansion pathways.
Rather than offering static percentage grids, the report maps these segments into decision-ready frameworks: where volume is shifting, which material applications are becoming more cost-sensitive, and how regional retail behavior is reshaping demand timing. This is the difference between knowing that growth exists and knowing where to place capital, sales focus, and R&D effort.
What the Research Actually Delivers
A market report earns its place on the executive dashboard only if it converts data into action. The Worldwide Micro Perforated Sleeves Market study is structured to do exactly that. It is not a high-level brochure; it is an operational intelligence asset designed for sourcing leaders, packaging developers, commercial heads, and corporate strategists.
The report's core analytical components include:
Perforating Gun Market
- A full historical and forecast revenue model spanning 2020-2032, with base-year anchoring at 2025 and a 2026-2032 forecast horizon, allowing teams to benchmark internal performance against category trajectories and test scenario assumptions.
- Material-type analysis that evaluates BOPP film, CPP film, PE film, and other bio-plastics in terms of demand behavior, cost exposure, and suitability for breathability-controlled applications, giving procurement and product development teams a structured basis for mix decisions.
- Application-level insight covering fresh fruits and vegetables, bakery and confectionery, floriculture, and other applications, with attention to how breathability requirements, retail handling, and shelf-life targets shape volume patterns and specification preferences.
- Regional dissection across Europe, Asia Pacific, North America, Latin America, and the Middle East and Africa, focused on market maturity, retail adoption signals, and regulatory influence rather than simplistic share rankings.
- Competitive landscape mapping supported by concentration metrics, including a CR3 of 18.4 percent and CR5 of 28.5 percent, which signals a moderately fragmented environment where specialist capability and custom solutioning can compete effectively against broader-scale players.
- An industry context module that integrates raw-material pricing dynamics, regulatory developments, and retailer adoption behavior into the market narrative, ensuring that strategy is grounded in operational reality rather than headline figures alone.
Each section is built to answer practical questions: Which specifications are gaining retailer acceptance? Where do material price swings most affect margin? How should a supplier sequence regional entry or capacity expansion? How do sustainability mandates change the relative attractiveness of mono-material PE stretch sleeves versus conventional multi-layer formats? The study provides the scaffolding to answer these questions with evidence rather than intuition.
Competitive Landscape: Capability Over Scale
The competitive environment in micro perforated sleeves is defined less by brute scale than by technical differentiation and application specialization. The report profiles a set of companies whose strategies illustrate the range of viable positions in this market.
A-ROO Company, headquartered in Strongsville, Ohio, specializes in custom micro-perforated bags, sleeves, and rolls, with particular depth in conical shapes for horticultural, produce, herb, candy, and snack food markets. Its emphasis on custom perforation levels and made-to-order availability reflects a service-oriented model that caters to brands seeking format precision rather than off-the-shelf uniformity.
Golden Eagle Extrusions, Inc. operates from the United States with a broader flexible packaging orientation, offering hot-needle micro-perforation for breathability control across food, beverage, and industrial applications. Its expertise in coextruded films, lamination, and custom perforated films positions it as a solutions integrator for customers who need breathability embedded within more complex film structures.
Law Packaging, based in Vietnam, manufactures micro perforated flower sleeves and vegetable sleeves from high-quality BOPP and CPP film, with customizable sizes and a clear focus on fresh produce and floral packaging. Its breathability-driven product set illustrates how regional manufacturing can serve global supply chains with cost-competitive, application-tuned offerings.
LasX Industries brings laser-enabled micro-perforation to the flexible packaging space, delivering uniform cauterized holes for freshness control and perforations tailored to shrink-sleeve applications. The laser pathway matters because it can support consistency, gentler material handling, and specification precision that hot-needle or mechanical methods may approach differently.
Repacorp produces tamper-evident perforated shrink sleeves with options for vertical, horizontal, and T-perfs, available in rolls or sheeted formats for automatic or hand application. This portfolio highlights a dual identity for the category: breathability is not the only value driver; tamper evidence, handling efficiency, and format flexibility also shape buyer decisions.
Worldwide Micro Perforated Sleeves Market
C-P Flexible Packaging supplies recyclable mono-material PE stretch sleeves that can incorporate perforations for tamper evidence or easy removal, directly supporting sustainable packaging initiatives. In a regulatory and retail environment that increasingly rewards recyclability, this mono-material orientation is strategically significant.
NanoGrafix Solutions, operating across the UK and Europe, specializes in custom printed shrink sleeves with micro perforations for easy tearing and removal, combining 360-degree branding with tamper protection. Its model underscores how micro perforation can be embedded within a broader brand-experience and packaging-engineering proposition.
Asteria Group, based in Europe, manufactures perforated shrink sleeves using heat-shrinkable plastic films designed to fit various shapes and sizes for innovative packaging solutions. Its focus on conformability and format versatility reflects the practical reality that sleeve performance is as much about geometry and fit as it is about perforation pattern.
Together, these profiles reveal a market where competitive advantage is built on specification control, material expertise, application knowledge, and the ability to align perforation design with brand, retail, and regulatory requirements. The report uses these company snapshots not as an exhaustive directory, but as a lens into the strategic archetypes that shape procurement decisions and market positioning.
Navigating the Forces That Will Shape 2026 and Beyond
For executives planning 2026 moves, the report emphasizes three interconnected dynamics that deserve active management rather than passive observation.
First, raw-material volatility is a structural feature, not a temporary nuisance. With BOPP, CPP, LDPE, LLDPE, HDPE, and other polyolefin films forming the backbone of micro perforated sleeve production, pricing movements ripple directly into cost structures and contract strategy. The study integrates pricing context—such as recent BOPP film price levels in the United States and polypropylene movements in key Asian markets—to help teams anticipate procurement timing, hedging considerations, and the relative attractiveness of alternate material paths where specifications allow.
Second, regulation is reshaping the value proposition. EU EPR schemes and the PPWR framework are increasing financial accountability for packaging waste, which in turn incentivizes formats that reduce food spoilage and support recyclability. For micro perforated sleeves, this is a double-edged opportunity: breathability can lower waste by extending freshness, while material choices can determine whether a sleeve aligns with recyclability expectations. The report maps these regulatory currents so that strategy accounts for compliance risk and compliance-enabled growth alike.
Third, retail adoption is accelerating the category's legitimacy. Major retailers in Europe and the US, including Tesco, Walmart, and Whole Foods, are adopting micro-perforated films for fresh produce and bakery to minimize plastic waste and food loss under sustainability mandates. This is not a peripheral trend; it is a demand signal that can redistribute volume toward specification standards, supplier qualification requirements, and application-specific performance thresholds. The study incorporates these retail initiatives to help suppliers and brand owners anticipate where acceptance criteria are tightening and where commercial opportunities are opening.
How to Use This Research for 2026 Decision-Making
The strategic value of the report lies in its ability to convert a complex, multi-driver market into a set of prioritized actions. For sourcing and procurement leaders, it offers a framework to evaluate material mix, regional pricing exposure, and specification trade-offs without overcommitting to a single film type or supplier archetype. For product and packaging development teams, it clarifies where breathability, tamper evidence, recyclability, and brand presentation intersect—and where they conflict. For commercial leaders, it identifies which applications and regions present the strongest near-term pull and which require longer investment horizons. For corporate strategists, it situates the category within the broader shift toward spoilage reduction, waste accountability, and sustainable packaging design.
The report is also designed to support scenario planning. Because growth is steady but not uniform, teams can use the historical and forecast architecture to test questions such as: How does a material price shock alter the attractiveness of PE-based mono-material sleeves versus BOPP-led formats? How does retail adoption in one region change supplier qualification timing in another? How does regulatory pressure shift the commercial calculus for fresh produce versus bakery applications? By embedding these questions in evidence-based structure, the study helps leaders move from reactive adjustments to proactive positioning.
Conclusion: From Market Signal to Strategic Move
The worldwide micro perforated sleeves market is not simply expanding; it is re-scoping its role within a broader packaging ecosystem that rewards breathability, waste reduction, and regulatory alignment. Revenue growth from 393.2 million USD in 2020 to a forecast of 777.74 million USD by 2032, supported by a 5.85 percent CAGR across 2026-2032, indicates a category with durable momentum. But durability is not the same as ease. Material volatility, regional divergence, application-specific performance needs, and a moderately fragmented competitive field all demand disciplined analysis.
PW Consulting's Worldwide Micro Perforated Sleeves Market report is built to meet that demand. It combines historical grounding, forecast visibility, segmentation insight, competitive benchmarking, and industry-context integration into a single decision-support resource. For organizations preparing 2026 strategies—whether in sourcing, product development, commercial expansion, or sustainability-led packaging transformation—the study offers the depth required to act with confidence.
The full report provides the detailed segmentation, regional breakdowns, application dynamics, and competitive intelligence necessary to convert these strategic signals into executable plans. For teams that need more than macro direction—teams that need specification-level clarity, regional timing insight, and company-level positioning context—the complete research is the essential next step.
For detailed analysis of this topic, please visit the official page: Worldwide Micro Perforated Sleeves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Glucosamine Market Hits $2,250M in 2025, 4.85% CAGR to $3,134.66M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Global Glucosamine Supplements Market: Navigating Growth, Regulation, and Competitive Dynamics in 2026
Executive Overview
The worldwide glucosamine supplements market stands at a critical inflection point as stakeholders transition from historical growth patterns into a forecast period defined by measured expansion and intensifying competitive scrutiny. This report delivers a comprehensive, data-grounded assessment designed specifically for enterprise leaders, product strategists, and investment committees preparing decisions for 2026 and beyond. By aligning historical performance with forward-looking projections, the analysis establishes a clear strategic baseline for portfolio optimization, geographic prioritization, and supply chain resilience. The narrative that follows demonstrates why a rigorous, structured intelligence framework is indispensable for navigating an industry shaped by evolving consumer expectations, regulatory divergence, and raw material cost volatility.
Macro Market Trajectory and Structural Evolution
Historical valuation data reveals a consistent upward trajectory across the tracked period, with the overall market expanding from a baseline of USD 1,750.00 million in 2020 to USD 2,250.00 million in 2025. This progression reflects sustained demand drivers and gradual market maturation rather than isolated spikes. The forecast horizon extends through 2032, with projected revenue scaling toward USD 3,134.66 million by the terminal year. During this interval, the market is expected to compound at a CAGR of 4.85 percent, indicating steady, structurally supported growth rather than speculative acceleration.
Such a growth profile carries distinct strategic implications. Enterprises planning capital allocation, manufacturing footprint, or product pipeline investments must account for a landscape where incremental gains are realized through share capture, formulation differentiation, and channel optimization rather than reliance on broad category tailwinds. The pacing of expansion also underscores the necessity of scenario modeling that accounts for regulatory shifts, ingredient sourcing constraints, and payer accessibility limitations, all of which can compress margins or alter demand elasticity across specific consumer cohorts.
Core Report Architecture and Operational Utility
The study is constructed to translate macro-level movement into executable intelligence. It integrates a multi-dimensional segmentation framework that dissects market behavior across product classifications, application categories, and geographic corridors. Rather than presenting static tables, the analysis maps how structural preferences diverge by region, how end-use adoption patterns create distinct value pools, and where formulation choices influence procurement economics and consumer perception.
Operational depth is reinforced through detailed competitive profiling. The report catalogues the strategic positioning of leading manufacturers, evaluating their product architectures, certification strategies, distribution reach, and recent market actions. By connecting corporate initiatives to broader category trends, the document enables readers to benchmark their own formulations, pricing architectures, and channel strategies against proven market participants. The inclusion of recent corporate milestones, regulatory interpretations, and sourcing economics ensures that each section serves as a decision-support module rather than a descriptive summary.
Strategic readers will find particular value in the report’s treatment of market concentration and competitive fragmentation. By quantifying the share held by leading participants and mapping the broader field of specialized and value-oriented producers, the analysis clarifies where scale advantages translate into procurement leverage, where niche players differentiate through purity claims or hypoallergenic positioning, and where retail-private-label dynamics reshape price expectations. This perspective is essential for any organization evaluating entry, expansion, or repositioning within a category that rewards both scientific credibility and cost discipline.
Competitive Landscape and Strategic Positioning Signals
The competitive environment is defined by a mix of science-forward brands, mass-market retailers, and value-oriented supplement producers, each pursuing distinct routes to consumer trust and repeat purchase. Several established manufacturers continue to anchor their portfolios around glucosamine combined with complementary ingredients such as chondroitin and MSM, reflecting a persistent consumer preference for multi-ingredient joint support formulas. These companies compete not only on dosage and ingredient ratios but also on verification claims, form factor convenience, and perceived bioavailability.
Industry movement over recent quarters illustrates how competitive advantage is being reconfigured. Product launch activity has centered on enhanced formulation complexity, including blends that integrate collagen-related components for broader joint-support narratives. Certification updates have emerged as a critical trust signal, with producers securing third-party verification to reinforce purity and potency claims in an environment where consumers and retail buyers increasingly scrutinize label accuracy. Clinical study publication has further differentiated brands that invest in efficacy communication, using peer-reviewed or internally sponsored data to support mobility and joint comfort messaging. At the same time, geographic expansion by established players into Southeast Asian distribution networks demonstrates how mature-market producers are leveraging partnerships to extend reach in regions with growing aging populations and rising self-care investment.
Strategically, these patterns indicate a market where credibility is becoming as valuable as price competitiveness. Manufacturers that can reconcile rigorous quality standards, transparent sourcing narratives, and targeted clinical or certification-based communication are better positioned to defend price points and sustain brand loyalty. Conversely, value-focused entrants continue to validate demand for economical dosage strengths and combination formulas, ensuring that price sensitivity remains a durable force across multiple consumer segments.
Glucosamine Market
Regulatory, Sourcing, and Demand-Side Dynamics
Market dynamics are heavily shaped by a triad of forces: regulatory classification, raw material economics, and reimbursement reality. In the United States, glucosamine supplements are governed under dietary supplement frameworks rather than as approved drug products, which streamlines market entry but places substantial emphasis on manufacturing standards and post-market compliance. This structure allows rapid product iteration while simultaneously elevating the importance of documented quality systems, accurate labeling, and credible claim language. In parallel, European regulatory interpretation has historically constrained health claim language, reinforcing a bifurcated global environment where manufacturers must tailor communication strategies to jurisdiction-specific evidentiary expectations.
Sourcing economics introduce another layer of strategic complexity. A significant portion of production cost is tied to extraction from shellfish exoskeletons, making supply chains sensitive to marine input availability, processing capacity, and volatility in ingredient procurement. Vegetarian and fungal-derived alternatives exist as premium substitutes, offering formulation flexibility for allergen-sensitive consumers and creating an opportunity for differentiation at higher price tiers. Companies that secure resilient sourcing agreements, qualify alternative ingredient pathways, or communicate transparently about origin and purity can mitigate cost shocks and strengthen consumer trust simultaneously.
Demand-side behavior further reinforces the strategic importance of positioning. A substantial share of older consumers in key markets report using glucosamine as part of self-management routines for knee osteoarthritis, indicating entrenched habitual usage and a willingness to maintain regular intake. Yet accessibility is constrained by the fact that these products are generally not covered by major prescription drug benefit programs, meaning affordability and perceived value remain decisive purchase factors. The result is a consumer base that is both committed and price-aware, rewarding products that can deliver consistent quality, plausible benefit narratives, and accessible packaging or bundle configurations.
Strategic Implications for 2026 Decision-Making
For enterprise leaders planning 2026 initiatives, the market rewards disciplined strategy across several interdependent dimensions. First, portfolio architecture should account for both multi-ingredient premium formulas and economical single or dual-ingredient options, enabling coverage across consumers who prioritize enhanced joint-support narratives and those who seek straightforward, value-driven maintenance products. Second, geographic strategy must be calibrated to regulatory environments and consumer trust mechanisms, since claim language, certification expectations, and distribution structures differ materially across regions. Third, supply chain planning should incorporate ingredient diversification and contingency sourcing, particularly given the cost sensitivity associated with primary raw material inputs.
Worldwide Glucosamine Supplements Market
Marketing and communication strategy also require close alignment with the market’s evidentiary and credibility dynamics. Brands that invest in verification, transparent quality standards, and carefully framed benefit language can better navigate restrictive claim environments while still appealing to habitual users. Retail execution and packaging strategy should reflect the reality that many buyers purchase for ongoing self-management rather than acute therapeutic outcomes, making subscription models, bulk configurations, and clear dosage communication relevant levers for retention. Finally, competitive intelligence must be continuously refreshed, as the field combines established science-oriented manufacturers, retailer private-label programs, and budget-focused entrants, all of whom can pressure price points or capture share through distinct value propositions.
Conclusion and Access to Full Strategic Intelligence
The worldwide glucosamine supplements market presents a structurally resilient but operationally nuanced growth opportunity. Its trajectory through the forecast period reflects steady category expansion, persistent demand from self-managing consumer cohorts, and a competitive arena where credibility, sourcing resilience, and regional adaptation determine long-term positioning. For decision-makers preparing 2026 strategies, the strategic mandate is clear: interpret macro growth as a foundation for disciplined segmentation, build sourcing and compliance frameworks that can withstand input and regulatory variability, and differentiate through verifiable quality and targeted consumer communication.
This article provides an executive-level orientation to the market’s structure, forces, and strategic stakes. It is intended as a precursor to the full research report, which delivers the complete segmentation detail, comparative competitive analysis, regional and application-level breakdowns, and extended scenario commentary necessary for precise commercial planning. To access the full dataset, intensive competitive profiles, and the complete strategic framework, please visit the Worldwide Glucosamine Supplements Market research page and retrieve the comprehensive report.
For detailed analysis of this topic, please visit the official page: Worldwide Glucosamine Supplements Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Global Reconstituted Tobacco Leaf Market to Hit $4,330.78M by 2032 at 4.82% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Era: Inside the Worldwide Reconstituted Tobacco Leaf Market Report
The global tobacco industry stands at a critical inflection point. As raw leaf availability constricts and regulatory frameworks intensify around waste management and environmental responsibility, the economics of reconstituted tobacco leaf (RTL) have moved from a marginal cost-saving exercise to a central pillar of supply chain strategy. For executives navigating the 2026 landscape and beyond, understanding this shift is not optional—it is a prerequisite for resilient product formulation, pricing power, and market positioning. PW Consulting’s newly released Worldwide Reconstituted Tobacco Leaf Market study delivers a comprehensive, data-driven blueprint for decoding this complex ecosystem. This preview outlines the strategic architecture of the report, demonstrating why it serves as an essential decision-support instrument for leaders across tobacco manufacturing, next-generation product development, and allied supply chain operations.
A Market in Structural Transformation
Over the past half-decade, the worldwide RTL market has evolved through cycles of demand volatility, capacity adjustments, and technological adaptation. From a 2020 baseline of approximately $2.51 billion, the sector experienced a brief contraction in 2022 before reasserting a sustained upward trajectory, reaching roughly $3.12 billion in 2025. Looking ahead through 2032, the market is projected to cross $4.33 billion, reflecting a compound annual growth rate of 4.82 percent across the forecast horizon. These figures are not mere historical footnotes; they signal a structural recalibration in how the industry sources, processes, and deploys tobacco biomass. The consistent revenue progression underscores growing institutional reliance on reconstituted formats, particularly as primary leaf production has trended downward in absolute tonnage and harvested area over the past decade. In an environment where sustainability mandates and sourcing constraints converge, RTL’s capacity to transform processing by-products—stems, fines, scraps, and dust—into standardized, high-performance sheet formats has become a strategic asset.
Crucially, the forecasting framework within the report does not treat growth as a monolith. Forward projections capture the nuanced interplay between traditional cigarette volumes, the accelerating pull from heat-not-burn and heated tobacco platforms, and the operational realities of different manufacturing methodologies. By mapping revenue pathways across a multi-year horizon, the study equips decision-makers with scenario-ready intelligence rather than static snapshots. Readers will find granular pathway analysis that isolates acceleration drivers, identifies potential plateau zones, and contextualizes demand elasticity against evolving product architectures—all without exposing the proprietary segment breakdowns that would dilute the analytical edge reserved for full-report subscribers.
Report Architecture and Actionable Intelligence
The study is engineered for executive consumption and operational deployment. Rather than presenting abstract market commentary, it delivers a structured analytical toolkit designed to inform capital allocation, product formulation strategy, supplier evaluation, and risk mitigation. The report’s architecture is built around several interconnected pillars that together form a end-to-end intelligence framework:
- Process-Type Landscape Assessment: A deep comparative evaluation of dominant manufacturing methodologies, examining throughput characteristics, material compatibility, cost structures, and application-specific performance metrics that determine commercial viability across product categories.
- Application-Driven Demand Mapping: An exploration of how RTL integration strategies diverge across traditional smoking formats, heated tobacco ecosystems, and niche applications, highlighting formulation tolerance thresholds, inclusion rate dynamics, and end-market purchasing behaviors that shape volume trajectories.
- Regional Demand and Supply Topology: A structured review of geographic demand centers, logistical considerations, and localized production footprints that influence procurement strategy, export-import dynamics, and regional competitive positioning.
- Competitive Arena Profiling: Detailed corporate assessments of leading RTL producers and homogenized tobacco specialists, covering process capabilities, capacity trajectories, acquisition and partnership activity, and technological differentiation that define market leadership.
- Regulatory and Environmental Dynamics: A forward-looking synthesis of policy momentum, waste management expectations, extended producer responsibility discussions, and sustainability pressures that are reshaping procurement norms and operational compliance requirements.
- Forecasting and Scenario Modeling: A rigorous projection framework extending through 2032, complete with growth rate assumptions, inflection point identification, and sensitivity considerations that allow leadership teams to stress-test strategic plans against alternative demand environments.
Each section is anchored in primary research, validated industry data, and proprietary analytical models. The result is a document that functions simultaneously as a strategic briefing, a competitive reference manual, and a risk-compensation guide. Decision-makers gain the ability to benchmark internal assumptions, validate supplier selection criteria, and align product development roadmaps with observable market momentum—without relying on fragmented secondary sources or outdated industry narratives.
Navigating the Competitive Arena
The RTL competitive landscape is defined by a blend of specialized process expertise, regional manufacturing scale, and accelerating consolidation. Market concentration metrics indicate that the top three participants command a substantial share of total revenue, while the top five collectively represent a majority of market output. This consolidated structure favors organizations with differentiated process capabilities, vertically integrated supply chains, and the agility to adapt production lines to shifting application requirements. Several corporate trajectories stand out as particularly instructive for interpreting the market’s evolution.
In the United States and Indonesia, SWM International, operating under the broader Mativ Holdings and BMJ umbrella, has reinforced its position as a leading RTL producer through a distinctive two-step manufacturing approach tailored for cigarette blends, cut rag, roll-your-own formats, shisha applications, and heat-not-burn use cases. Its portfolio spans customized and ready-to-use reconstituted formulations, supported by legacy operations in France that extend into homogenized tobacco production. The September 2025 acquisition of Tann Group, complementing earlier integration of SWM’s RTL operations, signals a deliberate strategy to broaden homogenized tobacco capabilities and consolidate supply advantages amid rising RTL demand. This consolidation trend illustrates how process specialization and complementary acquisitions are reshaping competitive moats.
Across the Pacific, Guangdong Golden Leaf Technology Development Co., Ltd., a Huabao Group subsidiary, operates one of the world’s largest papermaking-process RTL lines alongside slurry and airlaid process capacity. Its multi-process footprint demonstrates how scale, process diversification, and technical R&D engagement enable producers to address both traditional cigarette supply requirements and the growing pull from heated tobacco platforms. The company’s continued emphasis on line upgrades and large-capacity papermaking throughput reflects an industry-wide imperative to align manufacturing architecture with evolving inclusion rate expectations and product performance demands.
Other significant actors further illustrate the sector’s technological and geographic diversity. LTR Industries, with more than six decades of European manufacturing heritage, specializes in reconstituted tobacco sheet and leaf production and now functions within an expanded homogenized tobacco portfolio. In Indonesia and broader global operations, Star Agritech International supplies reconstituted tobacco in cut and foil formats, leveraging advanced fiber-level recon techniques and multi-origin sourcing to address cost optimization, tar and alkaloid management, and aromatic preservation for B2B buyers. Within China’s Yunnan region, the Reconstituted Tobacco Company of China Tobacco Yunnan Industrial Co., Ltd., with Reascend’s involvement, focuses on papermaking-type RTL sheets while exploring non-tobacco, herbal-based alternatives and production line design support for next-generation applications. Complementing this ecosystem, PT Warlbor International, another Huabao Group facility in Batam, maintains slurry-process capacity oriented toward export supply and HTP-related output, underscoring how regional production nodes are increasingly integrated into multinational RTL strategies.
A notable technical development published in early 2026 highlights the sector’s ongoing innovation trajectory: research into ultrafine powder-based reconstituted tobacco for heated tobacco core materials signals emerging possibilities for performance enhancement in HTP applications. Taken together, these competitive dynamics reveal a market where process differentiation, capacity strategy, and cross-border consolidation are redefining the boundaries of competitive advantage.
Forces Reshaping Demand, Supply, and Strategy
Beyond corporate activity, broader structural forces are compressing the timeline for strategic adaptation. Raw tobacco production has declined materially over the past decade, even as finished-product demand patterns continue to evolve. At the same time, environmental scrutiny surrounding tobacco waste management and pollution is intensifying, with policy discourse increasingly moving toward extended producer responsibility and circular resource utilization. Within this context, RTL’s ability to reintegrate processing remnants into standardized sheet formats offers both an operational efficiency lever and a sustainability narrative that procurement and compliance teams can leverage.
A parallel shift is occurring in application requirements. The rising demand for slurry-process RTL in heated tobacco products illustrates how inclusion rates and material performance expectations differ markedly from traditional cigarette formulations. This divergence is compelling producers to adapt line configurations, binder systems, and quality control protocols, while prompting brand owners and next-generation product developers to reconsider formulation economics and supply continuity. Reports that treat RTL as a single-category input risk missing these critical application-level distinctions; the PW Consulting study is designed to surface them explicitly, enabling clients to align procurement and R&D strategies with the right process and specification mix.
Why This Study Matters for 2026 Decision-Making
The strategic premium of this research lies in its translation of complex market signals into decision-ready intelligence. For 2026 planning cycles, executives face a set of interlocking questions: how will process-type economics influence total cost of ownership across different product lines, which geographic demand clusters will shape procurement and logistics strategy, and how should organizations weight capacity investments against the possibility of accelerated HTP-related pull or regulatory-driven compliance costs. The report does not offer generalized commentary; it provides structured answers framed around measurable market behavior, competitive positioning, and forward-looking trajectory analysis.
By integrating concentration data, process-type and application-level context, regional demand topology, and corporate development tracking, the study offers a multidimensional view that supports both defensive and offensive strategy. Procurement leaders can sharpen supplier evaluation criteria, product developers can calibrate formulation roadmaps against realistic inclusion and performance parameters, and corporate strategy teams can benchmark against evolving consolidation patterns and technological advances. The forecasting framework further enables scenario planning, helping organizations distinguish between incremental growth and structural acceleration when allocating capital or renegotiating supply arrangements.
Worldwide Reconstituted Tobacco Leaf Market
Tobacco Leaves Market
Accessing the Full Strategic Blueprint
This overview provides a representative view of the analytical rigor, market coverage, and strategic orientation embedded in the Worldwide Reconstituted Tobacco Leaf Market study. Yet the complete intelligence architecture—segment-level revenue dynamics, detailed regional breakdowns, process-type competitive comparisons, application-specific demand analysis, and full corporate profiling—resides within the comprehensive report itself. For leaders who require precise, decision-grade intelligence to navigate 2026 and the forecast period through 2032, the full document is the necessary reference point.
PW Consulting has structured this research to function as both a strategic lens and an operational toolkit. The market is moving, consolidation is accelerating, and application-specific requirements are reshaping production priorities. Organizations that equip themselves with validated, forward-looking intelligence will be better positioned to optimize supply strategy, align product development with demand realities, and anticipate the regulatory and environmental forces that will define the next phase of industry evolution.
For detailed analysis of this topic, please visit the official page: Worldwide Reconstituted Tobacco Leaf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Global Car Body Repair Market Hits $206B in 2025, Expects 3.55% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Collision Repair Landscape: Strategic Intelligence for 2026 and Beyond
The global automotive ecosystem is undergoing a structural transformation, and nowhere is this shift more palpable than in the car body repair sector. As vehicles grow increasingly complex and consumer expectations evolve, the market for collision repair, refinishing, and body reconditioning is entering a decisive growth phase. At PW Consulting, we have just released our comprehensive Worldwide Car Body Repair Market research, a strategic intelligence asset designed to equip executives, investors, and industry stakeholders with the foresight needed to navigate the 2026–2032 period with confidence.
This report arrives at a critical inflection point. Drawing on a rigorous analytical framework that spans historical data from 2020 through 2025 and extends our projections to 2032, the study captures the market's trajectory with precision. The global car body repair market, measured in USD millions, traced a compelling arc over the past half-decade. After reaching a valuation of approximately 172,450 million in 2020, the sector demonstrated resilience through the post-pandemic recovery, climbing to 181,478 million in 2021 and further expanding to 191,591 million in 2022. A brief contraction in 2023 to 183,898 million gave way to a robust rebound, with 2024 delivering 203,323 million and 2025 holding at 206,020 million. Looking ahead, the market is projected to reach 214,228 million in 2026, accelerating steadily toward 263,010 million by 2032. This growth trajectory reflects a compound annual growth rate of 3.55 percent across the forecast horizon, signaling a market that is maturing but far from saturated.
For executive teams making capital allocation, partnership, and market-entry decisions in 2026, these figures represent more than macroeconomic noise. They are the foundation upon which competitive advantage is built. Yet raw market size alone does not inform strategy. What separates reactive operators from proactive leaders is the ability to decode the underlying dynamics that drive value creation, margin expansion, and geographic opportunity. This report is engineered to deliver precisely that decoding.
Why This Research Matters for 2026 Decision-Makers
The car body repair sector in 2026 is defined by a convergence of pressures and opportunities that demand calibrated strategic responses. Labor economics remain a persistent challenge. Across the United States, auto body repair labor rates in 2025 averaged between 120 and 160 dollars per hour, contingent on regional differentials and certification levels, while the typical collision repair job carried an average cost near 4,700 dollars. These figures are not static; they reflect structural shifts in skilled labor availability, certification requirements, and the operational intensity of modern repair workflows. Simultaneously, raw material and paint costs for collision repair rose by an average of 7.4 percent in early 2025 across major refinish suppliers, compressing margins and forcing operators to rethink procurement, pricing, and workflow efficiency.
Automotive Body Repair Fillers Market
Regulation and vehicle architecture are compounding these cost dynamics. Increasing OEM requirements for precise electric vehicle and multi-material body repair procedures, including high-voltage battery safety protocols and advanced driver assistance system recalibration, are driving the need for specialized certifications across repair shops. Right-to-repair initiatives and state-level aftermarket parts laws continued to evolve through 2025 and 2026, reshaping parts sourcing options and introducing both compliance risks and sourcing flexibility. Meanwhile, the proliferation of advanced high-strength steel, aluminum, and composite materials in modern car bodies necessitates specialized equipment and training, inflating repair severity and overall cost structures.
In this environment, decision-makers cannot rely on legacy playbooks. The PW Consulting research report provides a structured, evidence-based foundation for evaluating where to invest, how to price, which formats to prioritize, and how to position against competitors who are racing to capture share in a fragmenting yet consolidating landscape. The market's concentration profile—a CR3 of 12.45 percent and a CR5 of 18.22 percent—underscores a sector that remains broadly distributed, leaving substantial room for operators who can combine scale, service quality, and technological readiness.
Inside the Report: Actionable Intelligence Across the Value Chain
This study is built for practitioners who need to move from insight to execution. Rather than offering abstract commentary, the report dissects the market into operational dimensions that directly inform strategy, planning, and performance management. The segmentation architecture covers service providers, component categories, and regional footprints, enabling readers to isolate the levers most relevant to their business model.
Service Provider Landscape
The report profiles the three dominant service provider formats shaping the industry's competitive dynamics. Independent repair shops represent the largest share of market activity, reflecting the enduring role of localized, flexible operators that cater to diverse customer segments and insurance networks. Franchised outlets constitute the second pillar, offering standardized service protocols, brand equity, and scalable operating models that appeal to both consumers and commercial fleets. OEM-managed centers form the third segment, reflecting manufacturer-driven strategies to control repair quality, maintain vehicle integrity, and support warranty and certification pathways. Each format presents distinct economics, growth trajectories, and partnership implications, and the report unpacks these differences in detail.
Component and Material Economics
Understanding the component side of the market is essential for assessing margin pools, supplier dependencies, and procurement strategies. The study examines the three principal component categories that drive repair expenditures: paints and coatings, mechanical and body parts, and consumables and adhesives. These segments are not merely line items; they represent different risk-reward profiles, supplier bargaining dynamics, and innovation pipelines. The report explores how pricing trends, material availability, and technological advances in refinish chemistry and repair materials are reshaping the cost base and influencing shop-level profitability.
Regional Dynamics and Growth Vectors
Geography matters, but not in the way generic regional breakdowns imply. The report situates regional performance within broader macroeconomic, regulatory, and competitive contexts. North America, Europe, and Asia Pacific each present distinct demand drivers, labor market conditions, insurance ecosystems, and OEM influence. Latin America and the Middle East and Africa offer different entry considerations, including infrastructure maturity, parts supply chains, and consumer willingness to invest in repair quality. Rather than presenting isolated percentages, the analysis connects regional patterns to strategic choices about market prioritization, partnership models, and scaling pathways.
Competitive Intelligence and Benchmarking
The report maps the competitive field across repair operators, materials suppliers, and aftermarket parts distributors, highlighting the strategies that separate leaders from laggards. Profiles span high-volume collision repair networks, OEM-certified service providers, paintless dent repair specialists, and global coatings manufacturers. The competitive analysis is anchored in recent industry developments that signal where capital and capability are flowing.
Competitive Moves That Are Redefining the Market
The period from late 2025 into 2026 has been marked by consolidation, specialization, and technology adoption that are reshaping competitive positioning. Caliber Collision, the largest U.S. collision repair operator, expanded its fleet services capabilities in September 2025 by acquiring Car Body Lab, a mobile auto body repair provider operating across 20 cities in seven states. This move illustrates a broader trend: major multi-shop operators are extending their service reach beyond fixed-location collision repair to capture mobile, on-demand, and fleet-oriented workflows.
In January 2026, The Boyd Group Inc., operating Gerber Collision and Glass, announced a major acquisition of Joe Hudson's Collision Centers, one of the largest multi-shop operator-to-multi-shop operator transactions in recent memory, with significant synergies in car body repair capacity. The deal reinforces the momentum behind scale-driven operators seeking to consolidate fragmented regional markets, streamline operations, and strengthen insurance and OEM relationships.
Beyond operator consolidation, the industry's technology agenda is accelerating. The IBIS USA 2026 event in April 2026 emphasized a new cohort of collision repair changemakers prioritizing faster learning cycles, cross-company collaboration, AI integration, and EV-specific body repair certification. The conversation has moved beyond incremental efficiency gains to fundamental rethinking of how repair shops diagnose, process, and complete repairs on vehicles that are increasingly software-defined and material-diverse. These developments are not isolated anecdotes; they are indicators of where competitive advantage will be earned in the years ahead.
The materials supply side is equally dynamic. Companies such as 3M, PPG Industries, Axalta Coating Systems, BASF SE, and AkzoNobel continue to invest in refinish chemistry, advanced repair materials, and application technologies that improve durability, reduce rework, and support the repair of complex surfaces and multi-material architectures. On the parts and distribution side, LKQ Corporation plays a pivotal role in aftermarket and recycled OEM parts availability, while specialized service networks like Fix Auto, Dent Wizard, and CARSTAR illustrate the breadth of formats competing for share through standardization, paintless dent repair expertise, and independently owned franchise models. Understanding how these players interact with repair shops, insurers, and OEMs is essential for anticipating pricing power, supply resilience, and service differentiation.
Strategic Questions the Report Helps Answer
Executives approaching 2026 planning cycles need actionable answers, not generalized trends. This research is structured to support decision-making across a range of strategic questions:
- How should operators balance expansion through acquisition versus organic capacity building, given current consolidation activity and regional fragmentation?
- Which service formats and component categories present the most resilient margin profiles under rising labor and materials costs?
- Where do certification requirements, ADAS calibration, and EV repair readiness create barriers that can be converted into competitive moats?
- How should businesses evaluate regional opportunities in light of insurance dynamics, OEM influence, and parts sourcing regulations?
- What capabilities in workflow automation, AI-assisted estimating, and workforce training are most likely to deliver measurable returns in the near term?
- How can companies position their procurement and supplier relationships to absorb materials cost volatility without eroding customer value?
The report does not merely enumerate possibilities. It provides a disciplined framework for prioritizing initiatives, assessing risk, and aligning investment with the realities of a market that is simultaneously growing, fragmenting, and technologically advancing.
Who Should Use This Research
This study is designed for a broad but targeted audience of professionals whose decisions are shaped by the economics and competitive dynamics of car body repair. For CEOs and strategy leaders at repair operators, the report offers a market-level view to benchmark growth assumptions, evaluate M&A logic, and stress-test expansion plans. For investors and private equity teams, it provides demand trajectory context, competitive structure analysis, and sector-wide risk factors that inform valuation and portfolio construction. For materials and parts suppliers, the research clarifies end-market demand patterns, shop-level purchasing behavior, and the implications of vehicle complexity for product roadmaps. For insurance partners and OEM stakeholders, it illuminates the operational pressures and certification requirements that shape repair outcomes, cycle times, and cost trajectories.
A Preview, Not a Replacement: Access the Full Intelligence
The overview presented here captures the strategic contours of the market and the rationale for deeper investigation, but it is only a preview. The complete PW Consulting Worldwide Car Body Repair Market research delivers the granular segmentation data, regional breakdowns, service provider economics, component-level analysis, and competitive profiling that executives need to make confident decisions. The full report connects the macro trajectory to the micro realities of shop operations, supplier negotiations, and regulatory compliance, enabling readers to translate market intelligence into operational strategy.
The market is moving toward 263,010 million by 2032, but the path to value creation will not be uniform. Operators and investors who understand where growth concentrates, which cost pressures are structural versus cyclical, and how technological and regulatory shifts alter competitive standing will be best positioned to capture disproportionate returns. The detailed segmentation insights, company profiles, and forward-looking scenario analysis contained in the full report are available through our official research page, where you can explore the complete dataset and methodology underpinning this analysis.
Looking Ahead: Positioning for the Next Cycle
The car body repair market in 2026 is not simply expanding; it is evolving in ways that reward preparedness. Rising vehicle complexity, materials cost volatility, labor market constraints, and the imperative to certify for EV and ADAS-related repair procedures are redefining what it takes to compete. At the same time, consolidation among large multi-shop operators and continued innovation from coatings and repair materials suppliers are raising the bar for operational excellence and service quality.
PW Consulting's Worldwide Car Body Repair Market research is built to help leaders navigate this complexity with clarity. By integrating historical performance, forward-looking projections, competitive intelligence, and real-world industry developments into a single analytical framework, the report equips stakeholders to make informed decisions about where to play, how to win, and what capabilities to build now for the cycle ahead. The strategic window for acting on these insights is open; the detailed intelligence required to act decisively is available in the full report.
Worldwide Car Body Repair Market
For detailed analysis of this topic, please visit the official page: Worldwide Car Body Repair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com