

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Yeast Derivatives Market to Reach $4,775.66M by 2032, Growing at 7.0% CAGR

Strategic Intelligence for the Yeast Derivatives Market: Navigating Growth from 2026 to 2032
The global yeast derivatives market stands at a pivotal inflection point. As manufacturers, formulators, and ingredient suppliers recalibrate their portfolios for the next decade, the need for precise, forward-looking intelligence has never been more acute. Our latest Worldwide Yeast Derivatives Market research report delivers a comprehensive, data-grounded view of an industry that is expanding steadily while undergoing rapid structural transformation. This briefing synthesizes the report’s core findings to equip executive teams, commercial strategists, and R&D leaders with the strategic context required to make informed decisions in 2026 and beyond.
Drawing on a multi-year historical baseline and an extended forecast horizon through 2032, the analysis captures both the steady momentum of established value chains and the disruptive forces reshaping supply networks, product formulations, and competitive positioning. Rather than offering static snapshots, the study maps the mechanics of growth: how raw material economics influence production viability, how regulatory frameworks shape application boundaries, and how consolidation and product innovation are redrawing the competitive map.
Macro Trajectory and Forward Outlook
The market has demonstrated consistent expansion across the historical review period, moving from approximately 2,120 million USD in 2020 to an estimated 2,974 million USD by 2025. This trajectory reflects sustained demand across food and beverage formulation, animal nutrition, and an expanding suite of pharmaceutical and biotechnological applications. Building on this base, the forecast period projects a compound annual growth rate of roughly 7.0 percent, with global revenue expected to progress from the 3,163 million USD range in 2026 toward higher plateaus as the decade advances.
Such headline figures, however, only tell part of the story. The true strategic signal lies in the underlying dispersion of growth drivers. Demand is not expanding uniformly; it is being pulled by specific functional requirements, reformulation trends, and regional supply chain recalibrations. The report deconstructs these dynamics across multiple lenses, allowing decision-makers to distinguish between cyclical surges and structural shifts. In an environment where capital allocation and capacity planning require precision, understanding which segments will absorb incremental volume and which will face margin compression is essential.
For organizations evaluating 2026 priorities, the forecast framing is particularly valuable. It situates near-term investment horizons within a longer arc of market maturation, helping leaders differentiate between opportunistic short-term moves and durable competitive advantages. The analysis also highlights the influence of upstream feedstock dynamics on production economics. Molasses remains the primary substrate for yeast cultivation and derivative manufacturing. Pricing volatility, compositional variability, and seasonal availability all feed directly into cost structures and yield efficiency. Recent market observations place molasses pricing in the US market around 295 USD per metric ton during late 2025, reflecting relatively stable supply from sugar processing channels. Yet the sensitivity of yeast growth productivity to substrate fluctuations means that forward-looking procurement and hedging strategies are becoming integral to maintaining cost competitiveness.
Yeast Market
Report Architecture and Actionable Deliverables
The research is structured to support practical decision-making across commercial, operational, and strategic functions. Rather than presenting isolated statistics, the report integrates quantitative sizing with qualitative scenario analysis to help teams stress-test assumptions and align cross-functional roadmaps.
Key components of the study include:
- Detailed segmentation views that break down market value by product type, application, and geographic region, enabling targeted portfolio assessment and go-to-market positioning.
- Comparative analysis of growth vectors, including the relative contribution of mainstream applications versus higher-value niche uses, with attention to formulation trends and ingredient substitution patterns.
- Supply-side evaluation covering production capacity trends, facility expansion activity, and the operational implications of substrate cost movements on derivative manufacturing.
- Regulatory and compliance mapping, including the role of food safety classification frameworks in shaping market access, formulation limits, and product positioning across major jurisdictions.
- Competitive landscape profiling that examines concentration dynamics, strategic moves, and the positioning of leading multinational and regional players.
- Forecast sensitivity and scenario discussion to support sensitivity testing around demand elasticity, input cost variance, and capacity utilization.
Throughout the report, analysts avoid oversimplified aggregations. Instead, the methodology prioritizes transparency around assumptions, data sources, and segmentation logic. This approach allows readers to trace how conclusions are derived and to adapt the insights to their own operational contexts. For instance, a formulation company seeking clean-label alternatives can use the application-level analysis to gauge adoption velocity and pricing tolerance, while a producer evaluating capacity additions can draw on the type-level and regional breakdowns to identify demand pockets with the strongest pull.
Competitive Landscape and Strategic Concentration
The yeast derivatives sector is characterized by a blend of established global incumbents, specialized ingredient specialists, and regionally anchored producers that have expanded their footprints through investment and acquisition. Market concentration metrics indicate a moderately consolidated environment, with the top three players accounting for a significant share of total industry revenue and the top five firms representing a substantial majority. This concentration has implications for pricing power, supply reliability, and the pace at which innovation diffuses through the value chain.
Among the organizations profiled in the study, several stand out for their strategic breadth and active portfolio management. Lesaffre Group, headquartered in France, operates as a global leader across yeast and derivative categories, including extracts, autolysates, beta-glucans, and nucleotides for food, feed, and nutrition applications. Its recent expansion through a major acquisition of a controlling stake in Biorigin’s relevant business unit underscores a deliberate push to strengthen capacity in yeast-derived savory ingredients and specialty solutions. Angel Yeast Co., Ltd., based in China, has been scaling its international footprint while deepening R&D in fermentation technology. The company’s recent product launches introduce yeast-based flavor variants with floral and buttery profiles aimed at natural flavor enhancement, complementing a concurrent capacity expansion initiative for specialty products in China.
Lallemand Inc. of Canada continues to emphasize yeast derivatives spanning extracts, cell wall components, and bioactive compounds for baking, brewing, animal nutrition, and human health, maintaining a recognized presence in probiotic and specialty yeast solutions. On the savory flavor side, Associated British Foods plc through its subsidiary operations focuses on yeast extracts and autolysates that serve taste enhancement and nutritional functions in food processing. Koninklijke DSM N.V., now operating under the DSM-Firmenich framework in the Netherlands, supplies high-purity extracts and functional components across nutrition, food, and biotechnology applications. Kerry Group plc in Ireland contributes yeast extracts as natural flavor enhancers and umami ingredients, aligning with reformulation trends that favor clean-label and plant-compatible taste solutions. Leiber GmbH in Germany specializes in brewers’ yeast derivatives, cell walls, and extracts for food, feed, and pharmaceutical-grade contexts, while Alltech Inc. in the United States supplies extracts and cell wall products with a strong orientation toward animal nutrition and feed additives.
Additional notable participants include Chr. Hansen A/S, now integrated within Novonesis, which develops microbial solutions and yeast derivatives for food cultures and natural ingredients; AB Mauri, which concentrates on baking and specialty yeast derivatives with global production capabilities; and Pak Group in Turkey, which produces yeast and derivatives for baking and industrial applications with a regional and export-oriented strategy. Together, these organizations illustrate the diversity of positioning within the market: some compete primarily on scale and supply reliability, others on functional specificity or application-focused innovation.
Recent Industry Moves Shaping the 2026 Landscape
Strategic activity over the past year signals a market in motion. Consolidation and capability-building transactions are accelerating as companies seek to secure access to differentiated ingredients, expand production capacity, and deepen application expertise. In mid-2025, a major European yeast and derivatives leader completed a transaction to acquire a controlling interest in a business unit focused on yeast-derived savory ingredients, reinforcing its ability to serve flavor and specialty solution demand. Around the same time, a leading Chinese producer introduced a new line of yeast-based flavor variants designed to broaden natural taste options, reflecting continued investment in formulation innovation. By the end of 2025, that same organization had initiated trial production at a new specialty plant designed to support higher-volume output of targeted product lines.
Separately, a prominent brewers’ yeast specialist was acquired by a global food group to expand its international presence and broaden access to derivative-based applications across food and feed channels. These moves collectively highlight three themes that the report examines in greater depth: the premiumization of functional ingredients, the geographic rebalancing of supply capacity, and the growing importance of differentiated taste and nutrition attributes in end-product formulation.
Regulatory and Standards Frameworks as Market Enablers and Constraints
Regulatory classification and safety recognition play a defining role in how yeast derivatives are positioned and adopted. In the United States, yeast extracts are generally recognized as safe for use as flavoring agents and nutrient enhancers in food products, providing a relatively stable pathway for inclusion in a wide range of applications. In Europe, producers operate under stringent food additive oversight and benefit from Qualified Presumption of Safety status for Saccharomyces-based products, which supports market access while also requiring rigorous documentation and quality assurance practices. These frameworks are not merely compliance hurdles; they shape formulation strategies, labeling approaches, and the speed at which new ingredients can be introduced to specific categories.
The report’s regulatory review connects these standards to commercial implications, including the relative ease of market entry for certain derivative types, the potential for reformulation-driven demand shifts, and the operational requirements that differentiate commodity-grade offerings from higher-specification functional ingredients. For suppliers and buyers alike, understanding how regulatory environments vary by region and application is a prerequisite for reliable forecasting and product planning.
Segmentation Insights Without Compromising Analytical Depth
To support precise decision-making, the study provides segmentation views across product types, applications, and regions. In terms of product categories, yeast extracts represent the largest share of market value, followed by autolyzed yeast, yeast cell wall ingredients, and other derivative types. Each category carries distinct functional attributes and application relevance: extracts are widely utilized for flavor and nutrition enhancement, autolyzed forms serve both taste and functional roles, cell wall components are valued in animal nutrition and specialized health applications, and other derivative types address niche formulation needs.
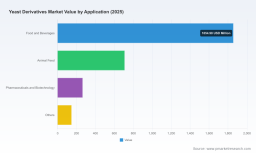
Application-wise, food and beverages dominate total market value, reflecting the breadth of formulation use cases and the ongoing push toward natural taste and texture improvement. Animal feed forms the second major application channel, driven by nutritional additives and functional feed ingredients. Pharmaceuticals and biotechnology account for a smaller but strategically important share, with growth tied to specialized functional components and high-purity requirements. A remaining set of applications encompasses additional industrial and specialty uses.
Regionally, Europe, North America, and Asia Pacific each represent substantial portions of total market value, with Latin America and the Middle East and Africa contributing complementary demand. The report examines these regional profiles not as static shares but as evolving ecosystems shaped by local formulation habits, procurement structures, regulatory environments, and capacity distribution. For 2026 planning, these regional nuances matter: growth opportunities are rarely uniform, and the most effective strategies typically align product positioning and supply planning with regional demand characteristics rather than relying on global averages alone.
Strategic Implications for 2026 Decision-Making
The convergence of sustained top-line growth, active consolidation, raw material sensitivity, and regulatory clarity creates a market environment where informed differentiation can yield durable advantages. The report is designed to help organizations translate market intelligence into concrete actions across several strategic dimensions.
First, portfolio and product strategy can be sharpened by understanding how demand is distributed across categories and applications. Companies can prioritize incremental investment in segments where functional benefits align with end-market reformulation trends, while selectively managing exposure to segments facing cost pressure or substitution risk. Second, supply chain and procurement planning can be strengthened by incorporating substrate cost dynamics and capacity expansion timelines into scenario models, reducing the likelihood of margin surprises. Third, competitive positioning can be refined by mapping how leading players are aligning production footprint, innovation pipelines, and application expertise, enabling more targeted differentiation rather than broad-based competition.
Finally, the forecast period through 2032 provides a long-enough horizon to evaluate capacity decisions, partnership opportunities, and innovation roadmaps against realistic demand trajectories. In a market where multiple routes to growth exist, the ability to distinguish between high-conviction opportunities and marginal gains is a decisive advantage.
This Worldwide Yeast Derivatives Market research report offers the analytical foundation required to make those distinctions with confidence. By combining rigorous sizing, segmentation logic, competitive profiling, and forward-looking scenario discussion, it equips commercial and strategic teams to act decisively in 2026 and to prepare for the structural shifts that will define the remainder of the decade. For the complete dataset, detailed segmentation tables, company profiles, and region-specific forecasts, please access the full report through our official publication page.
Worldwide Yeast Derivatives Market
For detailed analysis of this topic, please visit the official page: Worldwide Yeast Derivatives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com