

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Pet Food Delivery Revenue Hits $6.48B in 2025, Projected 10.51% CAGR to $13B by 2032

Global Pet Food Delivery Market 2026: Strategic Imperatives in a High-Growth Subscription Economy
The worldwide pet food delivery market has transitioned from a discretionary convenience to a core distribution channel for the broader pet care industry. Over the past half-decade, structural shifts in consumer purchasing behavior, advancements in cold-chain logistics, and the maturation of recurring revenue models have fundamentally reshaped how pet nutrition reaches households. For executives, investors, and category managers navigating 2026, understanding the mechanics of this shift is no longer optional. It is a prerequisite for capital allocation, supply chain redesign, and competitive positioning.
This deep-dive analysis draws from our newly released Worldwide Pet Food Delivery Market research to outline the strategic landscape shaping the 2026–2032 forecast period. Rather than offering a superficial overview, the study dissects the operational, regulatory, and competitive forces driving sustained expansion. Below, we preview the critical insights that matter most for enterprise decision-making, while preserving the granular segmentation, pricing architectures, and regional breakdowns exclusively available in the full report.
Market Trajectory: A Decade of Accelerating Adoption and Forecasts Through 2032
The market's historical trajectory reflects a compounding adoption curve that accelerated sharply between 2020 and 2025. Revenue expanded from approximately 3,520.45 million USD in 2020 to 6,480.0 million USD by 2025, signaling a structural migration away from episodic, in-store purchasing toward recurring, digitally mediated fulfillment. This momentum carries directly into the forecast window: the market is projected to reach 7,184.13 million USD in 2026 and continue scaling toward 13,043.27 million USD by 2032.
The compound annual growth rate of 10.51% across the 2026–2032 horizon underscores a market that is compounding rather than merely recovering. Several underlying drivers sustain this trajectory. First, the normalization of subscription-based consumption has reduced purchase friction and elevated customer lifetime value across demographic segments. Second, premiumization trends in pet humanization have shifted spend toward specialized, fresh, and veterinarian-endorsed formulations that align naturally with recurring delivery models. Third, logistics networks have matured enough to support cold-chain and temperature-controlled fulfillment at scale, unlocking product categories that were previously constrained by retail shelf limitations.
For strategic planners, the forecast period presents both expansion opportunity and execution risk. Companies that treat delivery as a pure distribution add-on will likely cede share to operators who have embedded fulfillment architecture into their brand identity, pricing strategy, and unit economics. The full report quantifies the inflection points across product formats, subscription maturity curves, and geographic adoption differentials, enabling leadership teams to calibrate investment timing rather than react to market shifts after they materialize.
Structural Shifts Reshaping Delivery Economics and Consumer Behavior
The pet food delivery ecosystem is being reengineered by intersecting forces that alter cost structures, compliance requirements, and competitive moats. Understanding these dynamics is essential for scenario planning in 2026.
Regulatory Compliance as a Competitive Filter
Regulatory frameworks have moved from background compliance to front-line strategic considerations. In the European Union, Regulation (EU) 2023/2345 mandates clear nutritional labeling on all pet food packaging, including products sold through delivery channels, with compliance effective from January 2024. This requirement compels operators to align packaging, digital product pages, and fulfillment documentation with standardized transparency expectations. Meanwhile, in the United States, the FDA continues to require AAFCO nutrient profile compliance across delivery channels, with 2025 updates refining taurine level requirements to support cardiac health. These updates directly affect formulation strategies, supplier qualification, and quality assurance workflows for brands distributing through subscription or direct-to-consumer pipelines.
Operators that treat regulatory adherence as a periodic checklist often face costly rework, delayed listings, or formulation adjustments late in the product lifecycle. By contrast, organizations that integrate compliance architecture into product development and logistics planning can reduce time-to-market friction and strengthen consumer trust through transparent nutritional communication.
Input Cost Volatility and Supply Chain Configuration
Ingredient pricing and trade policy remain central to margin management. Global corn prices, a foundational input across multiple pet food categories, averaged 198 USD per metric ton in the fourth quarter of 2025 amid relatively stable supply conditions. While short-term stability provides planning visibility, the broader procurement environment remains sensitive to agricultural output variability, energy costs, and regional trade dynamics.
Compounding this sensitivity, US-China tariffs on pet food imports remain at 25% under Section 301, directly affecting delivery supply chains that rely on Asian-sourced ingredients or intermediate components. For operators with cross-border sourcing footprints, the tariff structure influences supplier diversification strategy, domestic manufacturing investment, and inventory positioning. Companies that proactively map ingredient origin, lead-time variability, and tariff exposure can build more resilient procurement architectures, while those with concentrated sourcing may encounter margin compression or fulfillment delays during trade policy shifts.
Segmentation Architecture: Food Type and Subscription Models
The market's composition reflects a divergence between traditional shelf-stable formats and the rapidly expanding premium fresh segment. Dry pet food continues to represent a substantial share of delivered volume, supported by established brand portfolios and efficient logistics economics. Wet pet food maintains a strong presence among consumers prioritizing moisture content, palatability, and specific dietary needs. Fresh and customized food has emerged as the most strategically dynamic category, driven by humanization trends, veterinary-backed formulation narratives, and the operational fit between subscription frequency and refrigerated fulfillment.
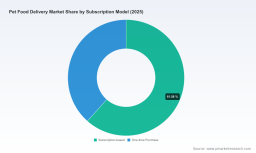
On the commercial model side, the market demonstrates a clear tilt toward recurring revenue. Subscription-based delivery accounts for a majority share of market value, reflecting the durability of autoship programs, personalized replenishment schedules, and loyalty-linked fulfillment incentives. One-time purchase transactions remain relevant, particularly for trial purchases, supplementary items, and same-day urgency fulfillment, but they generally contribute less to long-term retention economics. The strategic implication is consistent across categories: companies that can synchronize product design, packaging, and logistics with subscription cadence are better positioned to stabilize demand forecasting, reduce customer acquisition amortization, and build defensible retention loops.
The full report provides a detailed breakdown of these splits and their interaction with pricing tiers, channel mix, and regional purchasing patterns. This level of segmentation detail is critical for operators evaluating whether to expand into fresh formats, adjust autoship incentives, or restructure fulfillment partnerships.
Competitive Landscape: Leadership, Positioning, and Recent Strategic Moves
The competitive environment is defined by a mix of large-scale omnichannel retailers, e-commerce platforms, and specialized direct-to-consumer brands. Market concentration reflects meaningful share held by a limited group of scaled players, with the top three firms capturing approximately 32.4% of market revenue and the top five reaching roughly 45.6%. This concentration indicates that scale advantages in logistics, brand portfolio breadth, and customer data infrastructure matter significantly, while still leaving room for specialized operators that compete on formulation quality, personalization, and category expertise.
Scaled Retail and E-Commerce Platforms
Chewy, headquartered in Plantation, FL, remains a leading online retailer for direct-to-consumer pet food delivery. Its autoship subscription covers dry kibble, wet food, treats, and raw diets across major brands such as Purina and Blue Buffalo. In October 2025, Chewy expanded its fresh pet food line with refrigerated delivery options in partnership with PetSmart Ventures, signaling an intent to deepen its presence in higher-complexity fulfillment categories while leveraging external venture alignment for capability acceleration.
Petco, based in San Diego, CA, provides nationwide pet food delivery through its Vital Care subscription and same-day options, carrying premium brands including Hill's Science Diet and Wellness. In September 2025, Petco introduced unlimited free pet food delivery for Vital Care members, covering more than 5,000 SKUs. This move illustrates how subscription health and fulfillment incentives are being used to reinforce membership economics and reduce churn through perceived value expansion.
PetSmart, headquartered in Phoenix, AZ, offers delivery via its Autoship program with free shipping on orders over 49 USD, incorporating fresh and frozen meals from partners such as JustFoodForDogs. Its strategy highlights the continued relevance of brick-and-mortar-anchored brands extending into recurring digital fulfillment, using partner networks to broaden premium offerings without vertically building every capability in-house.
Amazon, headquartered in Seattle, WA, delivers pet food through Subscribe & Save and Prime fast shipping, featuring private-label brands like Wag! alongside third-party kibble options. Its advantages stem from nationwide fulfillment density, customer reach, and the ability to bundle pet food delivery into broader household subscription ecosystems. For competing brands, Amazon's presence raises the baseline for delivery speed, pricing transparency, and convenience expectations.
Instacart, based in San Francisco, CA, delivers pet food from grocery chains such as Kroger and Costco within hours, supporting same-day pet supply fulfillment. Its role in the market is distinct: rather than operating as a dedicated pet brand, it functions as an on-demand bridge between traditional grocery inventory and immediate household need, capturing urgency-driven purchases and expanding the definition of delivery beyond subscription replenishment.
Specialized Fresh and Direct-to-Consumer Operators
HelloFresh's pet division, operating from Berlin, Germany, manages The Farmer's Dog brand for fresh, human-grade pet food delivered weekly via subscription boxes in the US. In June 2025, The Farmer's Dog opened a new production facility in Columbus, OH to increase fresh pet food delivery capacity by 50%, reinforcing the strategic importance of production scale in sustaining growth for fresh-format subscription brands.
Ollie, headquartered in New York, NY, operates a direct-to-consumer fresh pet food delivery service that customizes recipes based on pet profiles and ships nationwide. Its positioning demonstrates how personalization and veterinary-aligned nutrition narratives can differentiate subscription offerings in a category where consumers are increasingly attentive to ingredient transparency and individual pet needs.
Pet Food Market
Nom Nom, based in San Francisco, CA, delivers veterinarian-formulated fresh pet meals monthly, focusing on nutritionally complete wet food portions. Its approach underscores the continued relevance of formulation expertise and portion design as differentiators, particularly for consumers seeking structured nutritional completeness rather than generalized premium branding.
Collectively, these competitive profiles reveal a marketplace where advantage is increasingly determined by the integration of formulation capability, recurring delivery economics, cold-chain execution, and customer retention design. The full report extends this analysis with a structured competitive benchmarking framework, examining positioning across fulfillment speed, brand portfolio breadth, subscription architecture, and regional service coverage.
What the Full Report Delivers for 2026 Decision-Making
This preview establishes the strategic terrain, but the operational and quantitative depth required for planning resides in the complete research package. The Worldwide Pet Food Delivery Market study is designed to support concrete decisions across strategy, operations, finance, and marketing functions. The report moves beyond high-level sizing to provide an actionable framework for evaluating where to invest, what to optimize, and how to respond to competitive and regulatory pressure.
Inside the full report, readers will find:
- A comprehensive market model spanning historical performance from 2020 to 2025 and a detailed forecast through 2032, anchored in consistent methodology and expressed in USD million.
- Segment-level analysis across food type categories and commercial delivery models, revealing how product format and subscription structure interact with growth dynamics and unit economics.
- Regional evaluation covering North America, Europe, Asia Pacific, and the Rest of the World, with context on adoption maturity, service density, and category preferences that shape localized go-to-market strategy.
- Competitive profiling of key market participants, including operating models, brand portfolios, fulfillment approaches, and recent strategic developments that indicate near-term trajectory.
- Structural market dynamics, including regulatory requirements, ingredient cost context, and trade policy exposure, integrated into the broader interpretation of market opportunity and risk.
- Strategic implications for subscription design, fresh-format expansion, supply chain configuration, and competitive positioning, enabling leadership teams to translate market data into operational priorities.
The purpose of this document is to demonstrate the rigor and applicability of the research while preserving the specific segmentation figures, regional revenue breakdowns, and detailed company-level indicators for the full report. Those data points matter because they convert broad market momentum into actionable investment logic. A company evaluating entry into fresh pet food delivery, for example, needs more than overall growth trends; it needs to understand how category economics vary by format, how subscription retention differs across customer profiles, and how regulatory and sourcing constraints shape feasible operating models in specific markets.
Conclusion: Positioning for the Next Phase of Market Expansion
The worldwide pet food delivery market is entering a phase where growth is increasingly determined by execution quality rather than category tailwinds alone. The forecast trajectory to 2032 points to continued expansion, but the companies that capture disproportionate value will be those that align subscription design, fulfillment capability, formulation strategy, and compliance discipline into a coherent operating model.
For 2026 planning, the strategic questions are already taking shape. How should a brand balance dry, wet, and fresh offerings within its delivery portfolio? What subscription incentives genuinely improve retention without eroding margin? Where do sourcing and tariff exposures create vulnerability, and how should procurement architecture adapt? Which competitive positions are defendable in a market where scale and specialization both matter?
These questions require more than directional insight. They require segment-level quantification, regional nuance, and competitive context that can be directly mapped to operational decisions. The complete Worldwide Pet Food Delivery Market research is built to provide that intelligence, giving executives a structured foundation for investment prioritization, channel strategy, and long-range planning.
Worldwide Pet Food Delivery Market
The market's next chapter will reward organizations that treat delivery not as a tactical channel, but as a strategic system. For decision-makers preparing for 2026, the full report offers the depth required to move from awareness to action with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Food Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com