

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Reports Global Car Body Repair Market Hits $206B in 2025, Expects 3.55% CAGR Through 2032

Navigating the Collision Repair Landscape: Strategic Intelligence for 2026 and Beyond
The global automotive ecosystem is undergoing a structural transformation, and nowhere is this shift more palpable than in the car body repair sector. As vehicles grow increasingly complex and consumer expectations evolve, the market for collision repair, refinishing, and body reconditioning is entering a decisive growth phase. At PW Consulting, we have just released our comprehensive Worldwide Car Body Repair Market research, a strategic intelligence asset designed to equip executives, investors, and industry stakeholders with the foresight needed to navigate the 2026–2032 period with confidence.
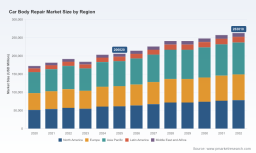
This report arrives at a critical inflection point. Drawing on a rigorous analytical framework that spans historical data from 2020 through 2025 and extends our projections to 2032, the study captures the market's trajectory with precision. The global car body repair market, measured in USD millions, traced a compelling arc over the past half-decade. After reaching a valuation of approximately 172,450 million in 2020, the sector demonstrated resilience through the post-pandemic recovery, climbing to 181,478 million in 2021 and further expanding to 191,591 million in 2022. A brief contraction in 2023 to 183,898 million gave way to a robust rebound, with 2024 delivering 203,323 million and 2025 holding at 206,020 million. Looking ahead, the market is projected to reach 214,228 million in 2026, accelerating steadily toward 263,010 million by 2032. This growth trajectory reflects a compound annual growth rate of 3.55 percent across the forecast horizon, signaling a market that is maturing but far from saturated.
For executive teams making capital allocation, partnership, and market-entry decisions in 2026, these figures represent more than macroeconomic noise. They are the foundation upon which competitive advantage is built. Yet raw market size alone does not inform strategy. What separates reactive operators from proactive leaders is the ability to decode the underlying dynamics that drive value creation, margin expansion, and geographic opportunity. This report is engineered to deliver precisely that decoding.
Why This Research Matters for 2026 Decision-Makers
The car body repair sector in 2026 is defined by a convergence of pressures and opportunities that demand calibrated strategic responses. Labor economics remain a persistent challenge. Across the United States, auto body repair labor rates in 2025 averaged between 120 and 160 dollars per hour, contingent on regional differentials and certification levels, while the typical collision repair job carried an average cost near 4,700 dollars. These figures are not static; they reflect structural shifts in skilled labor availability, certification requirements, and the operational intensity of modern repair workflows. Simultaneously, raw material and paint costs for collision repair rose by an average of 7.4 percent in early 2025 across major refinish suppliers, compressing margins and forcing operators to rethink procurement, pricing, and workflow efficiency.
Automotive Body Repair Fillers Market
Regulation and vehicle architecture are compounding these cost dynamics. Increasing OEM requirements for precise electric vehicle and multi-material body repair procedures, including high-voltage battery safety protocols and advanced driver assistance system recalibration, are driving the need for specialized certifications across repair shops. Right-to-repair initiatives and state-level aftermarket parts laws continued to evolve through 2025 and 2026, reshaping parts sourcing options and introducing both compliance risks and sourcing flexibility. Meanwhile, the proliferation of advanced high-strength steel, aluminum, and composite materials in modern car bodies necessitates specialized equipment and training, inflating repair severity and overall cost structures.
In this environment, decision-makers cannot rely on legacy playbooks. The PW Consulting research report provides a structured, evidence-based foundation for evaluating where to invest, how to price, which formats to prioritize, and how to position against competitors who are racing to capture share in a fragmenting yet consolidating landscape. The market's concentration profile—a CR3 of 12.45 percent and a CR5 of 18.22 percent—underscores a sector that remains broadly distributed, leaving substantial room for operators who can combine scale, service quality, and technological readiness.
Inside the Report: Actionable Intelligence Across the Value Chain
This study is built for practitioners who need to move from insight to execution. Rather than offering abstract commentary, the report dissects the market into operational dimensions that directly inform strategy, planning, and performance management. The segmentation architecture covers service providers, component categories, and regional footprints, enabling readers to isolate the levers most relevant to their business model.
Service Provider Landscape
The report profiles the three dominant service provider formats shaping the industry's competitive dynamics. Independent repair shops represent the largest share of market activity, reflecting the enduring role of localized, flexible operators that cater to diverse customer segments and insurance networks. Franchised outlets constitute the second pillar, offering standardized service protocols, brand equity, and scalable operating models that appeal to both consumers and commercial fleets. OEM-managed centers form the third segment, reflecting manufacturer-driven strategies to control repair quality, maintain vehicle integrity, and support warranty and certification pathways. Each format presents distinct economics, growth trajectories, and partnership implications, and the report unpacks these differences in detail.
Component and Material Economics
Understanding the component side of the market is essential for assessing margin pools, supplier dependencies, and procurement strategies. The study examines the three principal component categories that drive repair expenditures: paints and coatings, mechanical and body parts, and consumables and adhesives. These segments are not merely line items; they represent different risk-reward profiles, supplier bargaining dynamics, and innovation pipelines. The report explores how pricing trends, material availability, and technological advances in refinish chemistry and repair materials are reshaping the cost base and influencing shop-level profitability.
Regional Dynamics and Growth Vectors
Geography matters, but not in the way generic regional breakdowns imply. The report situates regional performance within broader macroeconomic, regulatory, and competitive contexts. North America, Europe, and Asia Pacific each present distinct demand drivers, labor market conditions, insurance ecosystems, and OEM influence. Latin America and the Middle East and Africa offer different entry considerations, including infrastructure maturity, parts supply chains, and consumer willingness to invest in repair quality. Rather than presenting isolated percentages, the analysis connects regional patterns to strategic choices about market prioritization, partnership models, and scaling pathways.
Competitive Intelligence and Benchmarking
The report maps the competitive field across repair operators, materials suppliers, and aftermarket parts distributors, highlighting the strategies that separate leaders from laggards. Profiles span high-volume collision repair networks, OEM-certified service providers, paintless dent repair specialists, and global coatings manufacturers. The competitive analysis is anchored in recent industry developments that signal where capital and capability are flowing.
Competitive Moves That Are Redefining the Market
The period from late 2025 into 2026 has been marked by consolidation, specialization, and technology adoption that are reshaping competitive positioning. Caliber Collision, the largest U.S. collision repair operator, expanded its fleet services capabilities in September 2025 by acquiring Car Body Lab, a mobile auto body repair provider operating across 20 cities in seven states. This move illustrates a broader trend: major multi-shop operators are extending their service reach beyond fixed-location collision repair to capture mobile, on-demand, and fleet-oriented workflows.
In January 2026, The Boyd Group Inc., operating Gerber Collision and Glass, announced a major acquisition of Joe Hudson's Collision Centers, one of the largest multi-shop operator-to-multi-shop operator transactions in recent memory, with significant synergies in car body repair capacity. The deal reinforces the momentum behind scale-driven operators seeking to consolidate fragmented regional markets, streamline operations, and strengthen insurance and OEM relationships.
Beyond operator consolidation, the industry's technology agenda is accelerating. The IBIS USA 2026 event in April 2026 emphasized a new cohort of collision repair changemakers prioritizing faster learning cycles, cross-company collaboration, AI integration, and EV-specific body repair certification. The conversation has moved beyond incremental efficiency gains to fundamental rethinking of how repair shops diagnose, process, and complete repairs on vehicles that are increasingly software-defined and material-diverse. These developments are not isolated anecdotes; they are indicators of where competitive advantage will be earned in the years ahead.
The materials supply side is equally dynamic. Companies such as 3M, PPG Industries, Axalta Coating Systems, BASF SE, and AkzoNobel continue to invest in refinish chemistry, advanced repair materials, and application technologies that improve durability, reduce rework, and support the repair of complex surfaces and multi-material architectures. On the parts and distribution side, LKQ Corporation plays a pivotal role in aftermarket and recycled OEM parts availability, while specialized service networks like Fix Auto, Dent Wizard, and CARSTAR illustrate the breadth of formats competing for share through standardization, paintless dent repair expertise, and independently owned franchise models. Understanding how these players interact with repair shops, insurers, and OEMs is essential for anticipating pricing power, supply resilience, and service differentiation.
Strategic Questions the Report Helps Answer
Executives approaching 2026 planning cycles need actionable answers, not generalized trends. This research is structured to support decision-making across a range of strategic questions:
- How should operators balance expansion through acquisition versus organic capacity building, given current consolidation activity and regional fragmentation?
- Which service formats and component categories present the most resilient margin profiles under rising labor and materials costs?
- Where do certification requirements, ADAS calibration, and EV repair readiness create barriers that can be converted into competitive moats?
- How should businesses evaluate regional opportunities in light of insurance dynamics, OEM influence, and parts sourcing regulations?
- What capabilities in workflow automation, AI-assisted estimating, and workforce training are most likely to deliver measurable returns in the near term?
- How can companies position their procurement and supplier relationships to absorb materials cost volatility without eroding customer value?
The report does not merely enumerate possibilities. It provides a disciplined framework for prioritizing initiatives, assessing risk, and aligning investment with the realities of a market that is simultaneously growing, fragmenting, and technologically advancing.
Who Should Use This Research
This study is designed for a broad but targeted audience of professionals whose decisions are shaped by the economics and competitive dynamics of car body repair. For CEOs and strategy leaders at repair operators, the report offers a market-level view to benchmark growth assumptions, evaluate M&A logic, and stress-test expansion plans. For investors and private equity teams, it provides demand trajectory context, competitive structure analysis, and sector-wide risk factors that inform valuation and portfolio construction. For materials and parts suppliers, the research clarifies end-market demand patterns, shop-level purchasing behavior, and the implications of vehicle complexity for product roadmaps. For insurance partners and OEM stakeholders, it illuminates the operational pressures and certification requirements that shape repair outcomes, cycle times, and cost trajectories.
A Preview, Not a Replacement: Access the Full Intelligence
The overview presented here captures the strategic contours of the market and the rationale for deeper investigation, but it is only a preview. The complete PW Consulting Worldwide Car Body Repair Market research delivers the granular segmentation data, regional breakdowns, service provider economics, component-level analysis, and competitive profiling that executives need to make confident decisions. The full report connects the macro trajectory to the micro realities of shop operations, supplier negotiations, and regulatory compliance, enabling readers to translate market intelligence into operational strategy.
The market is moving toward 263,010 million by 2032, but the path to value creation will not be uniform. Operators and investors who understand where growth concentrates, which cost pressures are structural versus cyclical, and how technological and regulatory shifts alter competitive standing will be best positioned to capture disproportionate returns. The detailed segmentation insights, company profiles, and forward-looking scenario analysis contained in the full report are available through our official research page, where you can explore the complete dataset and methodology underpinning this analysis.
Looking Ahead: Positioning for the Next Cycle
The car body repair market in 2026 is not simply expanding; it is evolving in ways that reward preparedness. Rising vehicle complexity, materials cost volatility, labor market constraints, and the imperative to certify for EV and ADAS-related repair procedures are redefining what it takes to compete. At the same time, consolidation among large multi-shop operators and continued innovation from coatings and repair materials suppliers are raising the bar for operational excellence and service quality.
PW Consulting's Worldwide Car Body Repair Market research is built to help leaders navigate this complexity with clarity. By integrating historical performance, forward-looking projections, competitive intelligence, and real-world industry developments into a single analytical framework, the report equips stakeholders to make informed decisions about where to play, how to win, and what capabilities to build now for the cycle ahead. The strategic window for acting on these insights is open; the detailed intelligence required to act decisively is available in the full report.
Worldwide Car Body Repair Market
For detailed analysis of this topic, please visit the official page: Worldwide Car Body Repair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com