

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Reports Global Reconstituted Tobacco Leaf Market to Hit $4,330.78M by 2032 at 4.82% CAGR

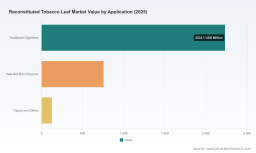
Strategic Intelligence for the Next Era: Inside the Worldwide Reconstituted Tobacco Leaf Market Report
The global tobacco industry stands at a critical inflection point. As raw leaf availability constricts and regulatory frameworks intensify around waste management and environmental responsibility, the economics of reconstituted tobacco leaf (RTL) have moved from a marginal cost-saving exercise to a central pillar of supply chain strategy. For executives navigating the 2026 landscape and beyond, understanding this shift is not optional—it is a prerequisite for resilient product formulation, pricing power, and market positioning. PW Consulting’s newly released Worldwide Reconstituted Tobacco Leaf Market study delivers a comprehensive, data-driven blueprint for decoding this complex ecosystem. This preview outlines the strategic architecture of the report, demonstrating why it serves as an essential decision-support instrument for leaders across tobacco manufacturing, next-generation product development, and allied supply chain operations.
A Market in Structural Transformation
Over the past half-decade, the worldwide RTL market has evolved through cycles of demand volatility, capacity adjustments, and technological adaptation. From a 2020 baseline of approximately $2.51 billion, the sector experienced a brief contraction in 2022 before reasserting a sustained upward trajectory, reaching roughly $3.12 billion in 2025. Looking ahead through 2032, the market is projected to cross $4.33 billion, reflecting a compound annual growth rate of 4.82 percent across the forecast horizon. These figures are not mere historical footnotes; they signal a structural recalibration in how the industry sources, processes, and deploys tobacco biomass. The consistent revenue progression underscores growing institutional reliance on reconstituted formats, particularly as primary leaf production has trended downward in absolute tonnage and harvested area over the past decade. In an environment where sustainability mandates and sourcing constraints converge, RTL’s capacity to transform processing by-products—stems, fines, scraps, and dust—into standardized, high-performance sheet formats has become a strategic asset.
Crucially, the forecasting framework within the report does not treat growth as a monolith. Forward projections capture the nuanced interplay between traditional cigarette volumes, the accelerating pull from heat-not-burn and heated tobacco platforms, and the operational realities of different manufacturing methodologies. By mapping revenue pathways across a multi-year horizon, the study equips decision-makers with scenario-ready intelligence rather than static snapshots. Readers will find granular pathway analysis that isolates acceleration drivers, identifies potential plateau zones, and contextualizes demand elasticity against evolving product architectures—all without exposing the proprietary segment breakdowns that would dilute the analytical edge reserved for full-report subscribers.
Report Architecture and Actionable Intelligence
The study is engineered for executive consumption and operational deployment. Rather than presenting abstract market commentary, it delivers a structured analytical toolkit designed to inform capital allocation, product formulation strategy, supplier evaluation, and risk mitigation. The report’s architecture is built around several interconnected pillars that together form a end-to-end intelligence framework:
- Process-Type Landscape Assessment: A deep comparative evaluation of dominant manufacturing methodologies, examining throughput characteristics, material compatibility, cost structures, and application-specific performance metrics that determine commercial viability across product categories.
- Application-Driven Demand Mapping: An exploration of how RTL integration strategies diverge across traditional smoking formats, heated tobacco ecosystems, and niche applications, highlighting formulation tolerance thresholds, inclusion rate dynamics, and end-market purchasing behaviors that shape volume trajectories.
- Regional Demand and Supply Topology: A structured review of geographic demand centers, logistical considerations, and localized production footprints that influence procurement strategy, export-import dynamics, and regional competitive positioning.
- Competitive Arena Profiling: Detailed corporate assessments of leading RTL producers and homogenized tobacco specialists, covering process capabilities, capacity trajectories, acquisition and partnership activity, and technological differentiation that define market leadership.
- Regulatory and Environmental Dynamics: A forward-looking synthesis of policy momentum, waste management expectations, extended producer responsibility discussions, and sustainability pressures that are reshaping procurement norms and operational compliance requirements.
- Forecasting and Scenario Modeling: A rigorous projection framework extending through 2032, complete with growth rate assumptions, inflection point identification, and sensitivity considerations that allow leadership teams to stress-test strategic plans against alternative demand environments.
Each section is anchored in primary research, validated industry data, and proprietary analytical models. The result is a document that functions simultaneously as a strategic briefing, a competitive reference manual, and a risk-compensation guide. Decision-makers gain the ability to benchmark internal assumptions, validate supplier selection criteria, and align product development roadmaps with observable market momentum—without relying on fragmented secondary sources or outdated industry narratives.
Navigating the Competitive Arena
The RTL competitive landscape is defined by a blend of specialized process expertise, regional manufacturing scale, and accelerating consolidation. Market concentration metrics indicate that the top three participants command a substantial share of total revenue, while the top five collectively represent a majority of market output. This consolidated structure favors organizations with differentiated process capabilities, vertically integrated supply chains, and the agility to adapt production lines to shifting application requirements. Several corporate trajectories stand out as particularly instructive for interpreting the market’s evolution.
In the United States and Indonesia, SWM International, operating under the broader Mativ Holdings and BMJ umbrella, has reinforced its position as a leading RTL producer through a distinctive two-step manufacturing approach tailored for cigarette blends, cut rag, roll-your-own formats, shisha applications, and heat-not-burn use cases. Its portfolio spans customized and ready-to-use reconstituted formulations, supported by legacy operations in France that extend into homogenized tobacco production. The September 2025 acquisition of Tann Group, complementing earlier integration of SWM’s RTL operations, signals a deliberate strategy to broaden homogenized tobacco capabilities and consolidate supply advantages amid rising RTL demand. This consolidation trend illustrates how process specialization and complementary acquisitions are reshaping competitive moats.
Across the Pacific, Guangdong Golden Leaf Technology Development Co., Ltd., a Huabao Group subsidiary, operates one of the world’s largest papermaking-process RTL lines alongside slurry and airlaid process capacity. Its multi-process footprint demonstrates how scale, process diversification, and technical R&D engagement enable producers to address both traditional cigarette supply requirements and the growing pull from heated tobacco platforms. The company’s continued emphasis on line upgrades and large-capacity papermaking throughput reflects an industry-wide imperative to align manufacturing architecture with evolving inclusion rate expectations and product performance demands.
Other significant actors further illustrate the sector’s technological and geographic diversity. LTR Industries, with more than six decades of European manufacturing heritage, specializes in reconstituted tobacco sheet and leaf production and now functions within an expanded homogenized tobacco portfolio. In Indonesia and broader global operations, Star Agritech International supplies reconstituted tobacco in cut and foil formats, leveraging advanced fiber-level recon techniques and multi-origin sourcing to address cost optimization, tar and alkaloid management, and aromatic preservation for B2B buyers. Within China’s Yunnan region, the Reconstituted Tobacco Company of China Tobacco Yunnan Industrial Co., Ltd., with Reascend’s involvement, focuses on papermaking-type RTL sheets while exploring non-tobacco, herbal-based alternatives and production line design support for next-generation applications. Complementing this ecosystem, PT Warlbor International, another Huabao Group facility in Batam, maintains slurry-process capacity oriented toward export supply and HTP-related output, underscoring how regional production nodes are increasingly integrated into multinational RTL strategies.
A notable technical development published in early 2026 highlights the sector’s ongoing innovation trajectory: research into ultrafine powder-based reconstituted tobacco for heated tobacco core materials signals emerging possibilities for performance enhancement in HTP applications. Taken together, these competitive dynamics reveal a market where process differentiation, capacity strategy, and cross-border consolidation are redefining the boundaries of competitive advantage.
Forces Reshaping Demand, Supply, and Strategy
Beyond corporate activity, broader structural forces are compressing the timeline for strategic adaptation. Raw tobacco production has declined materially over the past decade, even as finished-product demand patterns continue to evolve. At the same time, environmental scrutiny surrounding tobacco waste management and pollution is intensifying, with policy discourse increasingly moving toward extended producer responsibility and circular resource utilization. Within this context, RTL’s ability to reintegrate processing remnants into standardized sheet formats offers both an operational efficiency lever and a sustainability narrative that procurement and compliance teams can leverage.
A parallel shift is occurring in application requirements. The rising demand for slurry-process RTL in heated tobacco products illustrates how inclusion rates and material performance expectations differ markedly from traditional cigarette formulations. This divergence is compelling producers to adapt line configurations, binder systems, and quality control protocols, while prompting brand owners and next-generation product developers to reconsider formulation economics and supply continuity. Reports that treat RTL as a single-category input risk missing these critical application-level distinctions; the PW Consulting study is designed to surface them explicitly, enabling clients to align procurement and R&D strategies with the right process and specification mix.
Why This Study Matters for 2026 Decision-Making
The strategic premium of this research lies in its translation of complex market signals into decision-ready intelligence. For 2026 planning cycles, executives face a set of interlocking questions: how will process-type economics influence total cost of ownership across different product lines, which geographic demand clusters will shape procurement and logistics strategy, and how should organizations weight capacity investments against the possibility of accelerated HTP-related pull or regulatory-driven compliance costs. The report does not offer generalized commentary; it provides structured answers framed around measurable market behavior, competitive positioning, and forward-looking trajectory analysis.
By integrating concentration data, process-type and application-level context, regional demand topology, and corporate development tracking, the study offers a multidimensional view that supports both defensive and offensive strategy. Procurement leaders can sharpen supplier evaluation criteria, product developers can calibrate formulation roadmaps against realistic inclusion and performance parameters, and corporate strategy teams can benchmark against evolving consolidation patterns and technological advances. The forecasting framework further enables scenario planning, helping organizations distinguish between incremental growth and structural acceleration when allocating capital or renegotiating supply arrangements.
Worldwide Reconstituted Tobacco Leaf Market
Tobacco Leaves Market
Accessing the Full Strategic Blueprint
This overview provides a representative view of the analytical rigor, market coverage, and strategic orientation embedded in the Worldwide Reconstituted Tobacco Leaf Market study. Yet the complete intelligence architecture—segment-level revenue dynamics, detailed regional breakdowns, process-type competitive comparisons, application-specific demand analysis, and full corporate profiling—resides within the comprehensive report itself. For leaders who require precise, decision-grade intelligence to navigate 2026 and the forecast period through 2032, the full document is the necessary reference point.
PW Consulting has structured this research to function as both a strategic lens and an operational toolkit. The market is moving, consolidation is accelerating, and application-specific requirements are reshaping production priorities. Organizations that equip themselves with validated, forward-looking intelligence will be better positioned to optimize supply strategy, align product development with demand realities, and anticipate the regulatory and environmental forces that will define the next phase of industry evolution.
For detailed analysis of this topic, please visit the official page: Worldwide Reconstituted Tobacco Leaf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com