

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Data Center Optical Module Market to Hit $47.9B by 2032 at 16.48% CAGR

Strategic Intelligence for the AI Infrastructure Era: Inside the Worldwide Data Center Optical Module Market to 2032
The modern data center is no longer a static repository of information. It has evolved into a high-performance computational engine, driving artificial intelligence training, real-time inference, and hyperscale cloud workloads that demand unprecedented bandwidth and energy efficiency. At the heart of this transformation lies the optical module, the critical interface that enables high-speed, low-latency connectivity across server racks, inter-facility links, and global networks. As enterprises navigate the complex intersection of AI adoption, power constraints, and geopolitical supply chain shifts, strategic decisions regarding optical connectivity infrastructure have become a defining competitive differentiator.
PW Consulting presents a comprehensive market research study, the Worldwide Data Center Optical Module Market, designed to equip executive leadership, procurement strategists, and industry investors with the actionable intelligence required to navigate this dynamic landscape from 2026 through 2032. This analysis offers a rigorous, data-driven examination of market trajectories, segmentation dynamics, competitive positioning, and the macro forces reshaping the optical interconnect ecosystem.
A Market Accelerating Beyond Traditional Growth Trajectories
The global market for data center optical modules has entered a period of sustained, high-velocity expansion, fundamentally outpacing historical growth patterns observed in earlier telecom and enterprise networking cycles. Historical data from 2020 through 2025 establishes a clear compound growth narrative, with revenue expanding from approximately 7,520 million USD to over 16,479 million USD by the base year of 2025. This trajectory reflects the rapid deployment of higher-speed interconnects driven by hyperscale cloud expansion, enterprise digital transformation, and the initial wave of AI cluster deployments.
Looking forward, the forecast period spanning 2026 to 2032 projects a steep acceleration, with the market anticipated to reach nearly 47,939 million USD by the terminal forecast year. This expansion is underpinned by a compound annual growth rate of 16.48 percent over the forecast horizon, a figure that underscores the structural, rather than cyclical, nature of current demand. The growth is not merely an extension of existing trends but a reflection of a fundamental architectural shift: the migration from 100G and 400G interconnects toward 800G, 1.6T, and beyond, coupled with the scaling of AI-driven computational infrastructure that requires dense, high-bandwidth fabric connectivity.
The Strategic Imperative for Decision-Makers in 2026
For enterprise architects, supply chain leaders, and capital allocators, the optical module market represents a critical nexus where technology roadmaps, cost structures, and risk management converge. In 2026, several overlapping forces elevate the strategic importance of this market intelligence:
- AI Infrastructure Scaling: The rollout of next-generation AI training and inference clusters demands interconnect solutions that can sustain multi-terabit throughput while minimizing latency and power consumption. Optical module selection directly influences overall system performance, thermal profiles, and total cost of ownership.
- Energy and Operational Cost Pressures: Electricity expenses typically consume around 40 percent of a large data center’s operating budget, amounting to approximately 7.4 million USD annually for large-scale operations. As data center electricity consumption in the United States reached 176 TWh in 2023, representing 4.4 percent of total U.S. electricity, and is projected to surge to between 325 and 580 TWh by 2028, the energy efficiency of optical transceivers and their associated signal processing architectures has become a board-level concern.
- Power Grid and Infrastructure Constraints: U.S. utility companies plan to invest 1.4 trillion USD over the next five years to update the power grid, driven in part by surging data center electricity demand. This infrastructure evolution will influence site selection, capacity planning, and the feasibility of large-scale optical interconnect deployments in key regional hubs.
- Geopolitical and Regulatory Complexity: U.S. export controls apply to advanced semiconductors, high-bandwidth memory, and related items used in data centers supporting AI model training or inference, particularly targeting certain countries. Simultaneously, governments are implementing data sovereignty laws and strategies to ensure control over data and AI infrastructure, influencing data center deployment patterns and optical connectivity requirements across regions.
These dynamics create a decision environment where intuition and legacy procurement models are insufficient. Leaders require granular visibility into how different data rate tiers, transmission distances, protocol ecosystems, and regional demand profiles will evolve, alongside a clear understanding of which suppliers are positioned to deliver scalable, compliant, and technically advanced solutions.
Coherent Optical Module Market
What This Research Delivers: A Practical Blueprint for Action
The Worldwide Data Center Optical Module Market report is structured to translate complex market data into operational guidance. Beyond macroeconomic sizing and growth forecasts, the study provides a detailed segmentation framework that enables stakeholders to evaluate demand across multiple dimensions critical to procurement, product planning, and investment strategy.
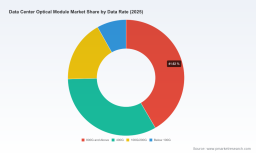
The analysis examines the market by region, capturing the distinct demand characteristics, infrastructure maturity, and deployment priorities that shape optical module consumption across North America, Asia Pacific, Europe, Latin America, and the Middle East and Africa. It further dissects the market by data rate, mapping the transition from legacy below-100G deployments through 100G/200G, 400G, and the rapidly expanding 800G and above segments that are redefining high-performance data center fabrics. Transmission distance segmentation distinguishes between short-reach intra-rack and direct-attach applications and intermediate/long-reach solutions that support data center interconnect, metro, and long-haul architectures. Protocol-level analysis clarifies the relative contributions of Ethernet, InfiniBand, and Fibre Channel and other standards, providing insight into the technology paths preferred by different workload profiles and customer segments.
In addition to segmentation, the report delivers a comprehensive competitive landscape assessment. It profiles the strategic positioning, product portfolios, and recent developments of leading market participants, including InnoLight Technology, Coherent Corp., Lumentum Holdings, Eoptolink Technology, Accelink Technologies, Broadcom, Cisco Systems, Applied Optoelectronics, Sumitomo Electric Industries, Hisense Broadband, Marvell Technology, and Fujitsu Optical Components. The analysis evaluates how these firms are responding to the AI-driven demand surge, the pace of their product commercialization, and the implications of their manufacturing and supply chain footprints for buyers and partners.
Recent industry developments illustrate the pace of innovation and commercial activity shaping the market. In April 2026, Applied Optoelectronics received a new upsized 71 million USD order for 800G single-mode data center transceivers from a major hyperscale customer for AI workloads, signaling the scale of demand and the strategic importance of high-volume, high-speed transceiver supply. In March 2026, Marvell Technology expanded its 1.6T optical DSP platform portfolio with new 3nm solutions, including Ara X, Ara T, Petra, and Aquila M, for AI data center connectivity, now sampling to customers. Also in March, Kyocera Corporation developed a pluggable optoelectronic module supporting PCIe 6.0 for high-speed, power-efficient AI data centers, to be exhibited at OFC 2026, while Semtech showcased 1.6T optical interconnect demonstrations and launched new 224 Gbps per lane TIAs and drivers for LPO and LRO architectures. Earlier, in July 2025, Universal Scientific Industrial announced the upcoming release of a next-generation 1.6T optical module for AI and high-performance computing data centers. These milestones reflect an industry in active transition, with multiple technology pathways and supplier capabilities competing for dominance in the next-generation interconnect landscape.
Navigating Competition, Concentration, and Supply Chain Realities
The competitive structure of the global data center optical module market reflects a blend of established multinational component suppliers, specialized transceiver manufacturers, and semiconductor firms extending into photonic integration. Market concentration metrics indicate that the top three players account for approximately 48.25 percent of total revenue, while the top five capture around 64.12 percent. This level of concentration suggests a market where scale, manufacturing capability, and long-term supplier relationships confer meaningful advantages, yet it also leaves substantial room for specialized players and regional participants to compete on technology differentiation, cost, and customer intimacy.
For buyers, this competitive environment carries several practical implications. First, the breadth of available solutions across data rates, transmission distances, and protocols means that procurement strategies must align technical requirements with supplier capabilities and roadmaps. Second, the concentration of revenue among leading suppliers underscores the importance of diversification, supply chain resilience, and contingency planning, particularly in a context where export controls and data sovereignty regulations may affect the availability of advanced components in certain geographies. Third, the rapid iteration of product generations, from 800G to 1.6T and beyond, demands that organizations maintain visibility into supplier development pipelines, sampling timelines, and manufacturing capacity to avoid bottlenecks as AI and high-performance computing deployments scale.
Worldwide Data Center Optical Module Market
Energy, Infrastructure, and the Broader Ecosystem Constraints
The optical module market does not operate in isolation. It is embedded within a broader data center ecosystem where power availability, thermal management, and total cost of ownership exert direct influence on technology selection and deployment economics. The fact that electricity expenses typically consume around 40 percent of a large data center’s operating budget, coupled with projected consumption growth to 325 to 580 TWh by 2028, makes energy efficiency a central criterion in evaluating optical interconnect options. Solutions that reduce power per bit, simplify thermal management, or enable higher density without proportional energy increases will increasingly command preference in procurement decisions.
At the same time, the need for grid modernization, with U.S. utility companies planning to invest 1.4 trillion USD over the next five years, highlights the infrastructural constraints that may shape where and how large-scale optical connectivity deployments can be sustained. Enterprises and cloud providers must factor these constraints into capacity planning, site selection, and the timing of interconnect upgrades. In parallel, regulatory frameworks, including U.S. export controls on advanced semiconductors and related items used in AI data centers, and the proliferation of data sovereignty mandates, add layers of complexity to cross-border supply chains and regional deployment strategies. Organizations that proactively map these constraints against their optical interconnect requirements will be better positioned to mitigate risk and maintain operational continuity.
Why the 2026 Outlook Demands a Forward-Looking Intelligence Framework
As the market advances toward the 2032 forecast horizon, the interplay of technology, cost, regulation, and demand will continue to evolve at a pace that challenges static planning assumptions. The projected expansion to nearly 47,939 million USD by 2032, supported by a 16.48 percent CAGR, signals that optical connectivity will remain a central enabler of data center growth, AI infrastructure scaling, and enterprise digital transformation. However, the distribution of that growth across regions, data rates, transmission distances, and protocols will not be uniform, and the competitive dynamics among suppliers will shift as new product generations, manufacturing investments, and regulatory developments take effect.
Organizations that treat optical module strategy as an afterthought risk facing escalating costs, performance limitations, and supply disruptions. Conversely, those that invest in rigorous market intelligence, align procurement roadmaps with technology trajectories, and incorporate energy, regulatory, and geographic factors into their decision frameworks will gain a measurable advantage in cost efficiency, deployment speed, and strategic flexibility.
Accessing the Full Strategic Picture
This overview provides a structured glimpse into the scope, methodology, and strategic relevance of the Worldwide Data Center Optical Module Market research. It highlights the macroeconomic arc of the market, the segmentation dimensions that matter most to decision-makers, the competitive players shaping the landscape, and the broader ecosystem forces that will influence deployment economics and supply chain resilience. Yet the full value of the study lies in its detailed segmentation data, granular regional and application insights, and comprehensive supplier analysis, which together enable precise scenario planning, benchmarking, and investment prioritization.
For executives, procurement leaders, and investors seeking to secure a decisive advantage in the AI and data center infrastructure race, the complete report offers the depth and specificity required to move from broad awareness to actionable strategy. We invite you to access the full Worldwide Data Center Optical Module Market study to obtain the comprehensive intelligence, detailed data tables, and strategic recommendations that will inform your 2026 decisions and long-term planning through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Data Center Optical Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com