

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Micro Perforated Sleeves Market to Reach $777.74M by 2032, 5.85% CAGR

Strategic Intelligence for a Breathing Market: Inside the Worldwide Micro Perforated Sleeves Industry (2026-2032)
The global packaging landscape is undergoing a quiet but decisive transformation. As retailers, brand owners, and regulators converge on a single mandate—extend shelf life, reduce food loss, and comply with tightening sustainability frameworks—the demand for controlled-breathability formats has moved from niche experimentation to mainstream procurement. Micro perforated sleeves sit precisely at this intersection. They are no longer just a technical accessory for fresh produce; they are becoming a strategic enabler of supply-chain efficiency, consumer experience, and regulatory resilience.
PW Consulting's latest research, Worldwide Micro Perforated Sleeves Market, was built to help executives navigate this inflection point with precision rather than speculation. Spanning historical analysis from 2020 through the base year of 2025 and extending forecast visibility to 2032, the study translates macro momentum into operational intelligence. Below is a strategic preview of what the report delivers, why it matters for 2026 decision-making, and how leadership teams can convert its findings into competitive advantage.
Why Micro Perforated Sleeves Matter Now
The category's growth is not accidental. It is the product of three reinforcing forces: material science maturation, retail sustainability mandates, and the economics of spoilage reduction. Micro perforation—achieved through hot-needle punching, laser cauterization, or precision die configurations—creates uniform micro-holes that regulate gas exchange without compromising structural integrity or brand presentation. For fresh fruits and vegetables, bakery and confectionery, and floriculture, this means extended freshness windows, fewer rejected units, and a packaging format that can align with recyclable mono-material streams.
The industry context is equally telling. Major retailers across Europe and North America are integrating breathable micro-perforated films into their fresh produce and bakery assortments to cut plastic waste and food loss under internal sustainability mandates. Simultaneously, regulatory architectures such as the EU's Packaging and Packaging Waste Regulation (PPWR) and Extended Producer Responsibility (EPR) schemes are increasing financial accountability for packaging waste. These frameworks do not merely penalize; they incentivize formats that reduce spoilage and support recyclability. In this environment, micro perforated sleeves transition from a cost line to a compliance and margin lever.
Yet the operational reality is nuanced. Raw material volatility remains a persistent variable. For example, BOPP film pricing in the United States reached levels around 2,216 USD/MT in December 2025, with a Q1 2026 outlook trending toward 2,312 USD/MT amid shifting regional supply dynamics. In parallel, polypropylene pricing in key Asian markets climbed to approximately 8,797 CNY/T as of late April 2026, reflecting ongoing feedstock-driven fluctuations across polyolefin-based packaging films. These movements matter because the category is predominantly manufactured from BOPP, CPP, LDPE, LLDPE, HDPE, and other polyolefin films. Decision-makers cannot treat material pricing as a back-office concern; it is a front-line strategic input that shapes sourcing contracts, product mix, and regional deployment.
Market Trajectory: Reading the Signal Behind the Numbers
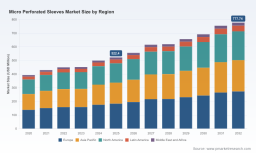
The market's trajectory from 2020 to 2032 tells a story of recovery, acceleration, and maturation. Revenue expanded from 393.2 million USD in 2020 to 429.51 million USD in 2021, then to 449.55 million USD in 2022 as supply chains stabilized and breathability-driven applications gained traction. The base year of 2025 registers 522.4 million USD, reflecting a market that has absorbed post-pandemic normalization and is now advancing on the strength of application adoption and regulatory tailwinds. The forecast arc continues upward, reaching 555.78 million USD in 2026 and progressing to 615.54 million USD in 2027, with growth continuing through 2032 at 777.74 million USD.
This path is not linear, and that is precisely why executive attention is required. The compound annual growth rate of 5.85 percent across the 2026-2032 forecast window signals steady, structurally supported expansion rather than cyclical overheat. For strategists, this implies a market where disciplined capacity planning, material procurement, and application-specific positioning will separate outperformers from laggards. The report's value lies in decoding where that growth concentrates, which applications are pulling demand, and how regional dynamics shape go-to-market timing.
Importantly, the study deliberately avoids flattening the category into a single narrative. Growth is uneven across film types, end-use segments, and geographies, and each variation carries distinct commercial implications. BOPP film and CPP film continue to anchor large shares of the material mix, while PE film and emerging bio-plastics represent differentiated opportunities tied to recyclability goals and regional supply conditions. On the application side, fresh fruits and vegetables command the largest demand pull, bakery and confectionery follows as a high-visibility growth lane, and floriculture maintains a specialized but resilient position. Regional distribution reflects a mature and diversified footprint, with Europe, Asia Pacific, and North America each presenting distinct procurement rhythms, regulatory pressures, and retail adoption curves, while Latin America and the Middle East and Africa offer earlier-stage but strategically relevant expansion pathways.
Rather than offering static percentage grids, the report maps these segments into decision-ready frameworks: where volume is shifting, which material applications are becoming more cost-sensitive, and how regional retail behavior is reshaping demand timing. This is the difference between knowing that growth exists and knowing where to place capital, sales focus, and R&D effort.
What the Research Actually Delivers
A market report earns its place on the executive dashboard only if it converts data into action. The Worldwide Micro Perforated Sleeves Market study is structured to do exactly that. It is not a high-level brochure; it is an operational intelligence asset designed for sourcing leaders, packaging developers, commercial heads, and corporate strategists.
The report's core analytical components include:
Perforating Gun Market
- A full historical and forecast revenue model spanning 2020-2032, with base-year anchoring at 2025 and a 2026-2032 forecast horizon, allowing teams to benchmark internal performance against category trajectories and test scenario assumptions.
- Material-type analysis that evaluates BOPP film, CPP film, PE film, and other bio-plastics in terms of demand behavior, cost exposure, and suitability for breathability-controlled applications, giving procurement and product development teams a structured basis for mix decisions.
- Application-level insight covering fresh fruits and vegetables, bakery and confectionery, floriculture, and other applications, with attention to how breathability requirements, retail handling, and shelf-life targets shape volume patterns and specification preferences.
- Regional dissection across Europe, Asia Pacific, North America, Latin America, and the Middle East and Africa, focused on market maturity, retail adoption signals, and regulatory influence rather than simplistic share rankings.
- Competitive landscape mapping supported by concentration metrics, including a CR3 of 18.4 percent and CR5 of 28.5 percent, which signals a moderately fragmented environment where specialist capability and custom solutioning can compete effectively against broader-scale players.
- An industry context module that integrates raw-material pricing dynamics, regulatory developments, and retailer adoption behavior into the market narrative, ensuring that strategy is grounded in operational reality rather than headline figures alone.
Each section is built to answer practical questions: Which specifications are gaining retailer acceptance? Where do material price swings most affect margin? How should a supplier sequence regional entry or capacity expansion? How do sustainability mandates change the relative attractiveness of mono-material PE stretch sleeves versus conventional multi-layer formats? The study provides the scaffolding to answer these questions with evidence rather than intuition.
Competitive Landscape: Capability Over Scale
The competitive environment in micro perforated sleeves is defined less by brute scale than by technical differentiation and application specialization. The report profiles a set of companies whose strategies illustrate the range of viable positions in this market.
A-ROO Company, headquartered in Strongsville, Ohio, specializes in custom micro-perforated bags, sleeves, and rolls, with particular depth in conical shapes for horticultural, produce, herb, candy, and snack food markets. Its emphasis on custom perforation levels and made-to-order availability reflects a service-oriented model that caters to brands seeking format precision rather than off-the-shelf uniformity.
Golden Eagle Extrusions, Inc. operates from the United States with a broader flexible packaging orientation, offering hot-needle micro-perforation for breathability control across food, beverage, and industrial applications. Its expertise in coextruded films, lamination, and custom perforated films positions it as a solutions integrator for customers who need breathability embedded within more complex film structures.
Law Packaging, based in Vietnam, manufactures micro perforated flower sleeves and vegetable sleeves from high-quality BOPP and CPP film, with customizable sizes and a clear focus on fresh produce and floral packaging. Its breathability-driven product set illustrates how regional manufacturing can serve global supply chains with cost-competitive, application-tuned offerings.
LasX Industries brings laser-enabled micro-perforation to the flexible packaging space, delivering uniform cauterized holes for freshness control and perforations tailored to shrink-sleeve applications. The laser pathway matters because it can support consistency, gentler material handling, and specification precision that hot-needle or mechanical methods may approach differently.
Repacorp produces tamper-evident perforated shrink sleeves with options for vertical, horizontal, and T-perfs, available in rolls or sheeted formats for automatic or hand application. This portfolio highlights a dual identity for the category: breathability is not the only value driver; tamper evidence, handling efficiency, and format flexibility also shape buyer decisions.
Worldwide Micro Perforated Sleeves Market
C-P Flexible Packaging supplies recyclable mono-material PE stretch sleeves that can incorporate perforations for tamper evidence or easy removal, directly supporting sustainable packaging initiatives. In a regulatory and retail environment that increasingly rewards recyclability, this mono-material orientation is strategically significant.
NanoGrafix Solutions, operating across the UK and Europe, specializes in custom printed shrink sleeves with micro perforations for easy tearing and removal, combining 360-degree branding with tamper protection. Its model underscores how micro perforation can be embedded within a broader brand-experience and packaging-engineering proposition.
Asteria Group, based in Europe, manufactures perforated shrink sleeves using heat-shrinkable plastic films designed to fit various shapes and sizes for innovative packaging solutions. Its focus on conformability and format versatility reflects the practical reality that sleeve performance is as much about geometry and fit as it is about perforation pattern.
Together, these profiles reveal a market where competitive advantage is built on specification control, material expertise, application knowledge, and the ability to align perforation design with brand, retail, and regulatory requirements. The report uses these company snapshots not as an exhaustive directory, but as a lens into the strategic archetypes that shape procurement decisions and market positioning.
Navigating the Forces That Will Shape 2026 and Beyond
For executives planning 2026 moves, the report emphasizes three interconnected dynamics that deserve active management rather than passive observation.
First, raw-material volatility is a structural feature, not a temporary nuisance. With BOPP, CPP, LDPE, LLDPE, HDPE, and other polyolefin films forming the backbone of micro perforated sleeve production, pricing movements ripple directly into cost structures and contract strategy. The study integrates pricing context—such as recent BOPP film price levels in the United States and polypropylene movements in key Asian markets—to help teams anticipate procurement timing, hedging considerations, and the relative attractiveness of alternate material paths where specifications allow.
Second, regulation is reshaping the value proposition. EU EPR schemes and the PPWR framework are increasing financial accountability for packaging waste, which in turn incentivizes formats that reduce food spoilage and support recyclability. For micro perforated sleeves, this is a double-edged opportunity: breathability can lower waste by extending freshness, while material choices can determine whether a sleeve aligns with recyclability expectations. The report maps these regulatory currents so that strategy accounts for compliance risk and compliance-enabled growth alike.
Third, retail adoption is accelerating the category's legitimacy. Major retailers in Europe and the US, including Tesco, Walmart, and Whole Foods, are adopting micro-perforated films for fresh produce and bakery to minimize plastic waste and food loss under sustainability mandates. This is not a peripheral trend; it is a demand signal that can redistribute volume toward specification standards, supplier qualification requirements, and application-specific performance thresholds. The study incorporates these retail initiatives to help suppliers and brand owners anticipate where acceptance criteria are tightening and where commercial opportunities are opening.
How to Use This Research for 2026 Decision-Making
The strategic value of the report lies in its ability to convert a complex, multi-driver market into a set of prioritized actions. For sourcing and procurement leaders, it offers a framework to evaluate material mix, regional pricing exposure, and specification trade-offs without overcommitting to a single film type or supplier archetype. For product and packaging development teams, it clarifies where breathability, tamper evidence, recyclability, and brand presentation intersect—and where they conflict. For commercial leaders, it identifies which applications and regions present the strongest near-term pull and which require longer investment horizons. For corporate strategists, it situates the category within the broader shift toward spoilage reduction, waste accountability, and sustainable packaging design.
The report is also designed to support scenario planning. Because growth is steady but not uniform, teams can use the historical and forecast architecture to test questions such as: How does a material price shock alter the attractiveness of PE-based mono-material sleeves versus BOPP-led formats? How does retail adoption in one region change supplier qualification timing in another? How does regulatory pressure shift the commercial calculus for fresh produce versus bakery applications? By embedding these questions in evidence-based structure, the study helps leaders move from reactive adjustments to proactive positioning.
Conclusion: From Market Signal to Strategic Move
The worldwide micro perforated sleeves market is not simply expanding; it is re-scoping its role within a broader packaging ecosystem that rewards breathability, waste reduction, and regulatory alignment. Revenue growth from 393.2 million USD in 2020 to a forecast of 777.74 million USD by 2032, supported by a 5.85 percent CAGR across 2026-2032, indicates a category with durable momentum. But durability is not the same as ease. Material volatility, regional divergence, application-specific performance needs, and a moderately fragmented competitive field all demand disciplined analysis.
PW Consulting's Worldwide Micro Perforated Sleeves Market report is built to meet that demand. It combines historical grounding, forecast visibility, segmentation insight, competitive benchmarking, and industry-context integration into a single decision-support resource. For organizations preparing 2026 strategies—whether in sourcing, product development, commercial expansion, or sustainability-led packaging transformation—the study offers the depth required to act with confidence.
The full report provides the detailed segmentation, regional breakdowns, application dynamics, and competitive intelligence necessary to convert these strategic signals into executable plans. For teams that need more than macro direction—teams that need specification-level clarity, regional timing insight, and company-level positioning context—the complete research is the essential next step.
For detailed analysis of this topic, please visit the official page: Worldwide Micro Perforated Sleeves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com