

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aircraft Pressurisation Systems Market to Hit $12,977.42M by 2032 at 6.32% CAGR

Decoding the Sky: Strategic Imperatives in the Global Aircraft Pressurisation Systems Market (2026–2032)
As commercial aviation enters a new phase of fleet renewal, fleet expansion, and architectural transformation, the humble yet critical aircraft pressurisation system has moved from a purely engineering concern to a strategic boardroom topic. In an industry where reliability, weight, fuel burn, and cabin environment quality directly shape profitability and passenger retention, mastering the dynamics of cabin pressure control is no longer optional. The Worldwide Aircraft Pressurisation Systems Market research published by PW Consulting provides decision-makers with a structured, data-rich view of how this subsystem is evolving, who is shaping its trajectory, and where the most consequential value creation opportunities will emerge through 2032.
This insight is designed as a strategic companion to that report. It distills the macro trajectory, competitive architecture, and operational themes that matter most for 2026 planning cycles—without giving away the granular segmentation that makes the full study a practical tool for sourcing, programme management, and investment prioritisation.
Why Pressurisation Systems Now Matter More Than Ever
Pressurisation is not simply a comfort feature; it is a regulatory and operational backbone that governs how high an aircraft can fly, how efficiently it breathes, and how safely it manages decompression events. As airframe manufacturers pursue aerodynamic efficiency at higher cruise altitudes, as airlines seek smoother fuel economics, and as defence and business aviation operators push platform envelopes, the pressurisation chain—outflow valves, cabin pressure controllers, safety and bulkhead valves, sensors, and actuators—must deliver more performance with less weight, less maintenance, and greater integration with flight management logic.
The global market for aircraft pressurisation systems has been expanding steadily on the back of rising air traffic, fleet modernisation, and tighter safety expectations. After a market size of roughly USD 6.1 billion in 2020, the sector climbed through the pandemic recovery years and reached approximately USD 8.45 billion in 2025. The forward arc continues to steepen: the base year is 2025 and the forecast runs from 2026 through 2032, with a compound annual growth rate of approximately 6.32%. By the end of the forecast horizon, revenue scale is projected to approach nearly USD 13.0 billion. These are not just growth figures for prognostication; they frame budgeting, capacity planning, and supplier negotiations for the next seven years of airframe programmes, retrofit campaigns, and fleet sustainment.
What makes this trajectory strategically interesting is not the headline alone. It is the way growth is skewed by product architecture, fleet composition, and regulatory pressure—and exactly where those skews occur is the intelligence that programme managers, procurement teams, and investment committees need before locking in multi-year commitments.
Market Size, Growth Trajectory, and What It Means for 2026 Decisions
The most useful way to read the market roadmap is as a sequence of decision triggers rather than a flat line.
-
Recovery-to-expansion inflection: The step from 2024 to 2025 reflects the deepening impact of production ramp-ups and the return of wider utilisation patterns across passenger and cargo platforms. For 2026 planning, this means demand visibility is improving, but timing discipline still matters—especially where programmes nest pressurisation hardware into new delivery slots.
-
Forecast momentum: The projected expansion from about USD 9.15 billion in 2026 to nearly USD 12.98 billion by 2032 signals a durable, above-trend environment for pressurisation content. Organisations that treat this as a stable tailwind can better align engineering roadmaps, spare parts inventories, and MRO partnerships.
-
Risk windows: Growth concentrated in the outer years also means that early movers in technology adoption, certification support, and retrofit readiness can secure stronger positioning before the market becomes crowded. Conversely, late adopters face more competition for slots in key platforms and more pressure on margins.
Because pressurisation systems sit at the intersection of safety regulation, environmental control, and power architecture, the “how” of growth will matter as much as the “how much.” That is precisely why the report crosses functional boundaries, linking market sizing to component logic, aircraft type economics, geographic concentration, and the competitive moves that define who wins content shares.
Segment Architecture: Where Value Is Being Created
The market breaks down across three analytical dimensions that shape procurement strategy and product roadmaps: parts of the world, aircraft types, and system components. The report treats each dimension as a lens for understanding where content intensity is rising, where consolidation is strongest, and where the next wave of specification decisions is likely to occur.
Regional Concentration and Demand Drivers
Demand is spread across multiple geographies, but it is far from uniform. North America remains a central hub of content demand, reflecting both domestic airframe activity and the export footprint of aircraft programmes, defence platforms, and business aviation. Europe follows as a structurally important region, anchored by OEM ecosystems and a dense network of retrofit and support operations. Asia Pacific stands out for its growth potential, propelled by rising air traffic, expanding fleet modernisation, and the localisation of supply chains around key airframe and engine programmes. The Middle East and Africa and Latin America together add additional layers of demand, often tied to specific fleet renewal cycles and niche platform requirements.
Rather than treating geography as a static backdrop, the analysis shows how regional demand patterns influence supplier positioning, after-sales service strategies, and the timing of content wins. The full report unpacks these dynamics with segmentation detail that procurement and business development teams can use to calibrate regional go-to-market plans.
Aircraft Type Economics and Programme Strategy
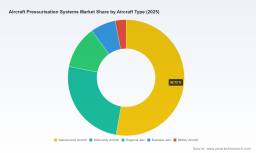
Pressurisation content does not scale linearly with aircraft size or mission type. Narrow-body aircraft command the largest share of market content, consistent with their volume role in global airline operations and the breadth of pressurisation hardware required across high-cycle fleets. Wide-body aircraft carry a differentiated content profile, where system complexity, stages, and integration constraints elevate the importance of reliability and serviceability. Regional jets, business jets, and military aircraft each bring specialised requirements—shorter field performance, reduced maintenance footprints, mission-specific pressure management, and platform-specific certification logic—that translate into distinct margins, content densities, and supplier selection criteria.
The strategic takeaway is that aircraft type is not just a classification; it is a demand filter that determines which components, which suppliers, and which technology paths matter most. Programme teams evaluating pressurisation content for a new platform or a retrofit campaign must look beyond overall market growth and examine how the mix of aircraft types is shifting under them.
Component-Level Logic: The Real Battleground
At the most actionable level, pressurisation value is split across key components and subsystems: outflow valves, cabin pressure controllers, safety and bulkhead valves, and sensors and actuators. Each of these categories carries different technical risk, different upgrade cycles, and different competitive dynamics.
-
Outflow valves remain central to pressure management, and they are a natural focal point for weight reduction, reliability improvement, and control integration.
-
Cabin pressure controllers increasingly function as the logic layer of the system, where algorithmic performance, health monitoring, and interface with flight management systems shape pilot workload and operational robustness.
-
Safety and bulkhead valves are fundamental to compliance and failure management, making them a steady but technically demanding content area.
-
Sensors and actuators represent the connective tissue between control logic and physical actuation, with growing relevance as architectures move toward electric and more-electric solutions.
Understanding the relative content weight of these categories is essential for sourcing strategy. It helps planners infer where substitution risk is highest, where integration value is greatest, and where suppliers can differentiate through digital features rather than mechanical performance alone. The complete report details the component-level splits that underpin these conclusions.
Regulation, Technology, and the Reshaping of Demand
No pressurisation strategy is complete without regulatory and architectural context. Safety requirements establish the floor, while technology trends define the ceiling for performance and cost.
Regulatory Dynamics as Market Forces
Pressurisation systems operate under a strict overlay of certification and operational requirements. Cabin pressure management must maintain protected conditions under normal operations and limit occupant exposure in the event of failure. For large aeroplanes, the design basis requires that the pressurisation system minimise the time occupants are exposed to cabin altitudes above 8,000 feet, while also addressing decompression scenarios. Redundancy is built into the logic through requirements for pressure relief arrangements, ensuring that positive pressure differentials are automatically limited and that safety is preserved even if one valve becomes unavailable.
These rules are not static background; they influence design choices, qualification effort, and the cost of programme entry. As regulatory expectations continue to evolve around cabin environment quality and contamination risk, suppliers and operators alike must anticipate not just current compliance but the direction of tightening scrutiny on air quality, fume event management, and contaminant monitoring. That forward-looking compliance posture is increasingly a competitive differentiator in sourcing decisions.
From Bleed Air to More-Electric Architectures
A defining technology shift is the movement toward more-electric aircraft architectures, where electric compressors and electrically driven pressurisation subsystems can replace or supplement traditional bleed air arrangements. This transition is being pursued for several reasons: fuel efficiency, system simplification, reduced dependence on engine architecture, and lowered potential for contamination pathways associated with bleed air. At the same time, it introduces new engineering requirements around electrical power management, thermal integration, and health monitoring.
For pressurisation suppliers, this evolution is both an opportunity and a test. Companies that can offer electric cabin pressure control subsystems with integrated health monitoring, reduced maintenance burden, and lower installation complexity are well positioned for next-generation platforms and retrofit campaigns. The report evaluates how far this transition has progressed and where the balance between pneumatic and electric solutions is likely to sit across different aircraft categories.
Competitive Landscape: Who Sets the Pace
The pressurisation market is characterised by a small group of large, well-established players, with meaningful concentration among the top firms. This concentration matters because it shapes pricing power, technology leadership, certification readiness, and the ability to support global fleets at scale. The report quantifies this concentration and then drills into the companies that define it.
Several global suppliers sit at the centre of this ecosystem.
-
Honeywell Aerospace provides cabin pressure control systems including its fourth-generation digital cabin pressure control system, which is built around brushless DC technology, meaningful weight reduction, and enhanced reliability. The breadth of its application coverage—from large air transport to regional, business, military, and general aviation platforms—makes it a reference point for digital pressurisation control. A product brochure released in early 2025 underlined weight reduction and reliability as core differentiators, reinforcing a narrative that has clear resonance in both new aircraft and retrofit discussions.
-
Collins Aerospace, part of RTX offers integrated air management solutions that include cabin pressurisation and control, with outflow valves, cabin pressure controllers, and safety valves available in both electric and pneumatic configurations. Its coverage across commercial, military, fixed-wing, and helicopter platforms makes it a broad-spectrum contender in the pressurisation value chain. A next-generation cabin pressure control system introduced in 2024 emphasised enhanced health monitoring and longer service intervals, pointing toward the serviceability and uptime arguments that increasingly influence airline purchasing criteria.
-
Safran Group supplies cabin pressure control systems focused on accurate, automatic pressurisation with fully automatic operation designed to reduce pilot workload. Its emphasis on proprietary controller algorithms and internal test labs for performance verification and certification highlights the role of software-defined control and in-house qualification capability in maintaining competitive differentiation.
-
Liebherr-Aerospace delivers integrated air management systems that incorporate cabin pressure control as part of broader bleed air, air conditioning, and environmental control solutions for commercial and business aircraft programmes. Its strength lies in the integration perspective—positioning pressurisation not as an isolated component but as part of a complete environmental architecture.
The competitive field also includes several strategic specialists and component-focused firms.
-
ACE Thermal Systems, under Signia Aerospace , specialises in automated cabin pressurisation systems with an auto-schedule controller that integrates with flight management systems, reducing pilot input and trimming weight and installation costs for advanced aircraft performance requirements. This positions the company at the interface of automation and programme cost-efficiency.
-
Aeronamic develops electric cabin pressurisation systems and high-speed electric compressors with oil-less air-foil bearings, aligned with more-electric and electric aircraft concepts. Its inclusion of smoke evacuation and health monitoring illustrates how pressurisation subsystems are being reimagined as multi-function, safety-integrated solutions.
-
Moog Inc. provides components and valves for environmental control and life support systems that support cabin pressurisation, including high-pressure oxygen isolation valves and low-pressure cabin atmosphere control valves. Its role underscores how component-level precision and fluid/gas management expertise remain vital to the overall system.
-
Parker Aerospace, part of Parker Hannifin , supplies bleed air control systems and components supporting cabin pressurisation, with valves and electronic controllers for flow and temperature management in turboprop and other aircraft. This reflects the continued relevance of bleed air management even as electric architectures expand.
The competitive story is not only about who has the largest share; it is about who is advancing the right combination of weight reduction, automation, health monitoring, electric integration, and certification depth at the right moment in the aircraft cycle. The report maps these capabilities against the market structure so that readers can see where each competitor is strongest and where headroom remains.
What the Report Delivers for Operational Decision-Making
This market research is built to support real operating decisions, not just strategic narrative. It is structured to be usable across several planning horizons and functional teams.
-
Sizing and forecasting: The report provides market size and forecast data across the relevant timeline, enabling demand planning for content, components, and aftermarket support. Because pressurisation is tied to fleet mix and programme timing, the forecast logic is presented so that users can test assumptions about new aircraft deliveries, retrofits, and replacement cycles.
-
Segmentation clarity: Regional, aircraft-type, and component-level segmentation is provided to help readers identify where content growth is concentrated and where the economics differ most. The intention is to support sourcing decisions, pricing strategy, and business development targeting with a clear map of the opportunity landscape.
-
Competitive profiling: Detailed company profiles and recent developments give readers a practical view of supplier positioning, product evolution, and move timing. Rather than treating competitors as static names, the analysis connects product releases and technology claims to the broader market direction.
-
Regulatory and technology integration: The report folds in the regulatory and architectural context so that compliance and technology trends are evaluated as part of the market dynamic, not as separate commentary. This makes it easier to judge how technology shifts such as electric pressurisation and cabin environment quality concerns will alter content demand over time.
-
Strategic synthesis: Above all, the report translates market data into decision frameworks—where to invest in capability, where to watch substitution risk, where to align aftermarket planning, and where to position for programme wins in an increasingly concentrated market.
These elements are designed to work together. A procurement lead can use the segmentation detail to refine vendor shortlists; a business development team can use the competitive profiles to identify white space and timing; an engineering manager can use the technology and regulatory context to anticipate qualification effort and architecture trade-offs; and an investor or strategist can use the forecast arc to understand where value creation is likely to concentrate.
Reading the Signals for 2026 and Beyond
Several strategic signals stand out when the market is read as a whole.
First, pressurisation content demand is on a durable growth path, but the shape of that growth is uneven across platforms and regions. This means the highest-value moves will come from understanding the mix, not just the total. Organisations that map their own pipeline to the underlying aircraft-type and regional patterns will be better placed to anticipate content timing and avoid over-committing to segments with thinner economics.
Second, technology differentiation is increasingly tied to digital and electric capabilities. Weight reduction, brushless and electric actuation, automated control logic, health monitoring, and integration with flight management systems are all coming into sharper focus as platforms pursue more-electric architectures and operators push for lower maintenance burden. Suppliers and platform teams alike need to decide how aggressively to invest in these directions, because the transition is not uniform across the fleet.
Third, regulation remains a powerful driver of design discipline and long-term demand. Cabin altitude protection, pressure relief redundancy, and ongoing attention to air quality and contamination risk create both a compliance floor and a pressure to improve. As expectations around cabin environment quality evolve, pressurisation and environmental control become even more central to platform value propositions.
Fourth, market concentration means competitive positioning matters. With a meaningful share held by a small group of large players, access to content, certification support, and aftermarket presence is not equally distributed. This does not make the market inaccessible to smaller or specialist firms, but it does raise the importance of clear differentiation—whether through electric compression technology, automation, integration breadth, or targeted niche platforms.
Aviation Oxygen Systems Market
Conclusion: From Market Intelligence to Boardroom Action
The Worldwide Aircraft Pressurisation Systems Market research is built for the moment when strategic questions outpace general industry commentary. It takes a market that is often discussed in parts—components, platforms, regions, regulations—and turns it into a single, decision-ready view of where demand is going, who is shaping it, and what that means for 2026 planning.
The headline figures tell a compelling story: a market that has grown from around USD 6.1 billion in 2020 to about USD 8.45 billion in 2025, with a forecast rise to roughly USD 9.15 billion in 2026 and continued expansion toward nearly USD 13.0 billion by 2032 at a CAGR of approximately 6.32%. But the strategic value lies beneath the totals—in the component logic, aircraft-type economics, regional concentration, regulatory drivers, and competitive moves that determine which organisations capture value and which merely observe it.
For executives, procurement teams, programme managers, and investors who need a sharper lens on this subsystem, the full report provides the segmentation detail, company-level intelligence, and forecast reasoning required to move from observation to action. The market is expanding, the technology is evolving, and the competitive field is consolidating around integrated, digital, and increasingly electric solutions. The organisations that decode these patterns early will be the ones best positioned to win content, manage risk, and shape their pressurisation strategy for the decade ahead.
Worldwide Aircraft Pressurisation Systems Market
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Pressurisation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com