

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Global Titanium Chloride Market to Hit $21.5B by 2032, Growing at 4.8% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Titanium Chloride Market: Navigating Growth, Volatility, and Competitive Shifts Through 2032
Executive Overview
The global titanium chloride market stands at a critical inflection point. As the foundational intermediate for titanium sponge production, chloride-process titanium dioxide, and advanced Ziegler-Natta catalysts, titanium tetrachloride (TiCl4) demand is tightly coupled to downstream materials cycles, regulatory evolution, and regional capacity restructuring. Our latest Worldwide Titanium Chloride Market research report delivers a comprehensive, data-grounded assessment designed specifically for executive decision-makers navigating the 2026–2032 horizon.
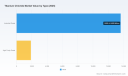
Between 2020 and 2025, the market expanded from approximately 12,150 million USD to 15,510 million USD, reflecting sustained industrial demand and incremental capacity additions across key producing regions. The trajectory is projected to continue through the forecast window, with the market expected to reach roughly 21,534 million USD by 2032 at a compound annual growth rate of 4.8 percent. These macro indicators are more than backward-looking statistics; they form the analytical backbone of a deeper investigation into supply chain resilience, pricing dynamics, competitive positioning, and regional risk exposure. This article outlines the strategic architecture of the research and explains why it should serve as a core input for capital allocation, procurement planning, and competitive strategy in 2026.
Worldwide Titanium Chloride Market
Zirconium Oxychloride Market
Why This Research Matters for 2026 Decision-Making
Market intelligence loses value when it remains abstract. The strategic function of this report is to translate market-scale trends into operational foresight. Several structural forces are actively reshaping how titanium chloride is produced, priced, and distributed, and each carries direct implications for procurement leaders, plant planners, and corporate development teams.
- Capacity additions in Asia have altered the regional supply baseline, while environmental enforcement and feedstock volatility continue to influence marginal production economics.
- Downstream titanium dioxide manufacturers are adjusting procurement strategies in response to chloride-process technology investments, export trade measures, and shifting feedstock contracts.
- Titanium sponge producers face a high input intensity relationship with TiCl4, meaning small changes in intermediate availability or pricing can cascade into broader cost structures.
- Maintenance cycles, logistics constraints, and energy costs are increasingly interacting to create short-term supply tightening, particularly in higher-cost operating environments.
The 2026 edition of this report is structured to help organizations separate signal from noise. Rather than presenting a static snapshot, the analysis integrates historical trajectory, forward projections, and company-level activity to support scenario planning. Executives evaluating new production investments, long-term offtake agreements, or market entry strategies can use the research to benchmark margin exposure, assess competitive moats, and identify where operational flexibility will matter most.
Market Trajectory and Structural Dynamics
The headline growth figures frame an industry that is expanding, but not uniformly. Over the historical period, revenue progression reflects both volume growth and shifting value capture across grades, end uses, and geographies. The forecast period through 2032 indicates continuing expansion, though the pace will be influenced by downstream demand elasticity, regulatory pressure on pollution-intensive processes, and the economics of chloride versus alternative production routes.
One of the most operationally relevant themes is the interaction between raw material costs and intermediate pricing. Titanium slag availability, chlorine gas pricing, and procurement patterns for ilmenite all feed directly into TiCl4 production economics. Recent market signals show firmer input procurement by titanium dioxide producers and price levels in certain regions reaching multi-year highs, underscoring the need for scenario-based procurement strategies rather than static budgeting. At the same time, the relationship between TiCl4 consumption and downstream output remains material: titanium sponge production in major manufacturing centers typically requires substantial TiCl4 input per ton of finished metal, which amplifies the strategic importance of intermediate supply security.
Trade policy and environmental regulation add another layer of complexity. Anti-dumping measures on certain titanium dioxide imports have ripple effects across the broader titanium chemicals value chain, altering demand patterns for intermediates and influencing where capacity is most competitive. In parallel, increasingly frequent environmental inspections targeting pollution reduction continue to affect production from titanium slag-based routes in key manufacturing regions. These constraints do not merely raise compliance costs; they influence which assets can flex output quickly, which operations face downtime risk, and how regional price dispersion evolves during periods of tight supply.
The report also examines market concentration and competitive structure. The industry is not fully fragmented; a meaningful share of value is captured by firms with integrated chloride-process operations, large pigment portfolios, or dedicated titanium metal capabilities. Understanding concentration dynamics helps buyers and investors evaluate bargaining power, substitution risk, and the likelihood of supply consolidation under stress conditions.
Competitive Landscape: Who Shapes the Market and How
Competitive advantage in titanium chloride increasingly derives from integration, technology access, and geographic positioning. The strongest players typically combine intermediate production with downstream titanium dioxide or titanium metal operations, allowing them to balance merchant sales with internal consumption and to manage feedstock flexibility more effectively. The report profiles the companies that are most actively shaping supply, technology, and regional capacity trends.
- Tronox Holdings plc operates as one of the largest global suppliers of titanium chemicals, including TiCl4 and derivatives, with production tied to both merchant sales and internal use in pigments and titanium sponge. Its footprint illustrates how integrated chloride chemistry supports broader titanium product portfolios.
- The Chemours Company is a major global producer of TiCl4 as a key intermediate in chloride-process titanium dioxide production, with large-scale facilities that leverage proprietary chloride technology and broad feedstock flexibility. Operational continuity at such sites can significantly affect regional supply conditions.
- Toho Titanium Co., Ltd. produces and sells titanium tetrachloride as part of its chemicals business, supporting titanium sponge production via the Kroll process and other titanium metal products. Its role highlights the linkage between intermediate supply and advanced metal manufacturing.
- OSAKA Titanium Technologies Co., Ltd. manufactures titanium tetrachloride under strict quality control for titanium sponge and other high-purity applications, with distribution adjusted to different transport requirements. This orientation emphasizes quality and application specificity in a market where grade differentiation matters.
- Ishihara Sangyo Kaisha, Ltd. (ISK) produces titanium tetrachloride as a main raw material for chloride-process titanium dioxide manufacturing, reinforcing the strategic importance of upstream intermediates in pigment supply chains.
- LB Group (Lomon Billions) operates significant chloride-process TiO2 capacity supported by dedicated titanium tetrachloride production, including a substantial capacity addition that reflects ongoing investment in chloride-based value chains.
- Kronos Worldwide, Inc. is a leading producer of TiO2 via chloride process requiring substantial TiCl4 volumes as an intermediate, positioning the company deeply within the global titanium chemicals value chain.
- Venator Materials PLC produces titanium tetrachloride for pigments and other applications as part of its titanium dioxide operations, linking intermediate chemistry directly to pigment market strategy.
- American Elements manufactures and distributes titanium tetrachloride for bulk industrial and research use, with production supporting advanced materials applications. Its presence broadens the market beyond mainstream pigment and sponge routes.
- CITIC Titanium Industry Co., Ltd. is a Chinese producer involved in titanium tetrachloride for chloride-process TiO2, with ongoing capacity expansions in high-purity grades, illustrating continued investment in differentiated product segments.
Recent company-level and market-level developments reinforce why competitive monitoring must be continuous rather than periodic. In mid-2025, several producers faced tightening supply conditions across North America and Europe during the third quarter, driven by scheduled maintenance, elevated energy costs, and logistics disruptions. The resulting price pressure was especially pronounced in Europe, where feedstock costs and export demand compounded the impact. Those episodes demonstrate how quickly regional availability can shift even in a structurally growing market.
Operational diplomacy can be just as important as capacity. In mid-2025, regulatory developments in Mexico allowed the resumption of normal operations at a major titanium dioxide facility dependent on TiCl4 production, showing how environmental and utility constraints can temporarily reshape regional supply expectations. Meanwhile, capacity expansion announcements in China have highlighted the continued push to support chloride-process titanium dioxide demand with dedicated intermediate production. Each event alters short-term availability and influences long-term competitive positioning.
Inside the Report: What Decision-Makers Will Find
This research is designed as a decision toolkit rather than a descriptive summary. It combines quantitative market modeling with qualitative analysis of competitive behavior, regulatory exposure, and downstream demand linkages. The objective is to provide a usable framework for pricing strategy, capacity planning, supplier evaluation, and investment prioritization.
The report includes detailed historical reconstruction and forward projection, enabling readers to trace how the market evolved from 2020 through the base year and how growth is expected to unfold across the forecast window. It analyzes segmentation by region, type, and application to clarify where value is concentrated and how demand drivers differ across end markets. Rather than reducing the industry to a single average, the segmentation analysis helps identify which segments are most exposed to feedstock volatility, which rely on high-purity specifications, and which are shaped by cyclical pigment or catalyst demand.
Competitive profiling is integrated with recent developments to show not only who the major participants are, but how their recent actions affect supply conditions. The report examines operational resumption events, capacity additions, and market-wide supply tightening to help readers interpret near-term risk. It also contextualizes raw material procurement trends and regulatory actions that influence production economics, making it easier to connect external disruptions with internal planning assumptions.
A central strength of the study is its emphasis on actionable interpretation. The analysis supports questions such as:
- Where are supply constraints most likely to emerge during maintenance-heavy periods or energy-cost spikes?
- Which downstream applications create the most stable demand anchors for titanium chloride?
- How do regional trade measures alter procurement geography and supplier qualification strategies?
- What does market concentration imply for negotiation leverage, substitution options, and long-term contracting?
How to Use This Intelligence Strategically
For procurement and supply chain leaders, the report provides a basis for building more resilient TiCl4 sourcing strategies. By understanding where capacity is expanding, where environmental and energy pressures are intensifying, and how regional tightening events have unfolded, teams can structure contracts, inventory buffers, and supplier diversification plans with greater confidence. For pricing and commercial teams, the analysis helps frame negotiation positions around feedstock sensitivity, grade differentiation, and regional availability dispersion.
For strategy and corporate development teams, the research supports evaluation of market entry, partnership, and capacity investment options. Because titanium chloride sits between raw material processing and high-value downstream products, the economics of any expansion or acquisition depend heavily on integration benefits, technology access, and exposure to regulatory or trade shocks. The report’s competitive and segmentation structure helps decision-makers test whether a proposed move aligns with structural demand or merely chases cyclical pricing.
For investors and advisors, the report offers a disciplined way to assess which participants are most likely to benefit from continued chloride-process adoption, which operations face greater disruption risk, and how market concentration may shape future margin distributions. The inclusion of recent operational and market events ensures that analysis is anchored in current conditions rather than outdated assumptions.
Conclusion: Turning Market Scale into Strategic Advantage
The worldwide titanium chloride market is expanding, but growth alone does not guarantee commercial advantage. Success in 2026 and beyond will depend on how well organizations interpret the interaction of capacity dynamics, feedstock costs, regulatory pressure, trade policy, and competitive behavior. Our Worldwide Titanium Chloride Market report is built to support that interpretation with structured data, company-level intelligence, and forward-looking analysis through 2032.
This article has provided a high-level view of the strategic logic behind the research and the market forces it examines. The full study goes further, offering detailed market sizing, segmentation mechanics, competitive profiling, recent development tracking, and scenario-ready insights that cannot be fully captured in a short briefing. For teams that need to move from general awareness to specific planning parameters, the complete report is the necessary next step.
For detailed analysis of this topic, please visit the official page: Worldwide Titanium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Veterinary API Market Hits $7.2B in 2025, Forecast 7.15% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Global Veterinary API Manufacturing Landscape: Strategic Imperatives for 2026 and Beyond
The global animal health industry is entering a critical inflection point. As veterinary care standards rise across both companion and livestock sectors, the demand for high-quality Active Pharmaceutical Ingredients has become a cornerstone of therapeutic innovation and supply chain resilience. For executives, investors, and supply chain strategists, understanding the trajectory of the veterinary API manufacturing market is no longer optional—it is a strategic necessity. Our newly released Worldwide Veterinary API Manufacturing Market study provides the comprehensive intelligence required to navigate this evolving terrain, with a particular focus on how macroeconomic tailwinds, regulatory shifts, and competitive realignments will shape enterprise decision-making throughout the 2026–2032 forecast horizon.
Market Trajectory and the 2026 Decision Window
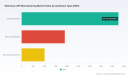
The veterinary API manufacturing sector has demonstrated consistent structural growth over the past half-decade, expanding from a baseline of approximately USD 5,100 million in 2020 to an estimated USD 7,200 million in 2025. This trajectory reflects more than incremental expansion; it signals a maturing ecosystem where pharmaceutical-grade precision, regulatory compliance, and scalable production capacity are increasingly intertwined. Looking ahead, the market is projected to reach a range exceeding USD 11,600 million by the close of 2032, underpinned by a compound annual growth rate of 7.15 percent. These figures frame the 2026 decision window as a pivotal moment for capital allocation, manufacturing footprint optimization, and partnership strategy.
For corporate planners, the near-term forecast carries distinct operational implications. The 2026–2028 period is expected to sustain steady revenue progression, driven by sustained demand for anti-infective therapies, parasiticides, and biological formulations across multiple animal species. However, growth alone does not dictate strategy. The real value of forward-looking intelligence lies in identifying where capacity constraints, regulatory bottlenecks, and geographic supply dependencies will intersect with corporate objectives. Companies that align their 2026 investment pipelines with validated demand signals and supply chain risk assessments will be better positioned to capture margin resilience and market share as the cycle advances toward the end of the decade.
Veterinary Drug Market
Our analysis situates these macro trends within a broader operational context, examining how shifting procurement patterns, evolving quality standards, and geopolitical trade dynamics are altering the cost structures and lead times that define modern veterinary API procurement. The study is designed to equip decision-makers with the analytical frameworks needed to evaluate sourcing strategies, assess manufacturing partnerships, and forecast capacity requirements before market conditions tighten.
Structural Drivers Shaping the Forecast Period
Several interconnected forces are accelerating the transition from routine production to strategically calibrated manufacturing. First, the global push toward standardized animal health protocols has elevated the baseline requirement for pharmaceutical-grade consistency, pushing manufacturers to invest in advanced synthesis capabilities and rigorous quality assurance infrastructure. Second, the growing complexity of formulation requirements across species—from ruminants and poultry to companion animals—has increased the demand for specialized active ingredients that cannot be efficiently sourced through fragmented or unverified supply networks.
Third, the regulatory environment continues to evolve at a pace that directly impacts manufacturing compliance and product availability. Monitoring bodies such as the U.S. Food and Drug Administration have highlighted recurring supply disruptions in critical antimicrobial ingredients, underscoring how dependent downstream formulations remain on stable upstream production. At the same time, international standards increasingly emphasize antimicrobial stewardship, residue management, and export-quality compliance, raising the operational bar for manufacturers seeking to serve regulated markets.
Fourth, geopolitical and trade developments have introduced a new layer of cost and continuity risk. With a significant share of veterinary active ingredients historically routed through specific overseas production hubs, any shift in tariff policy, logistics friction, or export control can quickly affect landed costs and supply reliability. These dynamics are not abstract; they are actively reshaping sourcing models, prompting manufacturers and buyers alike to reassess geographic concentration, redundancy planning, and long-term contract structures.
What This Study Delivers for Enterprise Strategy
The Worldwide Veterinary API Manufacturing Market report is structured to translate high-level trends into actionable intelligence. It provides a detailed examination of market sizing, growth trajectories, and segmentation patterns across the core dimensions that matter most to manufacturing and procurement leaders. Rather than presenting isolated statistics, the study weaves together demand-side drivers, production technology pathways, and competitive positioning to show how the ecosystem functions as an integrated system.
Readers will find a systematic breakdown of the principal active ingredient categories that anchor veterinary pharmaceutical portfolios, alongside an evaluation of the synthesis approaches that define production economics, scalability, and regulatory readiness. The analysis extends to regional manufacturing distribution, highlighting where production capacity is concentrated, where supply dependencies create vulnerability, and where emerging hubs are gaining relevance in global procurement strategies. By contextualizing these structural elements within the forecast period, the report enables clients to model scenarios, stress-test sourcing assumptions, and identify where strategic flexibility will yield the greatest commercial advantage.
Beyond market structure, the study incorporates a focused competitive assessment of the organizations shaping the field. This includes an evaluation of multinational animal health leaders with integrated API development capabilities, specialized manufacturers serving specific therapeutic categories, and contract development and manufacturing organizations expanding their veterinary capacity to meet global demand. The competitive lens is not limited to corporate profiles; it examines how facility investments, technology partnerships, and site acquisitions are altering supply network reliability and production readiness. Recent industry developments—including dedicated facility commissioning, strategic technology licensing agreements, and contract manufacturing site acquisitions—are analyzed as indicators of where capacity is being built, where innovation is being embedded, and where supply security is being prioritized.
To ensure operational relevance, the report also integrates key industry context across regulation, raw material availability, logistics, and trade policy. These inputs are mapped to the segments and regions they affect most, giving clients a clearer picture of the constraints and opportunities that will influence pricing, lead times, and formulation planning through 2032.
Competitive Realignment and Supply Network Resilience
The competitive landscape in veterinary API manufacturing is defined by a blend of established animal health enterprises and specialized production organizations, each pursuing distinct strategic advantages. At one end of the spectrum, global animal health leaders maintain in-house or tightly controlled API capabilities that support broad therapeutic portfolios spanning parasiticides, anti-infectives, vaccines, and biologicals for both livestock and companion animals. These organizations benefit from vertical integration, extensive regulatory experience, and the ability to align API supply with finished product pipelines.
At the same time, a robust tier of specialized manufacturers and CDMO-style operators has gained prominence by focusing on production efficiency, regulatory-grade quality systems, and flexible supply arrangements. Companies operating from established pharmaceutical manufacturing regions are expanding dedicated veterinary API capacity, investing in compliance infrastructure, and positioning themselves as reliable nodes within multinational supply chains. This specialization matters because veterinary formulations often require consistent batch quality, species-specific compliance, and the ability to support both generic and differentiated product pipelines.
Worldwide Veterinary API Manufacturing Market
Recent corporate activity reflects a clear emphasis on capacity assurance and technology access. Facility expansion and the commissioning of dedicated veterinary API production units signal growing confidence in long-term demand, while also addressing the need for modernized infrastructure that can satisfy tightening quality and sustainability expectations. In parallel, partnerships aimed at accessing advanced development platforms and the acquisition of contract manufacturing sites illustrate how organizations are fortifying supply continuity for critical farm animal and companion animal products. These moves are not isolated; they represent a broader pattern of structural reinforcement as buyers and producers alike respond to the reality that API availability can directly influence therapeutic access and commercial performance.
Navigating Concentration, Cost, and Continuity Risks
Market concentration remains an important strategic consideration. A meaningful share of revenue is held by a relatively compact group of leading participants, which shapes pricing dynamics, partnership leverage, and the bargaining power of downstream formulators. Understanding where concentration exerts pressure—and where fragmented supply offers flexibility—is essential for procurement strategy, contract negotiation, and multi-sourcing design.
Cost and continuity risks are equally central to 2026 planning. Regulatory oversight of antimicrobial supply, periodic ingredient shortages, and production delays tied to overseas manufacturing have already demonstrated how quickly availability can become a constraint. When combined with trade policy shifts affecting pharmaceutical inputs, these factors can raise production expenses and complicate inventory planning. The result is a market environment in which resilience is increasingly valued alongside efficiency. Organizations that diversify qualified sourcing channels, align manufacturing partnerships with compliance capability, and anticipate regulatory pacing will be better equipped to manage volatility without sacrificing product quality or therapeutic reliability.
Strategic Takeaways for 2026 Planning
The veterinary API manufacturing market is entering a phase where growth, regulation, and supply chain architecture will jointly determine competitive outcomes. For leadership teams preparing 2026 strategic plans, several priorities stand out. First, capacity strategy must be evaluated not only against projected volume but also against the quality, compliance, and continuity standards that regulated markets increasingly require. Second, sourcing models should be stress-tested against concentration risk, logistics variability, and shifting trade conditions to ensure that cost optimization does not inadvertently create exposure. Third, partnership selection should account for technological readiness, production flexibility, and the ability to support both current portfolios and emerging therapeutic categories.
Our Worldwide Veterinary API Manufacturing Market study is designed to support these decisions with rigorous market sizing, segmentation analysis, competitive intelligence, and scenario-ready context. It provides the evidentiary foundation necessary to move from reactive procurement to proactive market positioning. For organizations seeking to secure supply advantage, evaluate entry or expansion opportunities, and align manufacturing strategy with the realities of a maturing global animal health sector, the full report delivers the depth required to act with confidence.
The complete analysis, including detailed segmentation data, regional manufacturing profiles, and granular competitive assessments, is available through the full market research release. Accessing the complete study enables decision-makers to translate these directional insights into precise, executable strategies for the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary API Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fire System Aircraft Market to Hit $3,044.52M by 2032, 4.85% CAGR
By pmarketresearch, 2026-09-16
Unlocking Strategic Value in the Global Fire System Aircraft Market: A 2026 Outlook
As the aviation industry navigates a period of unprecedented transformation, the integration of advanced fire protection systems has evolved from a regulatory necessity to a critical competitive differentiator. At PW Consulting, we have meticulously compiled our latest Worldwide Fire System Aircraft Market research to provide stakeholders with the actionable intelligence required to navigate this complex landscape. This study is not merely a collection of statistics; it is a strategic compass designed to guide investment decisions, product development roadmaps, and supply chain optimizations throughout the forecast period extending to 2032.
Worldwide Fire System Design Market
The market has demonstrated resilience and steady growth over the past half-decade. Historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue, driven by aging fleet replacements, heightened safety regulations, and the expansion of global air travel networks. Building on this foundation, the market is projected to reach substantial valuation milestones by the end of the forecast horizon. With a compound annual growth rate of 4.85 percent across the forecast period of 2026 to 2032, the industry presents a compelling opportunity for stakeholders who can align their strategies with emerging technological and regulatory shifts. Understanding the magnitude of this growth is essential, but recognizing the underlying drivers is where true strategic advantage lies.
The Operational Core: What This Research Delivers
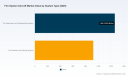
Our comprehensive analysis goes beyond top-line figures to dissect the operational mechanics of the market. The report provides a granular examination of the two primary system categories that define the industry landscape. We analyze the market share and growth potential of fire suppression and extinguishing systems versus fire detection and warning systems. While both segments are critical, their growth trajectories differ based on technological adoption rates and regulatory mandates. By understanding the distinct value propositions of each system type, manufacturers and investors can allocate resources more effectively.
Furthermore, the study segments the market by aircraft type, offering insights into the specific demands of narrow-body, wide-body, military, and regional or general aviation platforms. Each aircraft category presents unique engineering challenges and safety requirements. For instance, the density of installations in narrow-body aircraft contrasts sharply with the specialized suppression needs of military platforms. Our analysis illuminates these differences, helping partners tailor their solutions to the specific pain points of each segment. Additionally, the report breaks down revenue distributions across key geographic regions, highlighting where infrastructure development and regulatory enforcement are creating the most fertile ground for market expansion.
Beyond segmentation, the research delves into the qualitative dynamics shaping the industry. We examine the supply chain intricacies, from raw material sourcing for specialized agents to the manufacturing of high-pressure vessels and pyrotechnic cartridges. Our team has evaluated the production capabilities and technological readiness of major players to provide a clear picture of supply-side resilience. This is crucial for organizations seeking to mitigate risk in an era where supply chain disruptions can have cascading effects on aircraft maintenance schedules and operational readiness.
Competitive Landscape and Dominant Forces
The market structure is characterized by a mix of established aerospace giants and specialized niche manufacturers. Our analysis indicates a moderate to high level of market concentration, with the top three players holding a significant portion of the market share, while the top five collectively command an even larger share of total revenue. This concentration suggests that economies of scale and entrenched relationships with Original Equipment Manufacturers (OEMs) play a vital role in sustaining market position. However, the presence of agile, specialized firms indicates that innovation and certification speed remain powerful levers for market entry and growth.
Collins Aerospace (RTX) stands as a paramount example of integrated capability, providing a broad range of advanced fire detection and suppression systems for commercial and military aircraft. Their ability to cover automatic fire and explosion suppression for occupied spaces, cargo bays, and engine areas positions them as a central partner for major airframe manufacturers. Similarly, Meggitt PLC has established a reputation for designing and manufacturing fire suppression systems fitted on virtually every civil and military aircraft, leveraging in-house development for specific threat zones including engine, APU, and cargo applications. These entrenched players set the standard for reliability and certification compliance.
On the component and specialized manufacturing side, AMERON (AMETEK MRO) operates as a leading OEM manufacturer of aircraft fire suppression systems, components, high-pressure vessels, and pyrotechnic cartridges for engine, APU, cargo, and lavatory applications across commercial and military platforms. Their focus on critical hardware underscores the importance of the supply chain beneath the system integrators. Ventura Aerospace Inc. distinguishes itself by developing FAA-certified fire suppression systems specifically for Class E cargo compartments on aircraft such as MD-11F, MD-10F, and 777F, with modular designs adaptable to various fixed-wing platforms. This specialization highlights the opportunity for targeted solutions in cargo safety, a sector under increasing scrutiny.
The portable extinguisher market also sees dynamic activity. H3R Aviation supplies portable Halon and Halotron fire extinguishers and mounting options for fixed- and rotary-wing aircraft of all types and sizes. Amerex Corporation manufactures portable and fixed fire extinguishers for aviation applications, with ongoing innovation in aircraft fire safety products. These companies are often at the forefront of responding to regulatory changes regarding portable agent specifications. Meanwhile, Parker Aerospace offers ATA Chapter 26 fire protection systems with high accuracy, reliability, and low maintenance for aircraft safety, emphasizing the operational cost benefits of robust design.
Innovation in agents and specialized services is represented by companies like Hazard Control Technologies (HCT), which provides specialized aircraft fire suppression services and agents, including F-500 EA encapsulator technology qualified under FAA AC 150/5210-6E for aviation hazards including lithium-ion battery fires. Perimeter Solutions supplies SOLBERG and AUXQUIMIA Class B fluorine-free and AFFF firefighting foam concentrates, including AVIGARD line certified for ICAO aviation applications, addressing the environmental shift in chemical agents. Finally, PacSci EMC supplies energetic components and fire extinguishing cartridges qualified for commercial and military aircraft fire suppression systems, supporting FAA Airworthiness approvals, ensuring that the mechanical execution of suppression systems meets rigorous standards.
Regulatory Waves and Technological Shifts
No strategic analysis of this market is complete without a deep dive into the regulatory environment, which is currently undergoing significant turmoil and transformation. The phase-out of Halon-based systems is the single most impactful dynamic shaping the near-term market. The EU Ozone Regulation sets end-dates for halon use in existing fleets, with a key deadline of 31 December 2025 for portable Halon 1211 extinguishers in cabins and crew compartments on EASA-registered aircraft. This regulatory cliff creates an immediate demand for replacement solutions and retrofitting services.
In response to these mandates, EASA and the European Commission published the Halon replacement in the aviation industry guide 2025 to support compliance with EU Ozone Regulation on halon phase-out for portable extinguishers and onboard systems. This guidance serves as a critical roadmap for operators and manufacturers alike. Furthermore, ICAO has introduced cut-off dates after which Halon 1301-based fire extinguishing systems should no longer be used for new-type certified aircraft, including cargo compartments. These international standards reinforce the global trend away from ozone-depleting substances, forcing a structural shift in product portfolios.
The transition is not just about compliance; it is about performance and environmental stewardship. The transition to fluorine-free foam concentrates (SFFF/AR-SFFF) and clean agents such as Novec 1230 or 2-BTP/CO2 blends is accelerating for aviation applications due to environmental regulations and halon phase-out. Manufacturers who can validate the efficacy of these new agents under extreme aviation conditions will capture significant market share. This shift is complemented by evolving safety standards for emerging technologies. FAA and EASA continue to enforce enhanced fire protection requirements for lithium battery fires in cargo compartments and electronic device storage under updated airworthiness standards. As the electrification of aircraft components and the transport of lithium-ion batteries increase, the ability to suppress thermal runaway events becomes a premium capability.
Recent industry developments underscore the speed of this adaptation. In October 2025, H3R Aviation introduced Halotron BRx extinguishers as a Halon 1211 replacement for portable aircraft fire extinguishers ahead of regulatory deadlines, demonstrating proactive product lifecycle management. Concurrently, SAE International released new standards for powerplant fire protection systems, updating and supplementing FAA Advisory Circular 20-135 guidance, which will influence design requirements for engine fire protection for years to come. By December 2025, the deadline for European-registered aircraft to no longer carry Halon 1211 portable fire extinguishers marks a hard stop that will trigger a surge in replacement orders.
Strategic Implications for 2026 and Beyond
For decision-makers planning their moves in 2026, the implications of this research are clear. The convergence of steady market growth, regulatory pressure, and technological innovation creates a high-stakes environment. Companies must balance the immediate revenue opportunity presented by Halon replacement mandates with the long-term investment required for next-generation suppression agents and detection technologies. Partnerships between system integrators and agent suppliers will become increasingly vital to ensure certification speed and operational reliability.
Supply chain resilience is another critical focal point. With specific requirements for high-pressure vessels, pyrotechnic cartridges, and specialized foam concentrates, the ability to secure qualified components will differentiate successful market participants from those facing bottlenecks. The market concentration data suggests that while large players dominate, there is ample room for specialized firms to thrive by addressing niche requirements, such as cargo compartment specific solutions or lithium-ion battery fire suppression. Understanding the distinct growth profiles of narrow-body versus wide-body aircraft, as well as the persistent demand in military and general aviation sectors, allows for targeted portfolio strategy.
Worldwide Fire System Aircraft Market
The geographic dimension of the market also warrants attention. While historical revenue data shows strong performance across North America, Europe, and Asia Pacific, the rate of regulatory adoption and fleet modernization varies by region. Strategic market entry or expansion plans must account for these regional nuances rather than applying a one-size-fits-all approach. The research provides the necessary regional breakdowns to inform localized strategies without exposing the specific numerical allocations that would require a full report download to verify.
Conclusion: The Path to Informed Action
The Worldwide Fire System Aircraft Market is at a pivotal juncture. The data confirms a robust growth trajectory over the coming years, but the real value lies in understanding the forces that will shape that growth. Regulatory deadlines are acting as catalysts, environmental concerns are driving chemical innovation, and evolving safety standards for batteries and powerplants are redefining system requirements. Our latest research publication captures these complexities in a structured, actionable format.
We invite industry leaders, investors, and strategic planners to leverage this intelligence to fortify their 2026 decision-making processes. The complete report offers the detailed segmentation data, competitive profiling, and regional analysis necessary to build a resilient strategy. By accessing the full study, stakeholders can move beyond general trends to specific, data-backed plans that align with the realities of the market. The future of aviation fire safety is being written now, and those with the deepest insights will be best positioned to lead.
For detailed analysis of this topic, please visit the official page: Worldwide Fire System Aircraft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Paroxetine Market to Hit $1,074.88M by 2032, 4.12% CAGR
By pmarketresearch, 2026-09-16
Navigating the Paroxetine Market: Strategic Intelligence for 2026 and Beyond
The global pharmaceutical landscape for central nervous system therapeutics continues to evolve at a complex pace, shaped by shifting clinical guidelines, evolving pricing architectures, and persistent supply chain realignments. Among these therapeutic categories, paroxetine remains a cornerstone intervention for mood and anxiety disorders, with a market trajectory that demands precise, forward-looking intelligence. As organizations prepare for strategic planning cycles in 2026, understanding the structural dynamics, competitive positioning, and macroeconomic tailwinds of the worldwide paroxetine sector is no longer optional—it is a critical prerequisite for informed capital allocation, portfolio optimization, and market entry or expansion decisions.
Our newly released Worldwide Paroxetine Market research study delivers a comprehensive, multi-dimensional assessment of this therapeutic space. Designed for executive leadership, commercial strategy teams, and investment analysts, the report bridges historical performance with forward-looking projections, equipping stakeholders with the analytical rigor required to navigate an environment defined by biosimilar-style generic competition, regional regulatory divergence, and tightening margin structures. Below, we outline the core strategic value proposition of this research and preview the operational intelligence it contains.
Worldwide Paroxetine Market
Macro Trajectory and Forecast Architecture
The paroxetine market has demonstrated consistent, albeit moderate, growth over the past half-decade, reflecting steady clinical adoption across established indications and the gradual expansion of accessible treatment pathways in emerging economies. Historical revenue data from 2020 through 2025 reveals a market that has matured beyond its initial generic proliferation phase and entered a stabilization period, where volume growth is increasingly balanced by disciplined pricing dynamics and formulation differentiation. Base-year revenue positioning in 2025 anchors the analysis, providing a reliable foundation for forward extrapolation.
Paracetamol Market
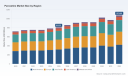
Looking ahead, the forecast horizon spanning 2026 through 2032 maps a clear growth continuum, with compound annual growth projections signaling a measured but sustained expansion trajectory. The market is expected to scale meaningfully across the forecast window, supported by persistent demand for first-line and adjunctive psychiatric therapies, broadening access in price-sensitive regions, and incremental formulation innovations that extend product lifecycles. While exact segmentation-level figures remain reserved for the full dataset, the overarching revenue curve points to a market that will cross significant valuation thresholds by the end of the decade, creating both opportunity and competitive intensity for active participants.
For strategic planners, this macro trajectory carries immediate implications. Organizations must evaluate whether their current market exposure aligns with projected regional demand shifts, assess the margin resilience of their product portfolios against anticipated pricing pressures, and determine the optimal timing for capacity investments or partnership structuring. The report translates these high-level trends into actionable scenario frameworks, allowing decision-makers to stress-test their strategies against multiple demand and pricing environments.
Competitive Landscape and Strategic Positioning
The paroxetine market is characterized by a concentrated yet highly fragmented competitive ecosystem, where branded legacy formulations coexist alongside a robust pipeline of generic alternatives. Major multinational pharmaceutical entities maintain strong commercial footprints through established branded portfolios, focusing on controlled-release architectures, brand equity preservation, and targeted physician engagement. Simultaneously, a cohort of globally integrated generic manufacturers has capitalized on the post-patent expiration environment, scaling production capabilities, securing regulatory clearances across multiple jurisdictions, and competing aggressively on price, supply reliability, and formulation breadth.
Industry concentration metrics underscore this dual dynamic. The market exhibits moderate concentration at the top tier, with leading participants commanding a meaningful share of total revenue, while the broader field remains highly competitive, particularly within the generic segment. This structure creates distinct strategic pathways: branded players must defend market share through clinical differentiation, specialty formulations, and value-based contracting, while generic manufacturers must optimize manufacturing efficiency, maintain stringent bioequivalence standards, and navigate increasingly complex procurement negotiations with distributors and pharmacy networks.
Recent regulatory and commercial milestones further illustrate the competitive velocity of this space. During the latter half of 2023 and into 2024, multiple manufacturers secured pivotal regulatory clearances for paroxetine hydrochloride and paroxetine mesylate formulations across key markets, expanding the availability of therapeutically equivalent alternatives and intensifying price competition in mature markets. These approvals reflect a broader trend of regulatory streamlining and heightened generic entry, which continuously reshapes supply availability and wholesale pricing architectures. For commercial teams, monitoring these approval timelines, understanding their downstream pricing implications, and aligning inventory or distribution strategies accordingly is essential to maintaining competitive agility.
The strategic depth of our analysis extends well beyond entity-level descriptions. The report evaluates competitive moats, examines supply chain dependencies, maps formulation-specific market penetration patterns, and assesses how recent regulatory events are likely to influence pricing trajectories and market share redistribution over the forecast period. Decision-makers gain a clear view of where competition is most intense, where differentiation remains viable, and how legacy product portfolios may need to be repositioned to sustain profitability.
Market Dynamics Shaping Operational Strategy
Several structural forces are actively redefining how the paroxetine market operates, and each carries direct implications for supply chain management, pricing strategy, and market access planning.
- Patent Landscape Evolution: The expiration of foundational intellectual property protections for core paroxetine formulations years ago fundamentally transformed market architecture, enabling widespread generic entry and initiating prolonged price erosion cycles. While this shift has improved patient access and reduced acquisition costs, it has also compressed margins and elevated the importance of manufacturing scale, regulatory compliance, and supply chain resilience. Organizations must continuously evaluate whether their cost structures can withstand ongoing pricing pressure while preserving service-level commitments to downstream partners.
- Essential Medicine Designation and Demand Stability: Inclusion of paroxetine on authoritative essential medicine listings reinforces its clinical indispensability and supports sustained demand visibility across both developed and developing healthcare systems. This designation provides a degree of commercial predictability that can inform long-term capacity planning, inventory positioning, and partnership structuring, particularly in regions where public procurement and formulary inclusion drive volume.
- API Sourcing and Geographic Concentration: The active pharmaceutical ingredient supply chain exhibits pronounced geographic concentration, with a substantial majority of production originating from a limited set of manufacturing hubs. While this concentration has enabled cost efficiencies and scalable output, it also introduces vulnerability to regulatory shifts, logistical disruptions, and geopolitical considerations. Strategic buyers and manufacturers alike must assess supplier diversification options, evaluate dual-sourcing feasibility, and model the financial and operational impact of potential supply interruptions.
- Supply Stabilization and Procurement Dynamics: Resolution of recent supply constraints in key markets has restored baseline availability and reduced acute procurement friction, but it has also recalibrated buyer expectations around reliability and pricing transparency. As inventory levels normalize, procurement teams are increasingly focused on total cost of ownership, contract flexibility, and supplier performance metrics rather than mere availability. Organizations that institutionalize these evaluation criteria will be better positioned to secure favorable terms amid competitive sourcing environments.
- Pricing Architecture and Margin Management: Intense generic competition has compressed unit economics in mature markets, with wholesale pricing settling at levels that demand operational efficiency and scale-driven cost advantages. Sustaining profitability in this environment requires disciplined procurement, optimized manufacturing yields, strategic bundling or contractual arrangements, and proactive engagement with distribution partners. The report provides analytical frameworks to evaluate pricing sensitivity, model margin scenarios, and identify where formulation differentiation or market-specific positioning can preserve value.
What the Full Research Delivers
While the macro trajectory, competitive dynamics, and structural forces outlined above establish the strategic backdrop, the complete Worldwide Paroxetine Market study translates this context into a granular, execution-ready intelligence package. The report is structured to support cross-functional decision-making, offering both high-level strategic synthesis and detailed operational segmentation.
Key components of the research include:
- Historical Performance Reconstruction: A year-by-year analysis tracing revenue evolution, demand patterns, and pricing behavior across the base period, enabling stakeholders to identify inflection points, validate internal forecasts, and benchmark organizational performance against market-wide trends.
- Forward Forecast Modeling: Multi-year projections extending through the end of the decade, constructed using rigorous demand-driver analysis, regulatory pathway assessment, and pricing trajectory modeling. These forecasts are designed to support capacity planning, investment prioritization, and scenario-based strategic planning.
- Segmentation and Application Mapping: Detailed breakdowns that illuminate how demand distributes across therapeutic applications, formulation types, and regional markets. These analyses help commercial teams identify high-growth pockets, evaluate formulary positioning opportunities, and tailor market access strategies to local prescribing behaviors and reimbursement environments.
- Competitive Intelligence and Benchmarking: Entity-level profiles that examine commercial positioning, formulation portfolios, regulatory footprints, and strategic initiatives. The analysis highlights competitive advantages, vulnerability points, and likely market share movement, enabling organizations to calibrate their own strategic responses with precision.
- Strategic Recommendations and Decision Frameworks: Actionable guidance tailored to distinct stakeholder objectives, whether the priority is market entry, portfolio expansion, supply chain optimization, pricing strategy refinement, or partnership evaluation. Each recommendation is grounded in the underlying data architecture and designed for direct integration into planning workflows.
The full dataset preserves the analytical granularity required for operational execution, including region-specific demand dynamics, formulation-level market sizing, application-level revenue distribution, and proprietary concentration metrics. These elements are deliberately reserved for the complete report to ensure that stakeholders who require execution-grade intelligence can access the full analytical architecture without compromise.
Why 2026 Decision-Making Depends on This Intelligence
As organizations finalize their strategic roadmaps for 2026, the paroxetine market presents a familiar paradox: stable clinical demand coexists with relentless competitive and pricing pressure, while regulatory and supply chain variables continue to introduce ambiguity. Navigating this environment successfully requires more than high-level trend awareness. It demands precise visibility into where growth is concentrating, how competitive positions are shifting, which formulation and regional segments offer the most favorable risk-reward profiles, and how pricing and procurement dynamics are likely to evolve as generic penetration deepens and supply chains recalibrate.
The Worldwide Paroxetine Market research study is built to meet this requirement. By integrating historical performance, forward-looking forecasts, competitive benchmarking, and structural market analysis into a single cohesive framework, the report equips executives, commercial leaders, and investment professionals with the evidence base needed to make confident, timely decisions. Whether the objective is to defend existing market position, identify high-potential expansion avenues, optimize supply chain resilience, or refine pricing and procurement strategies, the research provides the analytical foundation necessary to act with precision.
For teams preparing for 2026 planning cycles, the strategic window to align market intelligence with execution planning is narrow. Access the complete Worldwide Paroxetine Market study to unlock full segmentation data, detailed competitor analysis, scenario-modeling tools, and the operational insights required to translate market structure into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Paroxetine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global LAN Cable Tester Market Reaches $315.5M in 2025 with 5.82% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the 2026 Landscape: Strategic Imperatives in the Worldwide LAN Cable Tester Market
The global telecommunications infrastructure sector is entering a phase of accelerated transformation, driven by the convergence of higher-speed Ethernet standards, rising power-over-ethernet demands, and the relentless expansion of data center and enterprise connectivity. In this environment, the worldwide LAN cable tester market is not merely a niche instrumentation segment; it is a critical enabler of network reliability, compliance, and deployment velocity. Our latest market research provides a comprehensive, data-driven foundation for decision-makers who must align procurement, product development, and market-entry strategies with the realities of 2026 and beyond.
For executives, procurement leaders, and strategy teams, understanding the trajectory of cable testing equipment is no longer optional. The equipment used to validate, qualify, and certify copper and hybrid cabling infrastructures sits at the intersection of standards compliance, installation quality, and long-term network performance. As organizations prepare for Wi-Fi 7/8 deployments, AI-ready workplace architectures, and hyperscale data center expansions, the demand for precise, portable, and standards-aligned testing tools continues to reshape competitive dynamics. This report is designed to translate macro-level market momentum into actionable intelligence, giving stakeholders the clarity needed to act decisively in a segment where timing, compliance, and technology readiness determine market advantage.
Market Momentum: Tracking Growth Trajectories and Structural Shifts
The worldwide LAN cable tester market has demonstrated consistent expansion over the past half-decade, reflecting the broader rhythm of network modernization across enterprise, service provider, and infrastructure segments. From 2020 through 2025, revenue climbed steadily as organizations reinforced cabling backbones, upgraded edge networks, and responded to increasingly stringent connectivity requirements. The base year of 2025 establishes a meaningful benchmark, capturing the cumulative effect of post-pandemic infrastructure investment, the normalization of hybrid work architectures, and the early adoption of higher-speed Ethernet deployments.
Looking ahead, the forecast period from 2026 to 2032 projects a measured yet resilient growth path. The overall market is expected to advance at a CAGR of 5.82 percent, signaling steady demand supported by recurring installation activity, certification requirements, and the ongoing refresh of copper-based LAN environments. This trajectory is not purely linear; it reflects the interplay of multiple forces, including the adoption of multi-gigabit Ethernet in enterprise settings, the validation of PoE++ capabilities for modern endpoint ecosystems, and the compliance-driven need for certified cabling links in regulated installations. The growth curve underscores a market that is maturing but still expanding, where volume gains are increasingly tied to technology differentiation rather than sheer unit shipment.
Revenue expansion over the forecast horizon is shaped by more than incremental adoption. It is reinforced by structural shifts in how networks are designed, validated, and maintained. As enterprises move toward 2.5G, 5G, and 10GBASE-T deployments with faster optical uplinks, the role of testing equipment becomes more central to ensuring that physical layer performance matches logical network expectations. Likewise, the growing emphasis on AI-scale infrastructure and higher-density fiber deployments adds indirect pressure on copper validation workflows, since hybrid environments require robust verification before active equipment is commissioned. These dynamics contribute to a market rhythm in which demand is sustained by both new installations and the need to validate existing cabling against modern performance thresholds.
Industry Dynamics Reshaping the Testing Landscape
The current market environment is influenced by several converging developments that directly affect demand, product requirements, and purchasing behavior. One of the most significant is the continuing evolution of Ethernet roadmaps. As enterprise networks adopt faster copper-based speeds to support advanced wireless access points and bandwidth-intensive workplace applications, cable certification and qualification processes must adapt. Testing tools are increasingly expected to validate links for multi-gigabit performance while simultaneously checking PoE delivery capabilities, making multi-function handheld and benchtop platforms more relevant than single-purpose continuity tools.
Infrastructure trends in the broader data center and enterprise sectors also ripple into the LAN cable tester segment. The data center cabling market is projected to expand substantially by 2035, with fiber optic cables holding a significant share of the 2025 landscape. While this shift emphasizes fiber, it does not diminish the ongoing importance of copper validation in edge, access, and LAN environments. On the contrary, hybrid architectures and transitional deployments create persistent demand for testers that can verify copper links, support PoE performance checks, and confirm wiring integrity before higher-speed equipment is installed.
Regulatory and standards-driven requirements further reinforce market demand. Ethernet terminations in installation projects are expected to be tested in alignment with recognized standards such as TIA/EIA 568A, particularly in procurement and public-sector projects. Compliance-oriented purchasing increases the relevance of certification-grade testers and encourages buyers to prioritize instruments that can document adherence to industry specifications. In this context, the testing equipment market becomes tightly linked to project procurement cycles, contractor requirements, and quality-assurance workflows.
A recent product launch illustrates how manufacturers are responding to these pressures. NetAlly introduced the LinkRunner AT 1500, a new model designed for fast copper network link and cable testing, with PoE++ validation support extending up to 90W. This type of development reflects a broader industry direction: frontline technicians and managed service providers need portable, rapid, and multi-parameter tools that can handle both connectivity verification and power delivery checks in the field. The emphasis on speed, usability, and higher-wattage PoE validation points to a market where operational efficiency and feature depth are increasingly decisive differentiators.
The Strategic Lens: Why This Research Matters for 2026 Decisions
For organizations operating in or adjacent to the LAN cable testing ecosystem, strategic decisions in 2026 will hinge on a clear understanding of where demand is strongest, how product categories are competing, and which technology pathways are gaining traction. This research is built to support that decision-making process by providing a structured view of market size, growth pacing, segmentation dynamics, and competitive positioning.
The strategic value of the report begins with its treatment of market scale and trajectory. By grounding analysis in a robust historical window and extending forward through the forecast period, the study enables leaders to assess whether current planning assumptions align with observed momentum. The reported revenue progression and the projected CAGR offer a baseline for scenario planning, budget forecasting, and capacity alignment. More importantly, the report helps distinguish between short-term project-driven demand and longer-term structural adoption, which is essential for organizations deciding where to allocate sales resources, manufacturing capacity, or R&D attention.
Equally important is the report’s focus on segmentation logic. The market is not moving as a single homogeneous pool; it is shaped by different buyer needs across region, device type, and technology class. Understanding the relative weight of handheld portable testers versus benchtop and industrial models, for example, helps clarify where portability and field usability matter most. Similarly, distinguishing among certification, qualification/verification, and standard continuity solutions reveals how much of the market is driven by compliance-grade validation versus basic installation checks. These distinctions matter for product roadmap planning, pricing strategy, channel design, and go-to-market messaging.
The research is also designed to support competitive strategy. With a consolidated market structure, a limited number of established players hold a substantial share of revenue, while a broader field of specialists and emerging manufacturers competes on feature sets, price points, and regional reach. Mapping this landscape helps organizations identify where incumbents are strongest, where gaps may exist, and how new entrants or product launches could shift buyer expectations. Rather than treating competition as a static list of names, the report frames it as a dynamic environment in which product launches, technology upgrades, and regional specialization continuously reshape purchasing priorities.
Worldwide LAN Cable Tester Market
Inside the Report: Practical Intelligence for Execution
Beyond macro-level context, this study is structured to deliver practical, execution-ready content. The report framework is designed to help teams move from high-level awareness to informed action, with analytical components that align to common strategic questions.
- Market sizing and historical progression: A detailed view of revenue development across the historical window and forecast period, providing context for growth assumptions and planning benchmarks.
- Segmentation analysis: Breakdowns by region, type, and technology that illuminate where demand concentrates and how product categories compare in commercial relevance.
- Competitive landscape mapping: Profiles of leading and emerging participants, including their core offerings and positioning, to support benchmarking and differentiation planning.
- Industry and infrastructure context: Integration of broader cabling, data center, and Ethernet roadmap developments that influence testing demand and product expectations.
- Recent market developments: Coverage of notable product launches and segment events that signal near-term direction and competitive responsiveness.
- Regulatory and standards considerations: Discussion of compliance-linked testing needs that affect procurement behavior and product selection in project-driven environments.
Each component is intended to reduce ambiguity in planning. For product teams, the segmentation and competitive material can inform feature prioritization and portfolio architecture. For sales and channel leaders, the regional and technology perspectives can shape territory planning and messaging emphasis. For corporate strategy and investment groups, the market trajectory and concentration data provide a structured basis for evaluating opportunity size, entry risk, and long-term positioning.
Competitive Landscape: Established Leaders and Expanding Contenders
The worldwide LAN cable tester market is characterized by a blend of well-established testing specialists, broad instrumentation players, and regional manufacturers targeting specific price-performance segments. This mix creates a competitive environment in which brand trust, standards alignment, portability, and feature breadth all play meaningful roles in purchase decisions.
Headlight Tester Market
Fluke Networks remains a prominent force in the segment, offering a wide range of LAN cable testing solutions that span copper certification, qualification, and verification. Its product lineup includes the DSX CableAnalyzer series for copper certification up to Cat 8, the LinkIQ Cable+ Network Tester for Ethernet qualification and troubleshooting at speeds up to 10G, the MicroScanner series for verification tasks, and industrial Ethernet testers designed for demanding deployment environments. This breadth positions the company as a reference point for organizations seeking certification-grade accuracy and multi-purpose field tools.
NetAlly focuses strongly on handheld network and cable testing for frontline technicians and managed service providers. Its LinkRunner family, including the recently introduced AT 1500 model, supports copper network link and cable testing, PoE validation, and troubleshooting workflows. The emphasis on speed, field usability, and higher-wattage PoE support reflects a strategy aimed at users who need rapid diagnostics without sacrificing validation depth.
TREND Networks specializes in data cable testers, certifiers, and verifiers for LAN and WAN environments. Its LanTEK IV cable certifier series and SignalTEK qualification testers for copper and fiber support PoE and network performance testing, reinforcing a position centered on certified installation quality and robust verification capabilities.
Klein Tools approaches the market from an accessible, practitioner-oriented angle with products such as the LAN Scout Jr. 2, Scout Pro series, and VDV526-100 Network Cable Tester. These tools address continuity, wiremap, and basic Ethernet cable verification for CAT5e and CAT6 environments, appealing to installers and technicians who prioritize ease of use and straightforward validation tasks.
VIAVI Solutions contributes to the competitive field through Ethernet test solutions that support field testing of Ethernet services at higher speeds. Its T-BERD/MTS-5800 platform is oriented toward standards-based testing for network deployment and maintenance, aligning with environments where service-level validation and operational reliability are paramount.
Softing IT Networks offers WireXpert cable certifiers and LinkXpert/NetXpert series instruments for copper and fiber testing, qualification, PoE testing, and active network analysis, with ETL approval adding a compliance-related dimension to its value proposition. Platinum Tools provides the Net Chaser Ethernet speed certifier and network tester for certifying up to 1Gbps, cable fault detection, and noise testing in LAN environments, targeting performance validation in practical installation settings.
Triplett Test Equipment & Tools produces the Real World Certifier for network cable certification, emphasizing the identification of slow cables, wiring issues, and performance validation. AEM Holdings develops portable network cable testers such as the TestPro 100 multi-gigabit copper cable validator and certifier, supporting 2.5G, 5G, and 10G Ethernet along with PoE capabilities, which places it in the higher-performance portable segment. NOYAFA rounds out the competitive field with a range of affordable multi-function network cable testers, length testers, and Ethernet tracers that include PoE testing and PING features for LAN installation work, serving price-conscious buyers and broader installation markets.
Together, these companies illustrate the range of positions available in the market: from premium certification and field diagnostics to accessible continuity tools and multi-gigabit portable validation. The competitive picture is not static. Product launches, technology upgrades, and shifting buyer priorities continually redraw the boundaries between segments, making ongoing intelligence essential for any organization seeking to compete effectively.
Concentration, Positioning, and the Path to 2032
The market’s concentration profile adds another layer of strategic context. A relatively concentrated revenue base indicates that a core group of participants holds meaningful commercial influence, while the remaining share is distributed among regional specialists and value-oriented manufacturers. This structure has practical implications for pricing behavior, channel leverage, and differentiation. Incumbents with strong certification and qualification portfolios can command attention in compliance-driven and performance-sensitive segments, while smaller or regionally focused players can compete by addressing specific usability, affordability, or localized support needs.
As the forecast period extends toward 2032, the market’s evolution will likely be shaped by the continued adoption of higher-speed copper Ethernet, expanded PoE requirements, and the ongoing need to validate cabling before active equipment deployment. Testing instruments that can efficiently cover multiple parameters, support field workflows, and document compliance will remain especially relevant. At the same time, organizations that can align their offerings with emerging deployment patterns, including Wi-Fi 7/8 readiness and AI-enabled workplace infrastructure, will be better positioned to capture demand as installation standards and user expectations rise.
For stakeholders evaluating the market in 2026, the strategic task is not simply to identify growth, but to interpret it with precision. Where is demand coming from? Which product classes are gaining relevance? How are competitive offerings diverging? And what external developments are likely to alter purchasing behavior in the next planning cycle? The answers to these questions determine whether a company can move from reactive participation to informed leadership.
Conclusion: Turning Market Intelligence into Competitive Advantage
The worldwide LAN cable tester market is entering a period in which growth, technology change, and compliance expectations converge. For manufacturers, distributors, service providers, and enterprise decision-makers, this creates both opportunity and complexity. Our Worldwide LAN Cable Tester Market research is designed to cut through that complexity by combining macro-level market sizing with detailed segmentation, competitive profiling, and industry context that matter for execution.
The report provides the structural insight needed to plan product strategy, prioritize market opportunities, and anticipate shifts in buyer requirements. It also establishes a credible foundation for scenario planning, from near-term product launch timing to longer-term portfolio positioning through 2032. By connecting historical performance with forward-looking forecast logic, the study enables organizations to assess the market with greater confidence and fewer assumptions.
To access the full dataset, detailed segmentation breakdowns, competitive benchmarks, and the complete strategic analysis, we invite stakeholders to explore the full report. The complete intelligence package offers the depth required to turn market observation into concrete 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide LAN Cable Tester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide EV Fuses Market at $1.14 Billion in 2025, Projected $3.43 Billion by 2032
By pmarketresearch, 2026-09-16
The Invisible Backbone of Electrification: Strategic Intelligence for the Global EV Fuse Market (2026-2032)
The transition to electric mobility is often measured in electrified miles, battery capacity, or charging station deployments. Yet beneath every high-voltage battery pack, power electronics assembly, and vehicle charging interface lies a critical, often overlooked component: the EV fuse. As system voltages climb, power densities increase, and safety requirements tighten, fuses have evolved from passive overcurrent devices into sophisticated, highly engineered safety nodes that determine vehicle reliability, thermal resilience, and regulatory compliance. At PW Consulting, we recognize that the EV fuse market is no longer a derivative play on electric vehicle production. It is a distinct, high-growth arena where material economics, standardization, and product architecture intersect to shape supplier positioning and OEM sourcing strategies.
Worldwide Electronic Fuse Holders Market
Our newly released Worldwide EV Fuses Market study delivers a structured, decision-ready intelligence framework for corporate planning teams, sourcing leaders, and technology strategists preparing for the 2026-2032 horizon. This article previews the strategic contours of the research, outlines the analytical architecture of the report, and explains how our findings map directly to the procurement, product development, and competitive positioning decisions that will define the next cycle of electrification.
A Market Transitioning from Niche Component to Strategic Growth Engine
Historical market data reflects the compounding effect of electrification momentum. Between 2020 and 2025, the worldwide EV fuse market expanded from approximately $385.4 million to $1,142.5 million, marking a period of accelerated adoption driven by broader passenger EV rollouts, early commercial fleet electrification, and the initial scaling of charging infrastructure. Our forecast modeling projects continued expansion through 2032, with revenue expected to reach roughly $3,425.5 million by the end of the outlook window. This trajectory corresponds to a compound annual growth rate of 16.98 percent, a pace that places EV fuses among the more dynamically expanding segments of the automotive component ecosystem.
The growth profile is not linear, nor is it uniform across product categories or end-use applications. As battery architectures evolve toward higher-voltage platforms and electrified drivetrains become standard across more vehicle classes, the fuse requirements within these systems are shifting in both quantity and technical specification. Higher nominal voltages, sustained peak current exposures, and increasingly compact packaging demand protection solutions that balance interrupting capacity, response time, space efficiency, and long-term degradation stability. The research captures these structural shifts and maps them against demand signals that extend well beyond passenger vehicle production tallies.
What the Worldwide EV Fuses Market Study Delivers
PW Consulting’s research is designed as an operational reference rather than a static market summary. The report combines quantitative modeling with qualitative industry analysis to help decision-makers translate market trajectory into sourcing, product, and investment choices. The document is organized around several interconnected analytical pillars:
- Historical baseline and forward-looking modeling: A full retrospective spanning 2020 through 2025 anchors the analysis in observed market behavior, while the 2026-2032 forecast establishes scenario-consistent revenue projections with compound annual growth rates clearly delineated for planning purposes.
- Segmentation architecture: The study breaks down the market by geography, by fuse type, and by vehicle type, giving readers a structured understanding of where demand concentrates and how different product categories contribute to overall market value without relying on fragmented headline figures.
- Competitive landscape and corporate profiling: Detailed assessments of leading manufacturers provide visibility into product portfolios, application focus, and strategic direction, helping buyers and investors evaluate capability alignment, supply resilience, and innovation roadmaps.
- Industry context and market dynamics: The report integrates external drivers—including raw material conditions, regulatory and standards frameworks, and broader electrification trends—so that market sizing is interpreted within the environment that shapes pricing, capacity planning, and specification decisions.
- Development tracking and product intelligence: Recent corporate activities, including product launches, portfolio expansions, and catalog updates, are placed in context to illustrate how incumbents and specialists are responding to technical and commercial pressure.
Structural Demand Drivers Redefining Specification and Procurement Strategy
EV fuse demand does not grow in isolation. It is tied to a set of overlapping forces that influence both the volume of components required and the performance thresholds they must meet. Three dimensions stand out in our analysis.
Voltage escalation and system architecture change
Electric vehicle platforms continue to move toward higher-voltage architectures, and protection components must keep pace with those design choices. As battery packs, inverters, and high-power distribution networks operate at elevated direct-current levels, fuses face more demanding interrupting requirements and tighter thermal margins. This environment rewards designs capable of predictable fault interruption, stable performance under repeated stress, and compatibility with the space constraints of modern power electronics packaging. The report examines how these design pressures vary by application context and what they imply for product roadmaps and qualification pathways.
Raw material exposure and cost dynamics
Material costs are an increasingly important variable in the economics of EV fuse production and procurement. Copper, a key input across EV electrical systems, has experienced pronounced price volatility in recent months, reflecting surging demand from electrified transport, renewable energy installations, and broader supply constraints. Elevated metal pricing reverberates through component bill-of-materials calculations, affecting unit economics for manufacturers and influencing sourcing negotiations for OEMs and Tier suppliers. The study places these cost dynamics within the broader segmentation discussion so that planners can assess where material exposure is most influential and how value is distributed across the market.
Standards, compliance, and qualification complexity
Protecting high-voltage EV circuits requires adherence to automotive-specific requirements in addition to general electrical standards. Components must align with expectations tied to directives and specifications such as ISO 8820, AEC-Q200, UL 248-20, and IATF 16949 for high-voltage DC applications, alongside broader IEC 60269 family requirements that address low-voltage fuse performance up to 1500 V DC and relevant semiconductor protection use cases. Compliance is not a checkbox exercise; it shapes design cycles, validation timelines, supplier qualification, and the commercial viability of alternative parts. Our analysis addresses how these standards influence market entry, product differentiation, and the competitive balance between established automotive suppliers and specialized protection-device manufacturers.
Competitive Landscape: Capability, Specialization, and Strategic Positioning
The EV fuse market is shaped by a mix of established automotive protection specialists, diversified industrial manufacturers, and regional players with deep application experience. Market concentration reflects a meaningful degree of consolidation at the top, while still leaving room for differentiated performers in niche applications, high-voltage solutions, and safety-critical pyro fuse segments. Our report profiles leading companies to clarify where competitive advantage is being built and how firms are positioning for the next phase of electrification.
Specialized automotive protection providers
Littelfuse, Inc. continues to offer a broad high-voltage automotive fuse range, including solutions engineered for EV battery packs, power distribution, and charging systems in both passenger and commercial vehicles. Eaton Corporation has strengthened its position through Bussmann-series EV fuses and pyro fuse offerings for high-voltage protection, while also expanding assembly capacity with dedicated facilities. Mersen S.A. focuses on high-performance fuses and semiconductor protection products for battery systems, inverters, and high-current applications. These manufacturers illustrate how product breadth, application understanding, and production scale combine to influence supplier relevance across multiple vehicle and infrastructure segments.
Regional strength and precision engineering
In Japan, Pacific Engineering Corporation and SOC Corporation have built long-standing roles in EV-related fuse and pyro fuse production. Pacific Engineering’s updated catalog coverage for systems above 750 VDC, through-hole PCB fuses, and pyro fuse solutions highlights the continued importance of detailed product engineering and application-specific documentation. SOC Corporation’s compact high-performance EV fuse designs, including products developed from early mass-produced EV applications, show how heritage in automotivespecific protection can translate into sustained market presence. These firms reflect a broader pattern in which regional manufacturing expertise and close alignment with OEM validation cycles support durable competitive positioning.
Safety-critical pyro solutions and broader industrial participation
Pyro fuses and related safety switches add a different dimension to the market, particularly where fault response and crash safety integration matter. Daicel Corporation and Autoliv, Inc. address high-voltage circuit protection through pyro-based safety systems, embedding protection within the broader vehicle safety architecture. Meanwhile, companies such as Bel Fuse Inc., Sensata Technologies, SCHURTER Holding AG, ABB Ltd., and Siemens AG participate across overlapping domains, from high-voltage protection and resettable or hybrid switching solutions to industrial-grade protection devices applicable to EV power systems and infrastructure. Sensata’s continued development of high-voltage protection concepts that combine fuse and contactor functionality, and SCHURTER’s introduction of ALO series fuses for high-voltage EV applications, are representative of how product definitions are expanding at the boundary between protection, switching, and system integration.
Recent developments as market signals
The report also connects recent corporate activity to the strategic themes shaping the market. Product launches and portfolio updates from 2024 through early 2026—including new high-voltage switching and protection concepts, expanded AEC-Q200 qualified fuse lineups, comprehensive global fuse portfolios for EVs and energy storage, and updated catalog coverage for higher-voltage systems—demonstrate an industry that is iterating quickly in response to voltage escalation, safety demands, and infrastructure expansion. Tracking these moves matters because product announcements often precede shifts in qualification pipelines, sourcing preferences, and competitive differentiation.
Why This Research Matters for 2026 Decision-Making
Corporate teams entering 2026 face a set of questions that are only partially answered by top-line market growth figures. Sizing tells you the scale of the opportunity; it does not tell you where value accrues, which technical pathways are becoming preferred, how material and compliance pressures affect margin structures, or how competitive dynamics will influence supply security and pricing power. The PW Consulting study is built to address those gaps.
For procurement and supply chain leaders, the report provides a structured basis for evaluating supplier capability, understanding segment-level demand distribution, and anticipating where qualification complexity or material exposure may influence sourcing strategy. For product and engineering teams, it contextualizes the technical forces that are reshaping fuse requirements in battery packs, inverters, charging systems, and commercial vehicle applications. For strategy and corporate development groups, it frames the competitive landscape in a way that clarifies where specialization, portfolio breadth, or capacity expansion is likely to create durable advantage.
Worldwide EV Fuses Market
The study is deliberately designed to support scenario-based planning. It does not reduce the market to a single narrative. Instead, it offers the segmentation logic, competitive intelligence, and external context needed to model different sourcing, development, and investment paths with greater confidence. That approach is particularly important in a market where standards, voltage regimes, and material economics are all in motion simultaneously.
Previewing the Intelligence Inside
This article provides a strategic overview of the themes and structure embedded in the full report. It is not a substitute for the underlying analysis. The complete Worldwide EV Fuses Market study contains the detailed segmentation values, regional and application breakdowns, competitive profiling, and modeled revenue projections that planning teams need for precise internal benchmarking and decision support.
Readers who require granular market splits, type-specific and vehicle-type demand distributions, regional revenue comparisons, and in-depth corporate assessments will find those elements developed in full within the published research. The report translates market trajectory into a practical intelligence asset, giving teams a clearer view of where growth is concentrated, which capabilities are becoming more valuable, and how the competitive field is evolving as electrification moves from early expansion to broader structural integration.
Looking Ahead: Protection as a Strategic Layer in Electrification
The EV fuse market will continue to grow not simply because more electric vehicles are being produced, but because the protection architecture inside those vehicles and across the charging and energy-storage ecosystem is becoming more demanding, more regulated, and more important to overall system safety and reliability. That creates a market environment in which technical differentiation, compliance maturity, and supply resilience matter as much as unit volume.
PW Consulting’s Worldwide EV Fuses Market study is intended to give decision-makers the framework they need to navigate that environment with clarity. By combining historical context, forward-looking modeling, segmentation structure, competitive profiling, and industry dynamics, the report turns a high-growth segment into an actionable strategic reference. For organizations preparing sourcing plans, product roadmaps, capacity decisions, or market-entry assessments for 2026 and beyond, the full analysis offers the depth required to move from broad market awareness to precise, evidence-based action.
For detailed analysis of this topic, please visit the official page: Worldwide EV Fuses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MPPE Market Hits $2.04B in 2025, Projects $3.07B by 2032 at 6% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Modified Polyphenylene Ether Market: Navigating Growth, Supply Shifts, and Innovation Through 2032
The engineered thermoplastics landscape is undergoing a structural recalibration, and Modified Polyphenylene Ether (MPPE) stands at the intersection of material science, regulatory evolution, and sector-specific performance demands. As suppliers, OEMs, and procurement leaders map their portfolios for the next decade, the Worldwide Modified Polyphenylene Ether Market study from PW Consulting provides a decision-grade foundation for capital allocation, capacity planning, and competitive positioning. This overview highlights the strategic architecture of the market, the forces reshaping supply-demand equilibrium, and the analytical depth you will need to convert macro trends into executable strategy.
Market Trajectory and the Strategic Value of Forward Visibility
The global MPPE market has demonstrated consistent expansion over the historical tracking window, moving from approximately $1.52 billion in 2020 to a base-year valuation of $2,040.0 million in 2025. The forecast horizon extends through 2032, with the overall market size projected to reach an estimated $3,067.41 million by the terminal forecast year. This trajectory reflects a compound annual growth rate of 6.0%, signaling a compoundable growth engine that rewards early movers with scale advantages, feedstock hedging discipline, and application-specific formulation leadership.
In an environment where raw material volatility, regional trade policy shifts, and application-specific performance requirements are simultaneously intensifying, historical hindsight is insufficient. Decision-makers need a unified view that connects pricing sensitivity to downstream demand elasticity, capacity utilization to geographic trade flows, and product architecture to end-use qualification cycles. Our Worldwide Modified Polyphenylene Ether Market research is built to support precisely that type of integrated planning.
Report Architecture: Operational Intelligence for Cross-Functional Teams
The study is designed as a working document for strategy, R&D, procurement, and commercial leadership. Its structure emphasizes actionable granularity without losing sight of market-wide dynamics. Key components include:
- Base-line and forward sizing anchored to a defined base year and a multi-year forecast window, enabling scenario modeling for capacity expansion, share-gain targets, and revenue planning.
- Segmentation frameworks that map market structure across material variants, end-use verticals, and regional demand centers, providing the analytical scaffolding needed to prioritize investments.
- Competitive profiling that examines leadership positions, portfolio differentiation, manufacturing footprints, and recent strategic activity across incumbent and specialized producers.
- Decision-support tools that translate quantitative outputs into practical templates for price-setting, inventory strategy, customer-facing positioning, and partnership evaluation.
The objective is not simply to describe the market, but to equip teams with the logic required to test assumptions. Readers will find coverage that helps answer questions such as where growth is concentrated by application class, how material blends compete on property-performance and cost, which geographic corridors carry the highest structural demand intensity, and how recent production and product announcements are reshaping competitive momentum.
Segment Intelligence: Blends, Applications, and Geographic Drivers at a Glance
MPPE’s market structure is defined by how different formulation classes align with diverging performance requirements across end-use sectors. The category spans high-performance engineering blends that balance heat resistance, dimensional stability, flame retardancy, and dielectric behavior, as well as more cost-optimized architectures targeting specific processing and mechanical constraints. Understanding these trade-offs is essential for both suppliers designing next-generation grades and buyers specifying materials for qualification-critical applications.
Application-level demand is anchored by performance-driven verticals where weight reduction, thermal management, electrical insulation, and durability directly influence product architecture. The electrical and electronics sector remains a central demand pillar, driven by connectors, housings, and insulation needs that reward flame retardancy and signal-integrity characteristics. Automotive demand continues to expand alongside vehicle electrification and thermal-load complexity, with components increasingly specified for under-hood durability and impact resistance. Industrial machinery and broader healthcare and specialty applications contribute additional layers of demand, each with distinct regulatory, hygiene, and reliability considerations.
Regionally, the market reflects uneven demand endowments shaped by manufacturing density, automotive and electronics clustering, and supply-chain proximity. The analysis maps these regional dynamics in a way that highlights where volume flows are concentrated and where tariff, logistics, and feedstock considerations influence sourcing strategies. Rather than offering superficial share estimates, the study provides the comparative structure needed to assess regional attractiveness for capacity deployment, distribution investment, and localized formulation strategy.
Competitive Landscape: Leaders, Differentiation, and Recent Strategic Moves
The MPPE competitive field is shaped by a small group of specialized producers with strong materials science capabilities and well-established branded product lines. The sector exhibits a meaningfully concentrated structure, where leading participants command significant share and shape pricing norms through scale, formulation IP, and application engineering support. Concentration levels in the report underscore the importance of understanding not just who the major players are, but how they compete on grade breadth, regional service, sustainability positioning, and customer qualification ecosystems.
SABIC remains a prominent participant through its NORYL™ resin platform, which is engineered for high heat resistance, dimensional stability, and flame retardancy across automotive, electrical, and electronics use cases. Asahi Kasei competes through its XYRON™ MPPE portfolio, emphasizing low dielectric constant, high rigidity, and chemical resistance for connectors, automotive components, and healthcare devices. Mitsubishi Gas Chemical contributes PPE-based resins under the Xyrol™ brand, with grades oriented toward electrical insulation, plumbing, and industrial machinery applications where hydrolysis resistance is a key differentiator. Sumitomo Chemical supplies modified PPE compounds tailored for high-heat environments in automotive under-hood parts and electronic housings, with a focus on impact strength and processability.
Recent developments illustrate how incumbents are translating technical capability into market momentum. In October 2024, SABIC introduced a NORYL™ PPE+PS resin with 50% recycled content developed for sustainable electronics housings, targeting UL94 V0 flame retardancy. That launch signals a direct link between sustainability messaging, regulatory preparedness, and performance qualification. In June 2024, Asahi Kasei expanded XYRON™ MPPE production capacity by 20% at its Nobeoka plant to serve rising demand in EV battery components, reflecting the strategic importance of electrification-linked applications in capacity planning.
These actions are not isolated product updates; they are indicators of competitive doctrine. They show how material suppliers are aligning portfolios with electrification, regulatory compliance, and sustainability expectations while protecting margins through differentiated grades and targeted capacity moves.
Industry Dynamics: Feedstock Volatility, Regulatory Reformulation, and Trade Friction
The MPPE market does not develop in a vacuum. Several concurrent dynamics are reshaping cost structures, qualification timelines, and sourcing logic. Feedstock volatility is a central concern, with phenol spot prices rising 15% to $1,450/MT in Q4 2024 due to supply disruptions across Asia-Pacific, a key feedstock pathway for PPE synthesis. At the same time, styrene monomer prices increased 12% to $1,120/MT in Asia during October 2024, driven by naphtha cost increases. These shifts directly influence economics for MPPE/PS blends and reinforce the need for robust hedging, grade substitution planning, and procurement flexibility.
Regulatory pressure is also redefining formulation strategy. EU REACH Annex XVII restrictions on certain flame retardants in PPE compounds require reformulation for electrical applications to remain compliant by 2025. This creates a compliance deadline that affects product qualification cycles, supplier selection, and time-to-market for updated grades. In parallel, trade policy continues to alter regional cost-benefit calculations. US Section 301 tariffs on Chinese PPE imports increased to 25% effective September 2024, with implications for North American supply chains and sourcing diversification plans.
Together, these dynamics create a market where cost, compliance, and continuity intersect. Buyers and suppliers alike must consider not only baseline demand growth but also sensitivity to raw material pricing, availability of compliant formulations, and exposure to tariff-affected trade corridors. The research connects these forces to the broader market model so that planners can evaluate risk-adjusted scenarios rather than assume static operating conditions.
Strategic Implications for 2026 Decision-Making
For organizations operating in or adjacent to the MPPE ecosystem, the 2026 outlook is not merely a forecast year; it is a planning pivot point. The period ahead rewards firms that can align material strategy with application roadmaps, anticipate feedstock and tariff exposure, and convert sustainability and regulatory requirements into competitive advantage rather than compliance cost.
Several strategic questions become especially salient:
- Where should capacity and formulation investment be concentrated to align with long-dated demand drivers in electrification, electronics miniaturization, and specialty industrial use?
- How can procurement and R&D coordinate to manage blended-material economics when feedstock prices and trade costs fluctuate?
- Which application segments offer the strongest combination of performance premium and qualification stability for share-gain initiatives?
- How can companies position around sustainability attributes, such as recycled content and reformulation readiness, while meeting electrical and thermal specifications?
- What regional sourcing adjustments are required to hedge against tariff exposure and feedstock disruption risk?
The answers depend on reliable segmentation logic, credible competitive context, and scenario-ready sizing. That is precisely where the full study delivers additional value, providing the depth needed to translate high-level growth signals into business-unit action.
Why This Research Matters Now
A 6.0% CAGR through 2032 indicates that MPPE is not a static niche material but a growth-attractive engineering polymer with expanding relevance across multiple high-value sectors. However, growth alone does not guarantee profitability or share gains. Success will depend on how well organizations anticipate feedstock volatility, reformulate around regulatory constraints, align capacity with application demand, and navigate concentrated competition.
Polyphenylene Ether (PPE) Market
PW Consulting’s Worldwide Modified Polyphenylene Ether Market research is structured to support that level of strategic clarity. It combines market sizing, segmentation, competitive profiling, and industry dynamics into a coherent framework that can be used for investment appraisal, product roadmap prioritization, sourcing policy, and risk assessment. The result is a reference point for teams that need to move from general market awareness to specific, defensible planning assumptions.
Worldwide Modified Polyphenylene Ether (MPPE) Market
To access the full segmentation detail, competitive benchmarks, scenario inputs, and region- and application-level intelligence, request the complete report through our official market research page. The macro trajectory and industry signals outlined here establish the strategic context; the full study provides the operational detail required to convert that context into decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Modified Polyphenylene Ether (MPPE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Plant Sterols Market Hits $1.25B in 2025, Projected to Reach $2.32B by 2032 at 9.24% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Growth Cycle: Strategic Intelligence for the Worldwide Plant Sterols and Esters Market (2026–2032)
Executive Overview
The global market for plant sterols and esters is entering a decisive growth phase, driven by converging consumer health trends, regulatory stabilization, and supply chain recalibration. As corporate strategy teams finalize their post-2025 investment roadmaps, understanding the structural shifts within this sector is no longer optional—it is a prerequisite for capital allocation, product positioning, and regional entry timing. This analysis introduces our latest comprehensive study, Worldwide Plant Sterols and Esters Market, which maps the trajectory from the 2020 historical baseline through the 2026–2032 forecast horizon with unprecedented granularity.
Over the past half-decade, the sector has demonstrated remarkable resilience and expansion. Market valuation progressed from approximately USD 802.15 million in 2020 to an estimated USD 1,247.69 million in 2025, reflecting a compound trajectory shaped by rising demand for cardiovascular wellness solutions and functional food fortification. Looking ahead, the forecast window projects a sustained expansion reaching USD 1,435.08 million in 2026, before accelerating through the late forecast period to culminate at USD 2,316.22 million by 2032. These figures anchor a forecast compound annual growth rate of 9.24 percent, signaling that the industry is transitioning from a mature niche to a structurally scalable value chain. The strategic implication is clear: scale economics, formulation agility, and regional compliance literacy will separate market leaders from followers over the next seven years.
Market Architecture and Growth Vectors
The market's expansion is not uniform; it is structured around distinct product architectures, delivery formats, and application ecosystems. Plant sterol esters currently command a dominant share of the form landscape, reflecting their superior bioavailability and ease of integration into lipid-based matrices. Free sterols maintain a meaningful secondary position, often favored in specialized nutraceutical and pharmaceutical formulations where purity profiles and processing constraints dictate alternative delivery routes. At the molecular level, the phytosterol portfolio is anchored by sitosterol, supported by campesterol and stigmasterol, with other phytosterols rounding out specialized high-purity applications. This compositional hierarchy influences everything from extraction economics to end-market claim substantiation.
Applications span a diversified matrix of consumer and clinical use cases. Food and beverage fortification remains the primary demand engine, leveraging heart health positioning within spreads, dairy alternatives, and fortified beverages. Dietary supplements represent a parallel growth conduit, where standardized extracts align with consumer self-care routines and clinical-grade transparency expectations. Pharmaceuticals and cosmetics constitute smaller but strategically important segments, where sterol derivatives serve targeted therapeutic pathways and premium personal care formulations respectively. Each application vertical carries distinct regulatory thresholds, customer procurement cycles, and margin structures, requiring differentiated go-to-market strategies.
Geographically, the market exhibits mature demand centers alongside high-potential emerging corridors. Demand concentration reflects long-standing nutritional intervention adoption patterns in Europe and North America, while Asia Pacific continues to expand its footprint through rising health-conscious consumption and localized manufacturing investments. Latin America and the Middle East and Africa represent smaller but increasingly relevant pathways, shaped by import dynamics, regulatory evolution, and cross-border supply relationships. The interplay between these regional demand profiles and feedstock availability will define both pricing power and distribution agility across the forecast period.
Competitive Landscape: Positioning, Moves, and Strategic Implications
The competitive environment is characterized by a concentrated core of established ingredient suppliers, each leveraging brand equity, formulation expertise, and supply chain scale to defend share while pursuing targeted expansion. Industry leadership is visibly consolidated, with the top three enterprises accounting for a substantial portion of total revenue and the top five extending that influence further. This consolidation underscores the strategic importance of manufacturing capability, regulatory credentialing, and application-specific technical support as durable competitive moats.
BASF Personal Care maintains a prominent position through its CardioAid brand, delivering plant sterols and sterol esters derived from vegetable oils for functional foods, supplements, and cosmetics. The company's June 2024 non-GMO certification for its CardioAid plant sterol esters line signals a deliberate response to clean-label demand and regulatory clarity requirements, reinforcing its relevance for manufacturers seeking verified ingredient integrity. Raisio Plc continues to lead in the plant stanol ester segment through its Benecol platform, targeting cholesterol-lowering margarines, spreads, and yogurts. Its October 2024 launch of new Benecol yogurts with enhanced bioavailability demonstrates a product-level push to improve functional efficacy and consumer acceptance in European markets, reinforcing brand-level differentiation through formulation science.
Archer Daniels Midland (ADM) operates as a major North American ingredient supplier, manufacturing plant sterols and esters from soy and other vegetable oil sources for food fortification and nutraceutical applications. Its March 2024 capacity expansion at the Decatur facility, increasing production capability by 20 percent, reflects a direct response to regional demand momentum and underscores the strategic value of domestic manufacturing in navigating trade complexity. Cargill complements this landscape by providing plant sterol esters for dairy, beverages, and bakery applications, with a clear emphasis on heart health claims and formulation compatibility. Veratech Fine Chemical specializes in high-purity beta-sitosterol and plant sterol esters for pharmaceutical and dietary supplement applications, occupying a precision-oriented niche that rewards technical consistency and specification control.
Worldwide Plant Sterols and Esters Market
Phytoene and Koninklijke DSM N.V. extend the competitive field across Asian sourcing dynamics and broad nutritional product portfolios respectively. Phytoene's production of plant sterols from pine and vegetable sources supports global food and pharmaceutical markets, while DSM's offerings target cardiovascular health within nutritional products, illustrating how feedstock versatility and end-use positioning can shape competitive advantage across different market tiers. Together, these players illustrate that leadership in this sector is increasingly defined by application engineering, regulatory readiness, and the ability to match ingredient specifications with claim-substantiated product architectures.
Forces Reshaping the Trajectory: Feedstock, Regulation, and Trade Dynamics
Strategic planning for the 2026–2032 window requires a clear view of the external forces that will modulate supply economics, claim substantiation pathways, and market accessibility. Three structural dynamics stand out as particularly consequential.
Raw material economics remain a central lever. Vegetable oil prices, the primary feedstock basis for plant sterol extraction, rose 8 percent year-over-year to approximately USD 1,200 per metric ton in the fourth quarter of 2025, reflecting palm oil supply constraints and broader commodity pressure. This feedstock trajectory influences extraction cost structures, formulation pricing strategies, and supplier negotiation leverage. Companies reliant on single-commodity sourcing will need to assess diversification pathways, contractual hedging mechanisms, and processing efficiency upgrades to protect margin integrity.
Worldwide ¦Â-Sitosterol Market
Regulatory frameworks continue to define the boundaries of commercialization. In Europe, EU Regulation (EC) No 1924/2006 maintains a daily intake range of 1.5 to 3 grams for cholesterol reduction claims, a parameter that remained unchanged through 2025. This stability provides a predictable compliance environment for European product developers, but it also sets a firm ceiling on claim architectures and serving-size design. In the United States, the FDA reaffirmed GRAS status for plant sterol esters up to 3.3 grams per day in conventional foods through its 2024 docket, offering manufacturers a clarified pathway for ingredient integration without sacrificing functional positioning. These regulatory baselines shape formulation ceilings, labeling strategies, and the comparative advantage of regional market entry.
Trade policy introduces additional complexity. US-China tariffs on vegetable oil derivatives increased import duties on plant sterols to 25 percent effective January 2025, altering cost competitiveness for cross-border ingredient flows and potentially accelerating regional sourcing realignments. For multinational suppliers and buyers alike, this shift increases the strategic value of localized production footprints, tariff-optimized logistics, and dual-supply resilience. The intersection of feed cost volatility, regulatory ceilings, and tariff-driven cost differentials means that pricing models, country prioritization, and manufacturing geography will become more tightly coupled over the forecast period.
What the Report Delivers: An Operational Intelligence Toolkit
This study is structured not merely as a data repository but as a decision-support instrument designed for cross-functional deployment. It maps historical performance from 2020 through 2025, establishes the 2026 baseline, and extends the forecast through 2032 with a clear growth pathway. Beyond aggregate market sizing, the report dissects the market by region, product type, form, and application, enabling stakeholders to identify where growth concentrates, where competitive intensity is highest, and where entry or expansion can be timed for maximum impact.
The segmentation framework provides actionable visibility into the relative scale and trajectory of each market pillar, allowing strategy, finance, and R&D teams to align product pipelines with addressable demand. The competitive intelligence module profiles leading manufacturers, their geographic bases, brand positions, and technical capabilities, while also documenting recent developments that signal strategic intent—product launches, certifications, and capacity expansions that directly affect supply availability and claim credibility. These developments are analyzed not in isolation but as indicators of broader market direction, including where incumbents are investing to protect share and where whitespace may be emerging.
In addition, the report integrates contextual dynamics that influence operating conditions, including feedstock price movements, regulatory claim parameters, and trade policy shifts. By embedding these forces within the market structure, the study enables scenario-based planning around sourcing costs, regional cost competitiveness, and compliance-driven product architecture. The objective is to give executives a coherent basis for pricing strategy, regional prioritization, supplier selection, and claim-substantiated product design across the forecast horizon.
Strategic Imperatives for 2026 Decision-Makers
As the market accelerates toward its USD 2,316.22 million endpoint by 2032, several strategic imperatives come into focus. First, formulation and application strategy will increasingly determine market share. Regions, forms, and product types are not interchangeable; each carries distinct margin profiles, regulatory constraints, and customer expectations. Companies that align their ingredient portfolios with application-specific efficacy and claim substantiation will capture greater value than those competing solely on commodity pricing.
Second, supply chain architecture demands proactive redesign. With feedstock volatility, regional tariff exposure, and concentrated manufacturing capability among leading suppliers, resilience will depend on diversified sourcing, capacity flexibility, and logistics optimization. Investments in production footprint, feedstock alternatives, and supplier partnerships will translate directly into pricing stability and delivery reliability.
Third, regulatory literacy will function as a competitive differentiator. The stability of European intake thresholds and US GRAS positioning provides a workable compliance foundation, but it also requires disciplined serving-size design, label architecture, and regional product adaptation. Firms that internalize these parameters early will move faster in product development and reduce time-to-market risk.
Finally, competitive intelligence must be treated as a living input. Recent developments across major players—enhanced bioavailability launches, non-GMO certifications, and capacity expansions—reflect strategic pivots that reshape supply availability and brand positioning. Monitoring these moves and linking them to segmentation and regional dynamics will help decision-makers anticipate shifts in competitive intensity rather than react to them.
The Worldwide Plant Sterols and Esters Market study is built to support these imperatives with structured, forecast-grounded intelligence. The full report extends beyond aggregate trajectories to deliver the detailed segmentation data, competitive profiling, and contextual scenario analysis necessary for precise strategic planning. For leadership teams preparing investment cases, product roadmaps, and regional entry strategies for 2026 and beyond, the complete dataset and analytical frameworks are available through the source page, where the full intelligence package can be accessed in detail.
For detailed analysis of this topic, please visit the official page: Worldwide Plant Sterols and Esters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LAL Deficiency Market Hits $196.72M in 2025, Projects 6.25% CAGR to 2032
By pmarketresearch, 2026-09-16
Unlocking Commercial Potential in the Lysosomal Acid Lipase Deficiency Treatment Market: Strategic Intelligence for 2026 and Beyond
A Market Defined by Precision, Scarcity, and High-Value Therapeutics
The global landscape for lysosomal acid lipase deficiency (LAL-D) treatment is undergoing a structural shift, driven by the intersection of ultra-rare disease economics, advanced biologics manufacturing, and evolving reimbursement paradigms. For senior executives, investors, and strategic planners operating in specialty pharmaceuticals, metabolic disorders, or rare disease infrastructure, the next five years will reward organizations that move beyond symptomatic awareness and invest in rigorous, forward-looking intelligence. Our newly released Worldwide Lysosomal Acid Lipase Deficiency Treatment Market study delivers exactly that: a data-grounded, decision-ready blueprint tailored to 2026 planning cycles.
Worldwide Lysosomal Acid Lipase Deficiency Treatment Market
Historically, the sector has navigated the inherent tension between clinical necessity and commercial scale. LAL-D remains a profoundly rare condition, with an estimated prevalence ranging from 1:40,000 to 1:300,000 live births. This epidemiological reality has historically constrained market visibility, but it has simultaneously elevated the strategic value of accurate forecasting, optimized launch sequencing, and precision-targeted market access strategies. The market has already demonstrated steady, compounding growth over the past half-decade, reflecting earlier diagnostic interventions, expanded therapeutic indications, and the institutionalization of orphan drug frameworks across developed healthcare systems.
Looking forward, the commercial trajectory points to sustained expansion through 2032, underpinned by a robust compound annual growth rate and a clear upward revenue arc. This report captures the full historical baseline from 2020 through the base year of 2025, then projects a calibrated forecast window that maps the incremental value creation expected across 2026 and beyond. The total addressable revenue environment is positioned to climb decisively, with pathway-dependent growth accelerating as diagnostic awareness improves, referral networks mature, and specialty care delivery models adapt to the nuances of ultra-rare metabolic conditions.
Why 2026 Is a Defining Inflection Point for Strategic Planning
The 2026 horizon is not merely a numerical checkpoint; it is a structural inflection point. By this stage, several operational and regulatory tailwinds will have fully materialized, while competitive and commercial pressures will require deliberate positioning. Organizations that enter 2026 with a clear, segment-aware strategy will be better equipped to allocate R&D capital, sequence commercial launches, negotiate with payers, and manage complex supply chains tied to specialized biologics production.
This market research was engineered specifically to inform those 2026 decisions. Rather than presenting a static snapshot, it maps the causal relationships between clinical adoption patterns, regulatory milestones, reimbursement architecture, and geographic deployment of care. The study translates macro-level market behavior into actionable intelligence that can be layered into portfolio planning, pricing strategy, market access roadmaps, and partnership evaluation. Executives will find a consistent analytical thread that connects historical momentum to forward-looking opportunity, enabling scenario modeling and risk-calibrated investment choices.
For stakeholders evaluating market entry, therapeutic expansion, or infrastructure investment, the forecast window offers critical signal. Growth is not uniformly distributed; it concentrates where diagnostic pathways are mature, where specialty clinical networks are well-defined, and where reimbursement policies align with orphan drug economics. Understanding where those conditions are forming, and how quickly they are likely to consolidate, is essential for timing commercial activities and avoiding capital misallocation.
What the Report Unpacks: Structure, Scope, and Decision-Ready Intelligence
The study is built to function as an operational companion rather than a theoretical overview. It examines the LAL-D treatment ecosystem across multiple analytical dimensions, synthesizing historical performance, structural segmentation, competitive positioning, and forward-looking market mechanics. Each section is designed to support concrete corporate actions, from pipeline prioritization to commercial readiness assessments.
The core analytical framework covers the following operational pillars:
- Historical and Forecast Revenue Mapping : A continuous timeline tracing the market’s evolution from 2020 through the base year of 2025, followed by a structured forecast that extends across the medium-to-long term. The trajectory reflects compounding adoption, therapeutic penetration, and care-delivery maturation, giving leadership a reliable baseline for planning.
- Segmentation by Treatment Modality : A detailed breakdown of how therapeutic approaches are shaping revenue composition. The analysis examines the dominant role of enzyme replacement therapy within the current commercial architecture, alongside the complementary but structurally distinct segment encompassing supportive care and diagnostics. This distinction is critical for understanding how value is distributed across treatment pathways and where future expansion is most likely to occur.
- End-User and Care Delivery Dynamics : An evaluation of where treatment is administered and how care settings influence purchasing behavior, procurement cycles, and service models. The report contrasts the central role of hospitals and specialty clinics with the growing relevance of home care pathways, highlighting how decentralization, patient convenience, and clinical monitoring protocols are reshaping demand patterns.
- Geographic Commercial Architecture : A regional analysis that examines how established markets, emerging care ecosystems, and localized reimbursement environments contribute to overall market behavior. The study identifies where mature demand centers are positioned and where infrastructure development is likely to drive incremental opportunity, without relying on simplified regional assumptions.
- Competitive Dynamics and Strategic Positioning : A focused review of the companies shaping the market, including their product pipelines, regulatory leverage, manufacturing footprint, and commercial execution strategies. The analysis connects corporate positioning to broader market structure, helping stakeholders assess concentration, competitive vulnerability, and partnership opportunity.
- Regulatory, Pricing, and Access Context : A contextualized examination of the policies and economic realities that influence market behavior, including orphan drug exclusivity, priority review pathways, pricing benchmarks, and reimbursement constraints. These factors are woven into the broader market narrative to show how policy architecture directly shapes commercial viability and expansion timelines.
This multi-layered structure ensures that decision-makers can move from high-level market direction to the specific operational considerations that affect execution. The report is designed to feed directly into strategy workshops, investment memos, and cross-functional planning processes.
Competitive Architecture: Concentration, Differentiation, and Strategic Implications
The LAL-D treatment market operates within a highly concentrated competitive environment. Such concentration carries both advantages and risks for organizations navigating the space. It signals the presence of dominant incumbents with established regulatory and commercial moats, while simultaneously creating strategic openings for differentiated entrants, collaboration models, and adjacent capability expansion.
The industry context notes underscore how regulatory milestones, pricing architecture, and manufacturing complexity collectively define competitive positioning. For example, the only FDA- and EMA-approved enzyme replacement therapy for LAL-D in both pediatric and adult populations has benefited from orphan drug designation, priority review, and multi-year market exclusivity. These regulatory mechanisms have shaped the company’s ability to establish clinical standards, negotiate reimbursement frameworks, and anchor a long-term revenue model. At the same time, the high annual treatment cost associated with this therapy illustrates how orphan drug economics can support premium pricing, but also intensify payer scrutiny and market access complexity.
From a manufacturing standpoint, the production process introduces a distinctive cost and supply-chain profile. Sebelipase alfa is generated through a proprietary platform that relies on egg-laying hens, making avian cell culture a defining operational variable. For competitors, partners, and infrastructure investors, this detail is strategically significant: it influences cost structure, scalability considerations, quality control requirements, and the broader economics of supply continuity. Understanding how manufacturing complexity interacts with pricing power and market access is essential for evaluating long-term competitiveness in this segment.
The market concentration profile reinforces the need for strategic clarity. A small number of firms command a substantial share of total market value, reflecting the reality that ultra-rare disease markets often consolidate around approved biologics with strong regulatory and clinical differentiation. This structure tends to elevate the importance of commercial execution, stakeholder engagement, and lifecycle management, while reducing the likelihood of rapid, undifferentiated market fragmentation.
Market Dynamics: Regulation, Pricing, Diagnostics, and Access as Commercial Levers
The growth trajectory of LAL-D treatment does not emerge in isolation. It is shaped by interacting forces that span regulatory policy, therapeutic pricing, diagnostic efficiency, and healthcare delivery design. This study treats those forces as operational levers rather than background context, mapping how they influence adoption speed, revenue realization, and competitive resilience.
Regulatory frameworks have played a decisive role in establishing the commercial foundation for LAL-D therapeutics. Orphan drug designations, priority review pathways, and multi-year exclusivity mechanisms have collectively supported product development incentives and helped secure market positioning for approved therapies. These mechanisms also affect how new entrants evaluate development risk, how payers anticipate long-term cost exposure, and how manufacturers plan lifecycle strategies. The study examines how these regulatory dynamics interact with broader market behavior and what they imply for future competitive maneuvering.
Pricing and reimbursement architecture is equally central to market outcomes. In ultra-rare disease settings, high per-patient treatment costs are often intrinsic to the economics of specialized biologics and limited patient populations. The report contextualizes these cost structures against reimbursement realities, showing how access strategies, payer negotiations, and health economic evaluations influence the speed and breadth of therapeutic adoption. For commercial leaders, the underlying question is not simply whether pricing is viable, but how pricing interacts with market penetration, geographic variability, and long-term sustainability.
Diagnostics and disease awareness represent another critical dynamic. Because LAL-D is an ultra-rare condition, earlier and more reliable identification directly affects treatment volumes and patient pathways. Improvements in diagnostic capability, referral practices, and clinical recognition can expand the realized market far more quickly than macro-level population statistics would suggest. The report addresses how diagnostic momentum interacts with care delivery, specialty clinic engagement, and downstream demand patterns, helping stakeholders understand where adoption acceleration is most likely to originate.
Taken together, these dynamics form a commercial environment that rewards precision. Organizations that can align therapeutic positioning with payer expectations, adapt to care-setting evolution, and anticipate regulatory or access shifts will be better positioned to convert market growth into durable value.
How to Use This Study for 2026 Decision-Making
This report is intended to support a range of strategic use cases. It can inform pipeline prioritization, support market access planning, guide partnership and licensing evaluations, and strengthen competitive benchmarking. The study’s structure allows leadership teams to isolate the dimensions most relevant to their immediate decisions while still benefiting from the broader market context.
For commercial and market access teams, the segmentation and regional architecture provide a basis for evaluating where demand is expanding and how care settings are evolving. For R&D and lifecycle teams, the treatment modality analysis and competitive framework offer perspective on differentiation opportunities and long-term positioning. For executive planning and investor relations, the historical-to-forecast trajectory delivers a credible growth narrative grounded in observable market behavior rather than speculative framing.
Worldwide Refsum Disease Treatment Market
In every case, the objective is the same: to move from high-level awareness to executable strategy. The study gives decision-makers the structure needed to evaluate opportunity, manage risk, and sequence action in a market where timing and precision matter.
Final Thought: Strategic Clarity in a High-Value, Low-Volume Market
The Worldwide Lysosomal Acid Lipase Deficiency Treatment Market is defined by a distinctive paradox: a small patient population, but a disproportionately large strategic footprint. That footprint is shaped by specialized therapeutics, concentrated competition, regulatory privilege, complex manufacturing, and evolving care pathways. In such a market, general assessments are insufficient. Organizations need detailed, forward-looking intelligence that connects market structure to commercial execution.
This study is designed to deliver that intelligence for 2026 and the years that follow. It maps the forces that are expanding the market, the structures that are concentrating value, and the dynamics that will determine which organizations capture sustainable advantage. The full depth of segmentation analysis, competitive profiling, and forecast modeling is intentionally structured to support rigorous internal planning and targeted strategic action. For leaders who want to move beyond surface-level sentiment and build decisions on verified, actionable market intelligence, the complete report provides the necessary foundation.
For detailed analysis of this topic, please visit the official page: Worldwide Lysosomal Acid Lipase Deficiency Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Racing Slicks Market Hits $1.2B in 2025, Projected to Reach $1.9B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Decision-Maker: Navigating the Global Automotive Racing Slicks Market
The automotive racing slicks market stands at a critical inflection point heading into mid-decade. As motorsport ecosystems worldwide recalibrate around performance benchmarks, sustainability mandates, and evolving governance structures, the tires that define grip, consistency, and strategic advantage on the track are experiencing a structural transformation. This comprehensive market research publication, anchored in validated historical data from 2020 through the base year of 2025 and projected across the 2026 through 2032 forecast horizon, delivers the kind of granular, decision-ready intelligence that strategic planners, procurement directors, and competitive intelligence teams require to anticipate shifts rather than merely react to them.
For organizations operating in or adjacent to professional motorsport, grassroots racing series, and high-performance track ecosystems, the trajectory of this market is not a passive backdrop—it is a direct input into product development roadmaps, supply chain positioning, partnership strategies, and capital allocation. The purpose of this overview is to preview the analytical architecture, competitive intelligence framework, and operational insights embedded within the full Worldwide Automotive Racing Slicks Market study, while deliberately reserving the deepest segment-level breakdowns, compound-type performance mapping, and application-specific revenue modeling for the complete report.
Market Trajectory and Forecast Architecture: What the Macro Data Reveals
The historical record from 2020 through 2025 establishes a clear growth narrative. Revenue across the global automotive racing slicks market expanded from approximately 845 million USD in 2020 to an estimated 1,208 million USD by the 2025 base year, reflecting sustained demand across professional circuits, amateur competition, and enthusiast track-day segments. The momentum carries into the forecast window, with 2026 projections placing the market at roughly 1,238 million USD before ascending toward a 1,942 million USD endpoint by 2032. The compound annual growth rate of 7.02 percent over the 2026 to 2032 period signals a market that is outgrowing legacy assumptions and responding to structural drivers: expanded series participation, renewed investment in prototype and GT racing categories, and the gradual professionalization of club-level competition environments.
Worldwide Automotive Racing Slicks Market
It is important to note that the forecast model does not treat growth as a uniform wave. Regional demand patterns, compound-type preference cycles, and application-driven purchasing behaviors diverge meaningfully across the projection window. The full report disentangles these layers with explicit segment breakdowns that allow buyers to isolate the revenue pools most relevant to their operational footprint. Rather than presenting a single headline figure, the study maps how different geographic corridors, material formulations, and usage categories contribute to the aggregate trajectory, enabling executives to benchmark their own portfolio exposure against the broader ecosystem.
Inside the Report: Operational Content Designed for Strategic Execution
A market study earns its keep when it converts macro trends into actionable reference points. The Worldwide Automotive Racing Slicks Market research is structured to serve precisely that function. Across its chapters, the publication integrates demand-side analysis, supply-side dynamics, pricing architecture, regulatory and sustainability influences, and competitive positioning into a unified analytical framework. The goal is to give strategists, product managers, and commercial leaders a document they can circulate across functions without requiring additional synthesis.
The report opens with a methodology and scope definition that clarifies data sources, modeling assumptions, and coverage boundaries, ensuring that every figure cited can be traced to a defined analytical logic. From there, the narrative moves into historical performance evaluation, examining how revenue evolution, volume patterns, and pricing behavior have shifted in response to series calendar changes, tire specification mandates, raw material cost pressures, and competitive product launches. The forecast section translates these historical lessons into forward-looking revenue pathways, distinguishing between base-case projections and sensitivity considerations tied to macroeconomic input volatility and motorsport governance shifts.
Beyond aggregate numbers, the study dedicates substantial attention to structural drivers. Readers will find analysis of how compound formulation strategies—spanning softer, medium, and harder material profiles—align with different performance requirements, track temperatures, and competition durations. The application dimension is explored in parallel, contrasting the procurement logic of international professional racing series with the price-sensitive, durability-oriented purchasing patterns of club competitors and private track-day users. Regional dynamics are assessed through the lens of series concentration, manufacturing proximity, distribution infrastructure, and local regulatory expectations, allowing commercial teams to identify where demand is consolidating and where underserved corridors may present expansion opportunities.
Worldwide Automotive Tire Socks Market
A dedicated competitive landscape chapter profiles the principal manufacturers shaping the market, evaluating their technical portfolios, series affiliations, geographic reach, and strategic orientation. This section is complemented by an inventory of recent developments—official tire nominations, partnership renewals, product line extensions, and supply commitments—that illustrate how incumbents and emerging players are positioning themselves for the 2026 season and beyond. The report also integrates an assessment of raw material and sustainability dynamics, including the implications of polymer and carbon black price volatility, the logistical complexity of high-performance compound procurement, and the increasing emphasis on renewable and recycled content in motorsport tire architectures. These factors are not treated as peripheral footnotes; they are mapped directly to margin pressure points, development cycle risk, and long-term brand positioning.
Competitive Landscape: Positioning, Partnerships, and the 2026 Season Reset
The racing slicks market is characterized by a concentrated core of globally recognized tire manufacturers, reinforced by regional specialists and licensing arrangements that extend heritage product lines into modern competition formats. The combined market footprint of the top three companies reflects a substantial share of total revenue, while the leading five firms collectively account for an even larger portion of the market. This concentration does not imply stagnation; rather, it frames a competitive environment in which differentiation is achieved through compound technology, series-specific homologation, supply reliability, and strategic partnerships with racing organizations.
Michelin continues to anchor its motorsport presence through high-performance radial racing slicks, with endurance programs and premier categories benefiting from compound architectures that increasingly incorporate renewable and recycled material content. The company's broader Pilot Sport lineage underscores a strategy in which motorsport-derived technology informs high-performance road and track applications, creating brand equity that extends beyond the circuit. Pirelli has moved to deepen its series-level commitments, including a dedicated racing slick program for major North American GT machinery beginning in 2026, reflecting an approach that pairs homologation precision with technology transfer from GT and high-performance racing applications. Yokohama has reinforced its position through spec-tire partnerships in Porsche-affiliated regional series, with its circuit-focused racing slicks serving as the specified competition rubber for multiple seasons, a model that ties product selection directly to series identity and driver familiarity.
Bridgestone contributes to the market through high-performance compounds and select automotive motorsport applications, extending its broader tire technology into dry-track racing contexts alongside motorcycle racing programs. Goodyear maintains a wide competition tire portfolio with strong relevance to oval and circuit formats, emphasizing grip consistency and durability across varied racing disciplines. Within the Michelin Group ecosystem, BFGoodrich continues to draw on its off-road and rally heritage while supplying slicks and competition tires suitable for a range of automotive racing formats. Hoosier Racing Tire remains a defining presence in domestic circuit racing, offering extensive compound and size options across bias ply and radial constructions, and recently expanded its dedicated radial slick line to address specific junior formula and sports racing platforms. American Racer brings decades of specialization in oval and circuit racing tires, while Nova Motorsport, operating under its Avon Motorsport licensing arrangement, supplies radial and historic slicks to competition and specialist motorsport segments globally. Rubbercraft Tire represents a newer manufacturing presence from China, building out high-quality racing slick offerings for diverse motorsport applications since 2018 and illustrating the broader geographic expansion of capable production capacity.
Recent developments underscore how quickly partnership and product signals can reshape competitive expectations. One major manufacturer was named the official tire supplier for a prominent North American Porsche racing cup series starting in 2026, with competition cars set to run on newly developed dedicated racing slicks. Another incumbent secured a renewed official partnership for a multi-regional Porsche sprint challenge program, locking in spec tire usage for the 2026 season. A separate commitment extended slick tire supply to an electric car racing class that uses slicks as standard competition rubber, signaling that electrification pathways are not bypassing slick tire demand but reshaping its application context. In parallel, a domestic specialist introduced a dedicated line of smaller-radial slicks in new sizes and compounds tailored to junior formula and sports racing cars, expanding the performance envelope for entry-level and mid-tier competition categories. Each of these events is examined in the full report with attention to strategic intent, series implications, and the likely ripple effects on competing manufacturers' portfolio and pricing decisions.
Market Dynamics: Raw Material Pressure, Sustainability Mandates, and the Cost-of-Performance Equation
The racing slicks market does not evolve in a vacuum. Production economics are directly exposed to volatility in natural rubber, synthetic rubber, and carbon black pricing, with fluctuations in essential rubber polymers and procurement logistics influencing both development timelines and high-performance compound costs. These input dynamics affect margins and can accelerate or delay new compound introductions, particularly for manufacturers balancing series-specific homologation requirements with broader commercial tire portfolios. The report integrates these considerations into its segment and dynamics analysis, helping commercial teams anticipate how cost structures may shift and where supply chain resilience becomes a competitive advantage.
Sustainability is moving from an aspirational narrative to an operational requirement. Several leading manufacturers are already incorporating meaningful ratios of renewable and recycled raw materials into select racing slick architectures, with endurance Hypercar-oriented compounds reflecting some of the most visible progress. Across the industry, there is an increasing focus on aligning tire material strategies with broader motorsport environmental initiatives, a trend that is likely to influence specification decisions, sponsor expectations, and series-level procurement criteria over the forecast period. The full study examines how these sustainability pressures interact with performance demands, how manufacturers are communicating material advancements, and what the trajectory implies for competitive differentiation in a market where grip, wear, and consistency remain the ultimate arbiters of success.
Why This Research Matters for 2026 Strategic Decisions
For organizations making decisions in 2026, the Worldwide Automotive Racing Slicks Market study provides a structured basis for answering questions that are otherwise difficult to resolve with fragmented public information. Which application segments are generating the most resilient revenue growth, and where do pricing and volume dynamics diverge from headline trends? How are compound-type preferences evolving across professional racing series versus amateur and club environments? Which regional corridors present the strongest alignment with existing distribution capabilities, and where do concentration patterns suggest entry barriers or partnership opportunities? How are recent series nominations, spec-tire renewals, and electric racing commitments likely to influence demand allocation over the next few seasons? And how should procurement and product teams factor raw material volatility and sustainability-driven material shifts into forecasting and inventory strategy?
The complete report answers these questions with segment-level detail, company-specific competitive profiles, development-event tracking, and forecast modeling that can be mapped directly onto internal planning assumptions. It is designed for strategic planners evaluating market entry or portfolio expansion, product managers assessing compound and size-line prioritization, commercial leaders benchmarking competitor positioning, and investment or procurement teams requiring defensible market sizing and trajectory analysis. The macro growth narrative establishes that the market is expanding at a robust pace, but the value of the study lies in the actionable segmentation, competitive intelligence, and dynamic-factor analysis that convert that headline into a practical decision framework.
Organizations that rely on aggregated estimates or series-level anecdotes risk misreading where value is being created and where competitive pressure is intensifying. This research closes that gap by providing a comprehensive, data-grounded view of the automotive racing slicks market across the historical period, the 2026 base year, and the 2032 forecast horizon. To access the full segment breakdowns, company profiles, regional demand mapping, compound-type analysis, application-level revenue modeling, and detailed recent-development assessment, request the complete Worldwide Automotive Racing Slicks Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Racing Slicks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com