

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Titanium Chloride Market to Hit $21.5B by 2032, Growing at 4.8% CAGR

Strategic Intelligence for the Titanium Chloride Market: Navigating Growth, Volatility, and Competitive Shifts Through 2032
Executive Overview
The global titanium chloride market stands at a critical inflection point. As the foundational intermediate for titanium sponge production, chloride-process titanium dioxide, and advanced Ziegler-Natta catalysts, titanium tetrachloride (TiCl4) demand is tightly coupled to downstream materials cycles, regulatory evolution, and regional capacity restructuring. Our latest Worldwide Titanium Chloride Market research report delivers a comprehensive, data-grounded assessment designed specifically for executive decision-makers navigating the 2026–2032 horizon.
Between 2020 and 2025, the market expanded from approximately 12,150 million USD to 15,510 million USD, reflecting sustained industrial demand and incremental capacity additions across key producing regions. The trajectory is projected to continue through the forecast window, with the market expected to reach roughly 21,534 million USD by 2032 at a compound annual growth rate of 4.8 percent. These macro indicators are more than backward-looking statistics; they form the analytical backbone of a deeper investigation into supply chain resilience, pricing dynamics, competitive positioning, and regional risk exposure. This article outlines the strategic architecture of the research and explains why it should serve as a core input for capital allocation, procurement planning, and competitive strategy in 2026.
Worldwide Titanium Chloride Market
Zirconium Oxychloride Market
Why This Research Matters for 2026 Decision-Making
Market intelligence loses value when it remains abstract. The strategic function of this report is to translate market-scale trends into operational foresight. Several structural forces are actively reshaping how titanium chloride is produced, priced, and distributed, and each carries direct implications for procurement leaders, plant planners, and corporate development teams.
- Capacity additions in Asia have altered the regional supply baseline, while environmental enforcement and feedstock volatility continue to influence marginal production economics.
- Downstream titanium dioxide manufacturers are adjusting procurement strategies in response to chloride-process technology investments, export trade measures, and shifting feedstock contracts.
- Titanium sponge producers face a high input intensity relationship with TiCl4, meaning small changes in intermediate availability or pricing can cascade into broader cost structures.
- Maintenance cycles, logistics constraints, and energy costs are increasingly interacting to create short-term supply tightening, particularly in higher-cost operating environments.
The 2026 edition of this report is structured to help organizations separate signal from noise. Rather than presenting a static snapshot, the analysis integrates historical trajectory, forward projections, and company-level activity to support scenario planning. Executives evaluating new production investments, long-term offtake agreements, or market entry strategies can use the research to benchmark margin exposure, assess competitive moats, and identify where operational flexibility will matter most.
Market Trajectory and Structural Dynamics
The headline growth figures frame an industry that is expanding, but not uniformly. Over the historical period, revenue progression reflects both volume growth and shifting value capture across grades, end uses, and geographies. The forecast period through 2032 indicates continuing expansion, though the pace will be influenced by downstream demand elasticity, regulatory pressure on pollution-intensive processes, and the economics of chloride versus alternative production routes.
One of the most operationally relevant themes is the interaction between raw material costs and intermediate pricing. Titanium slag availability, chlorine gas pricing, and procurement patterns for ilmenite all feed directly into TiCl4 production economics. Recent market signals show firmer input procurement by titanium dioxide producers and price levels in certain regions reaching multi-year highs, underscoring the need for scenario-based procurement strategies rather than static budgeting. At the same time, the relationship between TiCl4 consumption and downstream output remains material: titanium sponge production in major manufacturing centers typically requires substantial TiCl4 input per ton of finished metal, which amplifies the strategic importance of intermediate supply security.
Trade policy and environmental regulation add another layer of complexity. Anti-dumping measures on certain titanium dioxide imports have ripple effects across the broader titanium chemicals value chain, altering demand patterns for intermediates and influencing where capacity is most competitive. In parallel, increasingly frequent environmental inspections targeting pollution reduction continue to affect production from titanium slag-based routes in key manufacturing regions. These constraints do not merely raise compliance costs; they influence which assets can flex output quickly, which operations face downtime risk, and how regional price dispersion evolves during periods of tight supply.
The report also examines market concentration and competitive structure. The industry is not fully fragmented; a meaningful share of value is captured by firms with integrated chloride-process operations, large pigment portfolios, or dedicated titanium metal capabilities. Understanding concentration dynamics helps buyers and investors evaluate bargaining power, substitution risk, and the likelihood of supply consolidation under stress conditions.
Competitive Landscape: Who Shapes the Market and How
Competitive advantage in titanium chloride increasingly derives from integration, technology access, and geographic positioning. The strongest players typically combine intermediate production with downstream titanium dioxide or titanium metal operations, allowing them to balance merchant sales with internal consumption and to manage feedstock flexibility more effectively. The report profiles the companies that are most actively shaping supply, technology, and regional capacity trends.
- Tronox Holdings plc operates as one of the largest global suppliers of titanium chemicals, including TiCl4 and derivatives, with production tied to both merchant sales and internal use in pigments and titanium sponge. Its footprint illustrates how integrated chloride chemistry supports broader titanium product portfolios.
- The Chemours Company is a major global producer of TiCl4 as a key intermediate in chloride-process titanium dioxide production, with large-scale facilities that leverage proprietary chloride technology and broad feedstock flexibility. Operational continuity at such sites can significantly affect regional supply conditions.
- Toho Titanium Co., Ltd. produces and sells titanium tetrachloride as part of its chemicals business, supporting titanium sponge production via the Kroll process and other titanium metal products. Its role highlights the linkage between intermediate supply and advanced metal manufacturing.
- OSAKA Titanium Technologies Co., Ltd. manufactures titanium tetrachloride under strict quality control for titanium sponge and other high-purity applications, with distribution adjusted to different transport requirements. This orientation emphasizes quality and application specificity in a market where grade differentiation matters.
- Ishihara Sangyo Kaisha, Ltd. (ISK) produces titanium tetrachloride as a main raw material for chloride-process titanium dioxide manufacturing, reinforcing the strategic importance of upstream intermediates in pigment supply chains.
- LB Group (Lomon Billions) operates significant chloride-process TiO2 capacity supported by dedicated titanium tetrachloride production, including a substantial capacity addition that reflects ongoing investment in chloride-based value chains.
- Kronos Worldwide, Inc. is a leading producer of TiO2 via chloride process requiring substantial TiCl4 volumes as an intermediate, positioning the company deeply within the global titanium chemicals value chain.
- Venator Materials PLC produces titanium tetrachloride for pigments and other applications as part of its titanium dioxide operations, linking intermediate chemistry directly to pigment market strategy.
- American Elements manufactures and distributes titanium tetrachloride for bulk industrial and research use, with production supporting advanced materials applications. Its presence broadens the market beyond mainstream pigment and sponge routes.
- CITIC Titanium Industry Co., Ltd. is a Chinese producer involved in titanium tetrachloride for chloride-process TiO2, with ongoing capacity expansions in high-purity grades, illustrating continued investment in differentiated product segments.
Recent company-level and market-level developments reinforce why competitive monitoring must be continuous rather than periodic. In mid-2025, several producers faced tightening supply conditions across North America and Europe during the third quarter, driven by scheduled maintenance, elevated energy costs, and logistics disruptions. The resulting price pressure was especially pronounced in Europe, where feedstock costs and export demand compounded the impact. Those episodes demonstrate how quickly regional availability can shift even in a structurally growing market.
Operational diplomacy can be just as important as capacity. In mid-2025, regulatory developments in Mexico allowed the resumption of normal operations at a major titanium dioxide facility dependent on TiCl4 production, showing how environmental and utility constraints can temporarily reshape regional supply expectations. Meanwhile, capacity expansion announcements in China have highlighted the continued push to support chloride-process titanium dioxide demand with dedicated intermediate production. Each event alters short-term availability and influences long-term competitive positioning.
Inside the Report: What Decision-Makers Will Find
This research is designed as a decision toolkit rather than a descriptive summary. It combines quantitative market modeling with qualitative analysis of competitive behavior, regulatory exposure, and downstream demand linkages. The objective is to provide a usable framework for pricing strategy, capacity planning, supplier evaluation, and investment prioritization.
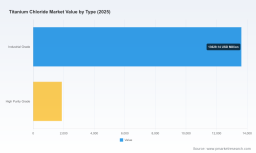
The report includes detailed historical reconstruction and forward projection, enabling readers to trace how the market evolved from 2020 through the base year and how growth is expected to unfold across the forecast window. It analyzes segmentation by region, type, and application to clarify where value is concentrated and how demand drivers differ across end markets. Rather than reducing the industry to a single average, the segmentation analysis helps identify which segments are most exposed to feedstock volatility, which rely on high-purity specifications, and which are shaped by cyclical pigment or catalyst demand.
Competitive profiling is integrated with recent developments to show not only who the major participants are, but how their recent actions affect supply conditions. The report examines operational resumption events, capacity additions, and market-wide supply tightening to help readers interpret near-term risk. It also contextualizes raw material procurement trends and regulatory actions that influence production economics, making it easier to connect external disruptions with internal planning assumptions.
A central strength of the study is its emphasis on actionable interpretation. The analysis supports questions such as:
- Where are supply constraints most likely to emerge during maintenance-heavy periods or energy-cost spikes?
- Which downstream applications create the most stable demand anchors for titanium chloride?
- How do regional trade measures alter procurement geography and supplier qualification strategies?
- What does market concentration imply for negotiation leverage, substitution options, and long-term contracting?
How to Use This Intelligence Strategically
For procurement and supply chain leaders, the report provides a basis for building more resilient TiCl4 sourcing strategies. By understanding where capacity is expanding, where environmental and energy pressures are intensifying, and how regional tightening events have unfolded, teams can structure contracts, inventory buffers, and supplier diversification plans with greater confidence. For pricing and commercial teams, the analysis helps frame negotiation positions around feedstock sensitivity, grade differentiation, and regional availability dispersion.
For strategy and corporate development teams, the research supports evaluation of market entry, partnership, and capacity investment options. Because titanium chloride sits between raw material processing and high-value downstream products, the economics of any expansion or acquisition depend heavily on integration benefits, technology access, and exposure to regulatory or trade shocks. The report’s competitive and segmentation structure helps decision-makers test whether a proposed move aligns with structural demand or merely chases cyclical pricing.
For investors and advisors, the report offers a disciplined way to assess which participants are most likely to benefit from continued chloride-process adoption, which operations face greater disruption risk, and how market concentration may shape future margin distributions. The inclusion of recent operational and market events ensures that analysis is anchored in current conditions rather than outdated assumptions.
Conclusion: Turning Market Scale into Strategic Advantage
The worldwide titanium chloride market is expanding, but growth alone does not guarantee commercial advantage. Success in 2026 and beyond will depend on how well organizations interpret the interaction of capacity dynamics, feedstock costs, regulatory pressure, trade policy, and competitive behavior. Our Worldwide Titanium Chloride Market report is built to support that interpretation with structured data, company-level intelligence, and forward-looking analysis through 2032.
This article has provided a high-level view of the strategic logic behind the research and the market forces it examines. The full study goes further, offering detailed market sizing, segmentation mechanics, competitive profiling, recent development tracking, and scenario-ready insights that cannot be fully captured in a short briefing. For teams that need to move from general awareness to specific planning parameters, the complete report is the necessary next step.
For detailed analysis of this topic, please visit the official page: Worldwide Titanium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com