

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide EV Fuses Market at $1.14 Billion in 2025, Projected $3.43 Billion by 2032

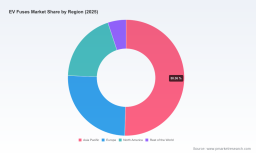
The Invisible Backbone of Electrification: Strategic Intelligence for the Global EV Fuse Market (2026-2032)
The transition to electric mobility is often measured in electrified miles, battery capacity, or charging station deployments. Yet beneath every high-voltage battery pack, power electronics assembly, and vehicle charging interface lies a critical, often overlooked component: the EV fuse. As system voltages climb, power densities increase, and safety requirements tighten, fuses have evolved from passive overcurrent devices into sophisticated, highly engineered safety nodes that determine vehicle reliability, thermal resilience, and regulatory compliance. At PW Consulting, we recognize that the EV fuse market is no longer a derivative play on electric vehicle production. It is a distinct, high-growth arena where material economics, standardization, and product architecture intersect to shape supplier positioning and OEM sourcing strategies.
Worldwide Electronic Fuse Holders Market
Our newly released Worldwide EV Fuses Market study delivers a structured, decision-ready intelligence framework for corporate planning teams, sourcing leaders, and technology strategists preparing for the 2026-2032 horizon. This article previews the strategic contours of the research, outlines the analytical architecture of the report, and explains how our findings map directly to the procurement, product development, and competitive positioning decisions that will define the next cycle of electrification.
A Market Transitioning from Niche Component to Strategic Growth Engine
Historical market data reflects the compounding effect of electrification momentum. Between 2020 and 2025, the worldwide EV fuse market expanded from approximately $385.4 million to $1,142.5 million, marking a period of accelerated adoption driven by broader passenger EV rollouts, early commercial fleet electrification, and the initial scaling of charging infrastructure. Our forecast modeling projects continued expansion through 2032, with revenue expected to reach roughly $3,425.5 million by the end of the outlook window. This trajectory corresponds to a compound annual growth rate of 16.98 percent, a pace that places EV fuses among the more dynamically expanding segments of the automotive component ecosystem.
The growth profile is not linear, nor is it uniform across product categories or end-use applications. As battery architectures evolve toward higher-voltage platforms and electrified drivetrains become standard across more vehicle classes, the fuse requirements within these systems are shifting in both quantity and technical specification. Higher nominal voltages, sustained peak current exposures, and increasingly compact packaging demand protection solutions that balance interrupting capacity, response time, space efficiency, and long-term degradation stability. The research captures these structural shifts and maps them against demand signals that extend well beyond passenger vehicle production tallies.
What the Worldwide EV Fuses Market Study Delivers
PW Consulting’s research is designed as an operational reference rather than a static market summary. The report combines quantitative modeling with qualitative industry analysis to help decision-makers translate market trajectory into sourcing, product, and investment choices. The document is organized around several interconnected analytical pillars:
- Historical baseline and forward-looking modeling: A full retrospective spanning 2020 through 2025 anchors the analysis in observed market behavior, while the 2026-2032 forecast establishes scenario-consistent revenue projections with compound annual growth rates clearly delineated for planning purposes.
- Segmentation architecture: The study breaks down the market by geography, by fuse type, and by vehicle type, giving readers a structured understanding of where demand concentrates and how different product categories contribute to overall market value without relying on fragmented headline figures.
- Competitive landscape and corporate profiling: Detailed assessments of leading manufacturers provide visibility into product portfolios, application focus, and strategic direction, helping buyers and investors evaluate capability alignment, supply resilience, and innovation roadmaps.
- Industry context and market dynamics: The report integrates external drivers—including raw material conditions, regulatory and standards frameworks, and broader electrification trends—so that market sizing is interpreted within the environment that shapes pricing, capacity planning, and specification decisions.
- Development tracking and product intelligence: Recent corporate activities, including product launches, portfolio expansions, and catalog updates, are placed in context to illustrate how incumbents and specialists are responding to technical and commercial pressure.
Structural Demand Drivers Redefining Specification and Procurement Strategy
EV fuse demand does not grow in isolation. It is tied to a set of overlapping forces that influence both the volume of components required and the performance thresholds they must meet. Three dimensions stand out in our analysis.
Voltage escalation and system architecture change
Electric vehicle platforms continue to move toward higher-voltage architectures, and protection components must keep pace with those design choices. As battery packs, inverters, and high-power distribution networks operate at elevated direct-current levels, fuses face more demanding interrupting requirements and tighter thermal margins. This environment rewards designs capable of predictable fault interruption, stable performance under repeated stress, and compatibility with the space constraints of modern power electronics packaging. The report examines how these design pressures vary by application context and what they imply for product roadmaps and qualification pathways.
Raw material exposure and cost dynamics
Material costs are an increasingly important variable in the economics of EV fuse production and procurement. Copper, a key input across EV electrical systems, has experienced pronounced price volatility in recent months, reflecting surging demand from electrified transport, renewable energy installations, and broader supply constraints. Elevated metal pricing reverberates through component bill-of-materials calculations, affecting unit economics for manufacturers and influencing sourcing negotiations for OEMs and Tier suppliers. The study places these cost dynamics within the broader segmentation discussion so that planners can assess where material exposure is most influential and how value is distributed across the market.
Standards, compliance, and qualification complexity
Protecting high-voltage EV circuits requires adherence to automotive-specific requirements in addition to general electrical standards. Components must align with expectations tied to directives and specifications such as ISO 8820, AEC-Q200, UL 248-20, and IATF 16949 for high-voltage DC applications, alongside broader IEC 60269 family requirements that address low-voltage fuse performance up to 1500 V DC and relevant semiconductor protection use cases. Compliance is not a checkbox exercise; it shapes design cycles, validation timelines, supplier qualification, and the commercial viability of alternative parts. Our analysis addresses how these standards influence market entry, product differentiation, and the competitive balance between established automotive suppliers and specialized protection-device manufacturers.
Competitive Landscape: Capability, Specialization, and Strategic Positioning
The EV fuse market is shaped by a mix of established automotive protection specialists, diversified industrial manufacturers, and regional players with deep application experience. Market concentration reflects a meaningful degree of consolidation at the top, while still leaving room for differentiated performers in niche applications, high-voltage solutions, and safety-critical pyro fuse segments. Our report profiles leading companies to clarify where competitive advantage is being built and how firms are positioning for the next phase of electrification.
Specialized automotive protection providers
Littelfuse, Inc. continues to offer a broad high-voltage automotive fuse range, including solutions engineered for EV battery packs, power distribution, and charging systems in both passenger and commercial vehicles. Eaton Corporation has strengthened its position through Bussmann-series EV fuses and pyro fuse offerings for high-voltage protection, while also expanding assembly capacity with dedicated facilities. Mersen S.A. focuses on high-performance fuses and semiconductor protection products for battery systems, inverters, and high-current applications. These manufacturers illustrate how product breadth, application understanding, and production scale combine to influence supplier relevance across multiple vehicle and infrastructure segments.
Regional strength and precision engineering
In Japan, Pacific Engineering Corporation and SOC Corporation have built long-standing roles in EV-related fuse and pyro fuse production. Pacific Engineering’s updated catalog coverage for systems above 750 VDC, through-hole PCB fuses, and pyro fuse solutions highlights the continued importance of detailed product engineering and application-specific documentation. SOC Corporation’s compact high-performance EV fuse designs, including products developed from early mass-produced EV applications, show how heritage in automotivespecific protection can translate into sustained market presence. These firms reflect a broader pattern in which regional manufacturing expertise and close alignment with OEM validation cycles support durable competitive positioning.
Safety-critical pyro solutions and broader industrial participation
Pyro fuses and related safety switches add a different dimension to the market, particularly where fault response and crash safety integration matter. Daicel Corporation and Autoliv, Inc. address high-voltage circuit protection through pyro-based safety systems, embedding protection within the broader vehicle safety architecture. Meanwhile, companies such as Bel Fuse Inc., Sensata Technologies, SCHURTER Holding AG, ABB Ltd., and Siemens AG participate across overlapping domains, from high-voltage protection and resettable or hybrid switching solutions to industrial-grade protection devices applicable to EV power systems and infrastructure. Sensata’s continued development of high-voltage protection concepts that combine fuse and contactor functionality, and SCHURTER’s introduction of ALO series fuses for high-voltage EV applications, are representative of how product definitions are expanding at the boundary between protection, switching, and system integration.
Recent developments as market signals
The report also connects recent corporate activity to the strategic themes shaping the market. Product launches and portfolio updates from 2024 through early 2026—including new high-voltage switching and protection concepts, expanded AEC-Q200 qualified fuse lineups, comprehensive global fuse portfolios for EVs and energy storage, and updated catalog coverage for higher-voltage systems—demonstrate an industry that is iterating quickly in response to voltage escalation, safety demands, and infrastructure expansion. Tracking these moves matters because product announcements often precede shifts in qualification pipelines, sourcing preferences, and competitive differentiation.
Why This Research Matters for 2026 Decision-Making
Corporate teams entering 2026 face a set of questions that are only partially answered by top-line market growth figures. Sizing tells you the scale of the opportunity; it does not tell you where value accrues, which technical pathways are becoming preferred, how material and compliance pressures affect margin structures, or how competitive dynamics will influence supply security and pricing power. The PW Consulting study is built to address those gaps.
For procurement and supply chain leaders, the report provides a structured basis for evaluating supplier capability, understanding segment-level demand distribution, and anticipating where qualification complexity or material exposure may influence sourcing strategy. For product and engineering teams, it contextualizes the technical forces that are reshaping fuse requirements in battery packs, inverters, charging systems, and commercial vehicle applications. For strategy and corporate development groups, it frames the competitive landscape in a way that clarifies where specialization, portfolio breadth, or capacity expansion is likely to create durable advantage.
Worldwide EV Fuses Market
The study is deliberately designed to support scenario-based planning. It does not reduce the market to a single narrative. Instead, it offers the segmentation logic, competitive intelligence, and external context needed to model different sourcing, development, and investment paths with greater confidence. That approach is particularly important in a market where standards, voltage regimes, and material economics are all in motion simultaneously.
Previewing the Intelligence Inside
This article provides a strategic overview of the themes and structure embedded in the full report. It is not a substitute for the underlying analysis. The complete Worldwide EV Fuses Market study contains the detailed segmentation values, regional and application breakdowns, competitive profiling, and modeled revenue projections that planning teams need for precise internal benchmarking and decision support.
Readers who require granular market splits, type-specific and vehicle-type demand distributions, regional revenue comparisons, and in-depth corporate assessments will find those elements developed in full within the published research. The report translates market trajectory into a practical intelligence asset, giving teams a clearer view of where growth is concentrated, which capabilities are becoming more valuable, and how the competitive field is evolving as electrification moves from early expansion to broader structural integration.
Looking Ahead: Protection as a Strategic Layer in Electrification
The EV fuse market will continue to grow not simply because more electric vehicles are being produced, but because the protection architecture inside those vehicles and across the charging and energy-storage ecosystem is becoming more demanding, more regulated, and more important to overall system safety and reliability. That creates a market environment in which technical differentiation, compliance maturity, and supply resilience matter as much as unit volume.
PW Consulting’s Worldwide EV Fuses Market study is intended to give decision-makers the framework they need to navigate that environment with clarity. By combining historical context, forward-looking modeling, segmentation structure, competitive profiling, and industry dynamics, the report turns a high-growth segment into an actionable strategic reference. For organizations preparing sourcing plans, product roadmaps, capacity decisions, or market-entry assessments for 2026 and beyond, the full analysis offers the depth required to move from broad market awareness to precise, evidence-based action.
For detailed analysis of this topic, please visit the official page: Worldwide EV Fuses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com