

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Veterinary API Market Hits $7.2B in 2025, Forecast 7.15% CAGR Through 2032

Navigating the Global Veterinary API Manufacturing Landscape: Strategic Imperatives for 2026 and Beyond
The global animal health industry is entering a critical inflection point. As veterinary care standards rise across both companion and livestock sectors, the demand for high-quality Active Pharmaceutical Ingredients has become a cornerstone of therapeutic innovation and supply chain resilience. For executives, investors, and supply chain strategists, understanding the trajectory of the veterinary API manufacturing market is no longer optional—it is a strategic necessity. Our newly released Worldwide Veterinary API Manufacturing Market study provides the comprehensive intelligence required to navigate this evolving terrain, with a particular focus on how macroeconomic tailwinds, regulatory shifts, and competitive realignments will shape enterprise decision-making throughout the 2026–2032 forecast horizon.
Market Trajectory and the 2026 Decision Window
The veterinary API manufacturing sector has demonstrated consistent structural growth over the past half-decade, expanding from a baseline of approximately USD 5,100 million in 2020 to an estimated USD 7,200 million in 2025. This trajectory reflects more than incremental expansion; it signals a maturing ecosystem where pharmaceutical-grade precision, regulatory compliance, and scalable production capacity are increasingly intertwined. Looking ahead, the market is projected to reach a range exceeding USD 11,600 million by the close of 2032, underpinned by a compound annual growth rate of 7.15 percent. These figures frame the 2026 decision window as a pivotal moment for capital allocation, manufacturing footprint optimization, and partnership strategy.
For corporate planners, the near-term forecast carries distinct operational implications. The 2026–2028 period is expected to sustain steady revenue progression, driven by sustained demand for anti-infective therapies, parasiticides, and biological formulations across multiple animal species. However, growth alone does not dictate strategy. The real value of forward-looking intelligence lies in identifying where capacity constraints, regulatory bottlenecks, and geographic supply dependencies will intersect with corporate objectives. Companies that align their 2026 investment pipelines with validated demand signals and supply chain risk assessments will be better positioned to capture margin resilience and market share as the cycle advances toward the end of the decade.
Veterinary Drug Market
Our analysis situates these macro trends within a broader operational context, examining how shifting procurement patterns, evolving quality standards, and geopolitical trade dynamics are altering the cost structures and lead times that define modern veterinary API procurement. The study is designed to equip decision-makers with the analytical frameworks needed to evaluate sourcing strategies, assess manufacturing partnerships, and forecast capacity requirements before market conditions tighten.
Structural Drivers Shaping the Forecast Period
Several interconnected forces are accelerating the transition from routine production to strategically calibrated manufacturing. First, the global push toward standardized animal health protocols has elevated the baseline requirement for pharmaceutical-grade consistency, pushing manufacturers to invest in advanced synthesis capabilities and rigorous quality assurance infrastructure. Second, the growing complexity of formulation requirements across species—from ruminants and poultry to companion animals—has increased the demand for specialized active ingredients that cannot be efficiently sourced through fragmented or unverified supply networks.
Third, the regulatory environment continues to evolve at a pace that directly impacts manufacturing compliance and product availability. Monitoring bodies such as the U.S. Food and Drug Administration have highlighted recurring supply disruptions in critical antimicrobial ingredients, underscoring how dependent downstream formulations remain on stable upstream production. At the same time, international standards increasingly emphasize antimicrobial stewardship, residue management, and export-quality compliance, raising the operational bar for manufacturers seeking to serve regulated markets.
Fourth, geopolitical and trade developments have introduced a new layer of cost and continuity risk. With a significant share of veterinary active ingredients historically routed through specific overseas production hubs, any shift in tariff policy, logistics friction, or export control can quickly affect landed costs and supply reliability. These dynamics are not abstract; they are actively reshaping sourcing models, prompting manufacturers and buyers alike to reassess geographic concentration, redundancy planning, and long-term contract structures.
What This Study Delivers for Enterprise Strategy
The Worldwide Veterinary API Manufacturing Market report is structured to translate high-level trends into actionable intelligence. It provides a detailed examination of market sizing, growth trajectories, and segmentation patterns across the core dimensions that matter most to manufacturing and procurement leaders. Rather than presenting isolated statistics, the study weaves together demand-side drivers, production technology pathways, and competitive positioning to show how the ecosystem functions as an integrated system.
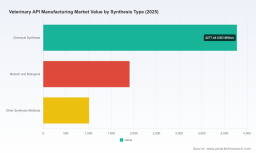
Readers will find a systematic breakdown of the principal active ingredient categories that anchor veterinary pharmaceutical portfolios, alongside an evaluation of the synthesis approaches that define production economics, scalability, and regulatory readiness. The analysis extends to regional manufacturing distribution, highlighting where production capacity is concentrated, where supply dependencies create vulnerability, and where emerging hubs are gaining relevance in global procurement strategies. By contextualizing these structural elements within the forecast period, the report enables clients to model scenarios, stress-test sourcing assumptions, and identify where strategic flexibility will yield the greatest commercial advantage.
Beyond market structure, the study incorporates a focused competitive assessment of the organizations shaping the field. This includes an evaluation of multinational animal health leaders with integrated API development capabilities, specialized manufacturers serving specific therapeutic categories, and contract development and manufacturing organizations expanding their veterinary capacity to meet global demand. The competitive lens is not limited to corporate profiles; it examines how facility investments, technology partnerships, and site acquisitions are altering supply network reliability and production readiness. Recent industry developments—including dedicated facility commissioning, strategic technology licensing agreements, and contract manufacturing site acquisitions—are analyzed as indicators of where capacity is being built, where innovation is being embedded, and where supply security is being prioritized.
To ensure operational relevance, the report also integrates key industry context across regulation, raw material availability, logistics, and trade policy. These inputs are mapped to the segments and regions they affect most, giving clients a clearer picture of the constraints and opportunities that will influence pricing, lead times, and formulation planning through 2032.
Competitive Realignment and Supply Network Resilience
The competitive landscape in veterinary API manufacturing is defined by a blend of established animal health enterprises and specialized production organizations, each pursuing distinct strategic advantages. At one end of the spectrum, global animal health leaders maintain in-house or tightly controlled API capabilities that support broad therapeutic portfolios spanning parasiticides, anti-infectives, vaccines, and biologicals for both livestock and companion animals. These organizations benefit from vertical integration, extensive regulatory experience, and the ability to align API supply with finished product pipelines.
At the same time, a robust tier of specialized manufacturers and CDMO-style operators has gained prominence by focusing on production efficiency, regulatory-grade quality systems, and flexible supply arrangements. Companies operating from established pharmaceutical manufacturing regions are expanding dedicated veterinary API capacity, investing in compliance infrastructure, and positioning themselves as reliable nodes within multinational supply chains. This specialization matters because veterinary formulations often require consistent batch quality, species-specific compliance, and the ability to support both generic and differentiated product pipelines.
Worldwide Veterinary API Manufacturing Market
Recent corporate activity reflects a clear emphasis on capacity assurance and technology access. Facility expansion and the commissioning of dedicated veterinary API production units signal growing confidence in long-term demand, while also addressing the need for modernized infrastructure that can satisfy tightening quality and sustainability expectations. In parallel, partnerships aimed at accessing advanced development platforms and the acquisition of contract manufacturing sites illustrate how organizations are fortifying supply continuity for critical farm animal and companion animal products. These moves are not isolated; they represent a broader pattern of structural reinforcement as buyers and producers alike respond to the reality that API availability can directly influence therapeutic access and commercial performance.
Navigating Concentration, Cost, and Continuity Risks
Market concentration remains an important strategic consideration. A meaningful share of revenue is held by a relatively compact group of leading participants, which shapes pricing dynamics, partnership leverage, and the bargaining power of downstream formulators. Understanding where concentration exerts pressure—and where fragmented supply offers flexibility—is essential for procurement strategy, contract negotiation, and multi-sourcing design.
Cost and continuity risks are equally central to 2026 planning. Regulatory oversight of antimicrobial supply, periodic ingredient shortages, and production delays tied to overseas manufacturing have already demonstrated how quickly availability can become a constraint. When combined with trade policy shifts affecting pharmaceutical inputs, these factors can raise production expenses and complicate inventory planning. The result is a market environment in which resilience is increasingly valued alongside efficiency. Organizations that diversify qualified sourcing channels, align manufacturing partnerships with compliance capability, and anticipate regulatory pacing will be better equipped to manage volatility without sacrificing product quality or therapeutic reliability.
Strategic Takeaways for 2026 Planning
The veterinary API manufacturing market is entering a phase where growth, regulation, and supply chain architecture will jointly determine competitive outcomes. For leadership teams preparing 2026 strategic plans, several priorities stand out. First, capacity strategy must be evaluated not only against projected volume but also against the quality, compliance, and continuity standards that regulated markets increasingly require. Second, sourcing models should be stress-tested against concentration risk, logistics variability, and shifting trade conditions to ensure that cost optimization does not inadvertently create exposure. Third, partnership selection should account for technological readiness, production flexibility, and the ability to support both current portfolios and emerging therapeutic categories.
Our Worldwide Veterinary API Manufacturing Market study is designed to support these decisions with rigorous market sizing, segmentation analysis, competitive intelligence, and scenario-ready context. It provides the evidentiary foundation necessary to move from reactive procurement to proactive market positioning. For organizations seeking to secure supply advantage, evaluate entry or expansion opportunities, and align manufacturing strategy with the realities of a maturing global animal health sector, the full report delivers the depth required to act with confidence.
The complete analysis, including detailed segmentation data, regional manufacturing profiles, and granular competitive assessments, is available through the full market research release. Accessing the complete study enables decision-makers to translate these directional insights into precise, executable strategies for the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary API Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com