

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MPPE Market Hits $2.04B in 2025, Projects $3.07B by 2032 at 6% CAGR

Strategic Imperatives in the Global Modified Polyphenylene Ether Market: Navigating Growth, Supply Shifts, and Innovation Through 2032
The engineered thermoplastics landscape is undergoing a structural recalibration, and Modified Polyphenylene Ether (MPPE) stands at the intersection of material science, regulatory evolution, and sector-specific performance demands. As suppliers, OEMs, and procurement leaders map their portfolios for the next decade, the Worldwide Modified Polyphenylene Ether Market study from PW Consulting provides a decision-grade foundation for capital allocation, capacity planning, and competitive positioning. This overview highlights the strategic architecture of the market, the forces reshaping supply-demand equilibrium, and the analytical depth you will need to convert macro trends into executable strategy.
Market Trajectory and the Strategic Value of Forward Visibility
The global MPPE market has demonstrated consistent expansion over the historical tracking window, moving from approximately $1.52 billion in 2020 to a base-year valuation of $2,040.0 million in 2025. The forecast horizon extends through 2032, with the overall market size projected to reach an estimated $3,067.41 million by the terminal forecast year. This trajectory reflects a compound annual growth rate of 6.0%, signaling a compoundable growth engine that rewards early movers with scale advantages, feedstock hedging discipline, and application-specific formulation leadership.
In an environment where raw material volatility, regional trade policy shifts, and application-specific performance requirements are simultaneously intensifying, historical hindsight is insufficient. Decision-makers need a unified view that connects pricing sensitivity to downstream demand elasticity, capacity utilization to geographic trade flows, and product architecture to end-use qualification cycles. Our Worldwide Modified Polyphenylene Ether Market research is built to support precisely that type of integrated planning.
Report Architecture: Operational Intelligence for Cross-Functional Teams
The study is designed as a working document for strategy, R&D, procurement, and commercial leadership. Its structure emphasizes actionable granularity without losing sight of market-wide dynamics. Key components include:
- Base-line and forward sizing anchored to a defined base year and a multi-year forecast window, enabling scenario modeling for capacity expansion, share-gain targets, and revenue planning.
- Segmentation frameworks that map market structure across material variants, end-use verticals, and regional demand centers, providing the analytical scaffolding needed to prioritize investments.
- Competitive profiling that examines leadership positions, portfolio differentiation, manufacturing footprints, and recent strategic activity across incumbent and specialized producers.
- Decision-support tools that translate quantitative outputs into practical templates for price-setting, inventory strategy, customer-facing positioning, and partnership evaluation.
The objective is not simply to describe the market, but to equip teams with the logic required to test assumptions. Readers will find coverage that helps answer questions such as where growth is concentrated by application class, how material blends compete on property-performance and cost, which geographic corridors carry the highest structural demand intensity, and how recent production and product announcements are reshaping competitive momentum.
Segment Intelligence: Blends, Applications, and Geographic Drivers at a Glance
MPPE’s market structure is defined by how different formulation classes align with diverging performance requirements across end-use sectors. The category spans high-performance engineering blends that balance heat resistance, dimensional stability, flame retardancy, and dielectric behavior, as well as more cost-optimized architectures targeting specific processing and mechanical constraints. Understanding these trade-offs is essential for both suppliers designing next-generation grades and buyers specifying materials for qualification-critical applications.
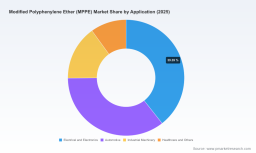
Application-level demand is anchored by performance-driven verticals where weight reduction, thermal management, electrical insulation, and durability directly influence product architecture. The electrical and electronics sector remains a central demand pillar, driven by connectors, housings, and insulation needs that reward flame retardancy and signal-integrity characteristics. Automotive demand continues to expand alongside vehicle electrification and thermal-load complexity, with components increasingly specified for under-hood durability and impact resistance. Industrial machinery and broader healthcare and specialty applications contribute additional layers of demand, each with distinct regulatory, hygiene, and reliability considerations.
Regionally, the market reflects uneven demand endowments shaped by manufacturing density, automotive and electronics clustering, and supply-chain proximity. The analysis maps these regional dynamics in a way that highlights where volume flows are concentrated and where tariff, logistics, and feedstock considerations influence sourcing strategies. Rather than offering superficial share estimates, the study provides the comparative structure needed to assess regional attractiveness for capacity deployment, distribution investment, and localized formulation strategy.
Competitive Landscape: Leaders, Differentiation, and Recent Strategic Moves
The MPPE competitive field is shaped by a small group of specialized producers with strong materials science capabilities and well-established branded product lines. The sector exhibits a meaningfully concentrated structure, where leading participants command significant share and shape pricing norms through scale, formulation IP, and application engineering support. Concentration levels in the report underscore the importance of understanding not just who the major players are, but how they compete on grade breadth, regional service, sustainability positioning, and customer qualification ecosystems.
SABIC remains a prominent participant through its NORYL™ resin platform, which is engineered for high heat resistance, dimensional stability, and flame retardancy across automotive, electrical, and electronics use cases. Asahi Kasei competes through its XYRON™ MPPE portfolio, emphasizing low dielectric constant, high rigidity, and chemical resistance for connectors, automotive components, and healthcare devices. Mitsubishi Gas Chemical contributes PPE-based resins under the Xyrol™ brand, with grades oriented toward electrical insulation, plumbing, and industrial machinery applications where hydrolysis resistance is a key differentiator. Sumitomo Chemical supplies modified PPE compounds tailored for high-heat environments in automotive under-hood parts and electronic housings, with a focus on impact strength and processability.
Recent developments illustrate how incumbents are translating technical capability into market momentum. In October 2024, SABIC introduced a NORYL™ PPE+PS resin with 50% recycled content developed for sustainable electronics housings, targeting UL94 V0 flame retardancy. That launch signals a direct link between sustainability messaging, regulatory preparedness, and performance qualification. In June 2024, Asahi Kasei expanded XYRON™ MPPE production capacity by 20% at its Nobeoka plant to serve rising demand in EV battery components, reflecting the strategic importance of electrification-linked applications in capacity planning.
These actions are not isolated product updates; they are indicators of competitive doctrine. They show how material suppliers are aligning portfolios with electrification, regulatory compliance, and sustainability expectations while protecting margins through differentiated grades and targeted capacity moves.
Industry Dynamics: Feedstock Volatility, Regulatory Reformulation, and Trade Friction
The MPPE market does not develop in a vacuum. Several concurrent dynamics are reshaping cost structures, qualification timelines, and sourcing logic. Feedstock volatility is a central concern, with phenol spot prices rising 15% to $1,450/MT in Q4 2024 due to supply disruptions across Asia-Pacific, a key feedstock pathway for PPE synthesis. At the same time, styrene monomer prices increased 12% to $1,120/MT in Asia during October 2024, driven by naphtha cost increases. These shifts directly influence economics for MPPE/PS blends and reinforce the need for robust hedging, grade substitution planning, and procurement flexibility.
Regulatory pressure is also redefining formulation strategy. EU REACH Annex XVII restrictions on certain flame retardants in PPE compounds require reformulation for electrical applications to remain compliant by 2025. This creates a compliance deadline that affects product qualification cycles, supplier selection, and time-to-market for updated grades. In parallel, trade policy continues to alter regional cost-benefit calculations. US Section 301 tariffs on Chinese PPE imports increased to 25% effective September 2024, with implications for North American supply chains and sourcing diversification plans.
Together, these dynamics create a market where cost, compliance, and continuity intersect. Buyers and suppliers alike must consider not only baseline demand growth but also sensitivity to raw material pricing, availability of compliant formulations, and exposure to tariff-affected trade corridors. The research connects these forces to the broader market model so that planners can evaluate risk-adjusted scenarios rather than assume static operating conditions.
Strategic Implications for 2026 Decision-Making
For organizations operating in or adjacent to the MPPE ecosystem, the 2026 outlook is not merely a forecast year; it is a planning pivot point. The period ahead rewards firms that can align material strategy with application roadmaps, anticipate feedstock and tariff exposure, and convert sustainability and regulatory requirements into competitive advantage rather than compliance cost.
Several strategic questions become especially salient:
- Where should capacity and formulation investment be concentrated to align with long-dated demand drivers in electrification, electronics miniaturization, and specialty industrial use?
- How can procurement and R&D coordinate to manage blended-material economics when feedstock prices and trade costs fluctuate?
- Which application segments offer the strongest combination of performance premium and qualification stability for share-gain initiatives?
- How can companies position around sustainability attributes, such as recycled content and reformulation readiness, while meeting electrical and thermal specifications?
- What regional sourcing adjustments are required to hedge against tariff exposure and feedstock disruption risk?
The answers depend on reliable segmentation logic, credible competitive context, and scenario-ready sizing. That is precisely where the full study delivers additional value, providing the depth needed to translate high-level growth signals into business-unit action.
Why This Research Matters Now
A 6.0% CAGR through 2032 indicates that MPPE is not a static niche material but a growth-attractive engineering polymer with expanding relevance across multiple high-value sectors. However, growth alone does not guarantee profitability or share gains. Success will depend on how well organizations anticipate feedstock volatility, reformulate around regulatory constraints, align capacity with application demand, and navigate concentrated competition.
Polyphenylene Ether (PPE) Market
PW Consulting’s Worldwide Modified Polyphenylene Ether Market research is structured to support that level of strategic clarity. It combines market sizing, segmentation, competitive profiling, and industry dynamics into a coherent framework that can be used for investment appraisal, product roadmap prioritization, sourcing policy, and risk assessment. The result is a reference point for teams that need to move from general market awareness to specific, defensible planning assumptions.
Worldwide Modified Polyphenylene Ether (MPPE) Market
To access the full segmentation detail, competitive benchmarks, scenario inputs, and region- and application-level intelligence, request the complete report through our official market research page. The macro trajectory and industry signals outlined here establish the strategic context; the full study provides the operational detail required to convert that context into decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Modified Polyphenylene Ether (MPPE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com