

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Fire System Aircraft Market to Hit $3,044.52M by 2032, 4.85% CAGR

Unlocking Strategic Value in the Global Fire System Aircraft Market: A 2026 Outlook
As the aviation industry navigates a period of unprecedented transformation, the integration of advanced fire protection systems has evolved from a regulatory necessity to a critical competitive differentiator. At PW Consulting, we have meticulously compiled our latest Worldwide Fire System Aircraft Market research to provide stakeholders with the actionable intelligence required to navigate this complex landscape. This study is not merely a collection of statistics; it is a strategic compass designed to guide investment decisions, product development roadmaps, and supply chain optimizations throughout the forecast period extending to 2032.
Worldwide Fire System Design Market
The market has demonstrated resilience and steady growth over the past half-decade. Historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue, driven by aging fleet replacements, heightened safety regulations, and the expansion of global air travel networks. Building on this foundation, the market is projected to reach substantial valuation milestones by the end of the forecast horizon. With a compound annual growth rate of 4.85 percent across the forecast period of 2026 to 2032, the industry presents a compelling opportunity for stakeholders who can align their strategies with emerging technological and regulatory shifts. Understanding the magnitude of this growth is essential, but recognizing the underlying drivers is where true strategic advantage lies.
The Operational Core: What This Research Delivers
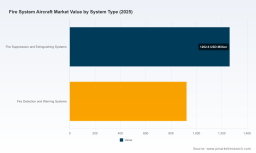
Our comprehensive analysis goes beyond top-line figures to dissect the operational mechanics of the market. The report provides a granular examination of the two primary system categories that define the industry landscape. We analyze the market share and growth potential of fire suppression and extinguishing systems versus fire detection and warning systems. While both segments are critical, their growth trajectories differ based on technological adoption rates and regulatory mandates. By understanding the distinct value propositions of each system type, manufacturers and investors can allocate resources more effectively.
Furthermore, the study segments the market by aircraft type, offering insights into the specific demands of narrow-body, wide-body, military, and regional or general aviation platforms. Each aircraft category presents unique engineering challenges and safety requirements. For instance, the density of installations in narrow-body aircraft contrasts sharply with the specialized suppression needs of military platforms. Our analysis illuminates these differences, helping partners tailor their solutions to the specific pain points of each segment. Additionally, the report breaks down revenue distributions across key geographic regions, highlighting where infrastructure development and regulatory enforcement are creating the most fertile ground for market expansion.
Beyond segmentation, the research delves into the qualitative dynamics shaping the industry. We examine the supply chain intricacies, from raw material sourcing for specialized agents to the manufacturing of high-pressure vessels and pyrotechnic cartridges. Our team has evaluated the production capabilities and technological readiness of major players to provide a clear picture of supply-side resilience. This is crucial for organizations seeking to mitigate risk in an era where supply chain disruptions can have cascading effects on aircraft maintenance schedules and operational readiness.
Competitive Landscape and Dominant Forces
The market structure is characterized by a mix of established aerospace giants and specialized niche manufacturers. Our analysis indicates a moderate to high level of market concentration, with the top three players holding a significant portion of the market share, while the top five collectively command an even larger share of total revenue. This concentration suggests that economies of scale and entrenched relationships with Original Equipment Manufacturers (OEMs) play a vital role in sustaining market position. However, the presence of agile, specialized firms indicates that innovation and certification speed remain powerful levers for market entry and growth.
Collins Aerospace (RTX) stands as a paramount example of integrated capability, providing a broad range of advanced fire detection and suppression systems for commercial and military aircraft. Their ability to cover automatic fire and explosion suppression for occupied spaces, cargo bays, and engine areas positions them as a central partner for major airframe manufacturers. Similarly, Meggitt PLC has established a reputation for designing and manufacturing fire suppression systems fitted on virtually every civil and military aircraft, leveraging in-house development for specific threat zones including engine, APU, and cargo applications. These entrenched players set the standard for reliability and certification compliance.
On the component and specialized manufacturing side, AMERON (AMETEK MRO) operates as a leading OEM manufacturer of aircraft fire suppression systems, components, high-pressure vessels, and pyrotechnic cartridges for engine, APU, cargo, and lavatory applications across commercial and military platforms. Their focus on critical hardware underscores the importance of the supply chain beneath the system integrators. Ventura Aerospace Inc. distinguishes itself by developing FAA-certified fire suppression systems specifically for Class E cargo compartments on aircraft such as MD-11F, MD-10F, and 777F, with modular designs adaptable to various fixed-wing platforms. This specialization highlights the opportunity for targeted solutions in cargo safety, a sector under increasing scrutiny.
The portable extinguisher market also sees dynamic activity. H3R Aviation supplies portable Halon and Halotron fire extinguishers and mounting options for fixed- and rotary-wing aircraft of all types and sizes. Amerex Corporation manufactures portable and fixed fire extinguishers for aviation applications, with ongoing innovation in aircraft fire safety products. These companies are often at the forefront of responding to regulatory changes regarding portable agent specifications. Meanwhile, Parker Aerospace offers ATA Chapter 26 fire protection systems with high accuracy, reliability, and low maintenance for aircraft safety, emphasizing the operational cost benefits of robust design.
Innovation in agents and specialized services is represented by companies like Hazard Control Technologies (HCT), which provides specialized aircraft fire suppression services and agents, including F-500 EA encapsulator technology qualified under FAA AC 150/5210-6E for aviation hazards including lithium-ion battery fires. Perimeter Solutions supplies SOLBERG and AUXQUIMIA Class B fluorine-free and AFFF firefighting foam concentrates, including AVIGARD line certified for ICAO aviation applications, addressing the environmental shift in chemical agents. Finally, PacSci EMC supplies energetic components and fire extinguishing cartridges qualified for commercial and military aircraft fire suppression systems, supporting FAA Airworthiness approvals, ensuring that the mechanical execution of suppression systems meets rigorous standards.
Regulatory Waves and Technological Shifts
No strategic analysis of this market is complete without a deep dive into the regulatory environment, which is currently undergoing significant turmoil and transformation. The phase-out of Halon-based systems is the single most impactful dynamic shaping the near-term market. The EU Ozone Regulation sets end-dates for halon use in existing fleets, with a key deadline of 31 December 2025 for portable Halon 1211 extinguishers in cabins and crew compartments on EASA-registered aircraft. This regulatory cliff creates an immediate demand for replacement solutions and retrofitting services.
In response to these mandates, EASA and the European Commission published the Halon replacement in the aviation industry guide 2025 to support compliance with EU Ozone Regulation on halon phase-out for portable extinguishers and onboard systems. This guidance serves as a critical roadmap for operators and manufacturers alike. Furthermore, ICAO has introduced cut-off dates after which Halon 1301-based fire extinguishing systems should no longer be used for new-type certified aircraft, including cargo compartments. These international standards reinforce the global trend away from ozone-depleting substances, forcing a structural shift in product portfolios.
The transition is not just about compliance; it is about performance and environmental stewardship. The transition to fluorine-free foam concentrates (SFFF/AR-SFFF) and clean agents such as Novec 1230 or 2-BTP/CO2 blends is accelerating for aviation applications due to environmental regulations and halon phase-out. Manufacturers who can validate the efficacy of these new agents under extreme aviation conditions will capture significant market share. This shift is complemented by evolving safety standards for emerging technologies. FAA and EASA continue to enforce enhanced fire protection requirements for lithium battery fires in cargo compartments and electronic device storage under updated airworthiness standards. As the electrification of aircraft components and the transport of lithium-ion batteries increase, the ability to suppress thermal runaway events becomes a premium capability.
Recent industry developments underscore the speed of this adaptation. In October 2025, H3R Aviation introduced Halotron BRx extinguishers as a Halon 1211 replacement for portable aircraft fire extinguishers ahead of regulatory deadlines, demonstrating proactive product lifecycle management. Concurrently, SAE International released new standards for powerplant fire protection systems, updating and supplementing FAA Advisory Circular 20-135 guidance, which will influence design requirements for engine fire protection for years to come. By December 2025, the deadline for European-registered aircraft to no longer carry Halon 1211 portable fire extinguishers marks a hard stop that will trigger a surge in replacement orders.
Strategic Implications for 2026 and Beyond
For decision-makers planning their moves in 2026, the implications of this research are clear. The convergence of steady market growth, regulatory pressure, and technological innovation creates a high-stakes environment. Companies must balance the immediate revenue opportunity presented by Halon replacement mandates with the long-term investment required for next-generation suppression agents and detection technologies. Partnerships between system integrators and agent suppliers will become increasingly vital to ensure certification speed and operational reliability.
Supply chain resilience is another critical focal point. With specific requirements for high-pressure vessels, pyrotechnic cartridges, and specialized foam concentrates, the ability to secure qualified components will differentiate successful market participants from those facing bottlenecks. The market concentration data suggests that while large players dominate, there is ample room for specialized firms to thrive by addressing niche requirements, such as cargo compartment specific solutions or lithium-ion battery fire suppression. Understanding the distinct growth profiles of narrow-body versus wide-body aircraft, as well as the persistent demand in military and general aviation sectors, allows for targeted portfolio strategy.
Worldwide Fire System Aircraft Market
The geographic dimension of the market also warrants attention. While historical revenue data shows strong performance across North America, Europe, and Asia Pacific, the rate of regulatory adoption and fleet modernization varies by region. Strategic market entry or expansion plans must account for these regional nuances rather than applying a one-size-fits-all approach. The research provides the necessary regional breakdowns to inform localized strategies without exposing the specific numerical allocations that would require a full report download to verify.
Conclusion: The Path to Informed Action
The Worldwide Fire System Aircraft Market is at a pivotal juncture. The data confirms a robust growth trajectory over the coming years, but the real value lies in understanding the forces that will shape that growth. Regulatory deadlines are acting as catalysts, environmental concerns are driving chemical innovation, and evolving safety standards for batteries and powerplants are redefining system requirements. Our latest research publication captures these complexities in a structured, actionable format.
We invite industry leaders, investors, and strategic planners to leverage this intelligence to fortify their 2026 decision-making processes. The complete report offers the detailed segmentation data, competitive profiling, and regional analysis necessary to build a resilient strategy. By accessing the full study, stakeholders can move beyond general trends to specific, data-backed plans that align with the realities of the market. The future of aviation fire safety is being written now, and those with the deepest insights will be best positioned to lead.
For detailed analysis of this topic, please visit the official page: Worldwide Fire System Aircraft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com