

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LAL Deficiency Market Hits $196.72M in 2025, Projects 6.25% CAGR to 2032

Unlocking Commercial Potential in the Lysosomal Acid Lipase Deficiency Treatment Market: Strategic Intelligence for 2026 and Beyond
A Market Defined by Precision, Scarcity, and High-Value Therapeutics
The global landscape for lysosomal acid lipase deficiency (LAL-D) treatment is undergoing a structural shift, driven by the intersection of ultra-rare disease economics, advanced biologics manufacturing, and evolving reimbursement paradigms. For senior executives, investors, and strategic planners operating in specialty pharmaceuticals, metabolic disorders, or rare disease infrastructure, the next five years will reward organizations that move beyond symptomatic awareness and invest in rigorous, forward-looking intelligence. Our newly released Worldwide Lysosomal Acid Lipase Deficiency Treatment Market study delivers exactly that: a data-grounded, decision-ready blueprint tailored to 2026 planning cycles.
Worldwide Lysosomal Acid Lipase Deficiency Treatment Market
Historically, the sector has navigated the inherent tension between clinical necessity and commercial scale. LAL-D remains a profoundly rare condition, with an estimated prevalence ranging from 1:40,000 to 1:300,000 live births. This epidemiological reality has historically constrained market visibility, but it has simultaneously elevated the strategic value of accurate forecasting, optimized launch sequencing, and precision-targeted market access strategies. The market has already demonstrated steady, compounding growth over the past half-decade, reflecting earlier diagnostic interventions, expanded therapeutic indications, and the institutionalization of orphan drug frameworks across developed healthcare systems.
Looking forward, the commercial trajectory points to sustained expansion through 2032, underpinned by a robust compound annual growth rate and a clear upward revenue arc. This report captures the full historical baseline from 2020 through the base year of 2025, then projects a calibrated forecast window that maps the incremental value creation expected across 2026 and beyond. The total addressable revenue environment is positioned to climb decisively, with pathway-dependent growth accelerating as diagnostic awareness improves, referral networks mature, and specialty care delivery models adapt to the nuances of ultra-rare metabolic conditions.
Why 2026 Is a Defining Inflection Point for Strategic Planning
The 2026 horizon is not merely a numerical checkpoint; it is a structural inflection point. By this stage, several operational and regulatory tailwinds will have fully materialized, while competitive and commercial pressures will require deliberate positioning. Organizations that enter 2026 with a clear, segment-aware strategy will be better equipped to allocate R&D capital, sequence commercial launches, negotiate with payers, and manage complex supply chains tied to specialized biologics production.
This market research was engineered specifically to inform those 2026 decisions. Rather than presenting a static snapshot, it maps the causal relationships between clinical adoption patterns, regulatory milestones, reimbursement architecture, and geographic deployment of care. The study translates macro-level market behavior into actionable intelligence that can be layered into portfolio planning, pricing strategy, market access roadmaps, and partnership evaluation. Executives will find a consistent analytical thread that connects historical momentum to forward-looking opportunity, enabling scenario modeling and risk-calibrated investment choices.
For stakeholders evaluating market entry, therapeutic expansion, or infrastructure investment, the forecast window offers critical signal. Growth is not uniformly distributed; it concentrates where diagnostic pathways are mature, where specialty clinical networks are well-defined, and where reimbursement policies align with orphan drug economics. Understanding where those conditions are forming, and how quickly they are likely to consolidate, is essential for timing commercial activities and avoiding capital misallocation.
What the Report Unpacks: Structure, Scope, and Decision-Ready Intelligence
The study is built to function as an operational companion rather than a theoretical overview. It examines the LAL-D treatment ecosystem across multiple analytical dimensions, synthesizing historical performance, structural segmentation, competitive positioning, and forward-looking market mechanics. Each section is designed to support concrete corporate actions, from pipeline prioritization to commercial readiness assessments.
The core analytical framework covers the following operational pillars:
- Historical and Forecast Revenue Mapping : A continuous timeline tracing the market’s evolution from 2020 through the base year of 2025, followed by a structured forecast that extends across the medium-to-long term. The trajectory reflects compounding adoption, therapeutic penetration, and care-delivery maturation, giving leadership a reliable baseline for planning.
- Segmentation by Treatment Modality : A detailed breakdown of how therapeutic approaches are shaping revenue composition. The analysis examines the dominant role of enzyme replacement therapy within the current commercial architecture, alongside the complementary but structurally distinct segment encompassing supportive care and diagnostics. This distinction is critical for understanding how value is distributed across treatment pathways and where future expansion is most likely to occur.
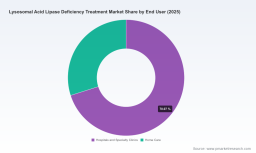
- End-User and Care Delivery Dynamics : An evaluation of where treatment is administered and how care settings influence purchasing behavior, procurement cycles, and service models. The report contrasts the central role of hospitals and specialty clinics with the growing relevance of home care pathways, highlighting how decentralization, patient convenience, and clinical monitoring protocols are reshaping demand patterns.
- Geographic Commercial Architecture : A regional analysis that examines how established markets, emerging care ecosystems, and localized reimbursement environments contribute to overall market behavior. The study identifies where mature demand centers are positioned and where infrastructure development is likely to drive incremental opportunity, without relying on simplified regional assumptions.
- Competitive Dynamics and Strategic Positioning : A focused review of the companies shaping the market, including their product pipelines, regulatory leverage, manufacturing footprint, and commercial execution strategies. The analysis connects corporate positioning to broader market structure, helping stakeholders assess concentration, competitive vulnerability, and partnership opportunity.
- Regulatory, Pricing, and Access Context : A contextualized examination of the policies and economic realities that influence market behavior, including orphan drug exclusivity, priority review pathways, pricing benchmarks, and reimbursement constraints. These factors are woven into the broader market narrative to show how policy architecture directly shapes commercial viability and expansion timelines.
This multi-layered structure ensures that decision-makers can move from high-level market direction to the specific operational considerations that affect execution. The report is designed to feed directly into strategy workshops, investment memos, and cross-functional planning processes.
Competitive Architecture: Concentration, Differentiation, and Strategic Implications
The LAL-D treatment market operates within a highly concentrated competitive environment. Such concentration carries both advantages and risks for organizations navigating the space. It signals the presence of dominant incumbents with established regulatory and commercial moats, while simultaneously creating strategic openings for differentiated entrants, collaboration models, and adjacent capability expansion.
The industry context notes underscore how regulatory milestones, pricing architecture, and manufacturing complexity collectively define competitive positioning. For example, the only FDA- and EMA-approved enzyme replacement therapy for LAL-D in both pediatric and adult populations has benefited from orphan drug designation, priority review, and multi-year market exclusivity. These regulatory mechanisms have shaped the company’s ability to establish clinical standards, negotiate reimbursement frameworks, and anchor a long-term revenue model. At the same time, the high annual treatment cost associated with this therapy illustrates how orphan drug economics can support premium pricing, but also intensify payer scrutiny and market access complexity.
From a manufacturing standpoint, the production process introduces a distinctive cost and supply-chain profile. Sebelipase alfa is generated through a proprietary platform that relies on egg-laying hens, making avian cell culture a defining operational variable. For competitors, partners, and infrastructure investors, this detail is strategically significant: it influences cost structure, scalability considerations, quality control requirements, and the broader economics of supply continuity. Understanding how manufacturing complexity interacts with pricing power and market access is essential for evaluating long-term competitiveness in this segment.
The market concentration profile reinforces the need for strategic clarity. A small number of firms command a substantial share of total market value, reflecting the reality that ultra-rare disease markets often consolidate around approved biologics with strong regulatory and clinical differentiation. This structure tends to elevate the importance of commercial execution, stakeholder engagement, and lifecycle management, while reducing the likelihood of rapid, undifferentiated market fragmentation.
Market Dynamics: Regulation, Pricing, Diagnostics, and Access as Commercial Levers
The growth trajectory of LAL-D treatment does not emerge in isolation. It is shaped by interacting forces that span regulatory policy, therapeutic pricing, diagnostic efficiency, and healthcare delivery design. This study treats those forces as operational levers rather than background context, mapping how they influence adoption speed, revenue realization, and competitive resilience.
Regulatory frameworks have played a decisive role in establishing the commercial foundation for LAL-D therapeutics. Orphan drug designations, priority review pathways, and multi-year exclusivity mechanisms have collectively supported product development incentives and helped secure market positioning for approved therapies. These mechanisms also affect how new entrants evaluate development risk, how payers anticipate long-term cost exposure, and how manufacturers plan lifecycle strategies. The study examines how these regulatory dynamics interact with broader market behavior and what they imply for future competitive maneuvering.
Pricing and reimbursement architecture is equally central to market outcomes. In ultra-rare disease settings, high per-patient treatment costs are often intrinsic to the economics of specialized biologics and limited patient populations. The report contextualizes these cost structures against reimbursement realities, showing how access strategies, payer negotiations, and health economic evaluations influence the speed and breadth of therapeutic adoption. For commercial leaders, the underlying question is not simply whether pricing is viable, but how pricing interacts with market penetration, geographic variability, and long-term sustainability.
Diagnostics and disease awareness represent another critical dynamic. Because LAL-D is an ultra-rare condition, earlier and more reliable identification directly affects treatment volumes and patient pathways. Improvements in diagnostic capability, referral practices, and clinical recognition can expand the realized market far more quickly than macro-level population statistics would suggest. The report addresses how diagnostic momentum interacts with care delivery, specialty clinic engagement, and downstream demand patterns, helping stakeholders understand where adoption acceleration is most likely to originate.
Taken together, these dynamics form a commercial environment that rewards precision. Organizations that can align therapeutic positioning with payer expectations, adapt to care-setting evolution, and anticipate regulatory or access shifts will be better positioned to convert market growth into durable value.
How to Use This Study for 2026 Decision-Making
This report is intended to support a range of strategic use cases. It can inform pipeline prioritization, support market access planning, guide partnership and licensing evaluations, and strengthen competitive benchmarking. The study’s structure allows leadership teams to isolate the dimensions most relevant to their immediate decisions while still benefiting from the broader market context.
For commercial and market access teams, the segmentation and regional architecture provide a basis for evaluating where demand is expanding and how care settings are evolving. For R&D and lifecycle teams, the treatment modality analysis and competitive framework offer perspective on differentiation opportunities and long-term positioning. For executive planning and investor relations, the historical-to-forecast trajectory delivers a credible growth narrative grounded in observable market behavior rather than speculative framing.
Worldwide Refsum Disease Treatment Market
In every case, the objective is the same: to move from high-level awareness to executable strategy. The study gives decision-makers the structure needed to evaluate opportunity, manage risk, and sequence action in a market where timing and precision matter.
Final Thought: Strategic Clarity in a High-Value, Low-Volume Market
The Worldwide Lysosomal Acid Lipase Deficiency Treatment Market is defined by a distinctive paradox: a small patient population, but a disproportionately large strategic footprint. That footprint is shaped by specialized therapeutics, concentrated competition, regulatory privilege, complex manufacturing, and evolving care pathways. In such a market, general assessments are insufficient. Organizations need detailed, forward-looking intelligence that connects market structure to commercial execution.
This study is designed to deliver that intelligence for 2026 and the years that follow. It maps the forces that are expanding the market, the structures that are concentrating value, and the dynamics that will determine which organizations capture sustainable advantage. The full depth of segmentation analysis, competitive profiling, and forecast modeling is intentionally structured to support rigorous internal planning and targeted strategic action. For leaders who want to move beyond surface-level sentiment and build decisions on verified, actionable market intelligence, the complete report provides the necessary foundation.
For detailed analysis of this topic, please visit the official page: Worldwide Lysosomal Acid Lipase Deficiency Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com