

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Plant Sterols Market Hits $1.25B in 2025, Projected to Reach $2.32B by 2032 at 9.24% CAGR

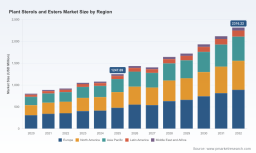
Navigating the Next Growth Cycle: Strategic Intelligence for the Worldwide Plant Sterols and Esters Market (2026–2032)
Executive Overview
The global market for plant sterols and esters is entering a decisive growth phase, driven by converging consumer health trends, regulatory stabilization, and supply chain recalibration. As corporate strategy teams finalize their post-2025 investment roadmaps, understanding the structural shifts within this sector is no longer optional—it is a prerequisite for capital allocation, product positioning, and regional entry timing. This analysis introduces our latest comprehensive study, Worldwide Plant Sterols and Esters Market, which maps the trajectory from the 2020 historical baseline through the 2026–2032 forecast horizon with unprecedented granularity.
Over the past half-decade, the sector has demonstrated remarkable resilience and expansion. Market valuation progressed from approximately USD 802.15 million in 2020 to an estimated USD 1,247.69 million in 2025, reflecting a compound trajectory shaped by rising demand for cardiovascular wellness solutions and functional food fortification. Looking ahead, the forecast window projects a sustained expansion reaching USD 1,435.08 million in 2026, before accelerating through the late forecast period to culminate at USD 2,316.22 million by 2032. These figures anchor a forecast compound annual growth rate of 9.24 percent, signaling that the industry is transitioning from a mature niche to a structurally scalable value chain. The strategic implication is clear: scale economics, formulation agility, and regional compliance literacy will separate market leaders from followers over the next seven years.
Market Architecture and Growth Vectors
The market's expansion is not uniform; it is structured around distinct product architectures, delivery formats, and application ecosystems. Plant sterol esters currently command a dominant share of the form landscape, reflecting their superior bioavailability and ease of integration into lipid-based matrices. Free sterols maintain a meaningful secondary position, often favored in specialized nutraceutical and pharmaceutical formulations where purity profiles and processing constraints dictate alternative delivery routes. At the molecular level, the phytosterol portfolio is anchored by sitosterol, supported by campesterol and stigmasterol, with other phytosterols rounding out specialized high-purity applications. This compositional hierarchy influences everything from extraction economics to end-market claim substantiation.
Applications span a diversified matrix of consumer and clinical use cases. Food and beverage fortification remains the primary demand engine, leveraging heart health positioning within spreads, dairy alternatives, and fortified beverages. Dietary supplements represent a parallel growth conduit, where standardized extracts align with consumer self-care routines and clinical-grade transparency expectations. Pharmaceuticals and cosmetics constitute smaller but strategically important segments, where sterol derivatives serve targeted therapeutic pathways and premium personal care formulations respectively. Each application vertical carries distinct regulatory thresholds, customer procurement cycles, and margin structures, requiring differentiated go-to-market strategies.
Geographically, the market exhibits mature demand centers alongside high-potential emerging corridors. Demand concentration reflects long-standing nutritional intervention adoption patterns in Europe and North America, while Asia Pacific continues to expand its footprint through rising health-conscious consumption and localized manufacturing investments. Latin America and the Middle East and Africa represent smaller but increasingly relevant pathways, shaped by import dynamics, regulatory evolution, and cross-border supply relationships. The interplay between these regional demand profiles and feedstock availability will define both pricing power and distribution agility across the forecast period.
Competitive Landscape: Positioning, Moves, and Strategic Implications
The competitive environment is characterized by a concentrated core of established ingredient suppliers, each leveraging brand equity, formulation expertise, and supply chain scale to defend share while pursuing targeted expansion. Industry leadership is visibly consolidated, with the top three enterprises accounting for a substantial portion of total revenue and the top five extending that influence further. This consolidation underscores the strategic importance of manufacturing capability, regulatory credentialing, and application-specific technical support as durable competitive moats.
BASF Personal Care maintains a prominent position through its CardioAid brand, delivering plant sterols and sterol esters derived from vegetable oils for functional foods, supplements, and cosmetics. The company's June 2024 non-GMO certification for its CardioAid plant sterol esters line signals a deliberate response to clean-label demand and regulatory clarity requirements, reinforcing its relevance for manufacturers seeking verified ingredient integrity. Raisio Plc continues to lead in the plant stanol ester segment through its Benecol platform, targeting cholesterol-lowering margarines, spreads, and yogurts. Its October 2024 launch of new Benecol yogurts with enhanced bioavailability demonstrates a product-level push to improve functional efficacy and consumer acceptance in European markets, reinforcing brand-level differentiation through formulation science.
Archer Daniels Midland (ADM) operates as a major North American ingredient supplier, manufacturing plant sterols and esters from soy and other vegetable oil sources for food fortification and nutraceutical applications. Its March 2024 capacity expansion at the Decatur facility, increasing production capability by 20 percent, reflects a direct response to regional demand momentum and underscores the strategic value of domestic manufacturing in navigating trade complexity. Cargill complements this landscape by providing plant sterol esters for dairy, beverages, and bakery applications, with a clear emphasis on heart health claims and formulation compatibility. Veratech Fine Chemical specializes in high-purity beta-sitosterol and plant sterol esters for pharmaceutical and dietary supplement applications, occupying a precision-oriented niche that rewards technical consistency and specification control.
Worldwide Plant Sterols and Esters Market
Phytoene and Koninklijke DSM N.V. extend the competitive field across Asian sourcing dynamics and broad nutritional product portfolios respectively. Phytoene's production of plant sterols from pine and vegetable sources supports global food and pharmaceutical markets, while DSM's offerings target cardiovascular health within nutritional products, illustrating how feedstock versatility and end-use positioning can shape competitive advantage across different market tiers. Together, these players illustrate that leadership in this sector is increasingly defined by application engineering, regulatory readiness, and the ability to match ingredient specifications with claim-substantiated product architectures.
Forces Reshaping the Trajectory: Feedstock, Regulation, and Trade Dynamics
Strategic planning for the 2026–2032 window requires a clear view of the external forces that will modulate supply economics, claim substantiation pathways, and market accessibility. Three structural dynamics stand out as particularly consequential.
Raw material economics remain a central lever. Vegetable oil prices, the primary feedstock basis for plant sterol extraction, rose 8 percent year-over-year to approximately USD 1,200 per metric ton in the fourth quarter of 2025, reflecting palm oil supply constraints and broader commodity pressure. This feedstock trajectory influences extraction cost structures, formulation pricing strategies, and supplier negotiation leverage. Companies reliant on single-commodity sourcing will need to assess diversification pathways, contractual hedging mechanisms, and processing efficiency upgrades to protect margin integrity.
Worldwide ¦Â-Sitosterol Market
Regulatory frameworks continue to define the boundaries of commercialization. In Europe, EU Regulation (EC) No 1924/2006 maintains a daily intake range of 1.5 to 3 grams for cholesterol reduction claims, a parameter that remained unchanged through 2025. This stability provides a predictable compliance environment for European product developers, but it also sets a firm ceiling on claim architectures and serving-size design. In the United States, the FDA reaffirmed GRAS status for plant sterol esters up to 3.3 grams per day in conventional foods through its 2024 docket, offering manufacturers a clarified pathway for ingredient integration without sacrificing functional positioning. These regulatory baselines shape formulation ceilings, labeling strategies, and the comparative advantage of regional market entry.
Trade policy introduces additional complexity. US-China tariffs on vegetable oil derivatives increased import duties on plant sterols to 25 percent effective January 2025, altering cost competitiveness for cross-border ingredient flows and potentially accelerating regional sourcing realignments. For multinational suppliers and buyers alike, this shift increases the strategic value of localized production footprints, tariff-optimized logistics, and dual-supply resilience. The intersection of feed cost volatility, regulatory ceilings, and tariff-driven cost differentials means that pricing models, country prioritization, and manufacturing geography will become more tightly coupled over the forecast period.
What the Report Delivers: An Operational Intelligence Toolkit
This study is structured not merely as a data repository but as a decision-support instrument designed for cross-functional deployment. It maps historical performance from 2020 through 2025, establishes the 2026 baseline, and extends the forecast through 2032 with a clear growth pathway. Beyond aggregate market sizing, the report dissects the market by region, product type, form, and application, enabling stakeholders to identify where growth concentrates, where competitive intensity is highest, and where entry or expansion can be timed for maximum impact.
The segmentation framework provides actionable visibility into the relative scale and trajectory of each market pillar, allowing strategy, finance, and R&D teams to align product pipelines with addressable demand. The competitive intelligence module profiles leading manufacturers, their geographic bases, brand positions, and technical capabilities, while also documenting recent developments that signal strategic intent—product launches, certifications, and capacity expansions that directly affect supply availability and claim credibility. These developments are analyzed not in isolation but as indicators of broader market direction, including where incumbents are investing to protect share and where whitespace may be emerging.
In addition, the report integrates contextual dynamics that influence operating conditions, including feedstock price movements, regulatory claim parameters, and trade policy shifts. By embedding these forces within the market structure, the study enables scenario-based planning around sourcing costs, regional cost competitiveness, and compliance-driven product architecture. The objective is to give executives a coherent basis for pricing strategy, regional prioritization, supplier selection, and claim-substantiated product design across the forecast horizon.
Strategic Imperatives for 2026 Decision-Makers
As the market accelerates toward its USD 2,316.22 million endpoint by 2032, several strategic imperatives come into focus. First, formulation and application strategy will increasingly determine market share. Regions, forms, and product types are not interchangeable; each carries distinct margin profiles, regulatory constraints, and customer expectations. Companies that align their ingredient portfolios with application-specific efficacy and claim substantiation will capture greater value than those competing solely on commodity pricing.
Second, supply chain architecture demands proactive redesign. With feedstock volatility, regional tariff exposure, and concentrated manufacturing capability among leading suppliers, resilience will depend on diversified sourcing, capacity flexibility, and logistics optimization. Investments in production footprint, feedstock alternatives, and supplier partnerships will translate directly into pricing stability and delivery reliability.
Third, regulatory literacy will function as a competitive differentiator. The stability of European intake thresholds and US GRAS positioning provides a workable compliance foundation, but it also requires disciplined serving-size design, label architecture, and regional product adaptation. Firms that internalize these parameters early will move faster in product development and reduce time-to-market risk.
Finally, competitive intelligence must be treated as a living input. Recent developments across major players—enhanced bioavailability launches, non-GMO certifications, and capacity expansions—reflect strategic pivots that reshape supply availability and brand positioning. Monitoring these moves and linking them to segmentation and regional dynamics will help decision-makers anticipate shifts in competitive intensity rather than react to them.
The Worldwide Plant Sterols and Esters Market study is built to support these imperatives with structured, forecast-grounded intelligence. The full report extends beyond aggregate trajectories to deliver the detailed segmentation data, competitive profiling, and contextual scenario analysis necessary for precise strategic planning. For leadership teams preparing investment cases, product roadmaps, and regional entry strategies for 2026 and beyond, the complete dataset and analytical frameworks are available through the source page, where the full intelligence package can be accessed in detail.
For detailed analysis of this topic, please visit the official page: Worldwide Plant Sterols and Esters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com