

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide Rod Gauge Market Hits $461 Million in 2025, Projects 5.12% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Inside the Worldwide Rod Capacitive Level Gauge Market
As industrial operations worldwide navigate a period of accelerated modernization, precise level measurement has emerged as a critical enabler of operational efficiency, safety compliance, and process automation. PW Consulting is proud to introduce our latest comprehensive market intelligence piece—the Worldwide Rod Capacitive Level Gauge Market study. Designed specifically to inform enterprise strategy in the 2026 fiscal cycle and beyond, this report provides a rigorous, data-driven examination of a specialized yet indispensable industrial instrumentation sector. Executives, product planners, and competitive strategists will find actionable insights calibrated to support capital allocation, market entry evaluation, and long-term portfolio positioning.
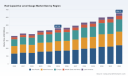
The global market for rod capacitive level gauges has demonstrated steady, resilient expansion over the past half-decade. Drawing from verified historical records spanning 2020 through 2025, our analysis traces a clear trajectory of commercial maturation. Starting from a foundational valuation of approximately 361.4 million USD in 2020, the industry climbed to 392.9 million USD in 2021 before experiencing a brief technical correction in 2022. Recovery proved swift and sustained, with revenues reaching 428.68 million USD in 2023, 435.14 million USD in 2024, and stabilizing at 461.24 million USD in 2025. These historical baselines anchor our forward-looking framework, which projects a compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast window. Under this growth trajectory, market valuation will exceed 466.94 million USD by 2026, advance toward 494.27 million USD in 2027, and continue its upward momentum through 2032, ultimately approaching 654.21 million USD.
Why 2026 Demands a Refined Strategic Lens
The year 2026 represents a decisive inflection point for industrial instrumentation stakeholders. Supply chain realignments, evolving environmental regulations, and the widespread integration of digital monitoring architectures are reshaping procurement behaviors across heavy process industries. Organizations that rely on legacy level-sensing methodologies face mounting exposure to measurement drift, maintenance overhead, and compliance vulnerabilities. Conversely, enterprises that align their instrumentation portfolios with next-generation capacitive rod technologies stand to capture measurable gains in uptime reliability, chemical compatibility assurance, and automated process control. Our study isolates the precise commercial vectors that will dictate competitive advantage during this transition period. Rather than offering generalized industry commentary, we deliver a quantified strategic map that connects technological specification capabilities to actual market demand patterns, pricing elasticity, and regional deployment cycles.
What the Study Delivers: A Practitioner’s Roadmap
This market research publication is structured to translate macroeconomic indicators into operational decision frameworks. Each chapter is engineered to address a specific strategic planning requirement. The analytical architecture includes:
- A complete historical reconstruction of market valuation from 2020 through the current baseline year, paired with a forward projection extending through the end of the decade, enabling accurate budgeting cycles and multi-year capacity planning.
- Application-specific demand profiling across core verticals, including water and wastewater management, chemicals and petrochemicals, food and beverage production, oil and gas operations, and pharmaceutical manufacturing, with emphasis on the distinct measurement challenges each sector presents.
- Product-type segmentation contrasting insulated rod gauge architectures against non-insulated variants, highlighting material compatibility considerations, environmental resilience thresholds, and total cost-of-ownership implications across corrosive, high-temperature, and hygienic process environments.
- Geographic market distribution analysis that maps revenue density, growth velocity, and infrastructure investment pacing across major industrial regions, helping organizations prioritize export logistics, localized service networks, and regional certification pathways.
- Cross-industry contextual intelligence that situates level gauge procurement within broader capital expenditure trends, notably the ongoing scrutiny of facility budgets and the parallel push toward sensor-enabled process optimization that is reshaping how industrial operators justify instrumentation investments.
- Competitive benchmarking that evaluates product roadmaps, portfolio breadth, and market positioning across established manufacturers and emerging challengers, providing a clear view of where differentiation is still achievable.
Competitive Dynamics: Measuring the Incumbents and Challengers
The rod capacitive level gauge landscape is characterized by a moderate concentration of established multinational players alongside a network of highly specialized engineering firms. Our analysis indicates that the top three competitors collectively command approximately 38.45 percent of total market revenue, while the top five players extend their combined share to roughly 54.12 percent. This structure suggests a market that remains accessible to agile entrants while rewarding incumbents who can scale certified product lines across multiple process sectors.
Worldwide Capacitive Height Controller Market
VEGA Grieshaber KG, headquartered in Schiltach, Germany, continues to anchor its commercial strategy on the VEGACAL series of rod probes. Their portfolio spans partially and fully insulated configurations utilizing PTFE, PE, and FEP materials, alongside ceramic-insulated variants, delivering continuous capacitive level measurement for both liquids and bulk solids. Endress+Hauser, based in Reinach, Switzerland, advances a complementary approach through its Liquicap FMI51 and FMI52 rod probes, engineered for continuous level and interface measurement in viscous, aggressive, and deposit-forming media, alongside FTI51 and FTI52 models dedicated to point level detection. Siemens AG, operating from Munich, Germany, positions the SITRANS LC300 capacitance level transmitter with active-shield technology as a continuous measurement solution for liquids, solids, and slurries, while the Pointek CLS200 rigid rod variant addresses point level detection requirements.
Mid-tier and regional specialists add substantial portfolio diversity. KOBOLD Instruments, with its operational base in Hofheim, Germany and United States presence in Pittsburgh, Pennsylvania, manufactures NMC capacitive level transmitters using rod probes ranging from 11 to 157 inches, specifically calibrated for aggressive chemical, pharmaceutical, and food-grade liquids. Dwyer Instruments and Omega Engineering, operating out of Michigan City, Indiana, deliver the LV3000 and LV4000 series capacitive rod probes designed for continuous measurement of liquids, pastes, and solids, with standard 4-20 mA output configurations suited to oils, solvents, and process water applications. NIVELCO Process Control Co., headquartered in Budapest, Hungary, supplies NIVOCAP capacitive level transmitters with rod and cable probe configurations, supporting conductive and non-conductive liquids with standard rod lengths reaching approximately three meters and high-temperature variants, all integrated with 4-20 mA and HART communication protocols.
The competitive field further extends with SenTec from Chengdu, China, whose SRC400 coaxial rod capacitive level gauge targets continuous measurement applications, and BinMaster, based in Lincoln, Nebraska, which specializes in custom-configured capacitance probes for level detection across bins, silos, tanks, and hoppers. European sensor specialists UWT GmbH and Baumer contribute Capanivo and RFnivo series capacitive sensors, including rod-based point level detection designs for demanding liquid and solid environments, while Balluff from Neuhausen, Germany rounds out the competitive matrix with a broad capacitive sensor lineup addressing diverse level measurement tasks.
Recent commercial activity reinforces the strategic relevance of this sector. In January 2026, NIVELCO Process Control Co. released its updated North America product catalog, featuring revised NIVOCAP capacitive level transmitters with rod probes, newly introduced PiloTREK radar models, and a clear emphasis on high-sensitivity capacitive solutions for liquid applications. Such catalog expansions signal an ongoing industry-wide push toward enhanced measurement sensitivity, broader material compatibility, and tighter integration with industrial communication standards.
Market Dynamics and the Case for Strategic Foresight
The rod capacitive level gauge market does not operate in isolation. It responds directly to macro-level capital allocation patterns, regulatory pressure on process transparency, and the accelerating digitization of industrial sensor networks. Across heavy process industries, procurement teams are increasingly weighing instrumentation purchases against broader facility budget constraints and long-term operational efficiency targets. The same financial discipline that shapes hospital and healthcare capital expenditure planning—where executive surveys indicate a cautious outlook on near-term budget expansion—mirrors a wider industrial tendency to prioritize instrumentation that demonstrably reduces maintenance frequency, minimizes process downtime, and supports automated control architectures.
Simultaneously, the steady escalation of operating costs across process-heavy sectors is reinforcing demand for measurement equipment that lowers total cost of ownership through extended service intervals, improved chemical resistance, and reliable performance in challenging media conditions. Level measurement technologies that can deliver continuous, stable readings in corrosive, viscous, or build-up-prone environments are increasingly evaluated not as commodity purchases but as strategic assets within facility modernization programs. Our study maps these behavioral shifts directly to purchasing criteria, helping leaders differentiate between tactical replacements and long-term capability investments.
Worldwide Rod Capacitive Level Gauge Market
How to Use This Research for Your 2026 Decisions
PW Consulting designed this market study to function as an internal reference asset rather than a passive industry overview. Product managers can leverage the type and application breakdowns to align engineering roadmaps with verified demand concentrations. Regional directors can use the geographic revenue distribution to calibrate distribution partnerships, service coverage expansion, and localized certification strategies. Competitive intelligence teams will find direct value in the incument profiling, which clarifies where portfolio overlaps exist and where whitespace opportunities remain viable. Finance and strategy groups can anchor long-range revenue forecasting and scenario modeling to the documented historical series and the 5.12 percent forward growth trajectory.
The full report contains extensive quantitative matrices, vendor capability comparisons, application-specific deployment considerations, and forward scenario analysis that extend well beyond the preview provided here. We have intentionally reserved the complete dataset, granular segmentation matrices, and proprietary competitive scoring methodologies for the full publication, ensuring that subscribers receive actionable intelligence rather than generalized market commentary.
Access the Complete Intelligence Package
The Worldwide Rod Capacitive Level Gauge Market study represents a comprehensive resource for stakeholders who require precise, forward-looking market visibility in 2026 and beyond. By integrating verified historical baselines, disciplined forecast modeling, application-specific deployment insights, and detailed competitive profiling, this publication equips decision-makers with the evidence needed to navigate an evolving industrial instrumentation landscape. Organizations that secure the full report will gain immediate access to the quantitative depth and strategic context necessary to optimize product positioning, inform capital deployment, and anticipate demand shifts across the forecast horizon. We invite executives, strategy leads, and market planners to access the complete research package through our official publication portal and integrate these findings into their 2026 strategic planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Rod Capacitive Level Gauge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Furniture Installation & Relocation Market to Hit $2.4B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Worldwide Furniture Installation and Relocation Service Market (2026–2032)
The global furniture installation and relocation service market stands at a critical inflection point as organizations navigate post-pandemic operational realignments, hybrid work mandates, and escalating logistics complexity. PW Consulting’s latest Worldwide Furniture Installation and Relocation Service Market research delivers a comprehensive, data-grounded assessment of this evolving landscape, providing executives, investors, and service operators with the analytical clarity required to make disciplined strategic decisions throughout the forecast horizon. Drawing on rigorous modeling, primary industry validation, and cross-sector demand mapping, this publication is engineered not as a static snapshot but as a forward-looking decision-support instrument for 2026 planning cycles and beyond.
Market Trajectory and Foundational Intelligence
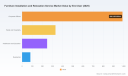
Historical performance across the 2020–2025 observation window demonstrates consistent revenue expansion, culminating in a baseline valuation of 1,650 million USD in the base year of 2025. Macroeconomic stabilization, sustained commercial real estate repositioning, and the continued normalization of corporate relocation programs have collectively reinforced demand resilience. Forward-looking projections spanning 2026 through 2032 indicate a sustained expansion trajectory, anchored by a compound annual growth rate of 5.45 percent. By the terminal forecast year, the market is positioned to cross the 2,400 million USD threshold, reflecting both organic volume growth and structural shifts in how organizations procure, manage, and redeploy physical assets.
These headline figures, while instructive at a macro level, represent only the outermost layer of a deeply segmented operating environment. Growth vectors vary materially across service typologies, end-user verticals, and geographic footprints, each carrying distinct margin profiles, capacity constraints, and competitive intensity. A disciplined approach requires unpacking the underlying demand architecture rather than relying on aggregated revenue totals. PW Consulting’s methodology isolates these dimensions through granular segmentation modeling, scenario testing, and sensitivity analysis, enabling leadership teams to calibrate capacity planning, pricing strategies, and geographic prioritization with precision.
The service ecosystem itself is undergoing measurable recalibration. Installation-driven engagements continue to anchor a substantial share of total contract value, driven by corporate fit-out cycles, retail refresh programs, and healthcare facility expansions. Relocation services maintain strong momentum as organizations execute footprint optimization and employees navigate hybrid living arrangements. Concurrently, asset management and decommissioning workflows are gaining strategic relevance as enterprises prioritize sustainable asset recovery, lifecycle tracking, and compliance-driven disposal protocols. Each segment operates under different operational economics, labor intensity profiles, and client procurement behaviors, necessitating differentiated go-to-market postures.
Structural Shifts Defining the Competitive Landscape
The market remains moderately fragmented, with no single entity exerting decisive pricing or capacity control. Aggregate concentration metrics indicate that the top three operators collectively account for approximately 18.5 percent of total revenue, while the top five expand that share to roughly 24.2 percent. This dispersion signals ample room for targeted scaling, regional consolidation, and service differentiation, but it also underscores the importance of defensible operational advantages. Companies that thrive in this environment typically combine reliable execution quality, transparent pricing frameworks, scalable dispatch infrastructure, and strong client retention mechanics.
A defining feature of the current landscape is the prominent role of platform-enabled and tech-forward service models. TaskRabbit, headquartered in San Francisco, operates a distributed marketplace architecture that connects end users with localized Taskers for furniture assembly, installation, and relocation across select international markets. Handy, based in New York, delivers an on-demand service platform emphasizing professional installation, assembly, and moving capabilities across major metropolitan corridors in the United States, the United Kingdom, and Canada. Thumbtack, also anchored in San Francisco, functions as a curated marketplace for local professionals specializing in furniture installation, disassembly, and relocation, with a strong domestic footprint. Angi, originally recognized as Angie’s List and now operating from Denver, maintains an online directory and booking infrastructure that routes clients to vetted contractors for installation and relocation work throughout the United States.
Beyond the platform layer, traditional and hybrid operators continue to shape market dynamics through scale, brand recognition, and operational specialization. CORT Furniture Rental & Delivery, headquartered in Chantilly, integrates delivery, installation, and relocation into a broader rental ecosystem, serving corporate and transitional housing demand across the United States and select international locations. Two Men and a Truck, based in Atlanta, operates a nationally distributed moving franchise model with more than 400 locations and international extensions, offering dedicated furniture relocation, disassembly, and reassembly capabilities. Bellhop, operating from Nashville, leverages a tech-enabled moving framework to deliver installation and relocation services across more than thirty-five U.S. cities. Collectively, these organizations illustrate the spectrum of business models competing for share—from marketplace aggregation to branded franchise networks to rental-integrated service bundles.
Operational Economics, Regulation, and Labor Dynamics
Strategic planning in this sector requires direct engagement with structural cost and compliance realities. Labor economics remain a central driver of unit economics. Hourly wages for furniture installers and movers averaged 18.50 USD in the United States as of 2024, according to federal labor statistics, establishing a baseline cost structure that directly influences margin thresholds, pricing elasticity, and service-tier design. At the same time, employment projections for furniture movers anticipate growth of approximately 5 percent between 2023 and 2033, a pace that trails broader occupational averages due to automation exposure and efficiency gains in scheduling, routing, and inventory handling. These dual pressures—rising wage floors and measured employment growth— compel operators to pursue labor productivity improvements, standardized process design, and selective technology adoption rather than relying solely on headcount expansion.
Regulatory and safety frameworks further condition operational execution. OSHA standard 1910.176 mandates safe handling and storage of materials, including furniture, to prevent workplace injuries during installation and relocation activities. Compliance with this standard influences training requirements, equipment provisioning, site assessment protocols, and liability management. In parallel, jurisdictional labor classification rules continue to shape platform economics. California’s AB5 framework classifies many gig workers as employees, altering contractor engagement models for marketplace-based service providers and influencing cost structures, scheduling flexibility, and scalability across affected regions. These regulatory dynamics are not static footnotes; they are active variables that inform market entry timing, operating model design, and risk allocation strategies.
Taken together, labor cost trends and regulatory requirements create a narrow window between service affordability and operational profitability. Operators that institutionalize safety-forward workflows, invest in modular training pipelines, and align workforce models with local compliance regimes are better positioned to sustain margins while preserving service quality. For corporate buyers, these same factors elevate the importance of vendor due diligence, ensuring that installation and relocation partners can demonstrate consistent adherence to safety expectations and labor standards across multiple sites and jurisdictions.
Demand Architecture Across End-User Verticals
The market’s expansion is not uniform; it is anchored by distinct demand profiles that differ in contract size, procurement cycles, service complexity, and retention behavior. Corporate offices represent a dominant share of total demand, reflecting ongoing workspace reconfiguration, hybrid seating models, and periodic relocation of regional hubs. These engagements tend to prioritize scheduling reliability, minimal operational disruption, and coordinated multi-site execution, making vendor capability and account management critical differentiators.
Retail and hospitality demand forms another substantial pillar, driven by seasonal remodels, flagship refreshes, franchise rollouts, and experiential space redesigns. Service requirements in these verticals frequently emphasize speed, aesthetic precision, and clear post-installation handoff procedures. Healthcare and education segments contribute steady, project-based volume characterized by strict compliance expectations, specialized handling requirements, and coordination with facilities management teams. Residential demand, while smaller in aggregate contract value relative to commercial segments, remains a consistent source of recurring activity, often mediated through platform marketplaces, localized service networks, and hybrid rental-and-relocation offerings.
Each vertical carries its own procurement rhythm and performance expectations. Corporate buyers typically evaluate vendors on execution consistency, safety records, and scalable deployment capacity. Retail and hospitality operators weigh speed, site sensitivity, and brand-aligned presentation. Institutional buyers in healthcare and education prioritize regulatory alignment, documented handling procedures, and coordinated logistics. Residential customers, particularly in platform-mediated transactions, emphasize convenience, transparent pricing, and localized availability. Understanding these divergent requirements is essential for service providers seeking to align sales messaging, operational design, and pricing architecture with the segments most compatible with their capabilities.
What the Full Research Delivers
PW Consulting’s Worldwide Furniture Installation and Relocation Service Market report is structured to translate high-level market intelligence into executable planning inputs. The full publication extends well beyond top-line sizing and trend commentary, offering a layered analytical framework designed for use for corporate strategy, venture and private equity evaluation, capacity planning, and competitive positioning exercises.
Worldwide Furniture Installation and Relocation Service Market
Core components of the research include a detailed segmentation architecture that maps service types, end-user verticals, and regional demand structures without reducing them to isolated percentages, preserving instead the relational context needed for strategic interpretation. The forecast model spans 2026 through 2032 and is supported by scenario analysis that accounts for shifts in commercial real estate utilization, relocation program frequency, labor availability, and regulatory evolution. Competitive profiling examines operating models, geographic reach, service scope, and positioning tactics across leading platform, brokerage, franchise, and rental-integrated participants, providing a reference map for benchmarking and differentiation planning.
The report also integrates operational and regulatory context into the market narrative, ensuring that executives can assess how wage structures, safety mandates, labor classification rules, and automation exposure influence margin potential and scalability. Demand-side analysis connects vertical-specific procurement behaviors to service design implications, clarifying where execution reliability, speed, compliance documentation, or localized availability creates the strongest competitive advantage. Additionally, the research surfaces practical guidance on pricing frameworks, capacity allocation, vendor selection criteria, and risk mitigation practices that can be applied directly to 2026 planning cycles.
For organizations evaluating market entry, geographic expansion, or portfolio adjustment, the publication provides a disciplined basis for comparing opportunity attractiveness across segments and locations. For existing operators, it supports refinement of service mixes, investment prioritization, and competitive response planning. For investors and advisory professionals, it delivers a structured synthesis of market size, growth trajectory, concentration dynamics, and structural risk factors that can inform diligence and valuation discussions.
Strategic Implications for 2026 Decision-Making
As organizations move into 2026 planning, several strategic priorities emerge from the market’s underlying structure. First, service differentiation will increasingly depend on execution quality and process reliability rather than price alone. As demand diversifies across corporate, retail, hospitality, healthcare, education, and residential channels, vendors that can tailor operating procedures, training, and dispatch logic to specific vertical expectations will capture stronger retention and pricing leverage.
Second, labor strategy will remain decisive. With wage floors established and employment growth projected to expand at a measured pace, operators must pursue productivity through standardized workflows, scheduling optimization, and targeted technology integration. Companies that treat labor not as a variable cost to be minimized but as a capability to be engineered will be better equipped to protect margins while meeting service-level expectations.
Third, regulatory and compliance awareness will shape both market access and operating model design. Safety standards, handling requirements, and labor classification frameworks influence training costs, contractor engagement models, and geographic feasibility. Forward-looking strategies should incorporate compliance mapping as a core planning input rather than a reactive operational concern.
Fourth, competitive positioning will increasingly reward clarity of scope and operational fit. The coexistence of platform marketplaces, branded franchise networks, rental-integrated providers, and specialized local operators creates a complex environment in which broad promises are less effective than well-scoped value propositions. Organizations that define where they compete, how they win, and which segments they intentionally serve will be better positioned to allocate capital and attention efficiently.
Final Perspective
The Worldwide Furniture Installation and Relocation Service Market is expanding along a measurable, structurally supported trajectory, but its real strategic value lies beneath the headline figures. Growth is unevenly distributed across service types, end-user segments, and geographies; competitive intensity is shaped by business model diversity; and operating economics are conditioned by labor costs, safety mandates, and regulatory frameworks. PW Consulting’s full market research consolidates these dimensions into a coherent intelligence asset, enabling decision-makers to move beyond surface-level sizing and engage the operational, competitive, and demand-side realities that will shape performance through 2032.
RTA (Ready-to-assemble) Furniture Market
For executives, investors, and service operators preparing for 2026, the complete report offers the segmentation depth, forecast discipline, competitive context, and operational insight required to translate market movement into actionable strategy. The full analysis, including detailed segmentation mapping, scenario frameworks, and competitive profiling, is available through the source publication and serves as a foundational reference for planning, investment evaluation, and market positioning across the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Furniture Installation and Relocation Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TFLN Modulator Market Hits $261M in 2025, 35.53% CAGR to $2.2B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Photonics Era: Inside the Worldwide Thin Film Lithium Niobate Modulator Market 2026-2032
The global optical communications landscape is undergoing a structural shift. As data center interconnects, telecommunication networks, and emerging quantum applications demand higher bandwidths, lower power consumption, and tighter integration, Thin Film Lithium Niobate (TFLN) modulators have emerged as a cornerstone technology. For enterprise leaders, investors, and technology strategists operating in 2026, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, supply chain resilience, and product roadmap planning.
PW Consulting's latest Worldwide Thin Film Lithium Niobate Modulator Market study delivers a comprehensive, data-driven foundation for these decisions. Below, we outline the strategic contours of the market, the competitive forces shaping its evolution, and the operational intelligence embedded in the full report.
The Macro Trajectory: A Sector in Hypergrowth
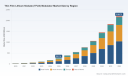
The TFLN modulator market has moved decisively beyond its early adoption phase. Historical data from 2020 through 2025 reveals an acceleration curve that underscores the technology's transition from specialized laboratory demonstrations to production-grade commercial deployment. Beginning at a modest baseline in the early 2020s, the market expanded rapidly as hyperscale data centers, coherent optical networks, and next-generation sensing platforms embraced TFLN's superior electro-optic efficiency, ultra-low half-wave voltage characteristics, and compatibility with scalable photonic integrated circuit architectures.
Looking forward, the forecast period from 2026 to 2032 projects a sustained, high-velocity expansion. The market is expected to grow at a compound annual growth rate of 35.53% over this horizon, reflecting the compounding effect of AI-driven interconnect demand, the rollout of next-generation telecommunication infrastructure, and the nascent but accelerating integration of TFLN devices into quantum and advanced sensing applications. By the close of the forecast window, the total market valuation is projected to reach a level that fundamentally reshapes the competitive landscape for photonic component suppliers and system integrators alike.
This growth trajectory is not merely a function of volume. It reflects a deeper structural realignment: TFLN is becoming the material platform of choice for high-speed, energy-efficient optical modulation across multiple end markets simultaneously. The strategic implication for 2026 decision-makers is clear. Companies that fail to map their product portfolios, supply partnerships, and technology roadmaps against this trajectory risk being left behind as the market compounds.
What the Report Delivers: Actionable Intelligence Beyond Top-Line Numbers
PW Consulting's study is designed for practitioners who require more than aggregate market projections. The report provides a granular, multi-dimensional analysis structured to support strategic planning across several critical dimensions:
Worldwide Thin Film Lithium Niobate (TFLN) Modulator Market
- End-to-end market sizing and forecasting: Detailed revenue projections across the forecast period, anchored in historical performance data from 2020 through the base year of 2025, enable precise demand modeling and investment scenario planning.
- Type-level segmentation analysis: The report dissects the market by modulator architecture, including intensity modulators, phase modulators, and IQ modulators. This breakdown clarifies where performance-differentiated products are capturing value, how application requirements are driving architecture preferences, and where R&D investment is most likely to yield competitive advantage.
- Application-driven demand mapping: Demand is analyzed across data center interconnects, telecommunication networks, aerospace and defense, and quantum and sensing verticals. Understanding the distinct performance thresholds, procurement cycles, and qualification requirements in each segment allows companies to prioritize product development and go-to-market strategies with precision.
- Regional dynamics and competitive positioning: The study maps geographic demand patterns and highlights where manufacturing capacity, design talent, and end-customer concentration are creating localized advantages or bottlenecks. This regional lens is essential for supply chain strategy, partnership evaluation, and market entry timing.
- Competitive landscape profiling: In-depth profiles of leading TFLN modulator developers, photonic foundries, and integrated device manufacturers are included, covering technology roadmaps, product families, foundry capabilities, and recent commercial milestones.
- Industry dynamics and constraint analysis: The report examines standardization progress, manufacturing equipment transitions, wafer supply bottlenecks, and the expanding ecosystem of foundry services, providing a realistic view of where growth may be constrained or accelerated in the near term.
This structure ensures that the report functions as a working document for strategy teams, not merely a reference for market awareness.
Competitive Landscape: Foundries, IDMs, and Technology Differentiation
The TFLN modulator market in 2026 is characterized by a dynamic mix of specialized startups, established photonic foundries, and integrated device manufacturers, many of whom are racing to scale production-grade platforms while locking in design-win pipelines. The competitive field reflects the technology's dual nature: it demands sophisticated materials processing, precision lithography, and packaging expertise, while simultaneously offering differentiation through bandwidth, half-wave voltage, integration density, and wavelength compatibility.
Several organizations have emerged as particularly influential in shaping the market's trajectory:
- HyperLight Corporation (Cambridge, Massachusetts, USA) has rapidly established itself as a leader in production-grade TFLN platforms. The company offers packaged electro-optic modulators spanning amplitude, phase, and IQ configurations, with bandwidth capabilities reaching 145 GHz and ultra-low Vπ specifications. Its TFLN Chiplet™ photonic integrated circuit platform targets IMDD architectures at up to 448 Gbps per lane, as well as DPIQ transmitters for AI and datacom, telecom, and quantum applications. The company supports MPW runs and custom development, and has moved aggressively into high-volume production partnerships.
- Lightium AG (Schlieren, Switzerland) operates a production-grade TFLN photonic foundry delivering 200 mm wafer manufacturing from MPW services through high-volume production. Its platform supports high-speed modulators exceeding 100 GHz with Vπ at or below 1V, and provides PDKs spanning C-band, O-band, and visible wavelengths. This foundry model enables customers to develop next-generation PICs for telecom, datacom, and integrated photonics without owning fab assets.
- Liobate Technologies (Nanjing, China) pursues an IDM approach focused on TFLN photonic devices and high-speed modulators for optical communications. Its portfolio includes TFLN-based chips and sub-assemblies built for mass production of electro-optic modulators and PICs targeting 1.6T and 3.2T applications, aligning closely with the escalating bandwidth requirements of next-generation data center and coherent optical infrastructure.
- Ori-Chip Optoelectronics Technology Co. Ltd. (Ningbo, China) develops and manufactures TFLN MZ modulators and PICs in-house on 4-inch wafers. Its products include folded intensity modulators with ultra-low Vπ below 3.3V and extinction ratios above 20 dB, alongside high-speed chips such as 1.6T DR8 MZ modulators and 4x100G DR4 PICs for high-speed optical communication.
- Quantum Computing Inc. (QCi) (Tempe, Arizona, USA) operates a dedicated TFLN foundry with 150 mm wafer processing for photonic ICs. It fabricates electro-optic modulators and phase modulators with low Vπ-length products tailored to high-baud-rate applications, and provides front-end and back-end capabilities, packaging, and PDK development.
- CCRAFT (CSEM spin-off, Switzerland) has launched what it describes as the world's first production-ready TFLN photonic chip foundry, offering MPW runs, a full PDK, and high-volume manufacturing for electro-optic modulators across telecom, datacom, AI, and quantum applications.
- Additional commercial suppliers including Agiltron Inc., Rofea Optoelectronics, Advanced Fiber Resources, and Neon CQ contribute a broad set of product options across bandwidth classes, modulation types, and application segments, from 20G to 60 GHz intensity and phase modulators, to IQ modulator solutions for OFDM and high-speed systems.
The market concentration among the top players is notable, with the top three firms accounting for approximately 68.5% of market share and the top five reaching 85.2%. This concentration underscores the technology's capital intensity and the advantage that early movers with scalable manufacturing platforms, established PDK ecosystems, and design-win momentum hold. However, it also signals opportunity for well-positioned entrants that can address specific performance niches, wavelength bands, or regional supply chain needs.
Recent Developments Shaping the 2026 Landscape
Recent commercial and ecosystem developments provide a concrete window into how the competitive and manufacturing landscape is evolving in real time:
- In March 2026, HyperLight Corporation introduced 400G-per-lane TFLN PICs on its Chiplet™ platform for AI interconnects, alongside 145 GHz packaged intensity modulators enabling 448 Gbps per lane IMDD and 260 GBaud coherent links. The same month, the company announced a strategic manufacturing partnership with UMC and Wavetek for high-volume production of the TFLN Chiplet platform on 6-inch and 8-inch wafers targeting AI and cloud infrastructure.
- In October 2025, Lightium AG participated in the European-Canadian INGENIOUS consortium, which secured €7.6M to integrate lasers and detectors into next-generation TFLN PICs, signaling the industry's push toward more fully integrated photonic solutions.
- In September 2025, Liobate Technologies showcased its latest TFLN chips and devices, including high-speed modulators, at ECOC 2025, reinforcing its focus on mass-producible solutions for high-throughput optical communications.
- In July 2025, CCRAFt launched a production-ready TFLN photonic chip foundry with MPW runs and a full PDK for scalable electro-optic modulators, expanding the foundry ecosystem and lowering barriers for customers seeking to prototype and scale TFLN-based designs.
These milestones illustrate the convergence of multiple forces: performance breakthroughs, manufacturing partnerships, consortium funding, and the expansion of foundry services. Together, they are compressing the timeline from laboratory demonstration to volume deployment.
Industry Dynamics: Standardization, Manufacturing Shifts, and Supply Constraints
Beyond company-level activity, several macro-level dynamics are influencing how the TFLN modulator market will evolve through the forecast period:
- Standardization toward foundry-compatible platforms: Industry efforts are progressing toward standardized TFLN photonic integrated circuits, including waveguides, modulators, and edge couplers, to support foundry platform compatibility and volume manufacturing. Standardization reduces design risk for customers and strengthens the business case for foundry-based production models, but it also raises the stakes for foundries that must deliver consistent, repeatable performance across multiple customers and designs.
- Manufacturing bottleneck dynamics: Limited commercial manufacturing capacity for high-quality TFLN wafers and specialized cleanroom processes has created supply chain constraints. As of early 2026, only a handful of foundries operate at meaningful scale, which means that even as end-market demand accelerates, the availability of production-grade wafers and processing capacity can become a binding constraint on growth. Companies that secure tightly coupled supply partnerships or invest in captive manufacturing capabilities gain a strategic buffer.
- Lithography transitions enabling yield and performance gains: A shift toward deep-ultraviolet (DUV) stepper lithography on 4-inch TFLN wafers with quartz handles is enabling high-yield volume manufacturing of modulators exceeding 110 GHz with propagation loss below 0.4 dB/cm. This transition is replacing lower-throughput electron-beam lithography for many production applications, reducing per-unit cost and improving consistency. The adoption curve of DUV-based processes will influence which foundries and product lines can scale most efficiently.
- Foundry services ecosystem maturation: Panels and industry discussions at venues such as ECOC 2025 have focused on turnaround times, yield, PDK completeness, and roadmaps to volume production for TFLN foundry services. As these services mature, they lower the barrier to entry for system designers and accelerate the pace of design wins, but they also intensify competition among foundries on quality, support, and scaling capacity.
- Geopolitical and regional capacity developments: In June 2025, China established its first pilot production line for 6-inch TFLN photonic chips at Shanghai Jiao Tong University's CHIPX, supporting domestic ambitions in AI, 6G, and quantum computing. Regional capacity investments of this nature signal a long-term push toward supply chain localization and may reshape competitive dynamics over the forecast period.
For strategists, these dynamics create a dual narrative: the market's growth potential is exceptionally strong, but realizing that potential depends on navigating manufacturing scale-up, supply constraints, standardization timing, and regional capacity investments. The companies that succeed will be those that treat these dynamics not as external noise, but as core inputs to capacity planning, partnership strategy, and technology roadmapping.
Why This Report Matters for 2026 Decision-Making
In a market growing at this pace and shaped by this level of technological and manufacturing complexity, decisions made in 2026 will compound over the entire forecast period. Whether the objective is to evaluate a vendor's scalability, assess a region's supply chain resilience, determine where to prioritize R&D investment, or model demand scenarios for a specific application segment, decision-makers need granular, forward-looking intelligence that goes beyond headline numbers.
PW Consulting's Worldwide Thin Film Lithium Niobate Modulator Market report provides that foundation. It combines rigorous historical analysis with forecast modeling, dissects the market by type, application, and region, maps the competitive landscape molecule by molecule, and embeds the industry dynamics that will determine which players scale and which stall. The report is structured to support board-level strategy discussions, product portfolio reviews, procurement planning, and investment committee evaluations.
Worldwide Phase Electro-optic Modulator Market
The macro trajectory is compelling. The competitive field is actively differentiating. The manufacturing and standardization landscape is evolving quickly. For organizations operating in or adjacent to the TFLN modulator ecosystem, the window for informed strategic positioning is open now.
To access the complete segmentation data, full forecast tables, detailed competitor profiles, and region-specific demand analysis, please visit PW Consulting's official report page. The full study provides the depth required to translate market momentum into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Thin Film Lithium Niobate (TFLN) Modulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Cera Market to Hit $21M by 2032, Driven by 6.01% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Evolving Landscape of Rhus Verniciflua Peel Cera
The global beauty and personal care sector is navigating a period of structural transformation, where ingredient provenance, regulatory alignment, and functional performance converge to redefine formulation strategies. Within this complex ecosystem, Rhus Verniciflua Peel Cera has emerged as a high-value botanical wax, bridging the gap between natural appeasement and sophisticated sensory engineering. As strategic decision-makers prepare for the commercial realities of 2026 and beyond, understanding the trajectory of this specialized market is no longer optional. PW Consulting's latest comprehensive analysis, Worldwide Rhus Verniciflua Peel Cera Market, provides the operational intelligence required to translate macro-trends into actionable enterprise advantage.
Worldwide Rhus Verniciflua Peel Cera Market
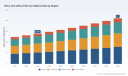
This research does not merely chart historical movement. It engineers a forward-looking decision matrix calibrated for the 2026-2032 forecast horizon. Built upon a rigorous historical foundation spanning 2020 through 2025, the study situates contemporary market behavior within a broader structural context, allowing organizations to stress-test procurement strategies, capacity expansion plans, and innovation roadmaps against verified baseline trajectories. The market has demonstrated consistent expansion, moving from a recorded valuation of 12.45 million USD in 2023 to an estimated 13.96 million USD in 2025. The momentum continues into the early forecast window, positioning the 2026 baseline at 14.8 million USD and projecting a sustained trajectory toward 21.0 million USD by 2032. Driving this progression is a compound annual growth rate of 6.01 percent, a figure that transcends superficial optimism and reflects deep-rooted demand shifts within premium cosmetic architectures.
For executives operating in an environment defined by volatile raw material pricing, tightening sustainability mandates, and increasingly discerning consumer palates, a growth rate of this nature signals more than incremental expansion. It indicates a structural re-rating of botanical wax categories as indispensable functional components rather than peripheral aesthetic additives. The strategic implication is clear: organizations that calibrate their 2026 planning cycles around verified market velocity will secure earlier access to supply chain efficiencies, formulation differentiation opportunities, and regional demand convergence patterns that slower-moving competitors will struggle to replicate.
Market Architecture and Strategic Segmentation Dynamics
The architecture of the Rhus Verniciflua Peel Cera market is defined by a multi-dimensional segmentation framework that directly informs procurement optimization, product development prioritization, and regional expansion sequencing. Our research dissects this architecture across three critical axes: regional distribution, application mapping, and physical form classification. Understanding how value flows through these segments enables formulation directors, sourcing managers, and market entry strategists to allocate capital and technical resources with precision rather than intuition.
The regional dimension reveals a complex interplay of established demand centers and emerging consumption zones. The segmentation data captures the nuanced distribution of market activity across Europe, Asia Pacific, North America, and the Rest of World, reflecting divergent regulatory environments, consumer preference gradients, and supply chain maturity levels. Rather than treating geography as a static backdrop, the analysis maps regional trajectories against procurement feasibility, logistics constraints, and formulation localization requirements. This approach allows organizations to identify where near-term commercial capture is most viable and where long-term positioning will yield compounding returns as regional formulation standards continue to harmonize around natural ingredient compliance.
Application segmentation further illuminates where functional demand is accelerating. The market's value dispersion across core cosmetic categories, including lip care formulations, skin care creams and lotions, stick cosmetics, and other applications, underscores the ingredient's versatility as a structural and sensory enabler. Formulators are increasingly integrating Rhus Verniciflua Peel Cera not merely for its emollient characteristics but for its ability to modulate texture, improve spreadability, and reinforce perceived natural authenticity within finished products. The research provides a detailed functional mapping of these application pathways, equipping R&D teams with the contextual intelligence necessary to align ingredient specification with end-product performance targets.
Form factor distribution adds another layer of operational relevance. The market's segmentation by form, encompassing pellets, flakes, and blocks, directly impacts handling efficiency, dosing precision, and manufacturing integration. Each physical configuration carries distinct implications for production throughput, inventory management, and formulation scalability. By analyzing form preferences through the lens of industrial practicality rather than theoretical categorization, the report enables procurement and operations teams to align material specifications with plant-level capabilities and cost-in-use objectives.
Competitive Field Structure and Strategic Positioning
The supplier landscape for Rhus Verniciflua Peel Cera is characterized by a concentrated yet functionally specialized competitive field. Market concentration metrics indicate that the top three players account for 54.2 percent of total revenue, while the top five firms extend their collective share to 68.45 percent. This structural concentration does not imply a monolithic marketplace. Instead, it reflects a tiered ecosystem where established wax specialists, regional distributors, and application-driven cosmetic brands occupy distinct strategic niches, each competing on technical differentiation, supply reliability, and formulation support rather than price alone.
Leadership in this space requires a clear understanding of how incumbent players are positioning their technical portfolios. Kahl GmbH & Co. KG, operating under the KahlWax brand in Germany, has reinforced its presence by offering KahlWax 6290 Berry, a low-melting soft wax engineered for velvet and powdery skin finishes. Recent documentation updates through August 2025 have emphasized its emollient and conditioning functions within skin care architectures, signaling a deliberate push toward performance-motivated natural wax positioning. In parallel, ROELMI HPC USA, leveraging the ABWAX portfolio through the ROELMI GROUP and Brasca Industrial srl, has maintained visibility through a vegetable-origin wax configured for anhydrous stick systems and personal care smoothness. The December 2025 technical profile update on industry ingredient platforms reaffirmed its melting range and stick-system compatibility, illustrating how documentation precision and technical transparency are becoming competitive differentiators in ingredient procurement decisions.
Complementing these specialized wax suppliers are distribution-focused and brand-integrated participants that shape market accessibility and downstream adoption. Ulrich GmbH operates as a German distribution channel for berry wax supplied in practical industrial packaging, simplifying procurement for cosmetic manufacturers seeking standardized natural wax inputs. Bay House Aromatics, based in the United Kingdom, positions its berry fruit wax around clean-label attributes, emphasizing vegan compliance and Kosher alignment alongside its Chinese Rhus Verniciflua berry peel origin. This profile appeals directly to formulation teams navigating claims substantiation and ingredient integrity requirements. Meanwhile, Olive Tree People, known through its Oliveda brand in Germany, demonstrates the downstream commercial translation of the ingredient by incorporating Rhus Verniciflua Peel Cera into targeted cosmetic products such as concealer serums, blush formulations, and contour systems, where it contributes to texture modulation, emulsification stability, and skin barrier support.
The strategic implication of this competitive mosaic is that procurement and partnership decisions cannot be evaluated on commodity metrics alone. Technical documentation reliability, claim-compatible sourcing narratives, form factor consistency, and application-specific performance data are increasingly decisive factors in supplier selection. Our report maps these competitive postures in detail, allowing organizations to benchmark potential partners against operational criteria that matter in real-world formulation and scale-up environments.
Regulatory Alignment, Sourcing Realities, and Tariff Structuring
The commercial viability of Rhus Verniciflua Peel Cera is inextricably linked to regulatory accessibility and supply chain transparency. Ingredient compliance is no longer a passive checklist item; it is an active architecture that determines market entry speed, formulation flexibility, and multinational scaling potential. Our research integrates a comprehensive regulatory review that situates the ingredient within the operational frameworks governing major cosmetic markets. The analysis confirms alignment with EU Cosmetics Regulation 1223/2009, inclusion in the IECSC inventory for China, and TSCA listing for the United States, with no restrictive designations noted under CLP Regulation as a non-dangerous vegetable substance. This compliance profile reduces regulatory friction and supports formulation teams seeking ingredient architectures that can travel across market jurisdictions without requiring extensive reformulation or claims restructuring.
Sourcing dynamics add an additional layer of strategic complexity. Rhus Verniciflua Peel Cera is derived from the berry fruit peels of the Rhus verniciflua tree through boiling and separation processes, with primary sourcing concentration in China. This geographic concentration intersects with broader themes of supply continuity, extraction consistency, and agricultural supply risk management. For procurement organizations, the operational question is not simply whether the raw material is available, but how sourcing dependencies influence lead time reliability, specification uniformity, and long-term cost predictability. The report addresses these considerations through a structured evaluation of extraction methodology, supply chain structure, and the practical implications of geographically anchored botanical sourcing within a global distribution environment.
Tariff classification represents another frequently underestimated variable in total cost modeling. The assigned tariff code of 15211000 carries direct implications for landed cost calculations, customs clearance efficiency, and regional pricing architecture. Organizations that integrate tariff structuring into their sourcing strategy early can avoid margin erosion that emerges when classification assumptions fail to align with actual clearance procedures. Our research embeds these regulatory and trade dimensions within the broader market narrative, ensuring that strategic recommendations reflect not only demand-side opportunity but also the operational realities that determine whether opportunity can be captured profitably.
Report Structure and the Decision Intelligence It Delivers
The Worldwide Rhus Verniciflua Peel Cera Market study is engineered as a practical decision-support instrument rather than an abstract market summary. Its architecture is designed to move executive teams, formulation leaders, procurement directors, and market development strategists from high-level awareness to executable planning. The report integrates verified market sizing and forecast modeling with segment-specific analysis, competitive participant profiling, regulatory context, and recent industry documentation developments that signal where technical emphasis is shifting.
Worldwide Pellicle Market
Readers will find structured coverage of historical performance baselines, forward-looking forecast trajectories through 2032, and segmentation analysis that clarifies how value distributes across regions, applications, and physical forms. The competitive landscape section delivers participant-level context that supports supplier evaluation, partnership screening, and benchmarking exercises. Recent development records, including technical profile updates and product listing refreshes from late 2025, are incorporated to illustrate how ingredient documentation and platform visibility are evolving in real time. These elements collectively enable organizations to identify where formulation emphasis is trending, which technical attributes are gaining procurement relevance, and how supplier communication strategies may influence selection outcomes.
Equally important, the research is built to support scenario-based planning. Rather than presenting a single deterministic path, the report frames market evolution through multiple lenses, allowing decision-makers to assess how changes in regional demand intensity, application adoption velocity, form preference shifts, or regulatory interpretation may alter commercial outcomes. This flexibility is essential for organizations operating in a market where raw material availability, consumer claim expectations, and formulation performance thresholds are all moving simultaneously.
Translating Market Intelligence into 2026 Strategic Execution
As enterprises enter 2026 planning cycles, the strategic value of this research lies in its ability to convert market movement into structured action. The documented growth trajectory and 6.01 percent compound annual growth rate are not isolated statistics; they are indicators of where formulation investment, supplier relationship development, and regional market prioritization will generate the strongest returns. Organizations that act on this intelligence early can secure advantageous positioning in application categories where natural wax functionality is becoming integral rather than optional, while also optimizing procurement approaches to reflect realistic supply, compliance, and landed cost dynamics.
The report also supports more nuanced competitive strategy. In a concentrated landscape where leading participants compete heavily on technical documentation, application specificity, and claim-compatible sourcing narratives, understanding the differentiation logic of key suppliers allows buyers to negotiate from informed positions and select partners whose capabilities align with product architecture goals. For brands and contract manufacturers seeking to enter or expand within the Rhus Verniciflua Peel Cera value chain, the segmentation and application insights provide a roadmap for identifying the highest-probability pathways to formulation success and market acceptance.
Ultimately, the decision to integrate this research into 2026 strategic planning is a decision to replace ambiguity with evidence. The market is expanding, the competitive field is crystallizing, and the regulatory and sourcing environment is demanding greater precision from ingredient stakeholders. PW Consulting's Worldwide Rhus Verniciflua Peel Cera Market study delivers the analytical depth required to navigate that environment with confidence. The full report provides the detailed segmentation data, regional and application-level breakdowns, supplier-specific evaluations, and forecast modeling necessary to translate market awareness into executable strategy. For decision-makers ready to move beyond surface-level trends and anchor their 2026 plans in verified market intelligence, the complete analysis offers the comprehensive perspective needed to act decisively.
For detailed analysis of this topic, please visit the official page: Worldwide Rhus Verniciflua Peel Cera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Decision Intelligence Market to Reach $59.65 Billion by 2032 at 18.25% CAGR
By pmarketresearch, 2026-09-16
Unlocking Enterprise Value in the Age of Decision Intelligence: PW Consulting's 2026 Market Analysis
The global business landscape in 2026 is defined by a singular imperative: speed, accuracy, and accountability in decision-making. As organizations navigate a complex web of regulatory requirements, volatile market conditions, and an explosion of data assets, the traditional reliance on intuition or siloed analytics is no longer sustainable. Enter Decision Intelligence (DI). This emerging discipline is not merely an extension of business intelligence; it is a rigorous engineering discipline that treats decisions as digital assets, embedding analytics, artificial intelligence, and continuous feedback loops directly into enterprise workflows.
At PW Consulting, we recognize that understanding the trajectory of the Decision Intelligence market is critical for C-suite executives and strategy leaders. Our newly released Worldwide Decision Intelligence Market research offers a comprehensive view of this rapidly evolving sector. This report serves as a strategic compass, guiding organizations through the noise of vendor claims and technological hype to identify where genuine value lies. In this insight piece, we preview the macro trends, competitive forces, and regulatory realities shaping the market, while underscoring the strategic value of deep-dive analysis for 2026 planning.
The Macro Trajectory: From Experimentation to Scale
The data tells a compelling story of acceleration. Our analysis tracks market revenue from 2020 through the forecast period ending in 2032, revealing a trajectory that moves beyond early adoption into mainstream enterprise integration. In 2020, the global market was valued at approximately 7,980 million USD. By 2025, that figure had surged to 18,450 million USD, reflecting a significant compound annual growth rate driven by digital transformation initiatives and the maturing of AI capabilities.
Looking forward, the momentum shows no signs of slowing. The market is projected to reach 22,452 million USD in 2026, climbing steadily to exceed 59,649 million USD by 2032. This growth reflects a compound annual growth rate of 18.25 percent across the forecast window. Such expansion signals a fundamental shift in how enterprises allocate technology budgets. Decision Intelligence is transitioning from a niche capability within data science teams to a core infrastructure component supporting operational resilience, risk management, and customer engagement. For strategy leaders, this trajectory implies that waiting to evaluate DI capabilities may result in a competitive disadvantage, as the ecosystem matures and standardization increases.
Market Dynamics: Regulation, Standardization, and the Human Element
The rapid growth of Decision Intelligence does not occur in a vacuum. Several critical dynamics are reshaping the market landscape in 2026, influencing how vendors build platforms and how enterprises deploy them.
Regulatory pressure is a primary catalyst. Frameworks such as the EU AI Act, the OECD Framework for the Classification of AI Systems, and the NIST AI RMF 1.0 mandate human supervision, transparency, and accountability for high-risk automated decisions. These regulations compel organizations to move beyond black-box algorithms toward systems that can explain rationale and audit outcomes. Additionally, ISO/IEC 42001 provides the first international standard for Artificial Intelligence Management Systems, promoting ethical AI development with a focus on fairness, risk management, and accountability. Compliance with these standards is no longer optional for enterprises in regulated industries; it is a prerequisite for deploying DI at scale.
Simultaneously, the definition of Decision Intelligence itself is crystallizing. Gartner defines DI as a practical discipline that advances decision-making by explicitly understanding and engineering how decisions are made. Outcomes are evaluated, managed, and improved via feedback loops, treating decisions as digitized assets. This distinction is vital. Decision intelligence platforms are distinct from agentic AI; they focus on explicit decision modeling, orchestration, and governance rather than fully autonomous agents. Gartner predicts that 75 percent of Global 500 companies will apply decision intelligence practices by 2026. This forecast highlights a shift toward structured, auditable decision processes that augment human judgment rather than replacing it entirely.
Responsible AI governance further emphasizes model explainability, fairness metrics, version control, real-time auditability, and compliance. As InRule and other industry voices note, these elements prevent bias and ensure transparency in high-stakes decisions. For enterprises, this means DI platforms must offer robust governance features to satisfy both internal risk committees and external regulators.
Competitive Landscape: A Fragmented but Maturing Ecosystem
The vendor ecosystem in Decision Intelligence is diverse, spanning established analytics giants, specialized decision management providers, and emerging AI-native platforms. Our report profiles key companies that are defining the boundaries of this market, each bringing distinct strengths to the table.
FICO continues to provide the FICO Platform for managing analytic workflows, decisions, and data integration, deploying models for risk, compliance, and customer engagement. SAS offers SAS Viya and SAS Intelligent Decisioning for unified decision intelligence solutions that automate and deploy rules and models, integrating real-time and batch processing with analytics and machine learning. SAS recently received recognition as a Leader in the inaugural 2026 Gartner Magic Quadrant for Decision Intelligence Platforms, noted for strong financial health, global footprint, and vertical strategies in financial services, healthcare, and manufacturing. IBM supplies decision intelligence capabilities integrated with AI and analytics platforms to support, augment, and automate decision-making processes. ACTICO offers platforms focused on rule-based and AI-enabled decision automation for enterprise use cases.
Software Engineering Intelligence Platform Market
In the realm of specialization, Aera Technology delivers the Aera Decision Cloud, a decision intelligence agent platform that automates and optimizes enterprise decisions in real time using AI for supply chain and finance. Quantexa provides the Quantexa Decision Intelligence Platform using entity resolution, knowledge graphs, and AI to create contextual views for risk, fraud, compliance, and customer intelligence. At QuanCon 2026, Quantexa showcased these capabilities and announced a strategic partnership with Moody's to advance enterprise risk decisioning.
Other notable players include o9 Solutions with its o9 Digital Brain and APEX Model for cross-domain decisions integrated with supply chain planning; Cloverpop, which delivers a platform for structured decision-making, collaboration, and AI insights via the D-Sight engine to reduce bias; Decisions, providing AI-powered platforms for designing, simulating, and operationalizing decisions with process orchestration; and InRule Technology, offering solutions for automating decisions and managing business rules without advanced programming. Rulex provides a platform combining explainable AI, what-if simulators, and optimization in a no-code interface for supply chain, life sciences, and fintech. Sapiens delivers an end-to-end AI-enabled platform for logic extraction, no-code modeling, deployment, and monitoring. Pegasystems integrates decision intelligence with process automation and AI for enterprise decision orchestration. Sparkling Logic offers a cloud-native rules and decision management platform with AI Assistant support, while Taktile provides a platform for building, managing, and optimizing automated decisions with visual modeling and real-time decisioning.
Recent developments underscore the intensity of innovation in this space. In February 2026, EXL was granted 10 new U.S. patents for AI solutions transforming data and enabling AI workflows across insurance, healthcare, retail, utilities, and financial services. EY announced a new patent for decision intelligence supporting hybrid classical-quantum computing models to help enterprises make better decisions in challenging situations. Axonis unveiled a Decision Intelligence offering to create a system of record for AI-driven decisions with role-aware interfaces for operators, analysts, clinicians, case managers, and risk teams. These milestones indicate that intellectual property and platform differentiation are becoming key battlegrounds for market share.
Market concentration data suggests a competitive environment that is accessible yet dynamic. The top three firms hold approximately 22.4 percent of the market, while the top five account for 31.85 percent. This distribution implies that no single vendor dominates the landscape, offering enterprises a range of options to tailor solutions to their specific decision architectures and industry requirements.
Worldwide Decision Intelligence Market
Operational Insights: What Your Organization Needs to Know
To navigate this complex environment, organizations need more than high-level market trends. They require actionable intelligence that bridges the gap between strategy and execution. Our report delivers deep operational content designed to support decision-makers across technology, risk, and business units.
The analysis covers deployment models, examining the shift toward cloud-based infrastructure versus on-premise solutions. Cloud deployments continue to gain traction, driven by scalability, integration capabilities, and the demand for real-time decisioning. However, on-premise solutions remain relevant for sectors with stringent data sovereignty requirements. The report explores how these deployment choices impact total cost of ownership, flexibility, and speed to value.
Component analysis distinguishes between software and services, highlighting where investments are concentrated. Software platforms form the backbone of decision intelligence, enabling rule management, model deployment, and orchestration. Services encompass implementation, consulting, and managed support, which are critical for successful adoption and governance. Understanding the balance between these components helps organizations budget accurately and structure their procurement strategies.
Vertical insights reveal how different industries leverage decision intelligence. BFSI continues to be a major adopter, using DI for risk scoring, fraud detection, and compliance automation. Healthcare applications focus on clinical decision support, resource allocation, and patient engagement. Retail and e-commerce leverage DI for personalization, inventory optimization, and dynamic pricing. Manufacturing utilizes DI for supply chain resilience, predictive maintenance, and quality control. IT and telecom sectors apply DI to network optimization, customer service automation, and churn prediction. Each vertical presents unique regulatory, data, and operational challenges, and our report dissects these nuances to guide industry-specific strategies.
Regional dynamics also play a crucial role. The North American market remains a leader in adoption and innovation, supported by a robust vendor ecosystem and early regulatory frameworks. Europe is characterized by strong regulatory drivers and a focus on ethical AI and compliance. Asia Pacific is emerging as a high-growth region, fueled by digital transformation initiatives and expanding enterprise data capabilities. Latin America and the Middle East and Africa are showing increasing interest as organizations recognize the value of structured decision processes. The report provides context on how regional factors influence vendor selection, deployment models, and implementation timelines.
Strategic Value for 2026 Decision-Makers
Why does this level of detail matter for your 2026 strategy? Because Decision Intelligence is not a plug-and-play technology; it is a strategic capability that requires alignment across people, processes, and technology. Missteps in vendor selection, governance design, or deployment architecture can lead to costly delays, compliance risks, and suboptimal outcomes.
Our report equips leaders to answer critical questions: How do you evaluate vendors against your specific decision use cases? What governance frameworks are necessary to meet evolving regulatory requirements? How do you balance the need for automation with the requirement for human oversight? How do you measure the ROI of decision intelligence investments? By providing granular analysis of market size, growth drivers, competitive positioning, and operational considerations, we enable organizations to make informed choices that reduce risk and accelerate value realization.
The distinction between decision intelligence and broader AI initiatives is particularly important. While generative AI and agentic systems capture headlines, decision intelligence platforms offer the structure, explainability, and auditability required for high-stakes enterprise decisions. Leaders who understand this distinction can allocate resources more effectively, ensuring that automation efforts are grounded in robust decision modeling and continuous improvement loops.
Conclusion: Navigate with Confidence
The Worldwide Decision Intelligence Market is at an inflection point. The convergence of regulatory mandates, technological maturity, and enterprise demand for accountable automation creates a unique window for strategic action. Organizations that invest now in understanding the market landscape, evaluating vendor capabilities, and designing decision architectures aligned with their business goals will be best positioned to thrive.
PW Consulting's full market research goes beyond the insights previewed here. It provides the detailed data, vendor profiles, and scenario analysis necessary to build a resilient decision intelligence strategy. We invite you to access the complete report to unlock the full depth of our analysis. In 2026, the decisions you make about Decision Intelligence will shape the decisions your enterprise can make for years to come. Make them with the confidence that comes from comprehensive, expert-backed intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Decision Intelligence Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Rotating Gamma System Market to Hit $507M by 2032, Growing at 5.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Horizon: Navigating the 2026 Worldwide Rotating Gamma System (RGS) Market
The global landscape for rotating gamma system technology is entering a pivotal phase. As we transition from a historical baseline into a forecast period defined by accelerated adoption and regulatory maturation, the strategic implications for healthcare providers, investors, and industry stakeholders are profound. Our latest Worldwide Rotating Gamma System (RGS) Market research delivers a comprehensive, data-driven blueprint designed specifically to inform high-stakes enterprise decisions throughout 2026 and beyond.
Market evolution over the past half-decade has established a resilient trajectory. Following a historical baseline that tracked consistent annual fluctuations between 2020 and 2025, the sector has demonstrated a clear inflection point. The current market valuation has climbed to approximately USD 348.66 million, reflecting sustained clinical demand and the gradual integration of rotating gamma platforms into both established and emerging treatment protocols. Looking forward, our forecasting models project steady expansion through 2032, with a compound annual growth rate of 5.5 percent. This trajectory points toward a market valuation that will cross the half-billion-dollar threshold by the early 2030s. Such a growth curve is not merely statistical noise; it signals a structural shift in how stereotactic radiosurgery and radiotherapy are conceptualized, procured, and reimbursed across institutional settings.
For strategic decision-makers operating in 2026, understanding this trajectory is the first step toward securing competitive advantage. The research does not simply chart historical performance; it decodes the underlying drivers that will dictate capital allocation, procurement timelines, and partnership strategies over the next seven years. By mapping the convergence of clinical innovation, regulatory clarity, and operational economics, this analysis equips leaders with the foresight required to navigate a rapidly maturing equipment landscape.
Decoding the Report Architecture: Actionable Intelligence Beyond the Surface
A market research publication only delivers value when it translates macro trends into executable strategy. Our Worldwide RGS Market study is engineered for that exact purpose. Rather than offering a superficial survey of equipment types, the report dissects the ecosystem into operational layers that directly impact purchasing cycles, service contracts, and clinical deployment roadmaps. Stakeholders will gain access to granular evaluations of system configurations, maintenance frameworks, and application-specific utilization patterns, all calibrated to reflect real-world procurement and clinical workflow constraints.
Ring Laser Gyroscope (RLG) Market
The analytical framework is structured to answer the questions that hospital administrators, clinical directors, and capital equipment planners actually face. How do rotating gamma platforms compare in terms of source management, rotational delivery mechanics, and long-term service requirements? Which clinical indications are driving sustained utilization, and how do reimbursement pathways align with institutional procurement priorities? What are the operational trade-offs between capital expenditure and lifecycle maintenance when evaluating next-generation rotating architectures? These are the core inquiries that shape the report's methodology.
Each section is built around decision-ready deliverables. Readers will encounter detailed technology benchmarking, lifecycle cost modeling, clinical adoption timelines, and regulatory clearance pathways. The analysis also incorporates procurement friction points, including lead time variability, source replacement logistics, and service-level agreement optimization. By focusing on practical implementation rather than abstract forecasting, the research transforms market data into a strategic playbook for 2026 planning cycles.
Market Dynamics and Operational Realities Shaping 2026
The operational environment for rotating gamma systems is being reshaped by simultaneous forces: technological refinement, regulatory milestones, and reimbursement continuity. A defining characteristic of the current generation of platforms is the reliance on rotating gamma delivery architectures that utilize multiple cobalt-60 sources to generate convergent arcs. This design philosophy offers a compelling alternative to static multi-source configurations, with particular relevance to source replacement complexity and rotational treatment precision. Understanding these technical nuances is essential for procurement teams evaluating total cost of ownership rather than upfront equipment pricing alone.
Regulatory progress has materially reduced market entry friction. Multiple rotating gamma platforms have achieved FDA 510(k) clearance in recent years, with additional clearances extending into Chinese regulatory frameworks. These approvals have normalized the clinical legitimacy of rotating architectures across both intracranial and extracranial applications. At the same time, reimbursement pathways remain relatively stable. Stereotactic radiosurgery procedures utilizing cobalt-60 rotating gamma systems are generally captured under existing CPT codes for intracranial and body SRS/SBRT in hospital settings. This reimbursement continuity means that clinical adoption is increasingly driven by operational fit and treatment workflow integration rather than reimbursement uncertainty.
Clinical implementation momentum is also accelerating. Recent real-world deployments have demonstrated the practical translation of rotating gamma technology into active treatment environments. First-in-region implementations and published retrospective clinical reviews are reinforcing confidence in outcomes across tumor and functional indications. These milestones matter because they convert engineering capability into clinical credibility, which in turn influences procurement prioritization, capital budgeting, and institutional adoption curves.
The competitive environment reflects these dynamics. Market concentration remains high, with a small group of established and emerging manufacturers commanding the majority of revenue share. This concentration shapes pricing expectations, service availability, and long-term partnership structures. For buyers, it means vendor evaluation must extend beyond product specifications to include regulatory standing, service network depth, source lifecycle support, and regional deployment track records. For investors and competitive strategists, it signals that market share gains will likely hinge on regulatory execution, clinical evidence generation, and service ecosystem scalability.
Key manufacturers currently shaping the landscape include American Radiosurgery Inc., which produces cobalt-60 based radiosurgery platforms designed for noninvasive treatment across head, neck, spine, and body indications; Akesis Inc., which offers rotating gamma systems utilizing continuous rotational technology and multiple cobalt-60 sources for stereotactic radiosurgery and radiotherapy; MASEP Medical Science & Technology Development Co. Ltd., which manufactures rotating gamma ray stereotactic systems for intracranial and extracranial applications; and OUR United Corp., which develops image-guided rotating gamma platforms for head and body stereotactic treatments. Each organization represents a distinct strategic positioning within the broader ecosystem, and the research evaluates their product architectures, clearance pathways, and clinical deployment patterns in a manner that allows decision-makers to map competitive moves to procurement and partnership implications.
Strategic Applications of the Forecast: How 2026 Leaders Can Act
The forecast horizon from 2026 through 2032 is not a passive projection; it is a decision framework. As rotating gamma systems continue to gain clinical and operational traction, the organizations that act early will secure advantages in equipment availability, service contracting, clinical program development, and regional market positioning. The research is designed to help leaders convert forecast intelligence into concrete planning actions.
- Capital planning teams can use the forward-looking valuation trajectory to model procurement timing, budget phasing, and multi-year equipment refresh strategies.
- Clinical operations leaders can align service-expansion roadmaps with application-level utilization patterns, ensuring that technology investments support the indications most relevant to institutional patient volume and referral pathways.
- Vendor evaluation committees can benchmark system architecture, source management, and maintenance models against total lifecycle cost expectations rather than isolated purchase price comparisons.
- Strategy and partnership teams can identify where regulatory clearance momentum and clinical evidence are strengthening the competitive position of specific platforms, enabling more informed negotiation and collaboration decisions.
This is particularly important in a market where equipment selection, service contracts, and source lifecycle planning are tightly interconnected. A rotating gamma platform decision affects clinical throughput, radiation safety logistics, maintenance scheduling, and long-term operational expenditure. The research provides the structural clarity needed to assess those interdependencies without relying on oversimplified assumptions.
Why This Research Matters for 2026 Decision-Making
As the rotating gamma system market matures, the margin for strategic error narrows. Procurement windows are increasingly tied to regulatory readiness, clinical program growth, and capital equipment budgeting cycles that demand defensible forecasting. Leaders who rely on fragmented data points or lagged industry commentary risk misaligning investment timing with the actual pace of adoption and regulatory progression. This research closes that gap by delivering an integrated view of market size dynamics, segmentation behavior, competitive positioning, and operational realities.
The strategic payoff is straightforward: better timing, better vendor qualification, and better alignment between clinical ambition and capital reality. Buyers can avoid overcommitting to architectures that do not match their service needs. Investors can distinguish between genuine adoption momentum and short-term market noise. Healthcare executives can plan program expansion with a clearer view of reimbursement continuity and equipment lifecycle implications. In all cases, the objective is the same: replace speculation with structured intelligence.
Worldwide Rotating Gamma System (RGS) Market
Moving From Insight to Execution
The Worldwide Rotating Gamma System (RGS) Market research is built for leaders who need more than a market snapshot. It is a strategic instrument for mapping procurement decisions, clinical program development, competitive positioning, and long-term capital planning against a market that is expanding steadily and evolving technologically. As the forecast period unfolds, the organizations that succeed will be those that ground their decisions in rigorous analysis rather than assumption. The complete report provides the segmentation depth, competitive profiling, regulatory chronology, and forward forecasts required to make those decisions with confidence.
To access the full intelligence package, including detailed market forecasts, segmentation analysis, competitive benchmarking, and actionable procurement guidance, visit the official source page for this study and secure the complete dataset for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Rotating Gamma System (RGS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Optical Networking IC Market to Hit $15.7B by 2032, Growing at 13.5% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Global Optical Networking IC Market
The global communications infrastructure is undergoing a structural transformation driven by the convergence of artificial intelligence workloads, cloud hyperscale expansion, and next-generation telecom architectures. At the core of this shift lies the optical networking integrated circuit market, a critical enabler of high-bandwidth, low-latency, and energy-efficient data transmission. PW Consulting's latest Worldwide Optical Networking IC Market research provides decision-makers with a comprehensive, forward-looking intelligence framework designed to navigate the complexities of a rapidly scaling industry. As enterprises, semiconductor firms, and system integrators chart their paths through 2026 and beyond, understanding the macroeconomic trajectory, technological inflection points, and competitive dynamics of this sector is no longer optional—it is a strategic imperative.
The Macro Trajectory: A Market Accelerating Under Convergent Demand
The optical networking IC sector has evolved from a specialized telecommunications component space into a foundational pillar of global digital infrastructure. Historical data reveals a pronounced acceleration in revenue generation, with the market expanding from approximately $3.42 billion in 2020 to $6.45 billion by 2025. This growth trajectory reflects not merely cyclical demand but a fundamental re-architecture of how data moves across networks. The transition to 800G and 1.6T optical modules, the proliferation of co-packaged optics, and the deployment of silicon photonics platforms are fundamentally reshaping component requirements and supply chain priorities.
Looking ahead, the forecast period spanning 2026 through 2032 projects continued robust expansion, supported by a compound annual growth rate of 13.52 percent. The market is expected to surpass the $15.6 billion threshold by the close of the forecast window, underscoring the sustained capital allocation toward optical interconnect technologies. This growth is not uniformly distributed across applications or product categories; rather, it is heavily weighted toward high-performance computing environments, cloud infrastructure buildouts, and advanced coherent transmission systems. Decision-makers must recognize that this trajectory is deeply intertwined with broader infrastructure economics, including the capital intensity of fiber deployment, the energy constraints of large-scale data centers, and the policy-driven expansion of broadband backbones. These intersecting forces create both tailwinds and constraints that will define procurement strategies, manufacturing investments, and product roadmaps throughout the decade.
2026 Decision-Making: Why This Research Matters Now
Entering 2026, the optical networking IC landscape presents a uniquely complex decision environment. Technology nodes are advancing at a pace that outstrips traditional procurement cycles, while energy efficiency mandates and thermal constraints are forcing architects to reconsider pluggable versus co-packaged approaches. Simultaneously, supply chain resilience, geopolitical considerations, and the consolidation of foundry and packaging capabilities are reshaping competitive positioning. In this context, strategic planning cannot rely on historical benchmarks or fragmented vendor narratives. It requires a unified, data-grounded view of market sizing, segmentation behavior, technology adoption curves, and competitive maneuvering.
This research is engineered to serve as a decision-support instrument for executives, product planners, investors, and procurement leaders. Rather than offering static snapshots, it maps the causal links between architectural shifts, component demand, and revenue flows. It clarifies where growth is structurally anchored, which product categories are emerging as critical bottlenecks or enablers, and how regional deployment patterns influence supply chain strategy. By synthesizing historical performance with forward-looking modeling, the report equips organizations to align capital allocation, partnership strategies, and technology roadmaps with the realities of a market that is scaling faster than legacy planning cycles can accommodate.
Inside the Report: What Decision-Makers Will Gain
The research is structured to deliver actionable intelligence across multiple dimensions of the optical networking IC ecosystem. The analytical framework integrates quantitative market modeling with qualitative technology and competitive assessment, ensuring that readers can translate high-level trends into operational strategy. Key components of the study include:
Comprehensive Market Modeling and Forecast Architecture
The report establishes a rigorous baseline using historical data from 2020 through 2025, then extends the analytical scope across the 2026–2032 forecast horizon. Revenue projections are modeled at the aggregate market level, with segmentation frameworks that dissect demand by product type, application vertical, and geographic region. This layered approach allows readers to understand not only where the market is heading, but how different technology categories and end-use environments contribute to overall growth dynamics. The modeling accounts for architectural transitions, module form-factor evolution, and the shifting economics of high-speed interconnect deployment.
Worldwide Optical Networking IC Market
Product Category and Application Deep Dives
Optical networking ICs encompass a diverse set of functional blocks, each with distinct performance requirements, manufacturing considerations, and demand drivers. The report examines the market position and growth trajectory of core product categories, including digital signal processors, laser drivers, transimpedance amplifiers, and clock and data recovery circuits. Each category is evaluated within the context of system-level architecture, highlighting how advancements in signaling rates, power efficiency, and integration complexity influence adoption patterns. Application-level analysis further maps demand to data center environments, telecommunication networks, and enterprise infrastructure, clarifying how workload characteristics and deployment scales shape procurement behavior.
Competitive Positioning and Strategic Movement Analysis
The report delivers a structured assessment of the companies shaping the optical networking IC landscape. Profiles capture corporate positioning, technology portfolios, recent strategic actions, and the implications of those moves for market structure. The analysis tracks product launches, technology acquisitions, interoperability initiatives, and architectural demonstrations that signal shifting competitive priorities. By mapping these activities against broader market trends, the research helps readers identify which players are extending leadership in high-performance DSP and coherent platforms, which are expanding silicon photonics and co-packaged optics capabilities, and how industry consortia and standards bodies are influencing multi-vendor compatibility.
Infrastructure, Energy, and Policy Contextualization
Optical networking IC demand does not exist in isolation. The report embeds component-level analysis within the broader context of infrastructure economics, energy consumption patterns, and policy-driven deployment programs. This contextual layer clarifies how capital intensity in fiber deployment, electricity constraints in large-scale computing facilities, and public investment in broadband expansion influence the pace and geography of optical interconnect adoption. Understanding these external drivers is essential for forecasting demand resilience, evaluating regional opportunity sets, and anticipating regulatory or sustainability-related shifts in procurement criteria.
Competitive Dynamics and the Shape of Market Leadership
The optical networking IC market is characterized by a concentrated yet highly active competitive environment. Incumbent semiconductor and optoelectronic firms are racing to advance process nodes, integrate coherent and PAM4 DSP capabilities, and scale silicon photonics platforms to meet the demands of AI-scale data centers and high-capacity telecom networks. System vendors and vertically integrated players are simultaneously strengthening their control over optical engines, transceiver architectures, and packaging technologies. This dynamic has produced a landscape where leadership is increasingly defined by the ability to deliver low-power, high-density, and interoperable solutions across multiple module form factors and networking architectures.
Recent industry activity illustrates the intensity of this competition. Broadcom has advanced its optical DSP roadmap with the introduction of its 3nm 400G-per-lane PAM-4 DSP, targeting low-power 1.6T pluggable modules for AI-driven networks. Marvell has expanded its technology footprint through the acquisition of plasmonics-based silicon photonics capabilities, positioning itself to scale modulation performance toward 3.2T and beyond. Semtech has demonstrated next-generation 224G-per-lane transimpedance amplifiers and modulator drivers supporting multiple optical architectures for AI data center interconnects. Meanwhile, industry-wide interoperability efforts led by standards organizations have showcased multi-vendor alignment across 800ZR, 400ZR, and emerging 224G/448G electrical and optical interfaces, signaling a concerted push toward energy-efficient, compatible AI cluster networking. These developments, among others, reflect a market where product cadence, technology integration, and ecosystem alignment are becoming decisive competitive differentiators.
The report's competitive analysis goes beyond company profiles to examine how these moves reshape market concentration, influence supply chain dependencies, and alter the balance between integrated solutions and disaggregated component procurement. By mapping strategic actions against market structure, the research helps readers anticipate where consolidation may accelerate, which technology stacks are likely to dominate specific application segments, and how new entrants or acquisitions could shift bargaining dynamics among suppliers and system integrators.
Strategic Takeaways for 2026 and Beyond
As organizations enter 2026, several strategic imperatives emerge from the market's structural evolution. First, technology roadmapping must account for the rapid migration toward higher-per-lane data rates and the parallel push for power reduction through architectural innovation. Decision-makers should evaluate how pluggable, linear pluggable, and co-packaged optics approaches align with their performance, thermal, and cost constraints. Second, supply chain strategy requires a clear view of where advanced DSP, silicon photonics, and high-speed analog integration are concentrating, as well as how packaging and testing capabilities influence time-to-market. Third, investment and partnership decisions should be informed by a nuanced understanding of application-led demand, recognizing that data center buildouts, telecom network upgrades, and enterprise infrastructure modernization are progressing at different speeds and under different economic conditions.
Optical Transceivers Market
The research also underscores the importance of monitoring interoperability and standards alignment. As multi-vendor demonstrations and consortium-driven initiatives gain momentum, compatibility across electrical and optical interfaces will increasingly influence procurement flexibility and deployment risk. Organizations that integrate standards awareness into their technology selection and vendor evaluation processes will be better positioned to manage transition costs and avoid premature lock-in to architectures that may face ecosystem headwinds.
Finally, the market's growth trajectory is intertwined with broader infrastructure and energy realities. Capital intensity in fiber deployment, electricity consumption trends in large-scale computing, and public investment in broadband expansion all shape the demand environment for optical networking ICs. Strategic planners should treat these factors not as peripheral context but as integral inputs to forecasting, capacity planning, and regional opportunity assessment.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Optical Networking IC Market is entering a phase of sustained, technology-driven expansion. The convergence of AI workload demands, high-capacity interconnect requirements, and architectural innovation is creating a market environment where insight quality directly correlates with strategic agility. PW Consulting's research is designed to provide the depth, structure, and forward-looking clarity needed to navigate that environment with confidence. By integrating market sizing, segmentation behavior, competitive movement, and infrastructure context into a single analytical framework, the report enables leaders to make informed decisions about product direction, partnership strategy, procurement posture, and investment prioritization.
For organizations seeking to understand where value is being created, which technologies are gaining structural advantage, and how competitive dynamics are evolving across the optical networking IC landscape, this research offers a comprehensive foundation for 2026 planning and beyond. The full analysis, including detailed segmentation breakdowns, regional demand patterns, product-type growth trajectories, application-level revenue distributions, and extended competitive profiling, is available through the complete report. Access the full study to equip your team with the intelligence required to act decisively in a market that is scaling rapidly and redefining the boundaries of high-performance optical networking.
For detailed analysis of this topic, please visit the official page: Worldwide Optical Networking IC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Small Flexible OLED Market Hits $40.55B in 2025, Poised to Reach $70.9B by 2032 at 8.31% CAGR
By pmarketresearch, 2026-09-16
Global Small Size Flexible OLED Panel Market: Strategic Intelligence for 2026 Decision-Makers
The small size flexible OLED panel market stands at a critical inflection point in 2026. As consumer electronics manufacturers navigate intensifying competition, evolving form factors, and shifting supply chain dynamics, having access to precise, forward-looking market intelligence is no longer optional; it is a prerequisite for strategic planning. This comprehensive market research report, covering historical performance from 2020 through 2025 and providing detailed forecasts through 2032, offers business leaders the analytical foundation required to make informed capital allocation, product roadmap, and competitive positioning decisions in the year ahead.
The industry has demonstrated remarkable resilience and growth trajectory over the past half-decade. Starting from a baseline of $22,500 million in 2020, the market expanded steadily to reach $40,550 million by 2025, reflecting a compound annual growth rate trajectory that underscores the accelerating adoption of flexible display technologies across multiple device categories. The forecast period extending to 2032 projects continued expansion, with market valuations anticipated to surpass $70,900 million by the end of the forecast horizon. These figures represent more than statistical progression; they signal a structural transformation in how manufacturers approach display technology integration, particularly in smartphone platforms, wearable devices, and emerging automotive applications where form factor flexibility delivers tangible user experience advantages.
For executives operating in this space, the strategic question is no longer whether flexible OLED will continue its growth path, but rather how to position organizations to capture disproportionate value within an increasingly concentrated and technologically demanding marketplace. This report provides the granular analysis necessary to answer that question with confidence.
Worldwide OLED Display for Smartwatch Market
Market Structure and Growth Architecture
Understanding the underlying architecture of this market requires moving beyond aggregate figures to examine the structural forces that will shape competitive outcomes through 2032. The analysis presented in this report dissects market composition across three primary dimensions, each carrying distinct implications for supply chain strategy, investment prioritization, and risk management.
The regional distribution of market activity reveals pronounced geographic concentration patterns that enterprise strategists must account for when evaluating supply chain resilience, manufacturing partnerships, and market entry timing. Similarly, the application segmentation framework illuminates where demand intensity is concentrated and where incremental growth opportunities are likely to emerge as device categories mature at different rates. Material substrate considerations further compound the strategic calculus, as the choice between established plastic polyimide solutions and emerging ultra-thin glass hybrid approaches introduces trade-offs between cost efficiency, mechanical reliability, and end-user durability expectations.
Rather than presenting static snapshots, this research traces how these structural elements interact over time, identifying the inflection points where supply constraints, technology transitions, or demand shifts will create both threats and opportunities for market participants. Readers gain access to scenario-based assessments that model how variations in key variables could alter competitive trajectories, enabling more robust strategic contingency planning.
Competitive Landscape and Strategic Positioning
The competitive dynamics of the small size flexible OLED panel market are characterized by pronounced concentration among a select group of manufacturing leaders, with the top three participants commanding a combined market share exceeding 82 percent and the top five entities consolidating approximately 91.5 percent of total market value. This concentration level has significant implications for both established players and new entrants seeking to navigate procurement relationships, pricing negotiations, and technology licensing arrangements.
Samsung Display continues to anchor its position as the leading global producer of small-to-medium size flexible AMOLED panels, maintaining dominance across smartphone, foldable, and wearable segments through advanced crease reduction technologies and high-volume production line optimization. Samsung Display's ongoing capacity investments, including announced expansion plans for its A4 factory commencing in the second quarter of 2026, signal a strategic commitment to capturing growing foldable smartphone volumes while reinforcing supply reliability for key customers.
LG Display maintains its standing as a major manufacturer focused on flexible OLED panels for smartphones, wearables, and increasingly automotive applications, supplying high-volume flexible panels including to major smartphone OEMs. The company's production architecture and customer relationships position it as a critical node within the broader supply network, particularly as automotive display integration begins incorporating flexible form factor requirements.
The competitive picture extends significantly into China, where multiple manufacturers have built substantial flexible AMOLED production capabilities. BOE Technology Group has emerged as a key producer with multiple Generation 6 flexible lines operating at high shipment volumes, complemented by active development in crease-free display technologies. BOE's recent technological demonstrations, including the Mirror-sense 0-Crease or Glaze Fold foldable OLED technology unveiled at MWC 2026 which reduces crease visibility by over 40 percent, illustrates the pace of innovation occurring among Chinese manufacturers. Additionally, BOE's activation of its first OLED panel prototype in the new Generation 8.6 B16 fab, demonstrating a 14-inch LTPO OLED notebook panel, underscores capacity expansion ambitions that extend beyond small size applications.
Tianma Microelectronics, Visionox, China Star Optoelectronics Technology, Everdisplay Optronics, and Truly Semiconductors each contribute specialized flexible OLED production capabilities targeting smartphones, wearables, and various consumer electronics applications. Their aggregate output and technology development trajectories warrant close monitoring, as Chinese manufacturers continue refining yield performance in Generation 6 and newer fabrication facilities while expanding flexible-dedicated production architectures.
Futaba Corporation represents a distinct competitive presence through its focus on small flexible PMOLED displays primarily serving wearable and consumer applications, highlighting the technology diversity that persists within the broader flexible display ecosystem.
Industry Dynamics Shaping 2026 Outcomes
Several concurrent industry dynamics will materially influence market conditions throughout 2026 and establish the operational context within which strategic decisions must be executed. Pricing environment expectations indicate that average flexible AMOLED prices are anticipated to experience downward pressure during the first half of 2026 due to prevailing market conditions, with stabilization projected for the second half as supply-demand equilibrium recalibrates. Organizations reliant on flexible OLED panel procurement must factor these pricing trajectories into component cost forecasting, margin planning, and product pricing strategies to avoid margin compression from unanticipated input cost fluctuations.
Production volume patterns suggest that flexible smartphone AMOLED shipments will encounter moderated growth rates entering 2026, influenced by broader economic factors affecting consumer electronics demand cycles. This moderation does not signal market contraction but rather a normalization phase following periods of accelerated adoption, requiring manufacturers and brand owners to recalibrate volume expectations and align production schedules with more measured demand projections.
Supply chain geography continues to exert decisive influence, with the Asia Pacific region, particularly South Korea and China, maintaining dominant positions in flexible OLED production and supply chain operations for small size panels. This geographic concentration, driven by the clustering of major fabrication facilities and manufacturing entities, creates both efficiency advantages and concentration risk considerations that procurement organizations and product planners must address through supplier diversification strategies, inventory buffer planning, and geopolitical risk assessments.
Technical standardization efforts around advanced LTPO backplane architectures and polyimide substrate processing remain central to ongoing industry development, with manufacturing focus intensifying around yield improvement initiatives in Generation 6 and newer fabrication facilities. The interplay between process maturity, defect rate reduction, and cost-per-unit economics will increasingly determine which manufacturers achieve sustainable competitive advantage as the market matures toward 2032.
Report Contents and Analytical Framework
This research publication delivers a comprehensive analytical toolkit designed to support multi-functional decision-making across corporate strategy, supply chain management, product development, and investor relations teams. The report structure integrates multiple analytical dimensions to provide both macro-level market orientation and micro-level competitive intelligence.
The historical analysis component traces market evolution from 2020 through 2025, establishing baseline performance patterns and identifying the demand drivers, technology adoption cycles, and supply-side developments that shaped past outcomes. This retrospective foundation enables readers to distinguish between temporary fluctuations and structural shifts, improving the accuracy of forward-looking projections applied to internal planning processes.
The forecast architecture provides detailed projections spanning 2026 through 2032, incorporating scenario modeling that accounts for variations in macroeconomic conditions, technology transition pacing, and competitive response dynamics. These projections are constructed to support capital investment evaluation, capacity planning, and revenue forecasting with sufficient granularity to inform board-level strategic discussions and operational budgeting cycles.
Worldwide Small Size Flexible OLED Panel Market
Competitive profiling extends beyond entity descriptions to examine strategic positioning, production capacity trajectories, technology roadmap alignment, and customer relationship structures across the principal market participants. By mapping the competitive field in operational rather than purely financial terms, the report equips readers to anticipate competitor moves, identify partnership opportunities, and assess vulnerability exposure within their own market positions.
The segmentation analysis framework enables readers to isolate performance characteristics across regional markets, application categories, and substrate technology choices without relying on oversimplified aggregate representations. This structured approach supports targeted strategy development, whether the priority involves optimizing product mix for specific geographic markets, evaluating entry timing for emerging application segments, or assessing the commercial viability of alternative substrate technology pathways.
Strategic Imperatives for 2026 Planning
As organizations prepare their 2026 strategic agendas, several priority actions emerge from the market intelligence synthesized in this research. First, procurement and supply chain leadership teams should evaluate supplier concentration exposure against the backdrop of pronounced market consolidation, developing contingency arrangements that balance cost efficiency with supply security. Second, product planning functions should align roadmap assumptions with realistic demand moderation scenarios for flexible smartphone AMOLED segments while identifying adjacent applications where flexible display integration may deliver differentiated user value propositions. Third, technology investment committees should assess the commercial implications of ongoing substrate technology evolution, weighing the maturity and cost advantages of established plastic polyimide approaches against the performance potential and market differentiation opportunities presented by ultra-thin glass hybrid solutions.
The market data, competitive analysis, and industry dynamic assessment contained within this report collectively provide the evidence base necessary to transform strategic ambiguity into actionable planning clarity. Whether the objective involves sizing market opportunity for new product introduction, evaluating partnership or acquisition targets, benchmarking internal performance against competitive norms, or constructing investor communications grounded in credible market projections, this research delivers the analytical rigor required to support confident decision-making.
The full Worldwide Small Size Flexible OLED Panel Market research publication contains the complete dataset, detailed segmentation breakdowns, company-level competitive assessments, and forward-looking scenario analyses that executive teams need to navigate the 2026 to 2032 market landscape with strategic precision. Access to the complete report enables organizations to move beyond general industry awareness into quantified, opportunity-specific strategic planning that aligns resources with the most promising market pathways.
For detailed analysis of this topic, please visit the official page: Worldwide Small Size Flexible OLED Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 4.78% CAGR for Global Coconut Oil Methyl Esters Market to Reach $1.3 Billion by 2032
By pmarketresearch, 2026-09-16
Global Coconut Oil Methyl Esters Market: Navigating Strategic Growth Through 2032
The worldwide Coconut Oil Methyl Esters Market is undergoing a period of measured expansion driven by shifting regulatory frameworks, evolving end-use demands, and the ongoing transition toward bio-based chemical intermediates. As industries seek to decouple from petrochemical derivatives while maintaining performance standards, methyl esters derived from coconut oil have emerged as a versatile feedstock spanning personal care, industrial cleaning, lubricants, and agro applications. Our latest market intelligence study maps the trajectory from 2020 through the forecast horizon of 2032, delivering a data-backed foundation for capital allocation, supply chain optimization, and competitive positioning.
Palm Methyl Ester Derivatives Market
Strategic decision-makers operating in 2026 face a landscape defined by modest but consistent growth, concentrated supplier dynamics, and heightened sensitivity to raw material pricing. This research briefing outlines the architecture of our analysis and explains how the full report equips corporate teams with the granularity required to navigate volatility, anticipate regulatory shifts, and identify actionable growth corridors within the oleochemical value chain.
Macro Trajectory: From Baseline Recovery to Sustained Expansion
The market has demonstrated steady revenue progression over the historical window. Starting from an estimated 742.15 million USD in 2020, the sector advanced through successive annual increments, reflecting both post-pandemic demand normalization and structural adoption of coconut-derived methyl esters across multiple verticals. By 2023, industry revenue reached approximately 885.02 million USD, and the upward cadence continued into 2024 with 929.19 million USD and 2025 with 945.5 million USD.
The forecast period from 2026 through 2032 indicates a compound annual growth rate of 4.78 percent, translating the sector toward a projected revenue level above 1.3 billion USD by the terminal year. This trajectory is not a simple linear extrapolation; it reflects compounding effects from regulatory mandates in select regions, gradual substitution of conventional solvents and surfactants, and sustained investment in downstream formulation capabilities. The base year of 2025 anchors the model, enabling stakeholders to benchmark current operational performance against forward-looking demand signals and evaluate whether existing capacity pipelines are sized appropriately for the coming cycle.
Importantly, the growth profile is differentiated across product families, application channels, and geographic corridors. While aggregate figures provide a directional compass, the strategic value of this study lies in unpacking the variance beneath the headline numbers—revealing where supply tightness intersects with pricing power, where formulation innovation accelerates adoption, and where policy environments create durable procurement advantages.
Market Segmentation Fundamentals
The worldwide Coconut Oil Methyl Esters Market is structured across three analytical dimensions that collectively determine competitive exposure and commercial opportunity. By product type, the market encompasses distinct methyl ester ranges that serve different solvency, emulsification, and lubricity requirements. The lighter C8-C10 segment and the broader C12-C14 range cater to divergent downstream applications, from high-performance surfactants and cleaning intermediates to emollient carriers and lubricant additives. Understanding the relative weight of these families is essential for assessing margin profiles, feedstock utilization efficiency, and the risk of regulatory or consumer preference shifts.
By application, end-use channels span personal care and cosmetics, detergents and cleaning agents, industrial lubricants and additives, and food alongside agrochemical segments. Each vertical imposes its own specification thresholds, regulatory scrutiny, and procurement cadence. Formulators in personal care, for example, prioritize purity, color, and free fatty acid constraints, while industrial and agro end-users focus on bulk availability, solvency behavior, and compatibility with existing process streams. The interplay between these application demands and the supply side’s fractionation and distillation capabilities shapes both volume distribution and pricing architecture.
Regional distribution further informs procurement strategy, capacity placement, and trade exposure. The study evaluates how local feedstock availability, refining infrastructure, and downstream manufacturing density influence consumption patterns across major economic corridors. For enterprises assessing distribution partnerships, blending facilities, or contract manufacturing arrangements, granular regional insight is indispensable for balancing incremental market access against logistical cost and regulatory compliance overhead.
Competitive Landscape and Strategic Positioning
Concentration within the market remains a defining feature of competitive dynamics. Our analysis indicates a consolidated environment in which a minority of leading participants command a significant share of revenue, while a broader ecosystem of specialized producers and distributors serves niche specification requirements. The reported market concentration metrics underscore the importance of supply relationship durability, technical service capability, and product consistency in securing long-term contracts with formulators and industrial buyers.
Several established players shape the competitive baseline. Wilmar International Limited operates extensive oleochemical production facilities in Southeast Asia and delivers fractionated methyl ester ranges, including stripped coconut methyl ester variants, through transesterification processes. Its portfolio is positioned across surfactants, lubricants, and intermediate applications, supported by integrated regional manufacturing capacity. Tantuco Enterprises, Inc. maintains a vertically integrated model anchored in the Philippines, with a coconut methyl ester operation linked to its oleochemical division and RBD coconut oil and glycerine lines, supported by substantial annual production capacity and direct copra sourcing. Stepan Company provides coconut-derived methyl ester series, including methyl laurate and related solvent and intermediate products, addressing surfactant, cleaner, and agricultural formulation needs.
Oleon NV contributes methyl ester offerings for oleochemical applications such as emollients and surfactants in personal care and industrial segments, reinforcing the European and global supply network for specialized specifications. Covalent Chemical distributes methyl cocoate as a surfactant raw material applicable across skin care, cosmetics, textiles, rubber, plastics, paints, and inks, serving formulators who require consistent quality and technical documentation. Parchem Fine & Specialty Chemicals supplies coconut oil methyl ester globally as an intermediate across agriculture, asphalt, cleaners, coatings, personal care, lubricants, metalworking, and biodiesel adjacencies, with defined specification parameters including free fatty acid limits and color thresholds.
These participants illustrate the spectrum of competitive approaches: large-scale integrated producers, regionally anchored manufacturers, and specification-focused distributors. Our report assesses the relative positioning of each, the implications of their capacity strategies and regional footprints, and the competitive pressure points likely to influence procurement terms, specification availability, and pricing stability over the forecast period.
Regulatory and Raw Material Dynamics Shaping 2026
Decision-making in 2026 must account for an active policy environment and raw material conditions that directly influence feedstock economics. International coconut oil prices, which serve as the primary input for coconut oil methyl ester production, have trended within an elevated band relative to pre-pandemic levels. Annual pricing has generally remained in a range anchored around the low thousands of USD per metric ton, reflecting modest production recovery, persistent demand from food, cosmetic, and bio-based industrial channels, and supply constraints linked to weather impacts. February 2026 pricing signals from key producing regions indicate continued tightness, reinforcing the importance of hedging strategies, contract structuring, and supply diversification for buyers exposed to input cost fluctuation.
On the policy front, regulatory mandates in select markets are actively shaping demand composition. In the Philippines, diesel fuel has maintained a mandatory blend requirement for coconut methyl ester following increases implemented in late 2024, with planned incremental increases to higher blend levels subject to ongoing review due to feedstock cost pressures. This regulatory stance carries broad implications for domestic production viability, copra price support, and the balance between imported alternatives and locally sourced methyl esters.
Recent policy positions underscore this tension. In March 2026, the Philippine Coconut Authority opposed any full suspension of the mandatory biodiesel blend program, advocating instead to preserve the current blend level or revert to a lower threshold rather than allow substitution with imported palm methyl ester. The stated rationale centered on protecting local copra prices, supporting farmers, and safeguarding the viability of domestic CME production facilities. This stance reflects a broader strategic concern: when policy design intersects with feedstock economics, procurement architectures must account not only for cost but also for continuity of supply, domestic content requirements, and potential future blending increments.
For enterprises operating across food, cosmetics, cleaning, lubricants, and agro segments, these dynamics translate into practical considerations. Procurement teams must evaluate the resilience of supply contracts under variable feedstock pricing, assess the likelihood of regulatory adjustments in blend mandates, and determine whether regional sourcing or blended feedstock strategies can mitigate exposure. Our complete study maps these dynamics against end-use demand and competitive capacity, enabling teams to model scenarios rather than react to them.
Actionable Intelligence Inside the Report
This research is designed as a decision-support instrument rather than a static overview. It combines historical tracking, forward modeling, segmentation detail, and competitive assessment into a coherent framework that can be applied across planning functions. The full publication includes:
Worldwide Coconut Oil Methyl Esters Market
- Historical reconstruction and forecast modeling that align baseline performance with projected growth corridors, enabling scenario testing around blend mandates, feedstock pricing, and downstream substitution trends.
- Product-type and application-level analysis that isolates the relative contribution, specification requirements, and procurement characteristics of each segment to inform product portfolio decisions and technical service investments.
- Regional consumption and supply context that connects feedstock availability, refining capacity, and end-user density to procurement footprints and distribution strategies.
- Competitor positioning and capability mapping that evaluates integrated producers, specialty manufacturers, and distributors by production approach, geographic reach, and application coverage, highlighting where differentiation is most durable.
- Regulatory and policy tracking that integrates mandates, blend trajectories, and industry association positions into a practical view of demand risk and supply continuity.
- Strategic recommendations for 2026 and beyond that translate market structure and dynamics into actionable guidance for capacity planning, contracting strategy, specification management, and market entry or expansion decisions.
The report also documents key specification parameters, quality controls, and application compatibility considerations that directly influence supplier selection and formulation adoption. For teams evaluating supplier qualification, contract terms, or technical collaboration, these details reduce uncertainty and accelerate internal decision cycles.
Why This Study Matters for 2026 Strategy
In a market where aggregate growth is steady but underlying conditions are variable, strategic advantage arises from knowing where concentration creates margin resilience, where application demand is expanding fastest, and where policy and feedstock economics may alter procurement economics. The 4.78 percent compound annual growth rate projected across the forecast window signals durability, yet the composition of that growth differs materially by segment and region. Generic market narratives are insufficient for capital planning, vendor selection, or portfolio optimization in this environment.
Our analysis equips leadership teams to answer targeted questions: which product ranges align with high-specification end-use channels and command premium positioning; how regional supply structures influence availability and trade exposure; what capacity strategies are being pursued by leading participants; and how blend mandate trajectories and feedstock pricing may alter the cost base and sourcing options over the next several years. By linking macro direction with segment-level context and competitive intelligence, the study helps organizations prioritize investments where the risk-reward profile is most favorable.
Access the Full Worldwide Coconut Oil Methyl Esters Market Research
The full report extends beyond headline growth figures to deliver detailed segment context, company-level capability assessment, policy tracking, and scenario-ready forecasting that can be integrated into procurement, R&D, and commercial strategy workflows. For organizations preparing for 2026 and the multi-year horizon through 2032, comprehensive intelligence is the difference between reactive positioning and deliberate market strategy.
To obtain the complete dataset, segmentation detail, competitive profiles, and forward-looking strategic guidance, request the full Worldwide Coconut Oil Methyl Esters Market research. The publication is structured to support executive review, operational planning, and supplier evaluation with the specificity required to act confidently in a dynamic oleochemical environment.
For detailed analysis of this topic, please visit the official page: Worldwide Coconut Oil Methyl Esters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Sparkling Water Maker Market to Hit $2.7B by 2032
By pmarketresearch, 2026-09-16
Global Sparkling Water Maker Market 2026–2032: Strategic Intelligence for Decision Makers
The worldwide sparkling water maker market is entering a phase of disciplined expansion, driven by shifting consumer habits, supply chain recalibration, and intensifying product innovation. At PW Consulting, we recognize that sustainable growth in this category requires more than headline revenue figures. It demands a rigorous understanding of how unit economics, channel dynamics, regional maturity, and competitive positioning intersect across the forecast horizon. Our Worldwide Sparkling Water Maker Market research was built to provide exactly that operational clarity.
Worldwide Sparkling Water Maker Market
Between 2020 and 2025, the category moved from post-pandemic normalization into a structurally stronger demand environment. Revenue progressed from approximately USD 1,020.15 million in 2020 to an estimated USD 1,533.95 million in 2025, reflecting a compound trajectory that underscores both household adoption and sustained commercial interest. The forecast window from 2026 through 2032 extends this momentum, projecting revenues to reach USD 1,732.84 million in 2026 and advance toward USD 2,715.31 million by 2032. This growth path corresponds to a forecast-period CAGR of 8.5 percent, a rate that rewards organizations able to align product portfolios, pricing architectures, and distribution strategies with evolving consumer expectations.
For executives planning 2026 budgets, capacity decisions, and channel investments, these aggregate numbers are only the starting point. The strategic value of our analysis lies in translating macro growth into actionablesegmentation, competitive mapping, and risk-aware scenario planning. The following overview outlines the structure, content, and decision utility of the full report, while intentionally leaving the granular regional, application, and channel data for the complete intelligence package.
Report Architecture: From Market Physics to Execution Roadmaps
What the Full Study Delivers
Our research is structured to support cross-functional planning across product, sales, supply chain, and corporate development teams. The report integrates historical performance tracking with forward-looking scenario modeling, ensuring that strategy teams can test assumptions against both demand-side shifts and input-cost realities.
Commercial Soda Water Dispenser Market
The core analytical modules include:
- Historical market sizing and trajectory analysis covering 2020 through 2025, establishing baseline momentum and post-cycle normalization patterns
- Forecast modeling for 2026–2032 with explicit growth drivers, moderation risks, and sensitivity considerations
- Type-level evaluation distinguishing manual sparkling water makers from electric sparkling water makers, with attention to performance trade-offs, consumer preference gradients, and portfolio implications
- Distribution channel assessment spanning online retail, hypermarkets and supermarkets, and specialty stores, including channel-mix dynamics and go-to-market leverage points
- Competitive benchmarking across the leading global and regional players, with emphasis on product architecture, brand positioning, and strategic differentiation
- Regulatory and input-cost context, particularly around beverage-grade carbon dioxide supply, purity standards, and cost volatility exposure
- Consumer habit analysis supporting demand forecasting, messaging strategy, and premiumization pathways
Each section is designed to avoid generic market description and instead surface implications for pricing power, channel selection, model mix, and capacity planning. The report also bridges market-level insights with operational reality, allowing teams to assess where growth is concentrated, where competition is intensifying, and where margin protection requires deliberate structuring.
Growth Dynamics and the 2026 DecisionHorizon
Why the Forecast Period Matters Now
The 2026–2032 window is not simply an extension of recent historical performance. It reflects a market where adoption is broadening beyond early innovators, yet competitive intensity is rising in parallel. Organizations entering this period with static product assortments or fixed channel assumptions risk losing share to players who are recalibrating around design, convenience, versatility, and input-cost resilience.
Several structural forces shape the trajectory:
- Demand normalization in developed markets, where carbonated water has become a recurring household staple rather than an occasional purchase
- Continued expansion in higher-growth regions, where urbanization, retail modernization, and aspirational kitchen appliance spending support incremental adoption
- Product-tier divergence, with premium design-led models competing alongside affordable, utility-focused offerings
- Channel evolution as digital retail infrastructure matures and omnichannel purchase journeys become more relevant to durable home appliances
Our forecast frames these dynamics within a disciplined growth path, but the real decision value lies in understanding which levers matter most in each strategic context. For instance, a manufacturer prioritizing volume may focus on accessible price points and mass retail reach, while a design-led brand may emphasize limited colorways, premium materials, and specialty retail credibility. The report helps leaders identify where their strategic posture aligns with market structure and where it may require adjustment.
Competitive Landscape: Strategic Archetypes and Positioning Pressure
Who Shapes the Market and How
The competitive environment is defined by a mix of scale leaders, design-focused specialists, versatile appliance players, and professional-grade tool manufacturers. Rather than treating competition as a static ranking, our analysis maps companies into strategic archetypes that reveal where differentiation is durable and where commoditization risk is rising.
At the center of the category sits a dominant global leader with broad product lines, strong retail distribution, and ecosystem advantages in flavor compatibility and brand recognition. This scale position supports shelf presence, consumer trust, and cross-selling potential, but it also invites targeted challenges from brands that compete on aesthetics, material quality, or functional flexibility.
Alongside the leader, a set of premium specialists competes through Scandinavian and European design language, stainless steel construction, and emphasis on durability and kitchen aesthetics. These players often target consumers willing to pay for appearance, perceived craftsmanship, and long-term product identity. Their relevance grows in markets where kitchen appliances are treated as lifestyle statements as much as utility devices.
A second competitive cluster focuses on versatility and beverage expansion. Some manufacturers position their systems as capable of carbonating more than plain water, including juices, cocktails, and other liquids. This functional breadth can widen use cases and justify higher price points, but it also introduces complexity in consumer education and usage expectations.
Budget-conscious and high-volume segments are served by affordable offerings that emphasize simplicity, quick bottle systems, and water-focused performance. These models compete on accessibility and ease of adoption, often relying on retail visibility and value messaging to capture first-time purchasers.
The landscape also includes iconic design brands that integrate carbonation into premium kitchen styling, appliance conglomerates extending into beverage carbonation within broader small-appliance portfolios, and niche specialists focused on siphons and professional-grade tools for culinary applications. Together, these players illustrate the category’s breadth: sparkling water makers are no longer a single product story but a spectrum of solutions spanning utility, design, versatility, and professional use.
Our corporate profiles examine each major player’s positioning, product architecture, and market relevance, then connect those profiles to broader strategic questions. Where does each brand win? Which consumer segments are most accessible? What product iterations signal future competition? These are the kinds of questions the full report is built to answer.
Demand Shifts, Input-Cost Realities, and Supply-Chain Implications
Beyond Consumer Adoption
Market growth cannot be understood in isolation from input availability and cost behavior. Beverage-grade carbon dioxide is a core enabler of sparkling water makers, and its supply dynamics directly influence production economics and margin planning. Recent analysis indicates that the U.S. beverage-grade carbon dioxide market was estimated at USD 547.0 million in 2025, with projections reaching USD 780.1 million by 2033. This trajectory signals expanding input demand, but also underscores the importance of sourcing stability.
Equally important is volatility. Beverage-grade CO2 has experienced price volatility exceeding 40 percent annually in recent periods, influenced by feedstock costs from ethanol and fertilizer production cycles. For sparkling water maker manufacturers and brand owners, this level of variability can affect cost structures, replenishment timing, and pricing flexibility. Even when final consumer pricing does not move in lockstep with input costs, internal budgeting and supplier negotiation strategies must anticipate fluctuation.
Regulatory expectations add another layer of complexity. Beverage manufacturers and carbonation system providers prioritize high-purity CO2 that meets FDA and food-safety requirements, with traceability for use in both home and commercial systems. This focus on purity and documentation matters not only for compliance but also for brand assurance, especially as consumers become more attentive to ingredient integrity and product safety.
Broader environmental policy trends also shape the operating environment. Global carbon pricing instruments covered around 28 percent of emissions in 2025, creating potential cost implications across CO2 production and beverage carbonation supply chains. While the direct impact will vary by region and supplier footprint, organizations with internationally exposed operations should consider how carbon-related costs may influence total landed cost and long-term competitiveness.
Consumer Behavior: The Demand Floor and the Premium Ceiling
Why Household Habits Translate into Category Resilience
Consumer adoption is the engine behind sustained category performance. Recent sector analysis indicates that more than 62 percent of urban households in developed markets considered carbonated water a weekly staple as of Q4 2025. This habit formation supports a durable demand base for home sparkling water makers, especially where convenience, cost-per-serving considerations, and flavor customization align with everyday usage.
Importantly, habit strength does not automatically translate into uniform purchasing behavior. Some households prefer low-friction manual systems, while others seek electric convenience. Some prioritize simplicity and price, while others choose premium design or multi-beverage capability. This behavioral diversity is precisely why segment-level evaluation matters: the market reward goes to companies that can match product architecture to the right consumer job-to-be-done, rather than relying on a single universal offering.
For 2026 planning, the implication is clear. Growth is supported by habitual usage, but differentiation is determined by how well brands serve distinct preference clusters. Messaging, packaging, accessory ecosystems, and after-sale support all influence whether a first purchase becomes repeat usage or category churn.
Recent Product Developments: Signals of Competitive Acceleration
What Launches Reveal About Direction
New product activity in this category is not merely cosmetic. It reflects shifting priorities in design, performance, and use-case expansion. In September 2025, MySoda Oy introduced the Ruby 2 All Black premium sparkling water maker, designed to compete with established brands through enhanced aesthetics and performance. This launch underscores the continued importance of premium positioning and material-led differentiation, especially where design credibility can support margin resilience.
In September 2024, SodaStream International Ltd. launched the enso and ART GOLD sparkling water makers alongside new SodaStream Crafted cocktail mixers, expanding home carbonation offerings into flavor and mixology adjacent use cases. Moves like these illustrate how category leaders seek to deepen engagement by broadening the functional and experiential appeal of home carbonation, rather than competing solely on the device itself.
These developments are consistent with a broader pattern: brands are refining aesthetics, expanding model ranges, and exploring adjacent consumption occasions. Our report contextualizes such launches within competitive strategy, helping readers interpret whether new products represent incremental line extensions, defensive positioning, or genuine differentiation.
How to Use This Research for 2026 Planning
From Intelligence to Action
The Worldwide Sparkling Water Maker Market report is designed to support concrete decisions rather than abstract market awareness. Depending on organizational role, the analysis can be applied to:
- Portfolio prioritization, including which product types and feature sets deserve investment in the next planning cycle
- Channel strategy, identifying where distribution effort should be concentrated and how channel mix may evolve
- Competitive response planning, especially as premium design players, versatile appliance brands, and value-oriented manufacturers all advance distinct propositions
- Supply chain and sourcing sensitivity, particularly regarding input volatility and the need for resilience in CO2-dependent categories
- Geographic expansion assessment, using regional maturity and demand structure to inform rollout sequencing without overcommitting to underdeveloped or saturated contexts
- Pricing and value architecture, aligning price tiers with consumer willingness to pay for design, convenience, and versatility
Because the market is projected to grow at an 8.5 percent CAGR across the 2026–2032 forecast period, pacing matters. Organizations that move early with well-targeted product and channel decisions may secure advantageous positions before competitive density increases further. At the same time, indiscriminate expansion can erode margins, especially where input costs fluctuate and regional demand structures differ. The full report provides the segmentation depth and strategic context required to make these trade-offs explicit.
Concentration, Risk, and the Case for Detailed Market Intelligence
Why Aggregation Is Not Enough
Market-level revenue and growth rates are essential, but they do not reveal the distribution of opportunity or the concentration of competitive advantage. The sparkling water maker market reflects a moderately concentrated structure, with the top three players accounting for approximately 68.45 percent of market share and the top five reaching about 76.12 percent. This level of concentration suggests that scale, distribution strength, and brand recognition continue to matter, while also implying that targeted differentiation can still create meaningful footholds for specialist and emerging players.
Concentration also shapes competitive behavior. In a market where leading positions are meaningful but not absolute, incumbents must defend shelf space, consumer attention, and product relevance, while challengers must identify niches where design, versatility, or value can break through. Understanding how these forces interact across segments and channels is central to strategic planning.
The report’s detailed segmentation and company-level analysis is intended to make these dynamics legible. By separating regional performance patterns, type-based demand profiles, and channel-specific behavior, the study allows decision makers to assess where concentration is an advantage, where it is a vulnerability, and where it can be disrupted through disciplined positioning.
Conclusion: A Market Ready for Disciplined Strategy
The worldwide sparkling water maker market is moving into a period where growth is supported by habitual demand and broadening product relevance, yet challenged by input volatility, competitive overlap, and the need for targeted differentiation. An 8.5 percent forecast-period CAGR through 2032 signals opportunity, but the real strategic advantage will belong to organizations that can translate that growth into segment-appropriate product strategies, channel choices, and supply-chain resilience.
This article has outlined the strategic architecture of our research and the decision problems it is built to address. To access the complete segmentation detail, competitive profiles, regional and channel-level intelligence, and the full forecast dataset needed for 2026 planning, we invite you to explore the full Worldwide Sparkling Water Maker Market report on the PW Consulting platform.
For detailed analysis of this topic, please visit the official page: Worldwide Sparkling Water Maker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com