

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Cera Market to Hit $21M by 2032, Driven by 6.01% CAGR

Strategic Intelligence for the Evolving Landscape of Rhus Verniciflua Peel Cera
The global beauty and personal care sector is navigating a period of structural transformation, where ingredient provenance, regulatory alignment, and functional performance converge to redefine formulation strategies. Within this complex ecosystem, Rhus Verniciflua Peel Cera has emerged as a high-value botanical wax, bridging the gap between natural appeasement and sophisticated sensory engineering. As strategic decision-makers prepare for the commercial realities of 2026 and beyond, understanding the trajectory of this specialized market is no longer optional. PW Consulting's latest comprehensive analysis, Worldwide Rhus Verniciflua Peel Cera Market, provides the operational intelligence required to translate macro-trends into actionable enterprise advantage.
Worldwide Rhus Verniciflua Peel Cera Market
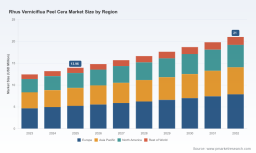
This research does not merely chart historical movement. It engineers a forward-looking decision matrix calibrated for the 2026-2032 forecast horizon. Built upon a rigorous historical foundation spanning 2020 through 2025, the study situates contemporary market behavior within a broader structural context, allowing organizations to stress-test procurement strategies, capacity expansion plans, and innovation roadmaps against verified baseline trajectories. The market has demonstrated consistent expansion, moving from a recorded valuation of 12.45 million USD in 2023 to an estimated 13.96 million USD in 2025. The momentum continues into the early forecast window, positioning the 2026 baseline at 14.8 million USD and projecting a sustained trajectory toward 21.0 million USD by 2032. Driving this progression is a compound annual growth rate of 6.01 percent, a figure that transcends superficial optimism and reflects deep-rooted demand shifts within premium cosmetic architectures.
For executives operating in an environment defined by volatile raw material pricing, tightening sustainability mandates, and increasingly discerning consumer palates, a growth rate of this nature signals more than incremental expansion. It indicates a structural re-rating of botanical wax categories as indispensable functional components rather than peripheral aesthetic additives. The strategic implication is clear: organizations that calibrate their 2026 planning cycles around verified market velocity will secure earlier access to supply chain efficiencies, formulation differentiation opportunities, and regional demand convergence patterns that slower-moving competitors will struggle to replicate.
Market Architecture and Strategic Segmentation Dynamics
The architecture of the Rhus Verniciflua Peel Cera market is defined by a multi-dimensional segmentation framework that directly informs procurement optimization, product development prioritization, and regional expansion sequencing. Our research dissects this architecture across three critical axes: regional distribution, application mapping, and physical form classification. Understanding how value flows through these segments enables formulation directors, sourcing managers, and market entry strategists to allocate capital and technical resources with precision rather than intuition.
The regional dimension reveals a complex interplay of established demand centers and emerging consumption zones. The segmentation data captures the nuanced distribution of market activity across Europe, Asia Pacific, North America, and the Rest of World, reflecting divergent regulatory environments, consumer preference gradients, and supply chain maturity levels. Rather than treating geography as a static backdrop, the analysis maps regional trajectories against procurement feasibility, logistics constraints, and formulation localization requirements. This approach allows organizations to identify where near-term commercial capture is most viable and where long-term positioning will yield compounding returns as regional formulation standards continue to harmonize around natural ingredient compliance.
Application segmentation further illuminates where functional demand is accelerating. The market's value dispersion across core cosmetic categories, including lip care formulations, skin care creams and lotions, stick cosmetics, and other applications, underscores the ingredient's versatility as a structural and sensory enabler. Formulators are increasingly integrating Rhus Verniciflua Peel Cera not merely for its emollient characteristics but for its ability to modulate texture, improve spreadability, and reinforce perceived natural authenticity within finished products. The research provides a detailed functional mapping of these application pathways, equipping R&D teams with the contextual intelligence necessary to align ingredient specification with end-product performance targets.
Form factor distribution adds another layer of operational relevance. The market's segmentation by form, encompassing pellets, flakes, and blocks, directly impacts handling efficiency, dosing precision, and manufacturing integration. Each physical configuration carries distinct implications for production throughput, inventory management, and formulation scalability. By analyzing form preferences through the lens of industrial practicality rather than theoretical categorization, the report enables procurement and operations teams to align material specifications with plant-level capabilities and cost-in-use objectives.
Competitive Field Structure and Strategic Positioning
The supplier landscape for Rhus Verniciflua Peel Cera is characterized by a concentrated yet functionally specialized competitive field. Market concentration metrics indicate that the top three players account for 54.2 percent of total revenue, while the top five firms extend their collective share to 68.45 percent. This structural concentration does not imply a monolithic marketplace. Instead, it reflects a tiered ecosystem where established wax specialists, regional distributors, and application-driven cosmetic brands occupy distinct strategic niches, each competing on technical differentiation, supply reliability, and formulation support rather than price alone.
Leadership in this space requires a clear understanding of how incumbent players are positioning their technical portfolios. Kahl GmbH & Co. KG, operating under the KahlWax brand in Germany, has reinforced its presence by offering KahlWax 6290 Berry, a low-melting soft wax engineered for velvet and powdery skin finishes. Recent documentation updates through August 2025 have emphasized its emollient and conditioning functions within skin care architectures, signaling a deliberate push toward performance-motivated natural wax positioning. In parallel, ROELMI HPC USA, leveraging the ABWAX portfolio through the ROELMI GROUP and Brasca Industrial srl, has maintained visibility through a vegetable-origin wax configured for anhydrous stick systems and personal care smoothness. The December 2025 technical profile update on industry ingredient platforms reaffirmed its melting range and stick-system compatibility, illustrating how documentation precision and technical transparency are becoming competitive differentiators in ingredient procurement decisions.
Complementing these specialized wax suppliers are distribution-focused and brand-integrated participants that shape market accessibility and downstream adoption. Ulrich GmbH operates as a German distribution channel for berry wax supplied in practical industrial packaging, simplifying procurement for cosmetic manufacturers seeking standardized natural wax inputs. Bay House Aromatics, based in the United Kingdom, positions its berry fruit wax around clean-label attributes, emphasizing vegan compliance and Kosher alignment alongside its Chinese Rhus Verniciflua berry peel origin. This profile appeals directly to formulation teams navigating claims substantiation and ingredient integrity requirements. Meanwhile, Olive Tree People, known through its Oliveda brand in Germany, demonstrates the downstream commercial translation of the ingredient by incorporating Rhus Verniciflua Peel Cera into targeted cosmetic products such as concealer serums, blush formulations, and contour systems, where it contributes to texture modulation, emulsification stability, and skin barrier support.
The strategic implication of this competitive mosaic is that procurement and partnership decisions cannot be evaluated on commodity metrics alone. Technical documentation reliability, claim-compatible sourcing narratives, form factor consistency, and application-specific performance data are increasingly decisive factors in supplier selection. Our report maps these competitive postures in detail, allowing organizations to benchmark potential partners against operational criteria that matter in real-world formulation and scale-up environments.
Regulatory Alignment, Sourcing Realities, and Tariff Structuring
The commercial viability of Rhus Verniciflua Peel Cera is inextricably linked to regulatory accessibility and supply chain transparency. Ingredient compliance is no longer a passive checklist item; it is an active architecture that determines market entry speed, formulation flexibility, and multinational scaling potential. Our research integrates a comprehensive regulatory review that situates the ingredient within the operational frameworks governing major cosmetic markets. The analysis confirms alignment with EU Cosmetics Regulation 1223/2009, inclusion in the IECSC inventory for China, and TSCA listing for the United States, with no restrictive designations noted under CLP Regulation as a non-dangerous vegetable substance. This compliance profile reduces regulatory friction and supports formulation teams seeking ingredient architectures that can travel across market jurisdictions without requiring extensive reformulation or claims restructuring.
Sourcing dynamics add an additional layer of strategic complexity. Rhus Verniciflua Peel Cera is derived from the berry fruit peels of the Rhus verniciflua tree through boiling and separation processes, with primary sourcing concentration in China. This geographic concentration intersects with broader themes of supply continuity, extraction consistency, and agricultural supply risk management. For procurement organizations, the operational question is not simply whether the raw material is available, but how sourcing dependencies influence lead time reliability, specification uniformity, and long-term cost predictability. The report addresses these considerations through a structured evaluation of extraction methodology, supply chain structure, and the practical implications of geographically anchored botanical sourcing within a global distribution environment.
Tariff classification represents another frequently underestimated variable in total cost modeling. The assigned tariff code of 15211000 carries direct implications for landed cost calculations, customs clearance efficiency, and regional pricing architecture. Organizations that integrate tariff structuring into their sourcing strategy early can avoid margin erosion that emerges when classification assumptions fail to align with actual clearance procedures. Our research embeds these regulatory and trade dimensions within the broader market narrative, ensuring that strategic recommendations reflect not only demand-side opportunity but also the operational realities that determine whether opportunity can be captured profitably.
Report Structure and the Decision Intelligence It Delivers
The Worldwide Rhus Verniciflua Peel Cera Market study is engineered as a practical decision-support instrument rather than an abstract market summary. Its architecture is designed to move executive teams, formulation leaders, procurement directors, and market development strategists from high-level awareness to executable planning. The report integrates verified market sizing and forecast modeling with segment-specific analysis, competitive participant profiling, regulatory context, and recent industry documentation developments that signal where technical emphasis is shifting.
Worldwide Pellicle Market
Readers will find structured coverage of historical performance baselines, forward-looking forecast trajectories through 2032, and segmentation analysis that clarifies how value distributes across regions, applications, and physical forms. The competitive landscape section delivers participant-level context that supports supplier evaluation, partnership screening, and benchmarking exercises. Recent development records, including technical profile updates and product listing refreshes from late 2025, are incorporated to illustrate how ingredient documentation and platform visibility are evolving in real time. These elements collectively enable organizations to identify where formulation emphasis is trending, which technical attributes are gaining procurement relevance, and how supplier communication strategies may influence selection outcomes.
Equally important, the research is built to support scenario-based planning. Rather than presenting a single deterministic path, the report frames market evolution through multiple lenses, allowing decision-makers to assess how changes in regional demand intensity, application adoption velocity, form preference shifts, or regulatory interpretation may alter commercial outcomes. This flexibility is essential for organizations operating in a market where raw material availability, consumer claim expectations, and formulation performance thresholds are all moving simultaneously.
Translating Market Intelligence into 2026 Strategic Execution
As enterprises enter 2026 planning cycles, the strategic value of this research lies in its ability to convert market movement into structured action. The documented growth trajectory and 6.01 percent compound annual growth rate are not isolated statistics; they are indicators of where formulation investment, supplier relationship development, and regional market prioritization will generate the strongest returns. Organizations that act on this intelligence early can secure advantageous positioning in application categories where natural wax functionality is becoming integral rather than optional, while also optimizing procurement approaches to reflect realistic supply, compliance, and landed cost dynamics.
The report also supports more nuanced competitive strategy. In a concentrated landscape where leading participants compete heavily on technical documentation, application specificity, and claim-compatible sourcing narratives, understanding the differentiation logic of key suppliers allows buyers to negotiate from informed positions and select partners whose capabilities align with product architecture goals. For brands and contract manufacturers seeking to enter or expand within the Rhus Verniciflua Peel Cera value chain, the segmentation and application insights provide a roadmap for identifying the highest-probability pathways to formulation success and market acceptance.
Ultimately, the decision to integrate this research into 2026 strategic planning is a decision to replace ambiguity with evidence. The market is expanding, the competitive field is crystallizing, and the regulatory and sourcing environment is demanding greater precision from ingredient stakeholders. PW Consulting's Worldwide Rhus Verniciflua Peel Cera Market study delivers the analytical depth required to navigate that environment with confidence. The full report provides the detailed segmentation data, regional and application-level breakdowns, supplier-specific evaluations, and forecast modeling necessary to translate market awareness into executable strategy. For decision-makers ready to move beyond surface-level trends and anchor their 2026 plans in verified market intelligence, the complete analysis offers the comprehensive perspective needed to act decisively.
For detailed analysis of this topic, please visit the official page: Worldwide Rhus Verniciflua Peel Cera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com