

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Rotating Gamma System Market to Hit $507M by 2032, Growing at 5.5% CAGR

Strategic Intelligence for the Next Horizon: Navigating the 2026 Worldwide Rotating Gamma System (RGS) Market
The global landscape for rotating gamma system technology is entering a pivotal phase. As we transition from a historical baseline into a forecast period defined by accelerated adoption and regulatory maturation, the strategic implications for healthcare providers, investors, and industry stakeholders are profound. Our latest Worldwide Rotating Gamma System (RGS) Market research delivers a comprehensive, data-driven blueprint designed specifically to inform high-stakes enterprise decisions throughout 2026 and beyond.
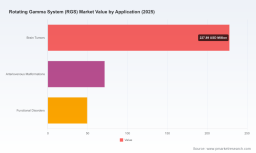
Market evolution over the past half-decade has established a resilient trajectory. Following a historical baseline that tracked consistent annual fluctuations between 2020 and 2025, the sector has demonstrated a clear inflection point. The current market valuation has climbed to approximately USD 348.66 million, reflecting sustained clinical demand and the gradual integration of rotating gamma platforms into both established and emerging treatment protocols. Looking forward, our forecasting models project steady expansion through 2032, with a compound annual growth rate of 5.5 percent. This trajectory points toward a market valuation that will cross the half-billion-dollar threshold by the early 2030s. Such a growth curve is not merely statistical noise; it signals a structural shift in how stereotactic radiosurgery and radiotherapy are conceptualized, procured, and reimbursed across institutional settings.
For strategic decision-makers operating in 2026, understanding this trajectory is the first step toward securing competitive advantage. The research does not simply chart historical performance; it decodes the underlying drivers that will dictate capital allocation, procurement timelines, and partnership strategies over the next seven years. By mapping the convergence of clinical innovation, regulatory clarity, and operational economics, this analysis equips leaders with the foresight required to navigate a rapidly maturing equipment landscape.
Decoding the Report Architecture: Actionable Intelligence Beyond the Surface
A market research publication only delivers value when it translates macro trends into executable strategy. Our Worldwide RGS Market study is engineered for that exact purpose. Rather than offering a superficial survey of equipment types, the report dissects the ecosystem into operational layers that directly impact purchasing cycles, service contracts, and clinical deployment roadmaps. Stakeholders will gain access to granular evaluations of system configurations, maintenance frameworks, and application-specific utilization patterns, all calibrated to reflect real-world procurement and clinical workflow constraints.
Ring Laser Gyroscope (RLG) Market
The analytical framework is structured to answer the questions that hospital administrators, clinical directors, and capital equipment planners actually face. How do rotating gamma platforms compare in terms of source management, rotational delivery mechanics, and long-term service requirements? Which clinical indications are driving sustained utilization, and how do reimbursement pathways align with institutional procurement priorities? What are the operational trade-offs between capital expenditure and lifecycle maintenance when evaluating next-generation rotating architectures? These are the core inquiries that shape the report's methodology.
Each section is built around decision-ready deliverables. Readers will encounter detailed technology benchmarking, lifecycle cost modeling, clinical adoption timelines, and regulatory clearance pathways. The analysis also incorporates procurement friction points, including lead time variability, source replacement logistics, and service-level agreement optimization. By focusing on practical implementation rather than abstract forecasting, the research transforms market data into a strategic playbook for 2026 planning cycles.
Market Dynamics and Operational Realities Shaping 2026
The operational environment for rotating gamma systems is being reshaped by simultaneous forces: technological refinement, regulatory milestones, and reimbursement continuity. A defining characteristic of the current generation of platforms is the reliance on rotating gamma delivery architectures that utilize multiple cobalt-60 sources to generate convergent arcs. This design philosophy offers a compelling alternative to static multi-source configurations, with particular relevance to source replacement complexity and rotational treatment precision. Understanding these technical nuances is essential for procurement teams evaluating total cost of ownership rather than upfront equipment pricing alone.
Regulatory progress has materially reduced market entry friction. Multiple rotating gamma platforms have achieved FDA 510(k) clearance in recent years, with additional clearances extending into Chinese regulatory frameworks. These approvals have normalized the clinical legitimacy of rotating architectures across both intracranial and extracranial applications. At the same time, reimbursement pathways remain relatively stable. Stereotactic radiosurgery procedures utilizing cobalt-60 rotating gamma systems are generally captured under existing CPT codes for intracranial and body SRS/SBRT in hospital settings. This reimbursement continuity means that clinical adoption is increasingly driven by operational fit and treatment workflow integration rather than reimbursement uncertainty.
Clinical implementation momentum is also accelerating. Recent real-world deployments have demonstrated the practical translation of rotating gamma technology into active treatment environments. First-in-region implementations and published retrospective clinical reviews are reinforcing confidence in outcomes across tumor and functional indications. These milestones matter because they convert engineering capability into clinical credibility, which in turn influences procurement prioritization, capital budgeting, and institutional adoption curves.
The competitive environment reflects these dynamics. Market concentration remains high, with a small group of established and emerging manufacturers commanding the majority of revenue share. This concentration shapes pricing expectations, service availability, and long-term partnership structures. For buyers, it means vendor evaluation must extend beyond product specifications to include regulatory standing, service network depth, source lifecycle support, and regional deployment track records. For investors and competitive strategists, it signals that market share gains will likely hinge on regulatory execution, clinical evidence generation, and service ecosystem scalability.
Key manufacturers currently shaping the landscape include American Radiosurgery Inc., which produces cobalt-60 based radiosurgery platforms designed for noninvasive treatment across head, neck, spine, and body indications; Akesis Inc., which offers rotating gamma systems utilizing continuous rotational technology and multiple cobalt-60 sources for stereotactic radiosurgery and radiotherapy; MASEP Medical Science & Technology Development Co. Ltd., which manufactures rotating gamma ray stereotactic systems for intracranial and extracranial applications; and OUR United Corp., which develops image-guided rotating gamma platforms for head and body stereotactic treatments. Each organization represents a distinct strategic positioning within the broader ecosystem, and the research evaluates their product architectures, clearance pathways, and clinical deployment patterns in a manner that allows decision-makers to map competitive moves to procurement and partnership implications.
Strategic Applications of the Forecast: How 2026 Leaders Can Act
The forecast horizon from 2026 through 2032 is not a passive projection; it is a decision framework. As rotating gamma systems continue to gain clinical and operational traction, the organizations that act early will secure advantages in equipment availability, service contracting, clinical program development, and regional market positioning. The research is designed to help leaders convert forecast intelligence into concrete planning actions.
- Capital planning teams can use the forward-looking valuation trajectory to model procurement timing, budget phasing, and multi-year equipment refresh strategies.
- Clinical operations leaders can align service-expansion roadmaps with application-level utilization patterns, ensuring that technology investments support the indications most relevant to institutional patient volume and referral pathways.
- Vendor evaluation committees can benchmark system architecture, source management, and maintenance models against total lifecycle cost expectations rather than isolated purchase price comparisons.
- Strategy and partnership teams can identify where regulatory clearance momentum and clinical evidence are strengthening the competitive position of specific platforms, enabling more informed negotiation and collaboration decisions.
This is particularly important in a market where equipment selection, service contracts, and source lifecycle planning are tightly interconnected. A rotating gamma platform decision affects clinical throughput, radiation safety logistics, maintenance scheduling, and long-term operational expenditure. The research provides the structural clarity needed to assess those interdependencies without relying on oversimplified assumptions.
Why This Research Matters for 2026 Decision-Making
As the rotating gamma system market matures, the margin for strategic error narrows. Procurement windows are increasingly tied to regulatory readiness, clinical program growth, and capital equipment budgeting cycles that demand defensible forecasting. Leaders who rely on fragmented data points or lagged industry commentary risk misaligning investment timing with the actual pace of adoption and regulatory progression. This research closes that gap by delivering an integrated view of market size dynamics, segmentation behavior, competitive positioning, and operational realities.
The strategic payoff is straightforward: better timing, better vendor qualification, and better alignment between clinical ambition and capital reality. Buyers can avoid overcommitting to architectures that do not match their service needs. Investors can distinguish between genuine adoption momentum and short-term market noise. Healthcare executives can plan program expansion with a clearer view of reimbursement continuity and equipment lifecycle implications. In all cases, the objective is the same: replace speculation with structured intelligence.
Worldwide Rotating Gamma System (RGS) Market
Moving From Insight to Execution
The Worldwide Rotating Gamma System (RGS) Market research is built for leaders who need more than a market snapshot. It is a strategic instrument for mapping procurement decisions, clinical program development, competitive positioning, and long-term capital planning against a market that is expanding steadily and evolving technologically. As the forecast period unfolds, the organizations that succeed will be those that ground their decisions in rigorous analysis rather than assumption. The complete report provides the segmentation depth, competitive profiling, regulatory chronology, and forward forecasts required to make those decisions with confidence.
To access the full intelligence package, including detailed market forecasts, segmentation analysis, competitive benchmarking, and actionable procurement guidance, visit the official source page for this study and secure the complete dataset for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Rotating Gamma System (RGS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com